
 Global Veterinary Radiography System Market | 2026-2036
Global Veterinary Radiography System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Radiography System Market Foresight
Capital-intensity divergence between full-platform manufacturers and component assemblers is bifurcating competitive returns in the Global Veterinary Radiography System Market. Siemens Healthineers leverages its detector fabrication depth to control margins on flat-panel digital systems. Fujifilm Holdings Corporation anchors its position through captive sensor production and veterinary-specific software workflows. IDEXX Laboratories dominates the North American clinic channel with integrated diagnostics-to-imaging bundling.
Veterinary radiography systems are diagnostic imaging devices engineered to capture anatomical structures in animals, typically operating at 40-150 kV tube voltage with specialized positioning tables and restraint interfaces for non-compliant patients. Their primary commercial purpose is to enable fracture assessment, thoracic evaluation, and dental imaging in clinical and hospital settings where patient cooperation cannot be verbally secured. Digital radiography leads product-type revenue due to replacement cycles from aging analog fleets, while portable radiography represents the fastest-expanding application segment as mobile veterinary services multiply. Flat-panel detector technology captures the dominant share of technology-driven value, though direct conversion architectures command premium positioning in equine and large-animal settings where image resolution at extended source-to-image distances matters.
The FDA Center for Devices and Radiological Health governs 510(k) clearance pathways for veterinary X-ray systems sold in the United States, while the EU Medical Device Regulation imposes clinical evidence and post-market surveillance obligations on imaging equipment distributed across Europe. Japan's PMDA maintains distinct pharmaceutical and medical device agency review standards that shape product localization requirements for Asian market entry. Stakeholders must monitor evolving radiation safety standards and software-as-medical-device classifications that could reclassify AI-enhanced image processing modules under stricter premarket review frameworks.
Market Dynamics
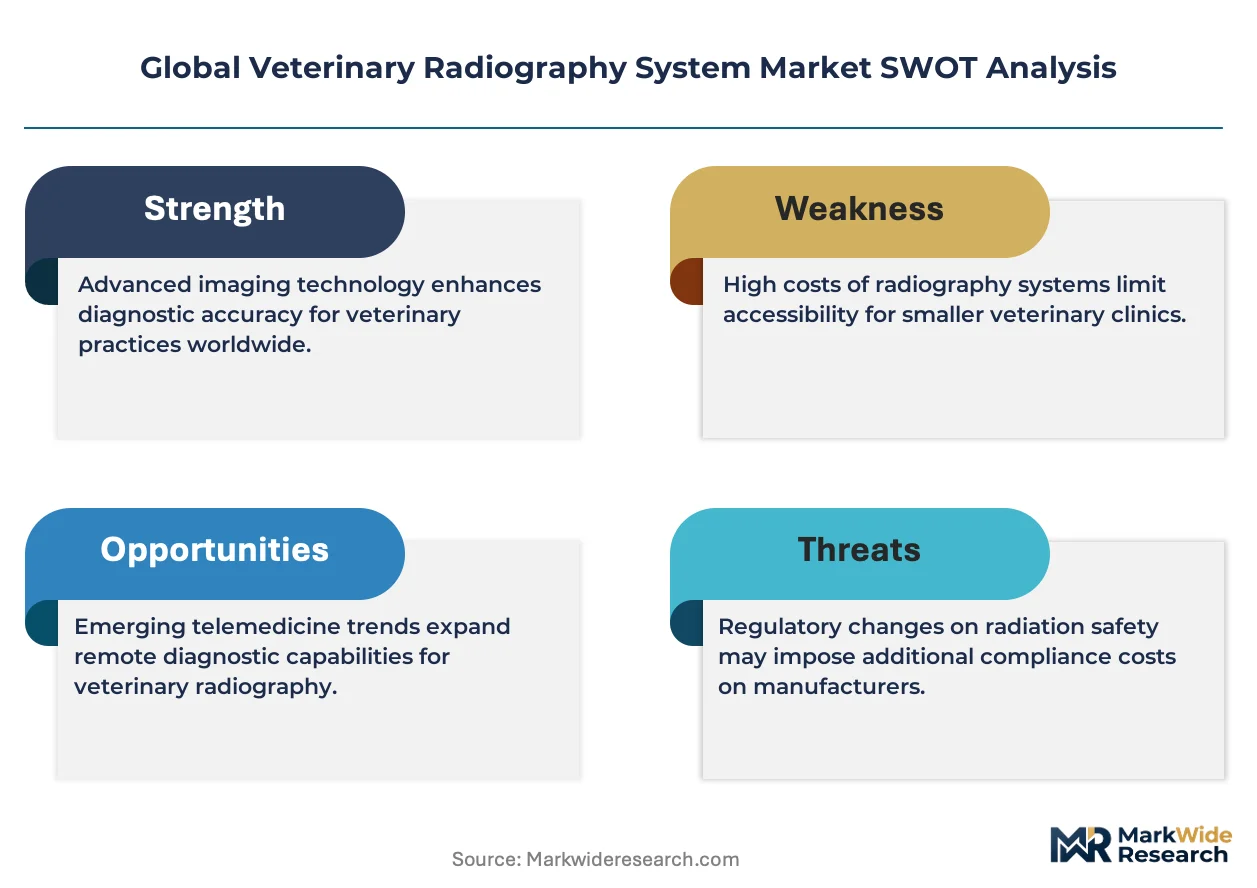
Digital flat-panel detector technology is decomposing the installed base of analog film-screen systems across companion animal clinics, compressing replacement cycles from decade-long intervals to five-to-seven-year refresh schedules as image quality standards escalate.
Growth Catalysts
- EU MDR post-market surveillance obligations:Stringent clinical evidence requirements for diagnostic imaging devices are filtering out low-quality imports, protecting premium manufacturers with established quality management systems.
- Mobile veterinary service expansion:Portable radiography units enable point-of-care imaging at farms, stables, and residential settings, extending diagnostic reach beyond fixed clinic infrastructure.
- Pet insurance penetration:Rising coverage rates in the United States and Germany reduce out-of-pocket cost sensitivity for advanced imaging procedures, accelerating equipment utilization.
Market Restraints
- Flat-panel detector supply concentration:Manufacturing of amorphous silicon and cesium iodide scintillator layers concentrates among Japanese and South Korean component suppliers, creating input vulnerability.
- FDA 510(k) clearance timelines:Pre-market notification pathways for software-as-medical-device classifications extend product launch schedules by twelve to eighteen months for AI-enhanced imaging modules.
- Computed tomography substitution:Declining cost curves for veterinary CT systems encroach on radiography's historical dominance in orthopedic and thoracic assessment.
Strategic Opportunities
- Telemedicine integration:Cloud-native image transmission protocols enable teleradiology services connecting general practitioners with boarded veterinary radiologists, expanding serviceable addressable market.
- Equine specialist channel:Large-animal practices in Kentucky, Newmarket, and Chantilly remain underpenetrated by digital systems, presenting first-mover potential for ruggedized portable units.
- ISO 13485 quality certification:Harmonized medical device quality management standards facilitate single-audit market access across multiple jurisdictions, reducing compliance redundancy.
Industry Challenges
- Veterinary radiographer training pipelines:Specialized positioning techniques for non-compliant patients require hands-on competency development that outpaces formal education program expansion.
- Legacy PACS integration:Digital radiography systems must interface with heterogeneous picture archiving infrastructure across independent clinic networks, complicating deployment workflows.
- Radiation safety officer designation:Regulatory mandates for designated personnel in clinic settings create staffing overhead that smaller practices struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Radiography System Market |
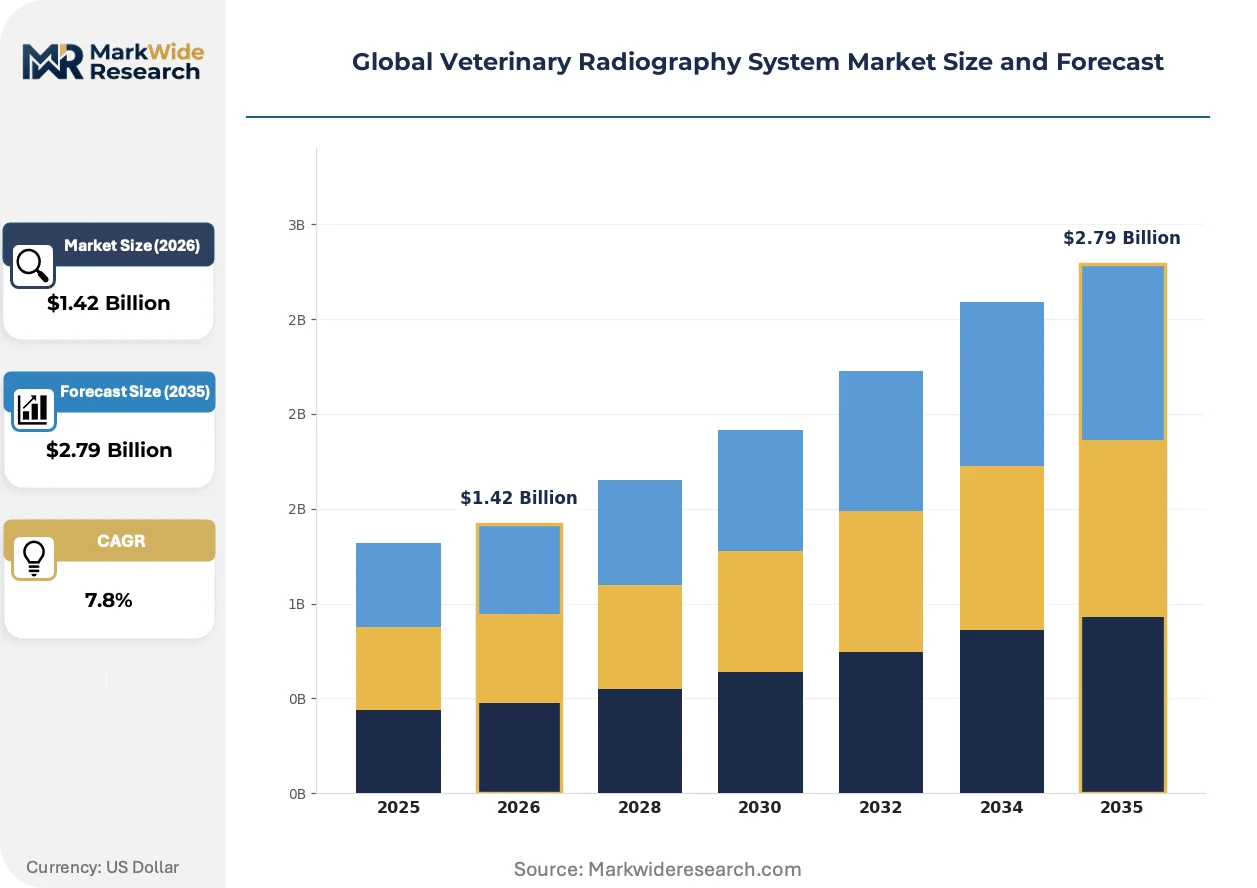
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Radiography, Analog Radiography, Computed Radiography, Portable Radiography, Cephalometric Radiography Technology: Flat Panel Detector, Charge Coupled Device, Photostimulable Phosphor Plate, Indirect Conversion, Direct Conversion Application: Small Animal Care, Large Animal Diagnostics, Equine Medicine, Exotic Animal Treatment, Livestock Monitoring End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Zoos, Mobile Veterinary Services |
| Companies Covered | Heska Corporation, Siemens Healthineers, Fujifilm Holdings Corporation, Sedecal USA, GE HealthCare, IDEXX Laboratories, Carestream Health, Lake Superior X-Ray, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Radiography System Market Shifts & Advancements
Artificial intelligence is penetrating image interpretation workflows, while hardware commoditization pressures manufacturers to differentiate through software and service layers. Three developments are restructuring competitive positioning.
Direct conversion detector architectures utilizing amorphous selenium photoconductors are decomposing the dominance of indirect conversion systems in equine and large-animal applications. Specialist practices in Lexington and Lambourn demand superior modulation transfer function performance at extended source-to-image distances. This technology shift compresses addressable market share for indirect conversion suppliers in premium segments.
Japan's PMDA has tightened software-as-medical-device classifications for AI-enhanced diagnostic algorithms, requiring clinical validation studies for machine learning modules embedded in radiography workstations. Manufacturers must submit prospective performance data demonstrating non-inferiority to human radiologist interpretation. This regulatory friction disproportionately affects Asian market entrants lacking established clinical trial infrastructure.
Consolidated purchasing by referral veterinary networks in the United States is compressing vendor margins through volume-scale procurement negotiations. Independent clinics in Texas and Florida increasingly delegate equipment selection to corporate procurement functions. This buyer concentration shifts pricing power toward multi-site operators and away from single-location practices.
Global Veterinary Radiography System Market Segmentation
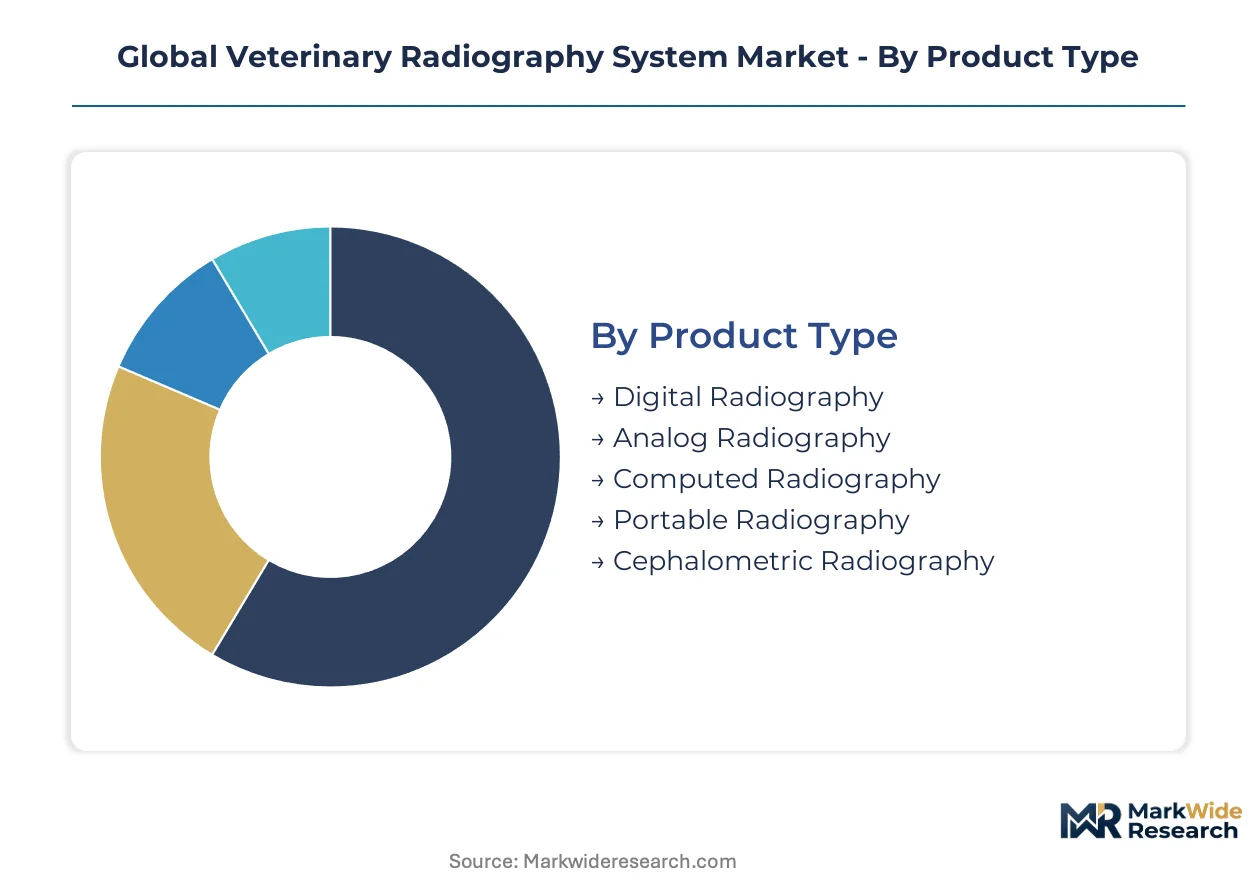
Segmentation in veterinary radiography systems reveals how technology substitution, workflow integration, and patient-type specialization create divergent growth trajectories across product categories. Understanding these fault lines helps manufacturers allocate R&D resources and distribution investments toward segments with durable competitive moats.
Product Type:
Digital radiography systems face intensifying substitution pressure from portable units and computed tomography in orthopedic applications, while analog installations erode fastest as regulatory radiation standards tighten.
- Digital Radiography:Flat-panel detector systems with 14-bit grayscale depth and sub-200 micron pixel pitch dominate fixed-installation environments. Demand concentrates in United States and German companion animal clinics where PACS integration and teleradiology workflows justify capital expenditure.
- Portable Radiography:Battery-powered units with wireless image transmission enable point-of-care imaging at farms, stables, and residential settings. Mobile veterinary services in Texas and Florida are expanding fleet acquisitions as house-call demand outpaces fixed-clinic growth.
- Analog Radiography:Film-screen systems persist in price-sensitive rural markets and developing veterinary economies where digital infrastructure remains absent.
- Computed Radiography:Photostimulable phosphor plate readers serve as transitional technology for clinics upgrading from analog without full digital detector investment.
- Cephalometric Radiography:Specialized skull-imaging systems support orthodontic and maxillofacial surgical planning in referral dentistry practices.
Digital radiography anchors the volume base while portable radiography gains share at the steepest rate.
Technology:
Cost tier stratification separates premium direct-conversion architectures from economy indirect-conversion systems, with detector fabrication depth determining margin capture across price bands.
- Flat Panel Detector:Amorphous silicon TFT arrays with cesium iodide scintillator layers constitute the mainstream technology platform. Japanese and South Korean component suppliers control scintillator deposition, creating input concentration for system assemblers.
- Direct Conversion:Amorphous selenium photoconductors eliminate light-scatter losses for superior modulation transfer function at extended source-to-image distances. Equine specialists in Kentucky and Newmarket pay premiums for large-animal thoracic imaging resolution.
- Indirect Conversion:Scintillator-photodiode architectures dominate small-animal applications where compact form factors and lower unit economics prevail.
- Charge Coupled Device:Legacy sensor technology persists in retrofit markets and budget-conscious clinic installations.
- Photostimulable Phosphor Plate:Reusable imaging plates with laser-scanning readout bridge analog-to-digital transitions in cost-constrained settings.
Flat panel detector technology commands the installed base while direct conversion climbs fastest in premium large-animal segments.
Application:
Customer type specialization fragments demand between high-volume small-animal general practice and low-volume, high-margin exotic species referral work.
- Small Animal Care:Canine and feline imaging constitutes the procedural volume core, with fracture assessment and thoracic evaluation driving utilization. Urban clinics in Tokyo and London achieve amortization through high caseload density.
- Equine Medicine:Portable systems with ruggedized enclosures serve ambulatory practitioners covering dispersed stables. Lexington, Newmarket, and Chantilly clusters concentrate purchasing power among large-animal referral networks.
- Large Animal Diagnostics:Bovine and porcine imaging supports production medicine and regulatory health certification in agricultural regions.
- Exotic Animal Treatment:Avian, reptile, and small mammal radiography requires specialized positioning restraint and reduced exposure protocols.
- Livestock Monitoring:Herd-level screening for metabolic and reproductive conditions in dairy and feedlot operations.
Small animal care anchors procedure volume while equine medicine expands most quickly as mobile service models proliferate.
End User:
Procurement concentration among corporate veterinary groups is compressing vendor margins while fragmenting purchasing authority across independent practice networks.
- Veterinary Clinics:General practice settings with 1-5 veterinarians represent the volume foundation, though corporate consolidation shifts pricing power toward centralized procurement functions.
- Animal Hospitals:24-hour emergency and specialty referral centers with boarded radiologists demand premium image quality and rapid turnaround. University teaching hospitals in Davis, Utrecht, and Tokyo drive technology validation.
- Mobile Veterinary Services:House-call and farm-visit practitioners require battery-powered, wireless-enabled portable systems. Fleet expansion in United States Sun Belt states outpaces fixed-clinic growth.
- Research Institutes:Preclinical imaging and pharmaceutical toxicology studies demand calibrated quantitative radiography.
- Zoos:Institutional wildlife health programs require anesthesia-compatible positioning systems for non-domestic species.
Veterinary clinics retain the volume base while mobile veterinary services accelerate fastest as labor models shift toward flexible deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German companion animal clinics where pet insurance density exceeds United States levels, while Japanese equine specialists command premiums for direct-conversion detector resolution at extended source-to-image distances.
United States
Corporate veterinary consolidation in Texas and Florida shifts procurement authority toward centralized buying functions, compressing vendor margins. The FDA Center for Devices and Radiological Health governs 510(k) clearance pathways that extend software-as-medical-device launch schedules. Lexington, Kentucky anchors equine specialist demand where ambulatory practitioners require ruggedized portable systems for stable-side thoracic imaging.
Germany
Pet insurance penetration above sixty percent reduces out-of-pocket cost sensitivity for advanced imaging procedures in Munich and Berlin metropolitan clinics. The EU Medical Device Regulation imposes clinical evidence and post-market surveillance obligations that filter low-quality imports. The Baden-Württemberg industrial corridor concentrates detector component fabrication, creating captive supply advantages for domestic system assemblers.
Japan
PMDA review standards for pharmaceutical and medical device agency submissions shape product localization requirements for Asian market entry. Amorphous silicon TFT array production concentrates among component suppliers in the Kanto region, creating input vulnerability for foreign system integrators. Tokyo university teaching hospitals drive technology validation for AI-enhanced image processing modules.
United Kingdom
Referral veterinary networks in Newmarket and Lambourn demand superior modulation transfer function performance for large-animal thoracic assessment. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-Brexit device registrations. London corporate groups consolidate purchasing power across multi-site small-animal practices.
Australia
Mobile veterinary service expansion in Queensland and Victoria outpaces fixed-clinic infrastructure growth, accelerating portable radiography fleet acquisitions. The Therapeutic Goods Administration maintains distinct medical device classification standards that affect software-as-medical-device review pathways. Sydney and Melbourne university hospitals validate preclinical imaging protocols for pharmaceutical toxicology studies.
Global Veterinary Radiography System Market Competitive Landscape
Concentration sits with full-platform manufacturers controlling detector fabrication depth and integrated diagnostics bundlers. The vendor base separates into three strategic archetypes: imaging conglomerates with captive sensor production, veterinary-specific diagnostics integrators, and component assemblers dependent on external detector supply. Dominant competitive moves include backward integration into scintillator deposition and strategic partnerships bundling imaging hardware with laboratory diagnostics.
Within the imaging conglomerate tier, Siemens Healthineers and Fujifilm Holdings Corporation exemplify players with in-house production of flat-panel detector substrates. IDEXX Laboratories occupies a position representing veterinary-specific diagnostics integrators leveraging channel control through bundled equipment procurement. These three anchors demonstrate how fabrication depth and workflow integration separate margin capture from price-competitive hardware assembly.
| Leading Market Players |
|---|
| Heska Corporation |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Sedecal USA |
| GE HealthCare |
| IDEXX Laboratories |
| Carestream Health |
| Lake Superior X-Ray |
| Canon Medical Systems Corporation |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day lead times for cesium iodide scintillator deposition concentrate pricing power with Japanese and South Korean substrate suppliers, while German and United States system assemblers absorb margin compression from detector input scarcity. This inventory intensity separates full-platform manufacturers with captive fabrication from component integrators exposed to spot-market volatility.
Pricing Analysis
Configured-to-order pricing for direct-conversion equine systems commands forty-to-sixty percent premiums over standard indirect-conversion small-animal configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector bit depth, software workflow integration, and after-sales service bundling. Price erosion runs through the portable radiography segment as Texas and Florida mobile veterinary services consolidate fleet procurement. Independent clinics in rural United States markets exhibit highest price sensitivity, while Japanese university teaching hospitals demonstrate lowest elasticity for AI-enhanced workstation modules.
Supply Chain Analysis
Amorphous silicon TFT array fabrication concentrates in Japan's Kanto region and South Korea's Gyeonggi cluster, creating single-source vulnerability for foreign system integrators lacking captive deposition capacity. Cesium iodide scintillator layers, amorphous selenium photoconductors, and wireless transmission modules constitute critical input dependencies. Tariff exposure on Japanese component imports threatens margin stability for European and North American assemblers. Distribution runs through veterinary diagnostics distributors in the United States, direct hospital sales in Germany, and regional equipment dealers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Veterinary Radiography System Market enters a cyclical recovery phase as decade-long analog replacement cycles compress to five-to-seven-year refresh schedules, driven by escalating image quality standards and regulatory radiation safety mandates.
For Market Incumbents: Compound channel control through integrated diagnostics-to-imaging bundling that locks in clinic procurement decisions, while deepening backward integration into scintillator deposition to defend margins against Japanese and South Korean substrate suppliers. CT substitution in orthopedic applications and corporate buyer consolidation in Texas and Florida represent imminent threats requiring software workflow differentiation and volume-scale contract structures. For New Entrants and Emerging Players: ISO 13485 certification fast-track enables single-audit market access across United States FDA, EU MDR, and Japanese PMDA jurisdictions, reducing compliance redundancy for capital-constrained challengers. Underpenetrated equine specialist clusters in Kentucky, Newmarket, and Chantilly offer white-space entry points for ruggedized portable units with direct-conversion architectures. Target mobile veterinary services in United States Sun Belt states through battery-powered wireless-enabled form factors and teleradiology workflow partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial imaging conglomerates seeking to divest non-core veterinary verticals, presenting acquisition opportunities for platforms with detector fabrication depth and established regulatory dossiers. Long-term viability hinges on AI-enhanced software module recurring revenue streams and service contract attach rates. Watch FDA software-as-medical-device classification expansion as the inflection signal for premarket review burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Captive cesium iodide scintillator deposition insulates margin capture from Japanese and South Korean supply concentration. |
| AI-Enhanced Software Module Development | FDA 510(k) clearance for machine learning image processing creates recurring revenue attach and workflow lock-in. |
| Equine Specialist Channel Partnership | Direct-conversion portable unit deployment in Kentucky and Newmarket clusters penetrates premium large-animal segments. |
| Teleradiology Platform Integration | Cloud-native image transmission connects general practitioners with boarded veterinary radiologists, expanding serviceable addressable market. |
| ISO 13485 Quality Certification Investment | Harmonized medical device quality management facilitates single-audit access across FDA, EU MDR, and PMDA jurisdictions. |
Research Methodology
The analysis maps digital radiography systems, portable radiography units, and detector technology sub-sectors, each validated through biomedical engineers, veterinary clinic procurement managers, GPO contracts administrators, and referral network operations directors. Primary interview intelligence triangulates against FDA 510(k) filings, EU MDR clinical evidence submissions, PMDA device registrations, and hospital procurement database records. Bottom-up equipment shipment tracking and top-down veterinary services revenue estimation cross-validate market size outputs.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions model product type, technology architecture, application specialization, and end-user procurement concentration. CAGRs derive from installed base replacement cycle analysis, pet insurance penetration trajectories, and mobile veterinary service expansion rates. Forecast inputs incorporate detector fabrication capacity constraints, software-as-medical-device regulatory friction, and corporate consolidation-driven pricing compression.
Decision-makers should treat outputs as directional under sustained pet insurance expansion and stable FDA review timelines; material deviation in reimbursement policy or AI classification stringency would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance obligations and Japanese PMDA software validation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market