
 Global Digital Radiography Market | 2026-2036
Global Digital Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Radiography Market Foresight
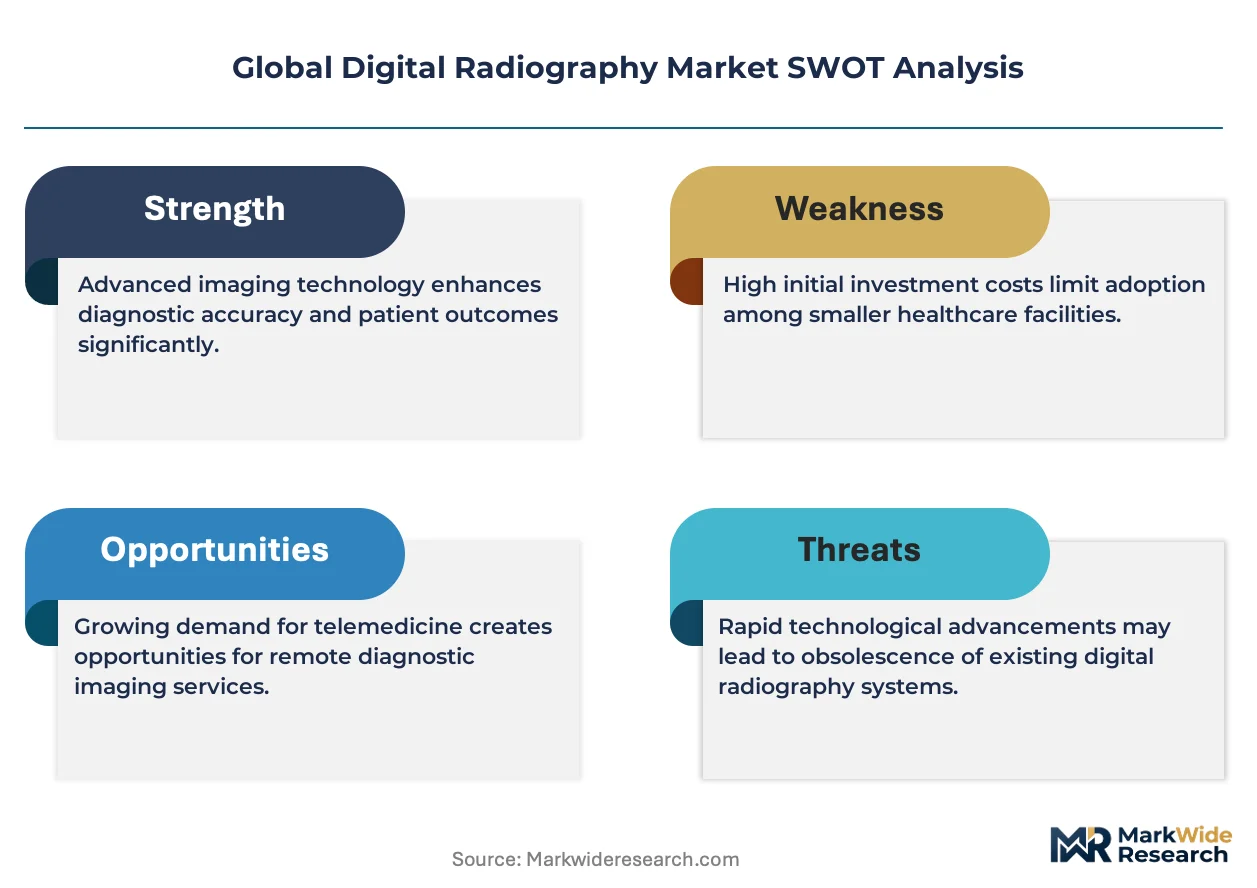
Wireless detector integration with cloud-based PACS architecture is tilting procurement criteria toward interoperability and remote diagnostics. Siemens Healthineers leverages its installed base of imaging suites to bundle digital radiography upgrades with service contracts. GE Healthcare anchors its position through in-house production of amorphous silicon flat panels, reducing dependency on external sensor foundries. Philips Healthcare differentiates via diagnostic workflow software that embeds AI-assisted image enhancement.
Digital radiography encompasses X-ray imaging systems that convert ionizing radiation directly into electronic signals for real-time visualization and storage, typically employing cesium iodide or gadolinium oxysulfide scintillators coupled to thin-film transistor arrays with spatial resolution exceeding 3.5 line pairs per millimeter. Flat panel detectors dominate capital expenditure budgets due to their superior dose efficiency and instant image availability compared to computed radiography cassettes. CMOS sensor technology is gaining share in portable and veterinary applications where lower power draw and faster readout speeds offset higher unit costs. Security screening represents an emerging application segment driven by customs modernization programs requiring high-throughput baggage and cargo inspection.
The FDA enforces radiation safety standards under 21 CFR 1020.32, mandating exposure index tracking and dose monitoring features that manufacturers must integrate at the firmware level. EMA's Medical Device Regulation requires clinical evidence documentation for digital radiography systems marketed in Europe, extending certification timelines and favoring established players with dedicated regulatory affairs teams. Japan's PMDA maintains stringent electromagnetic compatibility testing protocols that filter out lower-cost entrants. Stakeholders must weigh detector refresh rate specifications against total cost of ownership as healthcare systems consolidate purchasing authority into regional procurement networks.
Market Dynamics
Wireless flat-panel detectors are compressing replacement cycles across hospital radiology departments, forcing capital equipment vendors to bundle software subscriptions with hardware sales or lose procurement decisions to cloud-native competitors.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's abbreviated clearance process for digital X-ray iterations accelerates product launches for manufacturers targeting the US market, reducing time-to-revenue by twelve to eighteen months for incremental detector upgrades.
- Cesium iodide scintillator advances:Improved conversion efficiency in direct-capture detectors cuts patient radiation dose by thirty to fifty percent compared to analog film systems, driving replacement demand in pediatric and oncology screening protocols.
- German component clustering:Dense supplier networks around Erlangen and Forchheim enable rapid prototyping cycles and shared validation infrastructure that shorten development timelines for next-generation flat-panel architectures.
Market Restraints
- Amorphous silicon wafer concentration:Thin-film transistor substrate production concentrates among three East Asian foundries, exposing detector manufacturers to single-source disruption risk and input price volatility during semiconductor allocation cycles.
- EMA MDR clinical evidence requirements:Europe's Medical Device Regulation mandates prospective clinical studies for new digital radiography systems, extending certification timelines to twenty-four to thirty-six months and freezing out development-stage entrants lacking dedicated regulatory affairs capacity.
- Computed radiography cassette residual value:Existing CR infrastructure in cost-constrained health systems delivers adequate image quality for non-diagnostic screening, delaying full DR conversion and compressing addressable market expansion in price-sensitive segments.
Strategic Opportunities
- Veterinary dentistry specialization:CMOS sensor miniaturization enables intraoral radiography systems for companion animal practices, an application segment where premium pricing tolerance exceeds human healthcare equivalents and regulatory barriers remain minimal.
- India PLI scheme localization:Production-linked incentives for medical electronics manufacturing offer tariff advantages and government procurement preference to domestic assembly operations, creating beachhead positions for regional supply chain buildout.
- Security screening modernization:Customs agencies in Singapore and the Netherlands are replacing legacy baggage inspection systems with high-throughput digital radiography arrays capable of automated threat detection algorithm integration.
Industry Challenges
- Medical physics specialist scarcity:Dose optimization protocol configuration and acceptance testing require certified professionals whose training pipelines have not kept pace with installed base expansion, creating service backlogs and warranty exposure.
- PACS interoperability fragmentation:Proprietary image format implementations across vendor ecosystems force healthcare IT departments to maintain multiple translation layers, elevating integration costs and complicating enterprise-wide archive consolidation.
- Detector refresh rate specification inflation:Competitive benchmarking on technical parameters disconnected from clinical utility pressures engineering resources toward marginal gains rather than cost reduction or reliability improvement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Radiography Market |
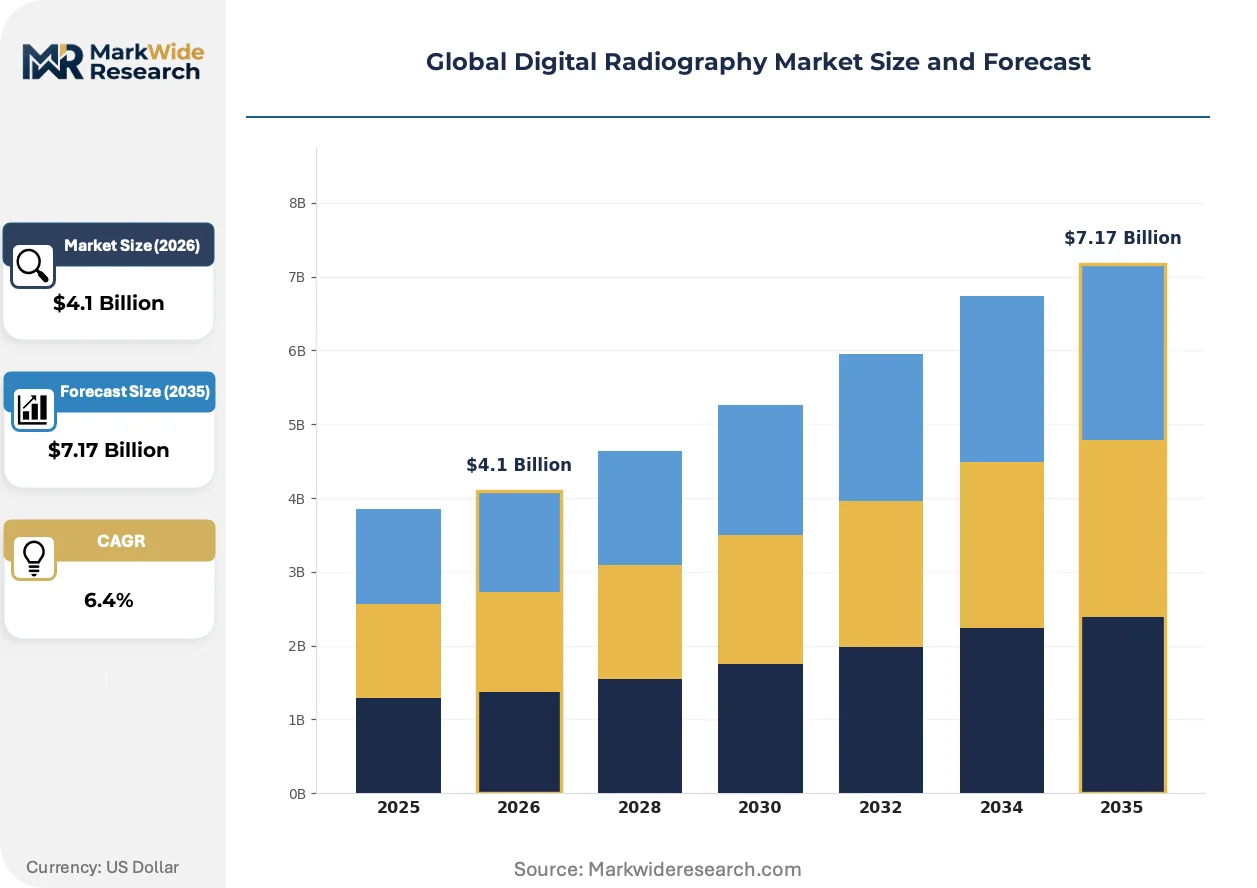
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography, Direct Radiography, Indirect Radiography Technology: Amorphous Silicon, CMOS, CCD, Photostimulable Phosphor Application: Orthopedics, Dentistry, Veterinary, Aerospace, Security Screening End User: Diagnostic Centers, Imaging Clinics, Research Institutions, Military Surveillance |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, FUJIFILM Holdings Corporation, Canon, Agfa-Gevaert Group, Konica Minolta, Carestream Health, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Radiography Market Shifts & Advancements
Artificial intelligence inference at the detector edge is restructuring competitive advantage around software-enabled workflow automation rather than pure hardware specifications.
CMOS active pixel sensor technology is rendering obsolete amorphous silicon flat-panel detectors in portable radiography applications where battery endurance and rapid sequential imaging determine purchase decisions. Mobile X-ray fleet operators in emergency departments and intensive care units are specifying CMOS-based systems exclusively for new procurements despite thirty to forty percent unit cost premiums. This sensor architecture transition is compressing margins for manufacturers lacking in-house CMOS design capability or captive foundry relationships.
The EU AI Act's risk classification framework for medical device software is mandating conformity assessment procedures for AI-assisted image enhancement algorithms embedded in diagnostic workflows. Manufacturers must now maintain technical documentation and post-market surveillance systems for machine learning components previously treated as ancillary features. European radiology equipment vendors are responding by segregating AI development into standalone software modules subject to separate regulatory pathways rather than integrated firmware.
Regional procurement networks in Germany, France, and the United Kingdom are consolidating purchasing authority for digital radiography systems into centralized tendering bodies that negotiate multi-hospital framework agreements. Independent distributors and local sales subsidiaries are losing access to decision-makers as tender specifications increasingly mandate direct manufacturer contracting and pan-European service coverage. This channel compression is most visible in National Health Service England's diagnostic imaging equipment frameworks, which now cover sixty to seventy percent of acute trust capital expenditure.
Global Digital Radiography Market Segmentation
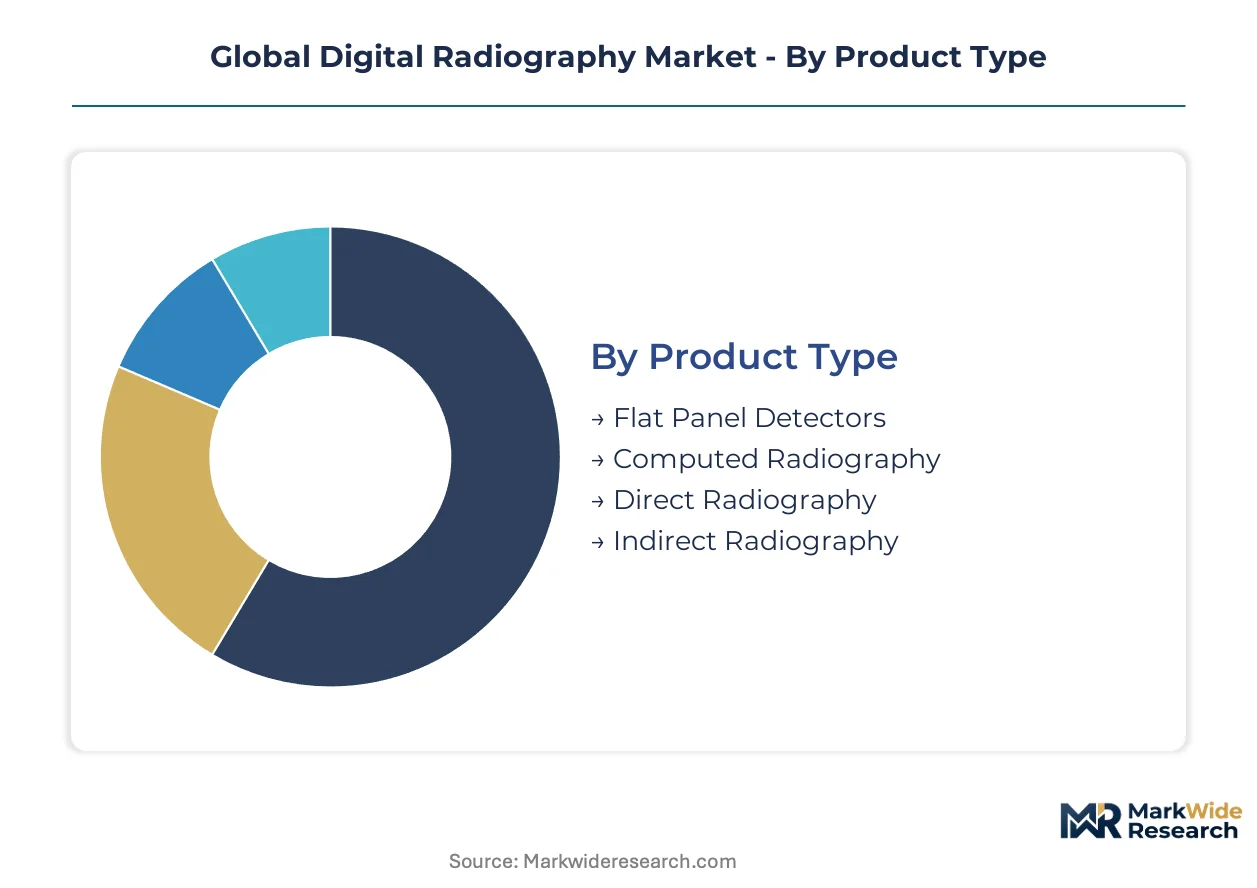
Digital radiography procurement diverges sharply across clinical, industrial, and security domains, with detector specifications and regulatory pathways dict entirely different commercial strategies. Understanding these segment boundaries clarifies why vendors like Siemens Healthineers and GE Healthcare maintain parallel product architectures rather than unified platforms.
Product Type:
Clinical throughput requirements and capital replacement cycles define the use-case spectrum across detector architectures.
- Flat Panel Detectors:These systems employ cesium iodide or gadolinium oxysulfide scintillators coupled to thin-film transistor arrays, delivering spatial resolution exceeding 3.5 line pairs per millimeter. Hospital radiology departments in Germany and the United States concentrate demand here, driven by dose efficiency mandates and pediatric screening protocols that reward instant image availability.
- Computed Radiography:Photostimulable phosphor cassettes retain residual value in cost-constrained health systems where image quality requirements remain modest. India's tier-2 diagnostic centers and Latin American public hospitals sustain this segment despite its technical obsolescence, as CR infrastructure delays full digital conversion.
- Direct Radiography:Selenium-based direct-capture detectors eliminate scintillator conversion losses, achieving superior dose efficiency for oncology and bariatric applications. Research institutions in Japan and Switzerland specify these systems for longitudinal studies requiring minimal radiation exposure.
- Indirect Radiography:Silicon photodiode arrays with structured cesium iodide layers balance cost and performance for mobile and veterinary deployments. Australian companion animal practices and Dutch equine clinics favor this architecture for its portability.
The dominant share belongs to Flat Panel Detectors, while Direct Radiography is closing the gap fastest.
Technology:
Sensor foundry capacity and power consumption specifications segment the supply base into distinct manufacturing ecosystems.
- Amorphous Silicon:Thin-film transistor substrates dominate fixed-installation radiography suites due to mature foundry economics and established reliability data. East Asian foundry concentration in Taiwan and South Korea exposes manufacturers to allocation risk during semiconductor cycles.
- CMOS:Active pixel sensors enable rapid sequential imaging and extended battery endurance for portable systems. Emergency departments in the United Kingdom and mobile X-ray fleet operators in France now specify CMOS exclusively despite thirty to forty percent unit cost premiums.
- CCD:Charge-coupled device technology persists in legacy dental intraoral systems and specialized industrial inspection equipment. Brazilian and Mexican dental equipment assemblers maintain CCD supply chains for price-sensitive export markets.
- Photostimulable Phosphor:Barium fluorohalide crystals enable computed radiography's reusable cassette architecture. Russian and Eastern European healthcare systems with limited capital budgets continue procurement of phosphor-based systems.
Amorphous Silicon retains installed base dominance, though CMOS is expanding most quickly in new procurements.
Application:
Regulatory classification intensity and reimbursement pathways fragment demand across medical and non-medical domains.
- Orthopedics:Weight-bearing extremity imaging and trauma screening drive specifications for high-resolution detectors with rapid readout. German trauma centers and Swedish sports medicine clinics prioritize systems with automated stitching algorithms for long-bone assessment.
- Dentistry:Intraoral and panoramic systems require miniaturized sensors with reduced radiation output for repetitive exposure protocols. Japanese dental chains and South Korean cosmetic surgery centers generate concentrated demand for premium digital panoramic units.
- Veterinary:Companion animal practices and equine hospitals tolerate higher per-procedure pricing than human healthcare equivalents. Australian veterinary dentistry and Dutch equine reproduction centers represent high-margin niches with minimal regulatory friction.
- Aerospace:Non-destructive testing of turbine blades and composite structures demands high-dynamic-range detectors for thick-section penetration. French and German aerospace maintenance facilities specify systems compliant with EN 17636 weld inspection standards.
- Security Screening:Customs modernization programs in Singapore and the Netherlands drive replacement of legacy baggage inspection systems. High-throughput arrays with automated threat detection algorithm integration command premium positioning.
Orthopedics commands the largest revenue pool, yet Security Screening is gaining share fastest on customs infrastructure investment cycles.
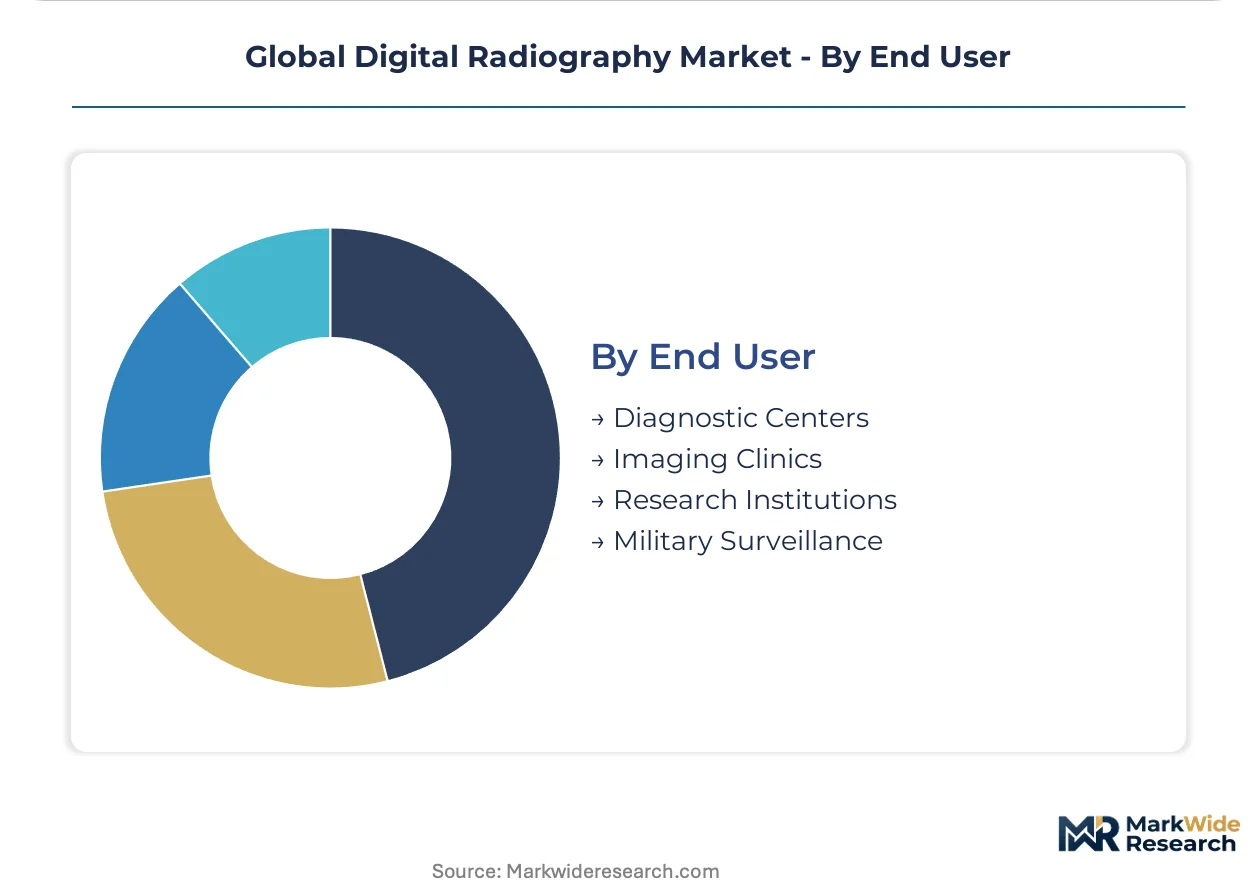
End User:
Procurement authority consolidation and service coverage requirements reshape channel economics across customer types.
- Diagnostic Centers:High-volume outpatient imaging operations prioritize throughput metrics and PACS integration depth. India's corporate hospital chains and Brazil's diagnostic networks negotiate multi-site framework agreements with direct manufacturer contracting.
- Imaging Clinics:Independent radiology practices balance capital constraints against competitive positioning through technology differentiation. Italian and Spanish private clinic associations pool purchasing power through regional procurement consortia.
- Research Institutions:Academic medical centers demand detector calibration traceability and longitudinal stability data for funded studies. Swiss and Dutch university hospitals specify systems with open software architectures for algorithm development.
- Military Surveillance:Defense procurement programs emphasize ruggedization and electromagnetic compatibility for field-deployable systems. Saudi and UAE border security agencies drive demand for mobile radiography arrays with satellite uplink capability.
Diagnostic Centers hold the dominant position, while Military Surveillance is climbing the fastest on defense modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export digital radiography systems to healthcare networks across the United States, India, and Brazil, establishing Erlangen and Forchheim as critical supply nodes for detector components and clinical validation infrastructure.
United States
Hospital radiology departments in Texas and Florida are replacing analog systems with digital flat-panel detectors to accelerate patient throughput. The FDA's 510(k) clearance pathway shapes product development timelines for manufacturers entering this market. Siemens Healthineers maintains significant installed base leverage through service contract bundling across major metropolitan hospital networks.
Germany
Trauma centers in Bavaria and Baden-Württemberg prioritize high-resolution detectors with automated stitching algorithms for long-bone assessment. EMA's Medical Device Regulation requires clinical evidence documentation, extending certification timelines and favoring established players. Dense supplier networks around Erlangen enable rapid prototyping cycles for next-generation flat-panel architectures.
Japan
Research institutions in Tokyo and Osaka specify selenium-based direct-capture detectors for longitudinal studies requiring minimal radiation exposure. PMDA maintains stringent electromagnetic compatibility testing protocols that filter out lower-cost entrants. Dental chains in Kanto generate concentrated demand for premium digital panoramic units with reduced radiation output protocols.
India
Corporate hospital chains in Maharashtra and Karnataka negotiate multi-site framework agreements with direct manufacturer contracting. The PLI scheme for medical electronics manufacturing offers tariff advantages and government procurement preference to domestic assembly operations. Tier-2 diagnostic centers in Gujarat sustain computed radiography demand despite technical obsolescence, delaying full digital conversion.
United Kingdom
Emergency departments in London and Manchester now specify CMOS-based systems exclusively for new procurements despite unit cost premiums. National Health Service England's diagnostic imaging equipment frameworks cover sixty to seventy percent of acute trust capital expenditure, consolidating purchasing authority. Mobile X-ray fleet operators across the National Health Service prioritize battery endurance and rapid sequential imaging capabilities.
Global Digital Radiography Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified imaging conglomerates with captive detector foundries, specialized radiography equipment vendors with software-centric differentiation, and regional assemblers leveraging government localization incentives. Competitive dynamics center on M&A activity targeting AI-enabled workflow software capabilities and strategic partnerships with cloud-native PACS providers to secure procurement decisions in consolidated hospital networks.
Within the diversified imaging conglomerate tier, Siemens Healthineers and GE Healthcare exemplify players leveraging installed base leverage and in-house component production to defend margin positions. Philips Healthcare occupies a position emphasizing diagnostic workflow software with embedded AI-assisted image enhancement. Among specialized equipment vendors, FUJIFILM Holdings Corporation and Canon represent archetypes pursuing differentiation through sensor technology specialization and vertical market focus.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| FUJIFILM Holdings Corporation |
| Canon |
| Agfa-Gevaert Group |
| Konica Minolta |
| Carestream Health |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
East Asian amorphous silicon foundry concentration in Taiwan and South Korea anchors input cost volatility for detector manufacturers, compressing margin pools at the flat-panel assembly tier while rewarding players with captive sensor production or long-term offtake agreements.
Pricing Analysis
Amorphous silicon-to-CMOS technology-generation pricing gaps now span forty to sixty percent at the system level, with premium CMOS-based portable units commanding three-tier pricing structure across premium, standard, and economy levels differentiated by detector refresh rate and AI software bundling. Certification grade—specifically FDA 510(k) clearance versus CE self-declaration—drives fifteen to twenty-five percent price premiums in tender specifications. Pricing pressure stems from regional procurement network consolidation in Germany and the United Kingdom, where multi-hospital frameworks squeeze list prices. Diagnostic centers in India and Brazil exhibit highest price sensitivity, while research institutions in Switzerland and Japan tolerate premium positioning for calibration traceability.
Supply Chain Analysis
Upstream feedstock for cesium iodide scintillators draws from specialized chemical processors in Japan and Germany, with thin-film transistor substrates sourced predominantly from Taiwan, South Korea, and select Chinese foundries. Raw material dependencies center on high-purity selenium for direct-capture detectors, rare-earth phosphors for computed radiography, and semiconductor-grade silicon wafers. Single-source vulnerability concentrates in amorphous silicon TFT backplane production, where three foundries control ninety percent of medical-grade supply. Distribution runs through direct manufacturer contracting with hospital procurement consortia, displacing independent distributors in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global digital radiography is cycling through a capital equipment replacement wave as healthcare systems exhaust computed radiography residual value and confront pediatric dose mandates, with hospital radiology department budget releases in Germany and Texas signaling trough-to-peak momentum.
For Market Incumbents: Insulate service contract revenue streams by embedding wireless detector upgrades with predictive maintenance algorithms, countering cloud-native PACS competitors. Deepen backward integration into CMOS sensor design through strategic foundry partnerships or acquisitions, reducing exposure to East Asian allocation cycles. Prioritize regulatory affairs capacity expansion to navigate EMA MDR clinical evidence requirements that freeze out development-stage entrants.
For New Entrants and Emerging Players: Build out veterinary dentistry specialization in Australia and the Netherlands, where premium pricing tolerance exceeds human healthcare and FDA 510(k) pathways remain streamlined. Target India's PLI scheme localization for medical electronics manufacturing, securing tariff advantages and government procurement preference. Lead with CMOS-based portable systems for mobile X-ray fleet operators in France and the United Kingdom, bypassing fixed-installation incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward AI-enabled workflow software specialists with existing FDA clearances for image enhancement algorithms, positioned for EU AI Act conformity assessment mandates. Long-term viability hinges on separating machine learning components into standalone regulatory pathways rather than integrated firmware. Watch for inflection in NHS England framework renewal cycles, where diagnostic imaging equipment tenders covering sixty to seventy percent of acute trust capital expenditure signal consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Technology Transition | Portable radiography procurement in UK emergency departments now specifies CMOS exclusively despite unit cost premiums. |
| AI-Assisted Image Enhancement Development | EU AI Act risk classification mandates conformity assessment procedures for diagnostic workflow software components. |
| Regional Procurement Network Direct Contracting | NHS England frameworks covering sixty to seventy percent of acute trust expenditure displace independent distributors. |
| Veterinary Dentistry Miniaturization | Australian companion animal practices tolerate higher per-procedure pricing than human healthcare equivalents. |
| India PLI Scheme Localization | Production-linked incentives offer tariff advantages and government procurement preference to domestic assembly operations. |
Research Methodology
A spread of perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at detector manufacturers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, hospital procurement frameworks from NHS England and German regional tendering bodies, and semiconductor foundry capacity disclosures. Bottom-up demand modeling by detector architecture and application segment was triangulated against top-down healthcare capital expenditure forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning detector technology type, clinical versus non-medical application, and procurement authority concentration level. CAGRs were derived from installed base replacement cycle analysis and procurement pipeline visibility. Industry-specific forecast inputs included PACS interoperability migration timelines and medical physics specialist training pipeline capacity constraints.
Sensitivities concentrate around semiconductor allocation cycle duration, EMA MDR certification timeline extensions, and regional procurement network consolidation pace. Forecasts reflect documented assumptions about wireless detector adoption curves and AI software bundling penetration. Cross-checking against hospital capital budget release schedules from Texas, Bavaria, and Maharashtra is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Global Veterinary CT Scanner Market