
 Orthodontic Supplies Market | 2026-2036
Orthodontic Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Supplies Market Analysis
Multi-source procurement for nickel-titanium archwires and ceramic brackets is hardening as manufacturers seek supply resilience against raw material volatility. Straumann Group anchors its position through captive production of premium orthodontic implants and related consumables. Align Technology Inc. differentiates via proprietary digital scanning ecosystems that lock clinics into recurring aligner shipments. Dentsply Sirona Inc. sustains manufacturing scale across metal and ceramic bracket lines while competing on distributor breadth.
Orthodontic supplies encompass fixed and removable appliances, anchorage devices, and adjunctive materials engineered to precise torque and force specifications, typically fabricated from nickel-titanium alloys, medical-grade ceramics, or biocompatible polymers through milling, molding, or additive processes. Their commercial purpose is to correct dental malocclusion and craniofacial anomalies under professional supervision. Metal brackets still occupy the largest volume pool globally, though aligner systems built on 3D printing and digital scanning represent the fastest-expanding margin segment. Ceramic materials command premium positioning for adult aesthetic cases, while plastic composites serve entry-level clear appliance tiers.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern biocompatibility and mechanical performance standards for orthodontic devices sold in the United States and Europe, with ISO 13485 certification now baseline for supplier qualification. China's NMPA enforces GB standards for imported and domestically produced orthodontic materials, creating divergent testing requirements for multinational manufacturers. Stakeholders must monitor regulatory harmonization progress between major jurisdictions to anticipate compliance cost shifts and market access timing.
Market Dynamics
Digital orthodontic workflows are compressing treatment planning cycles and redistributing value from bracket manufacturers toward software-integrated aligner platforms.
Growth Catalysts
- Clear aligner technology:3D printing and intraoral scanning reduce chair time and expand addressable patient pools beyond traditional adolescent brackets.
- EU MDR conformity pathways:Harmonized biocompatibility standards accelerate multi-country product launches for polymer-based appliances.
- Adult aesthetic demand:Ceramic and transparent systems capture professional demographics in China's tier-one cities.
Market Restraints
- Nickel-titanium price volatility:Archwire input costs fluctuate with mining supply from Southeast Asian concentrate producers.
- NMPA testing divergence:China's GB standards require separate clinical dossiers, extending approval timelines versus FDA 510(k) pathways.
- Lingual bracket technical ceiling:Customization complexity limits production scale and keeps unit economics above chairside tolerance thresholds.
Strategic Opportunities
- India's underpenetrated tier-2 cities:CDSCO streamlined medical device rules open distribution expansion beyond Mumbai and Delhi clusters.
- Remote monitoring convergence:Smartphone-based progress tracking merges with aligner platforms to reduce clinic visit frequency.
- Japan's aging malocclusion correction:PMDA reimbursement shifts for adult orthodontic intervention broaden covered indications.
Industry Challenges
- Digital workflow integration:Legacy practice management systems resist API connectivity with cloud-based treatment planning software.
- ISO 13485 auditor scarcity:Certification backlog delays supplier qualification for mid-tier manufacturers seeking European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Supplies Market |
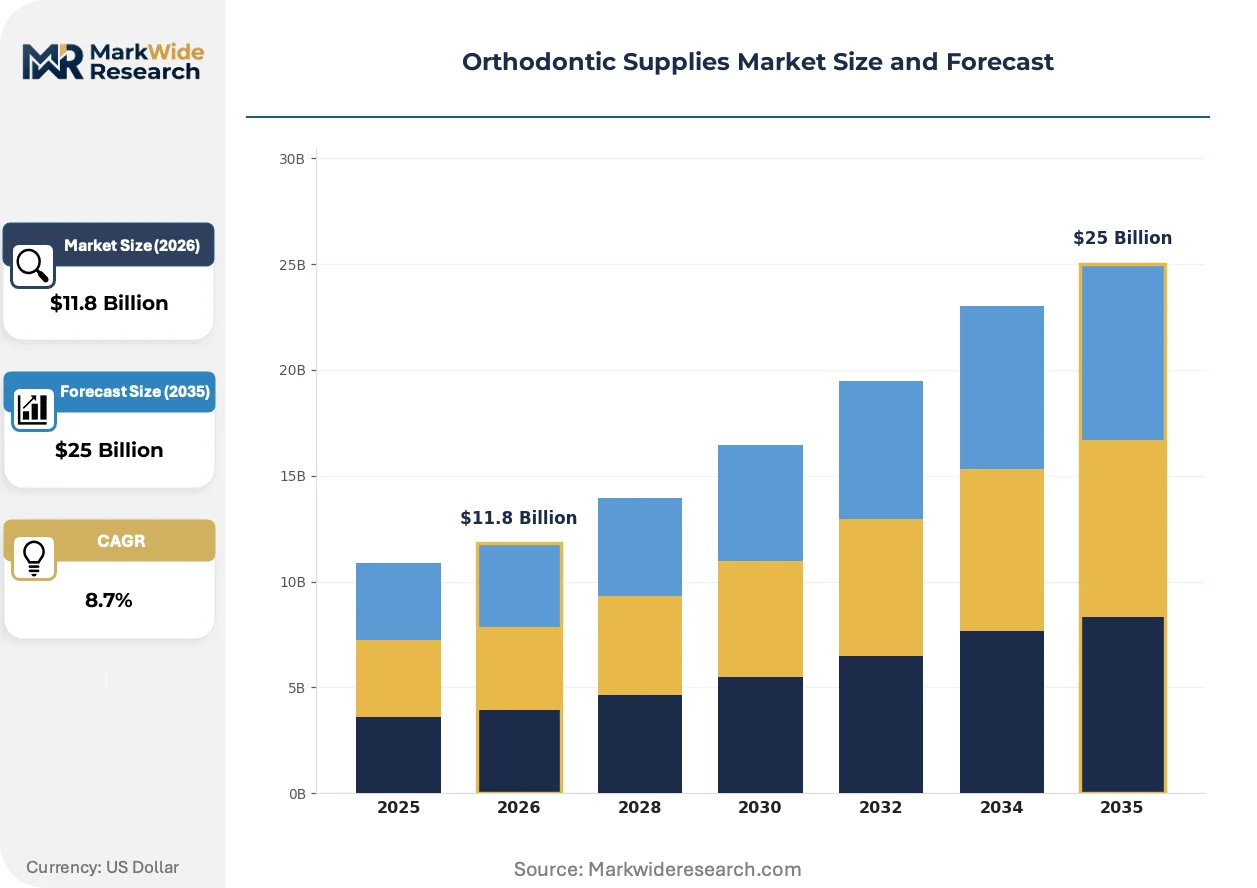
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Archwires, Bands, Sliders End User: Orthodontists, Dental Clinics, Hospitals, Laboratories Technology: 3D Printing, Digital Scanning, Aligners, Traditional Methods Material: Metal, Ceramic, Plastic, Composite |
| Companies Covered | 3M Company, Ormco Corporation, Align Technology Inc., Straumann Group, American Orthodontics, Dentsply Sirona Inc., Henry Schein Inc., TP Orthodontics Inc., Envista Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Supplies Market Emerging Trajectories
Orthodontic supply chains are reconfiguring around point-of-care manufacturing and direct-to-clinic digital distribution, compressing traditional distributor margins.
Intraoral scanning hardware is decentralizing impression capture from centralized dental labs to individual clinic operatories. General practitioner dentists in suburban United States markets adopt chairside scanners at replacement cycles under four years. This shift collapses physical mold shipping logistics and accelerates aligner production turnaround.
EU MDR technical documentation requirements are elevating clinical evidence thresholds for nickel-titanium archwire biocompatibility claims. Manufacturers must submit extended cytotoxicity and nickel ion release datasets. European orthodontic suppliers absorb testing costs into premium product tiers while Asian exporters face portfolio rationalization.
Subscription-based aligner replenishment contracts are replacing per-case purchasing at multi-location dental service organizations. DSO procurement offices negotiate enterprise pricing tied to volume commitments and exclusive digital platform adoption. This concentration is most advanced in Texas and Florida practice roll-ups.
Orthodontic Supplies Market Segmentation
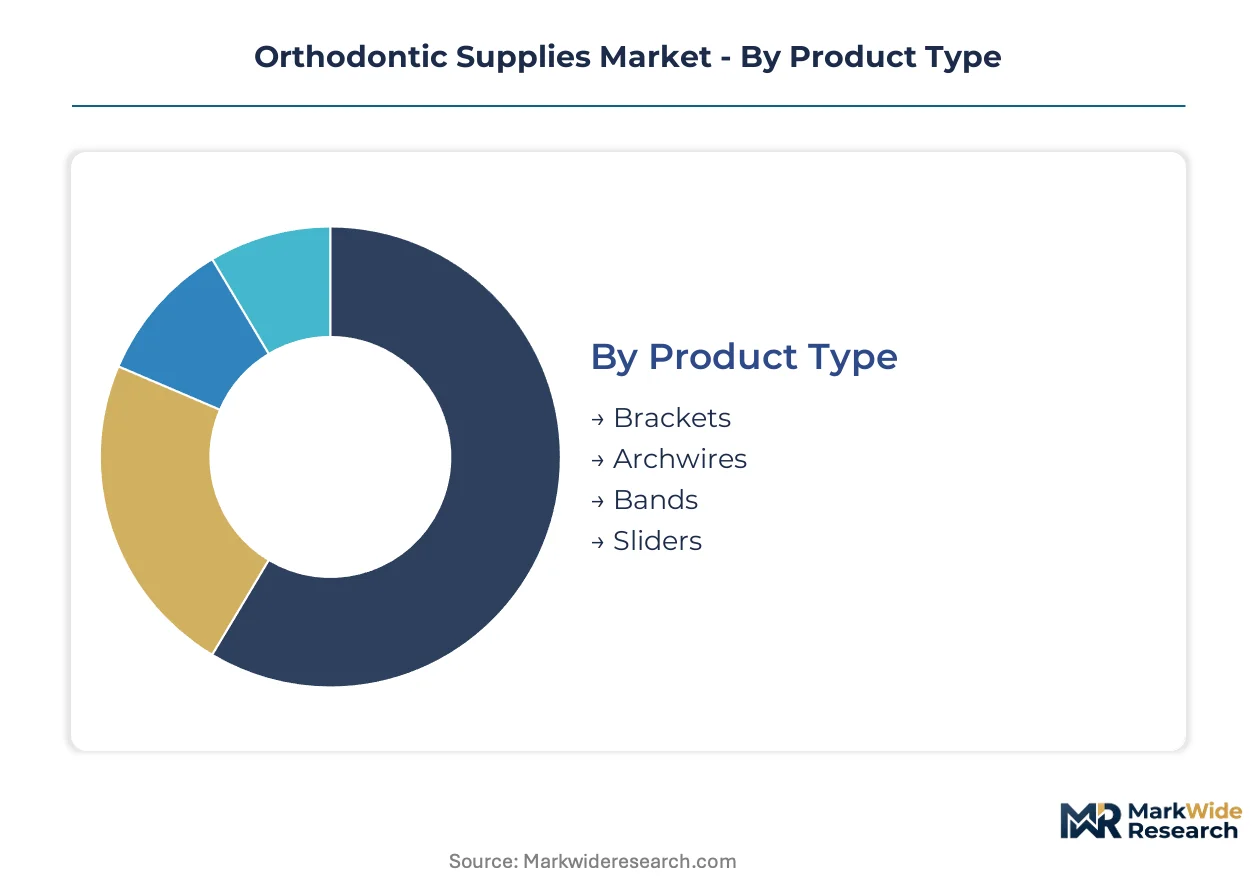
Orthodontic supply segmentation reveals divergent capital requirements across hardware fabrication, digital infrastructure, and material processing. Manufacturers must align production investments with the specific torque specifications, biocompatibility standards, and regulatory pathways governing each product category.
Product Type:
Capital intensity varies sharply across this category, with precision-machined components demanding specialized milling equipment while consumable attachments require lower fixed-asset thresholds.
- Brackets:Fabricated from stainless steel or ceramic substrates through metal injection molding or precision milling to achieve exact slot dimensions for archwire engagement. Demand concentrates in China's tier-one cities where digital orthodontic workflows are replacing conventional bracket systems, though metal variants retain volume dominance in price-sensitive markets.
- Archwires:Superelastic nickel-titanium alloys undergo specialized thermal processing to establish precise force-deflection curves for controlled tooth movement. Procurement offices at multi-location dental service organizations in Texas and Florida negotiate enterprise pricing tied to volume commitments for nickel-titanium and beta-titanium variants.
- Bands:Pre-formed stainless steel rings cemented to molars for anchorage and appliance attachment, produced through stamping and welding operations with moderate tooling investment.
- Sliders:Low-friction polymer or ceramic inserts enabling bracket-archwire interaction, manufactured via injection molding with rapid cycle times and minimal capital barriers.
Brackets absorb the bulk of installed capacity; archwires are expanding most quickly amid nickel-titanium alloy innovation and force-system customization.
End User:
Customer type determines purchasing cadence, with institutional buyers consolidating procurement through distributor networks while independent practitioners favor direct manufacturer relationships.
- Orthodontists:Specialists commanding premium case fees who specify torque prescriptions and force systems, driving demand for customized bracket prescriptions and premium archwire alloys. These practitioners in suburban United States markets adopt chairside scanners at replacement cycles under four years, collapsing physical mold shipping logistics.
- Dental Clinics:General practitioner settings expanding orthodontic service lines through aligner platform adoption, particularly across Asia-Pacific where clear aligner technology reduces chair time requirements. FDA 510(k) clearance pathways govern biocompatibility standards for appliances sold to these clinics in the United States.
- Hospitals:Academic and tertiary centers managing complex craniofacial anomalies, sourcing specialized anchorage devices and surgical orthodontic hardware through centralized supply chains.
- Laboratories:Independent and manufacturer-captive facilities producing custom appliances from digital impressions, absorbing capital investment in 3D printing and milling equipment.
Orthodontists command the highest per-case spend; dental clinics are gaining share fastest as aligner platforms democratize treatment delivery.
Technology:
Technology selection separates capital-heavy digital infrastructure from established mechanical methods, with platform investments creating switching costs that lock clinics into recurring supply relationships.
- 3D Printing:Additive manufacturing of aligner models, surgical guides, and indirect bonding trays using photopolymer resins and selective laser sintering systems. EU MDR conformity assessments govern biocompatibility and mechanical performance standards for polymer-based appliances sold in Europe.
- Digital Scanning:Intraoral capture hardware decentralizing impression workflows from centralized dental labs to individual clinic operatories, with Straumann Group and Align Technology Inc. competing on proprietary ecosystem lock-in.
- Aligners:Thermoformed polymer appliances produced from 3D-printed models, representing the fastest-expanding margin segment through subscription-based replenishment contracts.
- Traditional Methods:Physical impression materials, laboratory wax-ups, and manual appliance fabrication requiring minimal digital capital but facing margin compression.
Traditional methods retain the largest installed base; aligners are climbing the fastest as 3D printing and intraoral scanning compress treatment planning cycles.
Material:
Material tier dictates pricing architecture and regulatory testing burden, with premium substrates requiring extended cytotoxicity datasets while commodity inputs compete on scale.
- Metal:Stainless steel and nickel-titanium alloys dominating bracket and archwire production, subject to nickel ion release testing under EU MDR technical documentation requirements.
- Ceramic:Polycrystalline alumina and zirconia compounds commanding premium positioning for adult aesthetic cases in professional demographics.
- Plastic:PETG and multilayer polymer films serving entry-level clear appliance tiers with lower biocompatibility testing thresholds.
- Composite:Fiber-reinforced polymers and hybrid materials bridging mechanical performance and aesthetic demands in specialized applications.
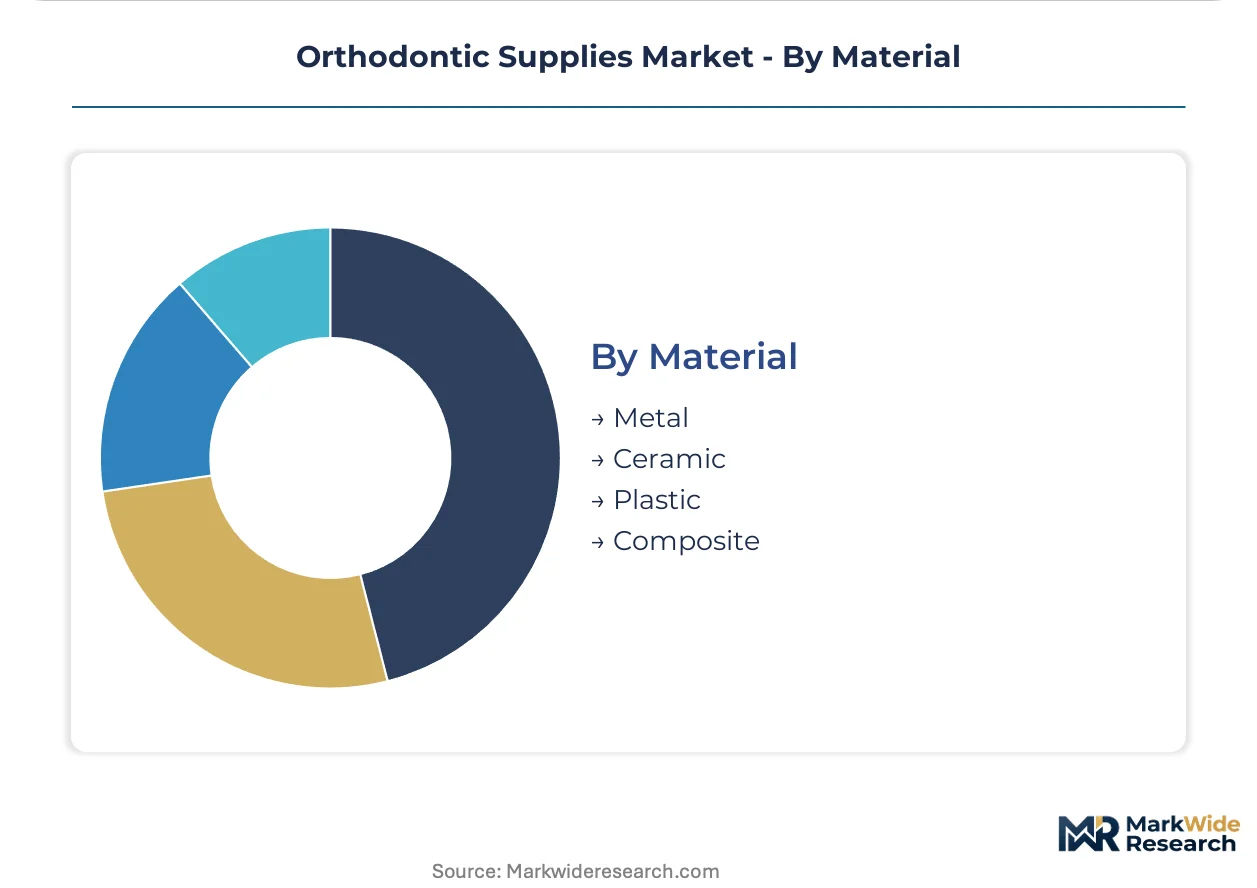
Metal commands the greatest production volume; ceramic is gaining share fastest among adult patient segments prioritizing aesthetic outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel mining districts supply the nickel-titanium alloys feeding archwire production across three continents. Raw material proximity shapes manufacturing investment and regulatory compliance strategies in major consumption markets.
United States
Suburban dental service organizations in Texas and Florida drive aligner platform consolidation through enterprise procurement contracts. FDA 510(k) clearance pathways govern biocompatibility standards for polymer-based appliances entering multi-location clinic networks. General practitioner dentists in these Sun Belt metros adopt chairside scanners at replacement cycles under four years, collapsing physical mold shipping logistics.
Germany
Precision machining heritage supports premium bracket and archwire fabrication serving adjacent European markets. EU MDR technical documentation requirements elevate clinical evidence thresholds for nickel-titanium biocompatibility claims, forcing extended cytotoxicity testing. Industrial clusters in Baden-Württemberg absorb these compliance costs into premium product tiers while maintaining export competitiveness.
China
Tier-one cities Beijing, Shanghai, and Shenzhen concentrate digital orthodontic workflow adoption as conventional bracket systems face displacement. NMPA enforces GB standards requiring separate clinical dossiers for imported materials, extending approval timelines versus Western pathways. Domestic manufacturers in the Yangtze River Delta exploit regulatory familiarity to capture share in aesthetic ceramic and transparent appliance segments.
Japan
Aging patient demographics broaden reimbursement-covered indications for adult malocclusion correction beyond traditional adolescent brackets. PMDA reimbursement shifts enable premium ceramic and aligner system uptake among professional demographics in Tokyo and Osaka. Kanto region clinics integrate remote monitoring capabilities to reduce visit frequency for time-constrained patients.
India
CDSCO streamlined medical device rules open distribution expansion beyond Mumbai and Delhi clusters into underpenetrated tier-2 cities. Price-sensitive demand favors metal bracket volumes while entry-level aligner platforms gain traction among urban professionals. Gujarat and Karnataka manufacturing zones emerge as regional production hubs serving Southeast Asian export markets.
Orthodontic Supplies Market Vendor Landscape
Global majors compete with regional champions across digital platform integration and raw material supply security. Market structure shows moderate consolidation around vertically integrated implant-to-consumable portfolios, with mid-tier specialists competing on regulatory agility and distributor breadth. Three archetypes dominate: diversified dental conglomerates with captive manufacturing, pure-play aligner platform operators with software lock-in, and regional metal-component fabricators serving price-sensitive brackets. Competitive moves center on backward integration into nickel-titanium supply and strategic partnerships with dental service organization procurement offices.
Within the diversified conglomerate tier, 3M Company and Dentsply Sirona Inc. exemplify scale-driven manufacturing breadth across metal and ceramic bracket lines. Align Technology Inc. occupies a distinct position as a platform-native operator with proprietary digital scanning ecosystems that anchor recurring aligner shipments. Straumann Group represents the implant-to-consumable integration archetype through captive production of premium orthodontic hardware. These three patterns illustrate how competitive positioning diverges between manufacturing scale, software ecosystem control, and vertical portfolio depth.
| Leading Market Players |
|---|
| 3M Company |
| Ormco Corporation |
| Align Technology Inc. |
| Straumann Group |
| American Orthodontics |
| Dentsply Sirona Inc. |
| Henry Schein Inc. |
| TP Orthodontics Inc. |
| Envista Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-location dental service organizations in Texas and Florida anchor procurement volume and negotiate subscription-based aligner contracts that compress per-unit margins while locking in recurring revenue streams for platform operators.
Pricing Analysis
Warranty and service bundling separates premium orthodontic tiers, with EU MDR-certified archwire systems including extended biocompatibility documentation against unbundled commodity metal brackets. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status, customization depth, and after-sales technical support. Pricing pressure stems from nickel-titanium raw material volatility and DSO enterprise bargaining power. Independent orthodontists in suburban United States markets show highest price sensitivity, while academic hospital systems absorb premium positioning for complex craniofacial hardware.
Supply Chain Analysis
China's GB standards and domestic-content preferences for NMPA-registered materials are redirecting sourcing toward Yangtze River Delta manufacturers. Nickel-titanium alloy feedstock draws from Indonesian mining districts, ceramic substrates from German industrial clusters, and polymer resins from South Korean petrochemical plants. Single-source vulnerability concentrates in Southeast Asian nickel concentrate supply. Distribution runs through manufacturer-captive digital platforms and traditional dental distributor networks serving independent clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessments function as a cost-of-compliance moat, elevating clinical evidence thresholds that filter out undercapitalized competitors and protect positions of certified European suppliers.
For Market Incumbents: Hedge against nickel-titanium price volatility through backward integration into alloy supply or long-term offtake agreements with Indonesian concentrate producers. Reinforce software ecosystem lock-in by deepening API connectivity with practice management systems, defending against emerging cloud-native aligner platforms that threaten distributor relationships.
For New Entrants and Emerging Players: Tier-2 cities in India represent the most penetrable buyer archetype, with CDSCO streamlined rules enabling distribution expansion beyond saturated Mumbai-Delhi corridors. Target price-sensitive metal bracket demand while building toward aligner platform credibility. Pursue white-label manufacturing partnerships with Gujarat-based producers to achieve cost parity against established brands.
For Investors and Strategic Acquirers: The window for entry favors regional champions with regulatory agility and captive production assets. Long-term viability hinges on vertical portfolio depth spanning implant hardware through consumables. Monitor PMDA reimbursement shifts in Japan as the signal indicating adult orthodontic market maturation and platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended cytotoxicity datasets satisfy EMA biocompatibility thresholds for nickel-titanium archwire claims. |
| Digital Platform Ecosystem Integration | API connectivity with cloud-based treatment planning software locks clinics into recurring aligner shipments. |
| Backward Integration into Nickel-Titanium Supply | Captive alloy production insulates margin compression from Indonesian concentrate price volatility. |
| DSO Enterprise Procurement Partnership | Volume commitments from Texas and Florida practice roll-ups secure predictable replenishment revenue. |
| Remote Monitoring Capability Development | Smartphone-based progress tracking reduces clinic visit frequency for Japan's aging patient demographics. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR technical documentation repositories formed the secondary backbone, supplemented by customs records tracking nickel-titanium alloy trade flows. Primary interviews with orthodontic supply procurement managers, GPO contracts administrators, biomedical engineers at academic medical centers, and regulatory affairs leads at polymer manufacturers validated demand assumptions. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation anchored segmentation splits across the analysis window.
Historical trendline analysis of bracket, archwire, and aligner shipment volumes established baseline growth patterns across product type, end user, technology, material, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to segment-specific adoption rates, with inputs including intraoral scanner replacement cycles, DSO practice roll-up velocity, and NMPA approval timeline differentials.
Revisions become necessary when nickel-titanium supply disruptions, EU MDR auditor scarcity delays, or PMDA reimbursement reversals materialize beyond modeled assumptions. Forecasts reflect documented expectations regarding digital workflow penetration and raw material price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Dental Consumables Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Endodontic Supplies Market