
 Asia-Pacific Digital Pathology Market | 2026-2036
Asia-Pacific Digital Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Pathology Market Analytics
Subscription-based leasing for whole slide imaging hardware is fragmenting competitive entry barriers across the Asia-Pacific Digital Pathology Market. Hamamatsu Photonics K.K. leverages its native Japanese manufacturing base to sustain premium scanner supply chains across East Asia. F. Hoffmann-La Roche Ltd. (Ventana) anchors its position through deep integration of staining workflows with digital readout systems. Danaher Corporation (Leica Biosystems) competes by extending its histology equipment installed base into downstream digital platforms.
Asia-Pacific digital pathology encompasses the digitization of glass histopathology slides into high-resolution whole slide images coupled with computational analysis, storage, and remote transmission infrastructure. Whole slide imaging systems typically capture tissue specimens at 20x or 40x optical magnification, producing multi-gigabyte image files that enable pathologist review without physical slide handling. Cloud-based solutions within the deployment segment are capturing disproportionate growth momentum as healthcare networks across the region prioritize capital expenditure reduction and multi-site accessibility. The end user landscape tilts toward diagnostic laboratories where high case volumes justify automation investments and where hybrid on-premises and cloud architectures address data sovereignty requirements.
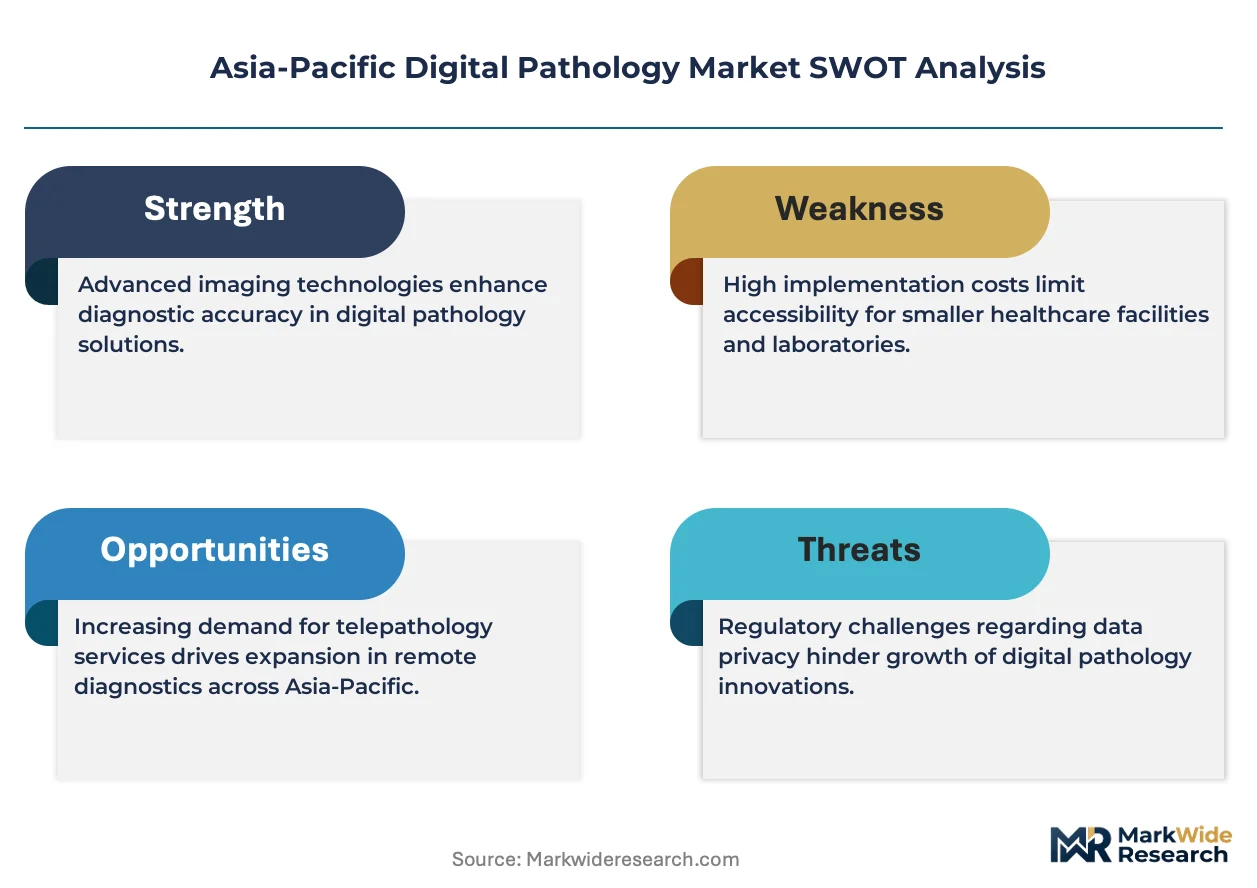
Japan's PMDA software-as-medical-device framework and Australia's TGA digital health regulations are shaping product registration pathways and clinical validation requirements for AI-assisted diagnostic tools entering the Asia-Pacific market. China's NMPA medical device classification rules for AI diagnostic software create additional compliance layers that influence development prioritization and commercial launch sequencing. Stakeholders must monitor how divergent national approval timelines for algorithm-based pathology tools reshape competitive positioning and partnership structures across the region.
Market Dynamics
Cloud-native pathology platforms are compressing capital deployment cycles across hospital networks, enabling multi-site diagnostic networks without on-premises infrastructure investments. This infrastructure shift is redistributing competitive advantage from hardware manufacturers toward software-integrated service providers.
Growth Catalysts
- Japan's PMDA SaMD framework:The software-as-medical-device classification pathway accelerates regulatory clearance for AI diagnostic algorithms, reducing time-to-market for algorithm developers targeting East Asian healthcare systems.
- Telepathology networks:Academic medical centers in China are deploying remote consultation infrastructure to connect tier-3 hospitals with specialist pathologists in Beijing and Shanghai, extending diagnostic capacity to underserved regions.
- Whole slide imaging standardization:The DICOM-WSI format is enabling interoperability between scanner hardware and viewing software, reducing vendor lock-in and facilitating multi-vendor procurement strategies.
Market Restraints
- Storage cost volatility:Multi-gigabyte image files generated at 40x magnification impose escalating cloud storage expenditures that strain diagnostic laboratory operating budgets.
- Optical component concentration:Precision lens assemblies and CMOS sensors for high-resolution scanning concentrate among Japanese and German component suppliers, creating supply vulnerability.
- China's NMPA AI classification rules:The three-tier medical device framework for diagnostic software imposes extended clinical validation requirements that delay commercialization timelines.
Strategic Opportunities
- India's tier-2 hospital clusters:Cloud-based pathology workflows address acute specialist shortages in secondary cities where pathologist-to-population ratios remain critically low.
- AI-staining integration:Convergence of computational pathology with automated immunohistochemistry staining creates closed-loop diagnostic systems that compress turnaround times.
- Australia's TGA digital health reimbursement:The national funding framework for telepathology services creates sustainable revenue models for remote diagnostic platforms.
Industry Challenges
- Computational pathology expertise gap:The intersection of histopathology and machine learning requires hybrid skill sets that remain scarce across Asia-Pacific healthcare systems.
- Legacy LIS integration complexity:Hospital information systems built on decades-old architectures resist seamless connectivity with modern digital pathology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Pathology Market |
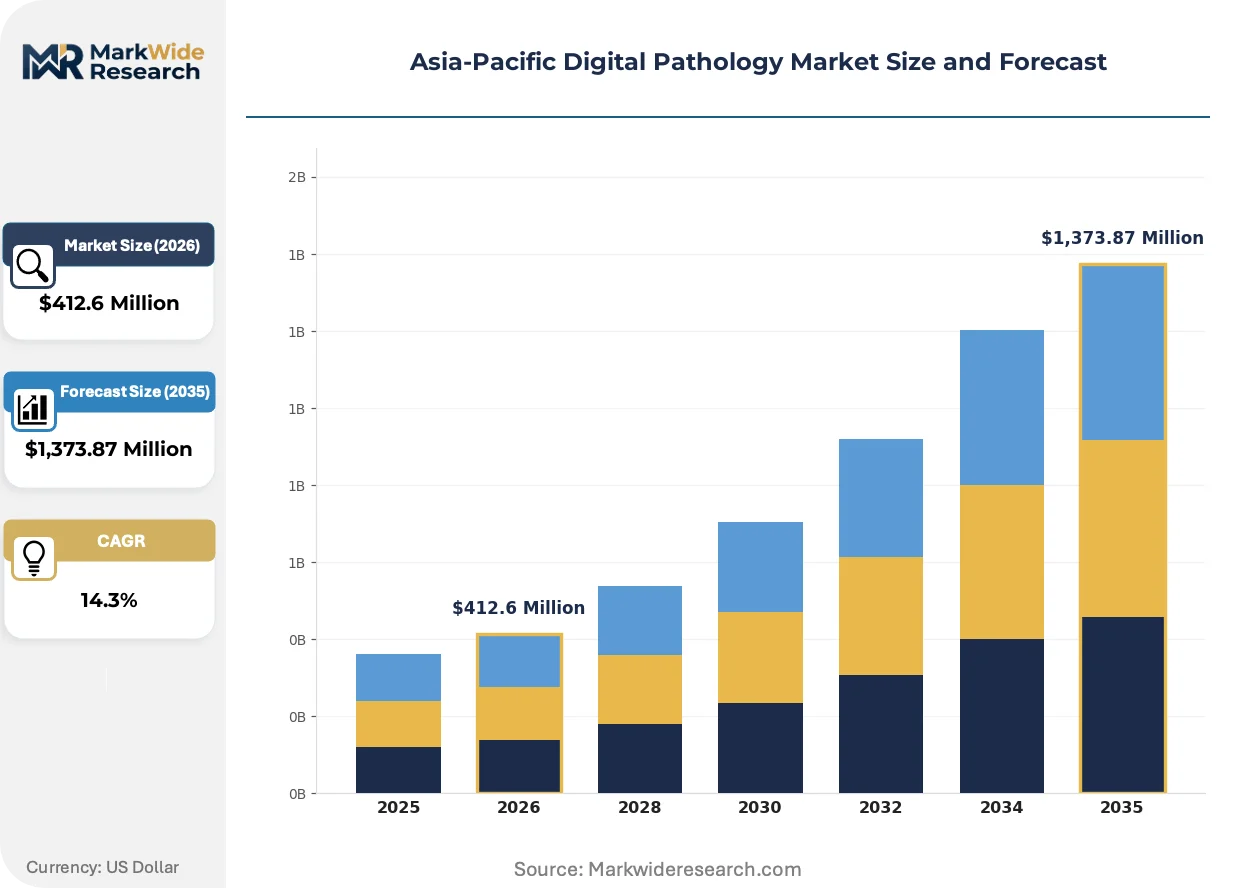
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,373.87 Million |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Whole Slide Imaging, Image Analysis Software, Telepathology, Digital Slide Scanners Application: Medical Diagnosis, Drug Discovery, Education, Research End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Pharmaceutical Companies Deployment: On-Premises, Cloud-Based Solutions, Hybrid Solutions, Others |
| Companies Covered | Hamamatsu Photonics K.K., Akoya Biosciences, F. Hoffmann-La Roche Ltd. (Ventana), Aether AI, Qritive, Koninklijke Philips N.V., Nikon Corporation, Indica Labs Inc., Danaher Corporation (Leica Biosystems), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Pathology Market Evolving Landscape
Computational analysis tools are migrating from research environments into clinical workflows, compressing the gap between image acquisition and diagnostic output. This transition is redefining value capture across the diagnostic value chain.
Multiplexed fluorescence imaging systems are digitizing spatial biology applications by capturing multiple biomarker expressions from single tissue sections. Oncology pathology departments in South Korea and Australia are adopting these platforms for immuno-oncology profiling. The technology is digitizing complex biomarker quantification that previously required serial sectioning and manual scoring.
Japan's PMDA software-as-medical-device guidelines are establishing precedent for AI algorithm validation requirements across the Asia-Pacific region. The framework mandates clinical performance testing against reference standards, elevating development costs but reducing post-market safety risks. Diagnostic software developers are responding by prioritizing Japan-first regulatory strategies to leverage mutual recognition pathways.
Subscription-based hardware leasing is displacing capital purchase models for whole slide scanners across hospital procurement departments. Diagnostic laboratories in India and Southeast Asia favor operational expenditure structures that align costs with case volume fluctuations. This shift is most visible among mid-sized private hospital chains seeking to minimize upfront technology investments.
Asia-Pacific Digital Pathology Market Segmentation
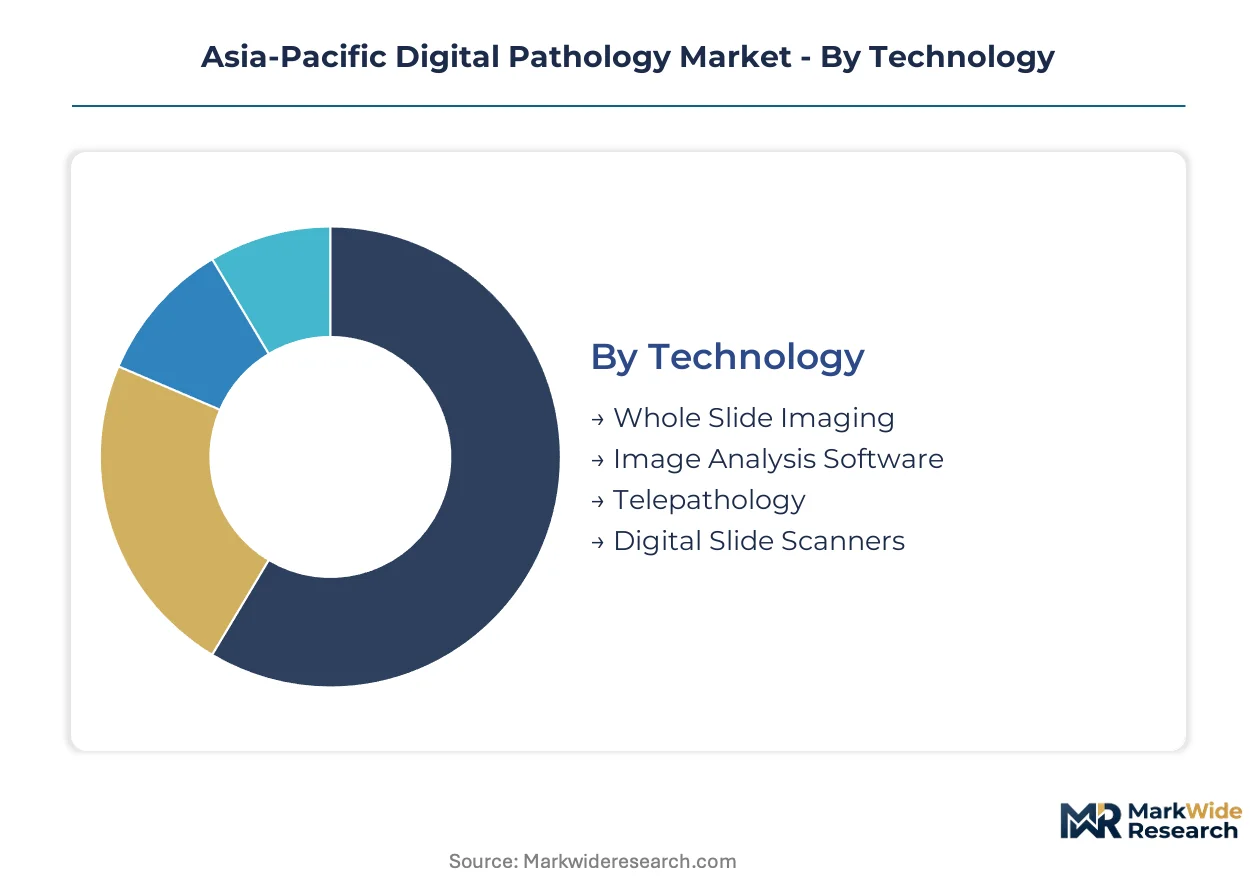
Segmentation across the Asia-Pacific Digital Pathology Market reveals how technology maturity, regulatory readiness, and infrastructure investment patterns fragment demand. Each dimension captures distinct procurement behaviors between established healthcare systems and emerging networks.
Technology:
Mature hardware platforms coexist with emerging computational layers across the technology spectrum.
- Whole Slide Imaging:High-resolution scanning systems capture tissue specimens at 20x or 40x optical magnification, producing multi-gigabyte image files. Demand concentrates in Japan's university hospitals where PMDA-cleared platforms anchor diagnostic workflows.
- Image Analysis Software:Computational algorithms enable quantitative biomarker assessment and pattern recognition on digitized slides. China's NMPA AI classification rules are accelerating clinical validation investments for algorithm developers targeting tertiary hospitals in Beijing and Shanghai.
- Telepathology:Real-time transmission infrastructure connects remote sites with specialist pathologists.
- Digital Slide Scanners:Hardware platforms convert glass slides into viewable digital formats.
Whole Slide Imaging handles the majority of throughput; Image Analysis Software is expanding most quickly on share.
Application:
Clinical utility drives premium pricing while research applications scale through volume licensing.
- Medical Diagnosis:Primary diagnostic workflows for cancer detection and disease classification. India's tier-1 hospital clusters deploy cloud-based pathology to address specialist shortages in oncology departments.
- Drug Discovery:High-throughput screening and biomarker validation for pharmaceutical development. Contract research organizations in South Korea leverage multiplexed fluorescence imaging for immuno-oncology profiling.
- Education:Training platforms for pathology residents and continuing medical education.
- Research:Academic investigations into disease mechanisms and therapeutic targets.
Medical Diagnosis commands the highest per-site revenue; Drug Discovery is climbing the fastest on investment intensity.
End User:
Capital availability and case volume determine deployment sophistication across customer types.
- Hospitals:Integrated health systems requiring enterprise-wide pathology digitization. Australia's TGA digital health reimbursement creates sustainable funding for telepathology services in public hospital networks.
- Diagnostic Laboratories:High-throughput reference labs processing thousands of cases daily. Subscription-based leasing models align costs with fluctuating case volumes across Southeast Asian private chains.
- Academic Institutions:Medical schools and research universities training next-generation pathologists.
- Pharmaceutical Companies:Drug developers integrating pathology into clinical trial workflows.
Diagnostic Laboratories process the highest case volumes; Hospitals are gaining share fastest on platform consolidation.
Deployment:
Data sovereignty requirements and infrastructure maturity shape architecture preferences.
- On-Premises:Local server installations maintaining physical control over patient data. China's data localization mandates steer government hospital procurement toward domestic server infrastructure.
- Cloud-Based Solutions:Scalable storage and compute without capital infrastructure investment. India's tier-2 cities adopt these platforms to circumvent specialist shortages without on-premises IT staffing.
- Hybrid Solutions:Mixed architectures balancing local processing with cloud storage.
- Others:Edge computing and containerized deployment models for specialized use cases.
On-Premises retains the largest installed base; Cloud-Based Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's software-as-medical-device framework and NMPA's AI classification rules are diverging regulatory pathways across the region. National data localization mandates and telepathology reimbursement policies are reshaping procurement priorities in key markets.
China
Academic medical centers in Beijing and Shanghai are deploying remote consultation networks to connect tier-3 hospitals with specialist pathologists. NMPA's three-tier medical device framework for diagnostic software imposes extended clinical validation requirements that delay commercialization timelines. The Yangtze River Delta region concentrates cloud-based pathology adoption where hybrid architectures address data sovereignty requirements.
Japan
University hospitals anchor diagnostic workflows around PMDA-cleared whole slide imaging platforms. METI's digital health initiatives align with PMDA guidelines to accelerate regulatory clarity for AI-powered diagnostic tools. The Kanto region sustains premium scanner supply chains through native manufacturing bases serving East Asian markets.
India
Tier-1 hospital clusters deploy cloud-based pathology workflows to address acute specialist shortages in oncology departments. The country's national pharmaceutical regulator maintains device classification pathways that influence import and local manufacturing decisions. Maharashtra and Karnataka host mid-sized private hospital chains favoring subscription-based leasing models to minimize upfront technology investments.
Australia
Public hospital networks leverage TGA digital health reimbursement to fund sustainable telepathology services. TGA regulations shape product registration pathways and clinical validation requirements for AI-assisted diagnostic tools. New South Wales and Victoria concentrate diagnostic laboratory infrastructure where high case volumes justify automation investments.
South Korea
Contract research organizations leverage multiplexed fluorescence imaging for immuno-oncology profiling in drug discovery applications. MFDS medical device regulations govern software validation requirements for algorithm-based pathology platforms. The Seoul Capital Area anchors pharmaceutical development activity driving high-throughput screening demand.
Asia-Pacific Digital Pathology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and integrated service layers. The vendor base separates into three tiers: precision optics manufacturers, staining workflow integrators, and cloud-native platform developers. Consolidation pressure concentrates among scanner hardware suppliers while software layers fragment. Dominant competitive moves include strategic partnerships between imaging hardware vendors and AI algorithm developers, plus geographic expansion through localized regulatory approval strategies.
Among precision optics specialists, Hamamatsu Photonics K.K. and Nikon Corporation exemplify the hardware-centric archetype with manufacturing positions in East Asia. Danaher Corporation (Leica Biosystems) represents the histology-to-digital extension strategy, leveraging installed base relationships into downstream platform adoption. F. Hoffmann-La Roche Ltd. (Ventana) occupies a position exemplifying deep staining-to-readout integration. These three anchors illustrate divergent pathways for value capture across the diagnostic chain.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Akoya Biosciences |
| F. Hoffmann-La Roche Ltd. (Ventana) |
| Aether AI |
| Qritive |
| Koninklijke Philips N.V. |
| Nikon Corporation |
| Indica Labs Inc. |
| Danaher Corporation (Leica Biosystems) |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese precision optics manufacturers concentrates pricing power upstream while compressing margins for downstream platform integrators across both premium certified tiers and emerging economy segments. Tariff exposure between China and key component source countries amplifies cost volatility, forcing procurement departments to restructure supplier relationships around geographic diversification.
Pricing Analysis
Certification level (PMDA-cleared versus NMPA-registered versus non-regulated research-grade) creates the primary spread between premium and standard pricing tiers. Subscription-based SaaS models dominate software layers while hardware procurement favors operational expenditure structures. Pricing pressure intensifies in the mid-market scanner segment as Chinese domestic manufacturers expand production capacity. Diagnostic laboratories in Southeast Asia exhibit highest price sensitivity; university hospitals in Japan demonstrate lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk calculations for precision lens assemblies and CMOS sensor procurement. Manufacturing concentrates in Japan, Germany, and South Korea for optical components while final assembly clusters in China and Southeast Asia. Critical dependencies include specialized glass substrates, high-resolution imaging sensors, and precision motion control systems. Distribution runs through authorized medical device distributors with regulatory clearance capabilities rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in digital pathology are crossing an inflection where DICOM-WSI interoperability standards enable multi-vendor ecosystems, collapsing proprietary lock-in premiums and redistributing value toward algorithm-integrated service layers.
For Market Incumbents: Build regulatory data moats through PMDA-first clearance strategies that leverage mutual recognition pathways into adjacent Asia-Pacific markets. Incumbents should deepen backward integration into precision optics manufacturing to offset Japanese supplier concentration risk while accelerating AI-staining workflow integration to defend against cloud-native platform entrants. Channel control through histology equipment installed base relationships remains the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 hospital clusters where cloud-based pathology workflows address acute specialist shortages without requiring capital-intensive on-premises infrastructure. The most penetrable segment combines subscription-based scanner leasing with AI-assisted diagnostic software targeting oncology departments in secondary cities. A regulatory-cooperative go-to-market angle partnering with established distributors for NMPA navigation accelerates market access. For Investors and Strategic Acquirers: PMDA's software-as-medical-device framework reshapes the acquisition landscape by elevating clinical validation capabilities as the scarce asset class. Long-term viability centers on platforms with demonstrated algorithm performance against reference standards and established reimbursement pathways. Target acquisition archetypes include computational pathology specialists with regulatory-cleared products in Japan or Australia. The signal to watch is NMPA clearance velocity for AI diagnostic software as an indicator of scalable China market access.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates regulatory clearance for AI diagnostic algorithms across East Asian healthcare systems. |
| Cloud-Native Platform Integration | Enables multi-site diagnostic networks without capital infrastructure investment in tier-2 cities. |
| AI-Staining Workflow Partnership | Creates closed-loop diagnostic systems that compress turnaround times in high-throughput laboratories. |
| Subscription-Based Hardware Leasing | Aligns scanner costs with case volume fluctuations across Southeast Asian private hospital chains. |
| Telepathology Reimbursement Strategy | Secures sustainable funding models for remote diagnostic platforms in Australia's public hospital networks. |
Research Methodology
Desk research of regulatory filings, hospital procurement databases, and medical device registration records preceded structured interviews with pathology department heads, biomedical engineers, GPO contracts managers, and diagnostic laboratory directors. Primary fieldwork across China, Japan, India, Australia, and South Korea validated secondary estimates. Bottom-up case volume modeling triangulated against top-down healthcare expenditure projections.
Assumptions held fixed include PMDA and NMPA regulatory pathway timelines, cloud infrastructure cost trajectories, and pathologist workforce growth rates; variables stress-tested included AI algorithm validation success rates, data localization policy stringency, and optical component supply disruptions. Segmentation dimensions modeled encompassed technology layer, deployment architecture, end-user type, and application purpose. CAGRs derived from logistic diffusion curves fitted to adoption data across the projection horizon. Industry-specific inputs included DICOM-WSI interoperability penetration and telepathology reimbursement policy evolution.
Stress conditions across regulatory approval delays, cloud storage cost volatility, and specialist workforce shortages were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from algorithm performance breakthroughs, reimbursement policy shifts, or supply chain reconfigurations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Radiology Services Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
United States Mammography Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market