
 Spain Magnetic Resonance Imaging Market | 2026-2036
Spain Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Magnetic Resonance Imaging Market Analytics
Aftermarket service revenue is rewriting profitability expectations for installed-base vendors. Siemens Healthineers leverages its extensive service footprint across Spanish hospital networks to capture recurring maintenance contracts. GE Healthcare anchors its position through predictive service platforms that minimize scanner downtime. Koninklijke Philips NV competes by embedding AI-assisted workflow tools into service agreements, raising switching costs for imaging departments.
Magnetic resonance imaging employs superconducting magnets generating field strengths from 1.5 to 3.0 Tesla to produce high-resolution tomographic images of soft tissues without ionizing radiation. The technology serves diagnostic radiology, intraoperative guidance, and research applications requiring differentiation between healthy and pathological tissue states. Closed MRI systems dominate hospital procurement budgets due to superior signal-to-noise ratios, while open architectures capture pediatric and claustrophobic patient segments where comfort design commands premium positioning. Superconducting technology leads technology segmentation with established helium supply chains, though permanent magnet alternatives gain traction in decentralized clinic settings seeking lower operational complexity.
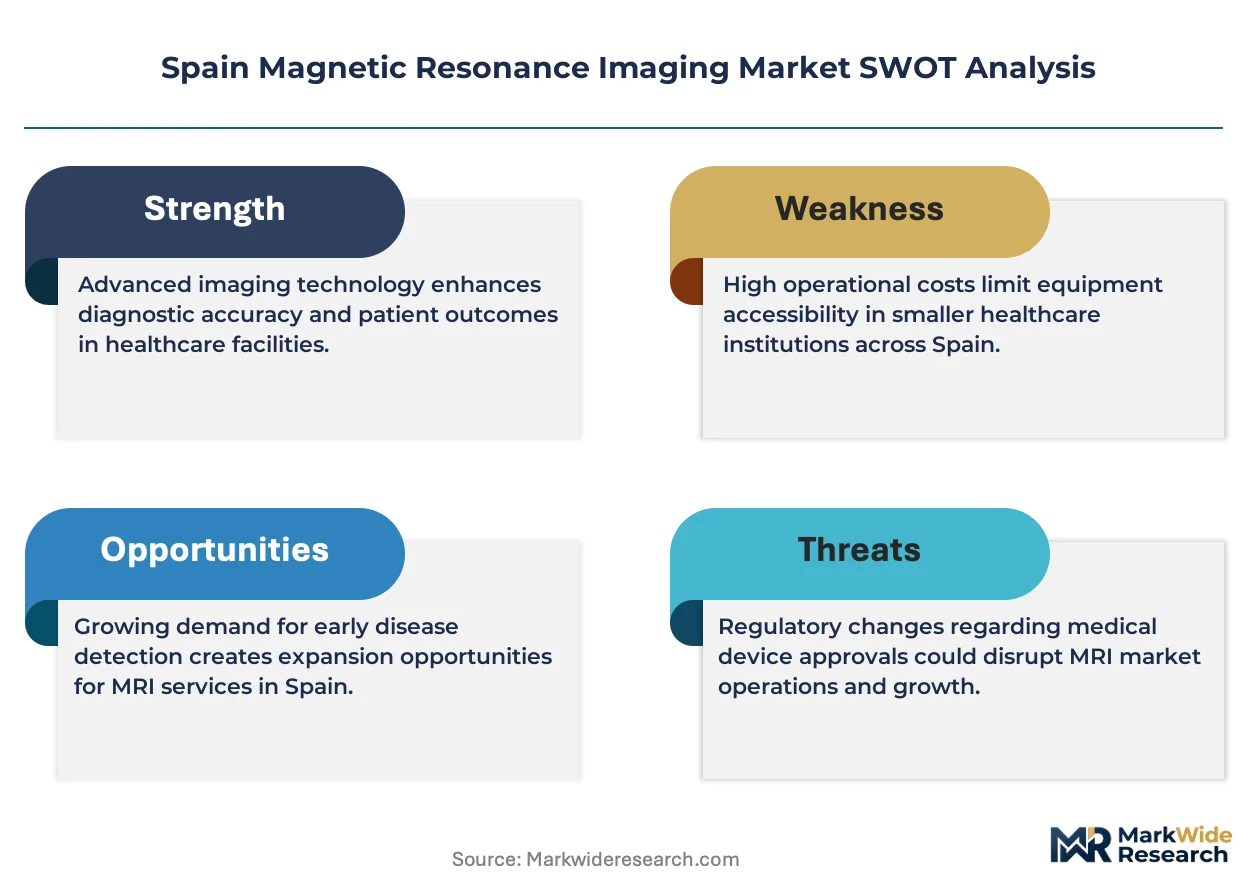
Spain's national pharmaceutical and medical device regulator, AEMPS, enforces EU MDR conformity assessment requirements that extend approval timelines for new MRI system introductions. BIS-equivalent Spanish standards bodies coordinate with ECHA on restricted substance rules affecting magnet manufacturing materials. The EU AI Act's risk classification framework for diagnostic algorithms will reshape software-enabled MRI analytics procurement criteria. Stakeholders must monitor regional health authority tender specifications evolving toward outcome-based equipment leasing models.
Market Dynamics
EU MDR compliance deadlines are compressing replacement cycles across Spanish hospital networks, forcing capital allocation toward closed-system high-field scanners while helium supply constraints reshape superconducting magnet economics.
Growth Catalysts
- EU MDR Conformity Timelines:AEMPS enforcement of Medical Device Regulation assessment protocols is accelerating scanner replacements in tertiary networks across Catalonia and Madrid.
- Helium Recovery Infrastructure:Closed-loop cryogenic systems are extending superconducting magnet operational life, reducing lifecycle costs for hospital procurement committees.
- Public-Private Partnership Models:Imaging service contracts in Barcelona and Madrid metropolitan clusters are expanding access to 3.0 Tesla diagnostics without full capital ownership.
Market Restraints
- Helium Price Volatility:Global helium supply concentration in Qatar and the United States creates input cost unpredictability for superconducting system operators.
- AEMPS Approval Friction:Extended conformity assessment timelines under EU MDR delay new system introductions by 12-18 months versus previous directives.
- Permanent Magnet Substitution:Low-field open architectures using ferrite or rare-earth permanent magnets are capturing decentralized clinic segments seeking operational simplicity.
Strategic Opportunities
- Andalusian Network Expansion:Underpenetrated tertiary capacity in Seville and Málaga provinces offers whitespace for high-field system deployment.
- AI-Assisted Workflow Convergence:Integration of diagnostic algorithms with MRI analytics is creating premium service tier differentiation for radiology departments.
- Outcome-Based Equipment Leasing:Regional health authority tender specifications are pivoting toward utilization-guaranteed contracts rather than capital purchase models.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized magnet maintenance expertise is concentrating among legacy vendor service teams, constraining independent servicing options.
- Legacy System Integration Complexity:PACS and RIS interoperability requirements are extending deployment timelines for new scanner installations in established hospital IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Magnetic Resonance Imaging Market |
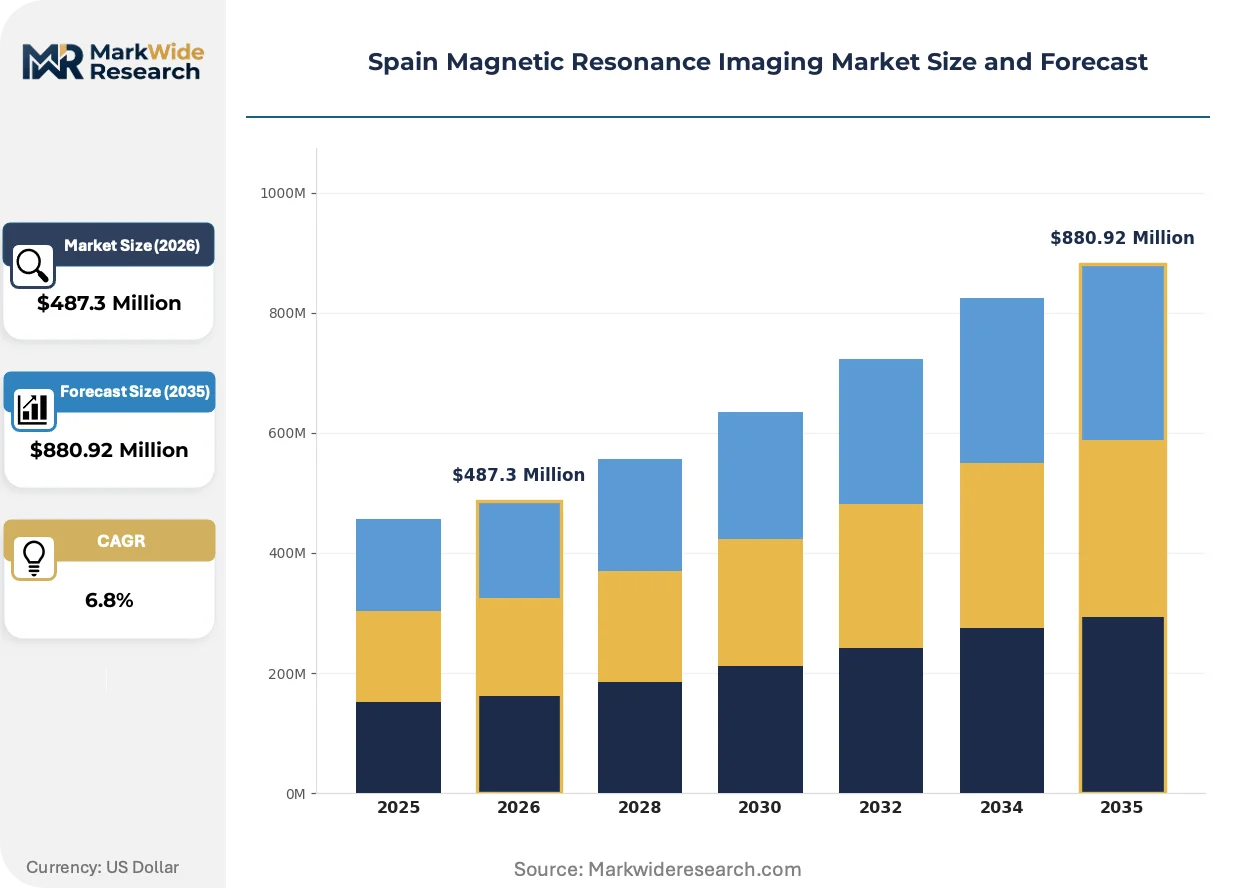
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Technology: Superconducting MRI, Permanent Magnet MRI, Optical MRI, Hybrid MRI End User: Hospitals, Imaging Centers, Research Institutes, Clinics Application: Neurological Imaging, Cardiovascular Imaging, Oncology Imaging, Musculoskeletal Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Bruker, Esaote SpA, Aurora Imaging Technology, Hitachi Medical Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Magnetic Resonance Imaging Market Evolving Landscape
Workflow automation and regulatory digitization are restructuring how Spanish radiology departments evaluate scanner acquisitions, with software-enabled service contracts displacing traditional hardware-centric procurement.
Compressed sensing reconstruction algorithms are digitizing raw k-space data acquisition protocols, reducing scan times by 40-50% for musculoskeletal and neurological protocols. Tertiary hospitals in Madrid and Barcelona are adopting these sequences to increase daily patient throughput without magnet saturation. The technology is digitizing radiology department scheduling economics, converting fixed scanner capacity into variable revenue streams.
EU AI Act risk classification frameworks are redefining software-as-medical-device boundaries for diagnostic algorithms embedded in MRI workstations. AEMPS is coordinating with notified bodies to establish conformity assessment pathways for machine learning-enabled image reconstruction tools. High-throughput oncology imaging centers face the steepest compliance burden as Class IIa and IIb algorithm deployments require updated quality management systems.
After-sales service unbundling is fragmenting traditional vendor-captive maintenance relationships. Independent service organizations are capturing preventive maintenance contracts for end-of-warranty 1.5 Tesla systems in regional hospital networks. This pattern is most visible in Valencia and Galicia, where budget-constrained public health systems prioritize operational expenditure flexibility over single-source vendor commitments.
Spain Magnetic Resonance Imaging Market Segmentation
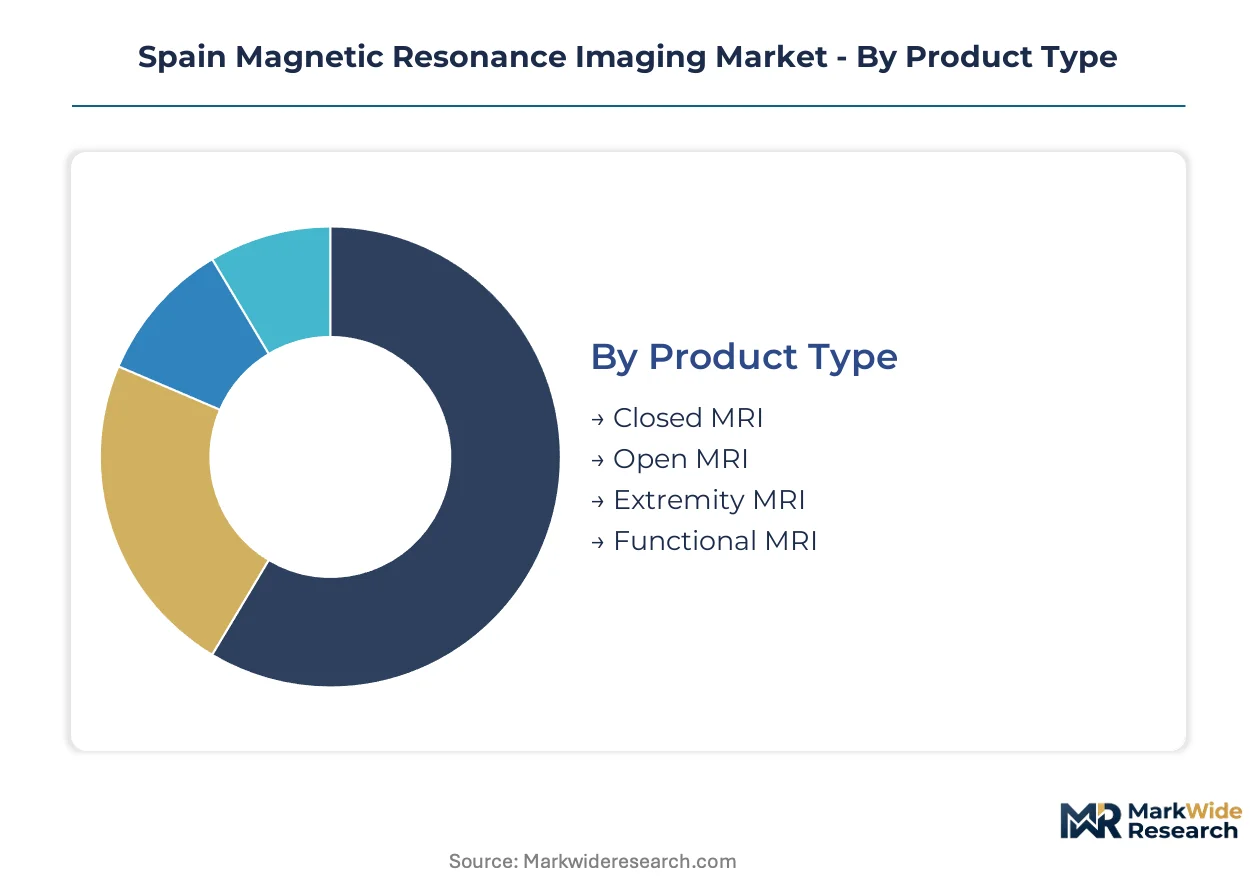
Segmentation in the Spain MRI market reveals how procurement priorities diverge across clinical settings and technological architectures. Understanding these fault lines exposes where capital concentrates and where substitution threats emerge.
Product Type:
Cost tier differentiation separates premium closed systems from accessible open architectures, with procurement committees weighing image fidelity against patient throughput economics.
- Closed MRI:Superconducting magnets operating at 1.5 to 3.0 Tesla generate superior signal-to-noise ratios essential for neurological and oncological diagnostics. Tertiary hospitals in Barcelona and Madrid prioritize these systems for high-volume oncology networks where diagnostic confidence justifies capital intensity.
- Open MRI:C-shaped or double-doughnut magnet geometries eliminate enclosed bore constraints, capturing pediatric and claustrophobic patient populations. Demand concentrates in community imaging centers across Andalusia where patient comfort design commands premium positioning despite lower field strength.
- Extremity MRI:Dedicated limb scanners using permanent magnets or low-field superconducting designs serve orthopedic specialty clinics.
- Functional MRI:Blood-oxygen-level-dependent sequences enable real-time brain mapping for neurosurgical planning and research protocols.
Closed MRI commands the established base. The steepest expansion runs through Open MRI architectures addressing patient accessibility gaps.
Technology:
Maturity curves and helium supply economics determine which magnet technologies sustain competitive positioning versus face displacement.
- Superconducting MRI:Niobium-titanium coils cooled to 4 Kelvin by liquid helium deliver field strengths from 1.5 to 7 Tesla with exceptional homogeneity. AEMPS-regulated tertiary networks in Catalonia and Madrid anchor procurement here despite helium price volatility constraining operational budgets.
- Permanent Magnet MRI:Ferrite or rare-earth configurations eliminate cryogenic infrastructure, reducing maintenance complexity for decentralized clinic deployments. Valencia and Galicia public health systems favor these for budget-constrained regional networks seeking operational expenditure flexibility.
- Optical MRI:Emerging atomic magnetometer approaches promise helium-independent ultra-low-field operation.
- Hybrid MRI:Combined PET-MRI or CT-MRI platforms integrate functional and anatomical imaging for radiation oncology planning.
Superconducting MRI retains the dominant installed base. Permanent Magnet MRI is climbing the fastest as decentralized care models expand.
End User:
Customer type determines capital commitment scale and service contract structures, from full ownership to managed equipment partnerships.
- Hospitals:Tertiary and secondary acute care facilities with integrated radiology departments drive high-field closed-system procurement. Public-private partnership imaging contracts in Barcelona and Madrid metropolitan clusters are converting capital expenditure to utilization-guaranteed operational models.
- Imaging Centers:Dedicated diagnostic facilities prioritize throughput-optimized 1.5 Tesla systems with extended service agreements.
- Research Institutes:University hospitals and neuroscience centers deploy 3.0 Tesla and experimental 7 Tesla platforms for protocol development.
- Clinics:Single-specialty and primary care settings adopt extremity or open systems for point-of-care musculoskeletal diagnostics.
Hospitals command the established base. Imaging Centers are gaining share fastest through managed service contract expansion.
Application:
Clinical volume and reimbursement economics determine which diagnostic protocols justify magnet saturation and AI-enabled workflow investments.
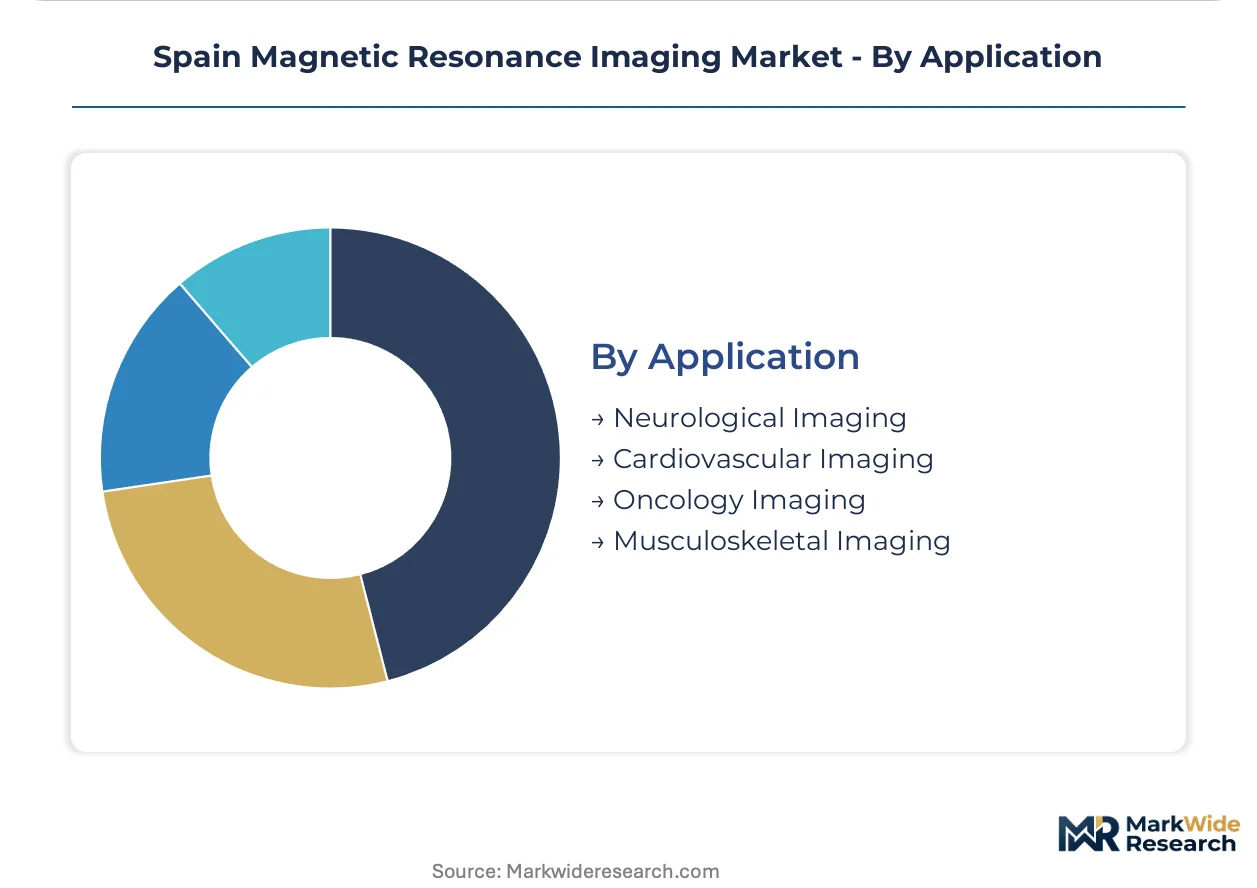
- Neurological Imaging:High-resolution brain parenchyma visualization for stroke, demyelinating disease, and tumor characterization demands 3.0 Tesla field strength. Madrid's comprehensive stroke networks and Barcelona's multiple sclerosis referral centers concentrate procurement here.
- Oncology Imaging:Multiparametric body imaging for staging and treatment response assessment drives scanner utilization in cancer center networks. EU AI Act risk classification frameworks for diagnostic algorithms are reshaping software procurement criteria in high-throughput centers.
- Cardiovascular Imaging:Non-invasive angiography and viability assessment without nephrotoxic contrast agents.
- Musculoskeletal Imaging:Ligament, cartilage, and bone marrow evaluation for orthopedic and sports medicine referrals.
Neurological Imaging commands the established base. Oncology Imaging is expanding most quickly through AI-assisted workflow convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional consumption patterns in Spain diverge sharply between high-field tertiary installations in metropolitan cores and decentralized low-field deployments in peripheral provinces. Madrid and Barcelona concentrate 3.0 Tesla procurement for complex neurological and oncological protocols, while Andalusia and Galicia favor operational-expenditure flexibility through managed service contracts.
Madrid
The capital region drives superconducting high-field demand through comprehensive stroke networks and multiple sclerosis referral centers. AEMPS coordinates EU MDR conformity assessments for new system introductions, compressing replacement timelines across Hospital Universitario La Paz and Hospital Clínico San Carlos networks. Public-private partnership imaging contracts are converting capital expenditure to utilization-guaranteed operational models in the metropolitan cluster.
Catalonia
Barcelona anchors procurement for oncology imaging networks requiring multiparametric body staging capabilities. The regional health authority's tender specifications are pivoting toward outcome-based equipment leasing rather than direct capital purchase. Vall d'Hebron Hospital and Hospital Clínic de Barcelona are deploying AI-assisted workflow tools under EU AI Act risk classification frameworks.
Andalusia
Seville and Málaga provinces present whitespace for high-field system deployment in underpenetrated tertiary capacity. Regional budget constraints are accelerating permanent magnet adoption in community imaging centers seeking lower operational complexity. The Andalusian Health Service is expanding managed equipment partnerships to access advanced diagnostics without full ownership burdens.
Basque Country
Bilbao and San Sebastián concentrate research-grade installations for neurosurgical planning and protocol development. The regional government's innovation agency is funding hybrid MRI-PET platforms for radiation oncology planning at University Hospital Donostia. EU MDR compliance deadlines are forcing replacement of legacy 1.5 Tesla systems ahead of scheduled depreciation cycles.
Valencia
The Mediterranean province exhibits the strongest independent service organization penetration for end-of-warranty maintenance contracts. Budget-constrained public health systems here prioritize operational expenditure flexibility over single-source vendor commitments. Hospital Universitario y Politécnico La Fe is piloting compressed sensing reconstruction algorithms to increase daily patient throughput.
Spain Magnetic Resonance Imaging Market Competitive Landscape
Capability concentration sits with legacy superconducting magnet specialists; scale advantage sits with diversified health technology conglomerates. The vendor base organizes into three tiers: integrated imaging platform providers with extensive service footprints, regional specialists in open and extremity architectures, and emerging independent service organizations capturing aftermarket maintenance contracts. Consolidation pressure is intensifying as EU MDR compliance costs favor players with established quality management systems and notified body relationships.
Among diversified health technology conglomerates, Siemens Healthineers, GE Healthcare, and Koninklijke Philips NV exemplify the integrated platform archetype. These entities anchor competitive positioning through recurring service revenue streams and predictive maintenance platforms that minimize scanner downtime. Siemens Healthineers leverages its extensive footprint across Spanish hospital networks; GE Healthcare competes through AI-enabled workflow integration; Koninklijke Philips NV raises switching costs by embedding diagnostic algorithms into service agreements. Regional specialists including Esaote SpA and Canon Medical Systems Corporation occupy positions in open-architecture and pediatric segments where patient comfort design commands premium positioning.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Bruker |
| Esaote SpA |
| Aurora Imaging Technology |
| Hitachi Medical Systems |
| Others |
Value Network & Pricing Analysis
Magnet saturation rates across Madrid and Barcelona tertiary networks are compressing scanner utilization below optimal thresholds, forcing vendors to extend payment terms and bundle service contracts to maintain procurement committee engagement.
Pricing Analysis
Long-term managed equipment contracts dominate procurement in Catalonia and Madrid, displacing capital purchase models as regional health authorities seek operational expenditure flexibility. Three-tier pricing structure across premium 3.0 Tesla, standard 1.5 Tesla, and economy open-architecture levels reflects field strength, helium recovery infrastructure, and AI-enabled workflow bundling. Cost compression in standard-tier systems is intensifying because permanent magnet alternatives are capturing decentralized clinic segments. Public hospital networks exhibit highest price sensitivity due to fixed capital budgets, while private imaging centers in Barcelona demonstrate lowest sensitivity where throughput economics justify premium positioning.
Supply Chain Analysis
Extended payment terms from Siemens Healthineers and GE Healthcare are stabilizing procurement timelines for Spanish hospital networks facing EU MDR compliance cost pressures. Niobium-titanium coil fabrication concentrates in Germany, Japan, and the United States, while helium liquefaction and cryogenic distribution draw from Qatar and the United States. Supply chain risk centers on single-source vulnerability for specialized superconducting wire and concentrated helium refining capacity. Distribution runs through authorized service organizations with captive maintenance agreements, though independent service organizations are fragmenting aftermarket relationships in Valencia and Galicia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among regional health authorities consolidating imaging procurement across hospital networks, compressing vendor margins and favoring outcome-based contract structures.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance platforms and AI-assisted workflow tools into multi-year agreements, raising switching costs for radiology departments facing AEMPS compliance deadlines. Deepen backward integration into helium recovery infrastructure to offset input cost volatility threatening superconducting system economics. For New Entrants and Emerging Players: Establish a beachhead in Andalusian community imaging centers where permanent magnet demand is climbing fastest and vendor relationships remain unconsolidated. Target Seville and Málaga provinces with operational-expenditure-flexible leasing models that bypass capital committee approval thresholds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent service organizations capturing end-of-warranty maintenance contracts in budget-constrained regional networks. Acquisition targets should demonstrate established notified body relationships for EU MDR conformity assessment and installed-base density in underpenetrated provinces. Watch for inflection when regional tender specifications pivot decisively toward utilization-guaranteed contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Infrastructure Deployment | Closed-loop cryogenic systems reduce lifecycle costs for hospital procurement committees facing supply volatility. |
| AI-Assisted Workflow Integration | Embedded diagnostic algorithms raise switching costs under EU AI Act risk classification frameworks. |
| Public-Private Partnership Expansion | Managed equipment contracts convert capital expenditure to operational models in Barcelona and Madrid clusters. |
| Independent Service Organization Buildout | Aftermarket unbundling captures preventive maintenance revenue from end-of-warranty 1.5 Tesla systems. |
| Permanent Magnet Product Line Extension | Low-field architectures address decentralized clinic demand in Valencia and Galicia budget-constrained networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, radiology department heads, and GPO contracts managers. Secondary validation drew from AEMPS regulatory filings, EU MDR notified body assessment records, hospital procurement databases, and regional health authority tender specifications. Bottom-up installed-base enumeration and top-down healthcare expenditure allocation were triangulated to establish market sizing boundaries.
Calibration against historical replacement cycles and EU MDR compliance deadline impacts anchored volume projections across the analysis window. Segmentation dimensions modeled include magnet technology architecture, field strength tier, end-user facility type, clinical application protocol, and regional health authority procurement structure. CAGRs were derived from replacement cycle compression rates and managed service contract penetration curves, with helium price volatility and AI algorithm adoption timelines as sensitivity inputs.
Sensitivities concentrate around AEMPS approval timeline extensions, helium supply disruptions, and permanent magnet substitution acceleration. Forecasts reflect documented assumptions on EU MDR enforcement consistency and regional budget allocation stability. Macroeconomic contraction, regulatory harmonization delays, or breakthrough low-field diagnostic equivalence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
South America MRI Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Ultrasound Market
Medical Imaging
France Mammography Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market