
 France Nuclear Imaging Market | 2026-2036
France Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Nuclear Imaging Market Foresight
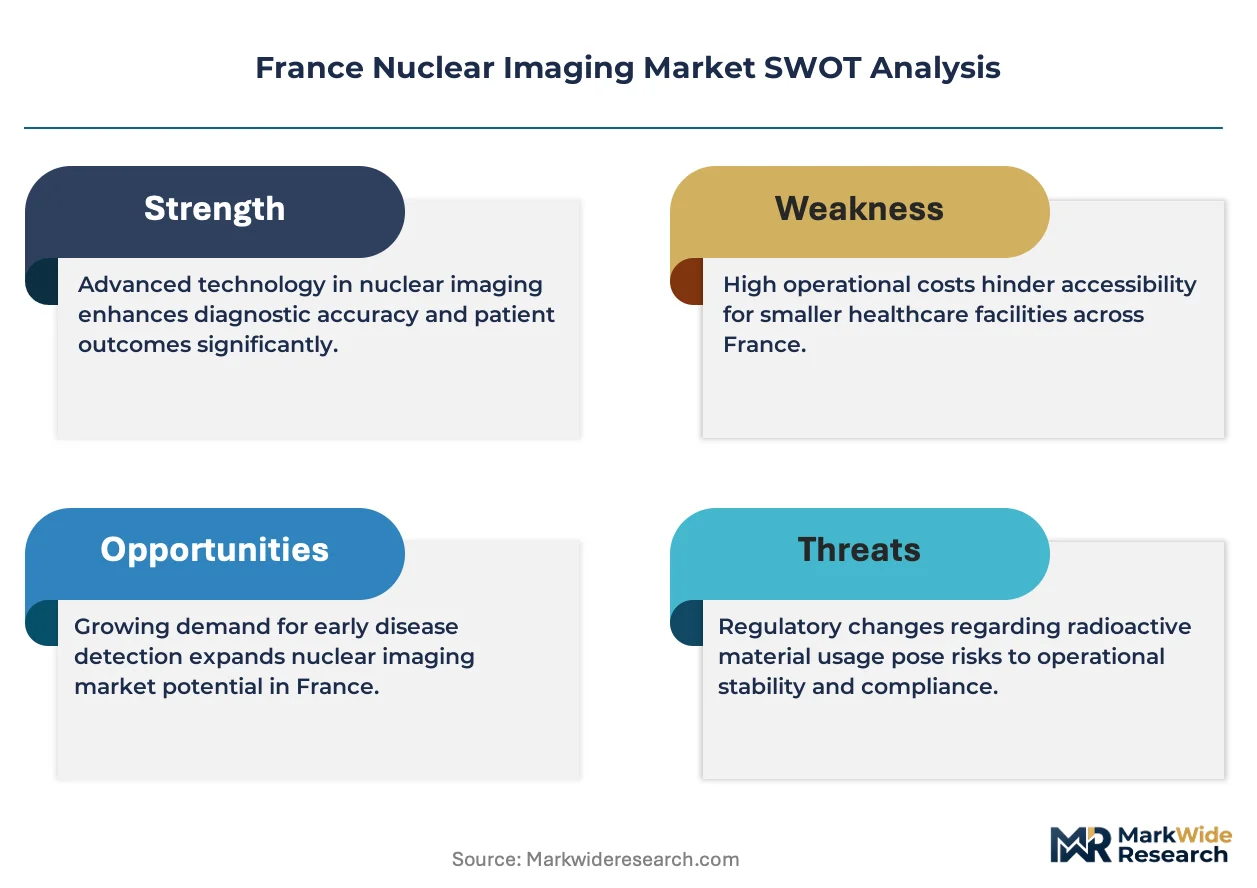
Equipment leasing and pay-per-scan service models is reconfiguring capital deployment across French imaging networks, allowing smaller diagnostic centers to access advanced modalities without full ownership burdens. Siemens Healthineers leverages its hybrid imaging portfolio to anchor large academic contracts in Lyon and Paris. Curium France SASU sustains domestic isotope production through its Val-de-Reuil facility, securing supply continuity for PET tracers nationwide. Canon Medical Systems differentiates through detector technology specialization, competing for replacement cycles in aging SPECT installations.
France nuclear imaging encompasses diagnostic systems that detect gamma ray emissions from administered radiopharmaceuticals to visualize metabolic and functional processes, with spatial resolution thresholds typically reaching 4-5 mm for PET and 8-12 mm for SPECT depending on detector configuration. These technologies enable precise localization of oncological, cardiac, and neurological pathologies where anatomical imaging alone proves insufficient. Hybrid systems combining PET or SPECT with CT or MRI dominate new installations, as multimodal registration improves diagnostic confidence and reduces false-positive rates in complex staging protocols. Radiopharmaceuticals represent the fastest-expanding technology segment, driven by therapeutic diagnostics pairing and novel tracer development for prostate and neuroendocrine indications.
ANSM oversees radiopharmaceutical manufacturing authorization and batch release, while ASN regulates nuclear safety for cyclotron and reactor-sourced isotope production facilities, jointly determining market access timelines for new diagnostic agents. France's incorporation of EU MDR requirements for active implantable and radiation-emitting devices adds conformity assessment layers that shape product registration strategies for imported systems. HAS evaluation of clinical benefit and reimbursement levels directly conditions hospital procurement volumes, creating a tripartite gatekeeper structure that manufacturers must navigate sequentially. Stakeholders should monitor ASN's evolving criteria for production facility licensing, as capacity constraints for technetium-99m and gallium-68 generators could redirect procurement toward alternative isotope sources or regional production partnerships.
Market Dynamics
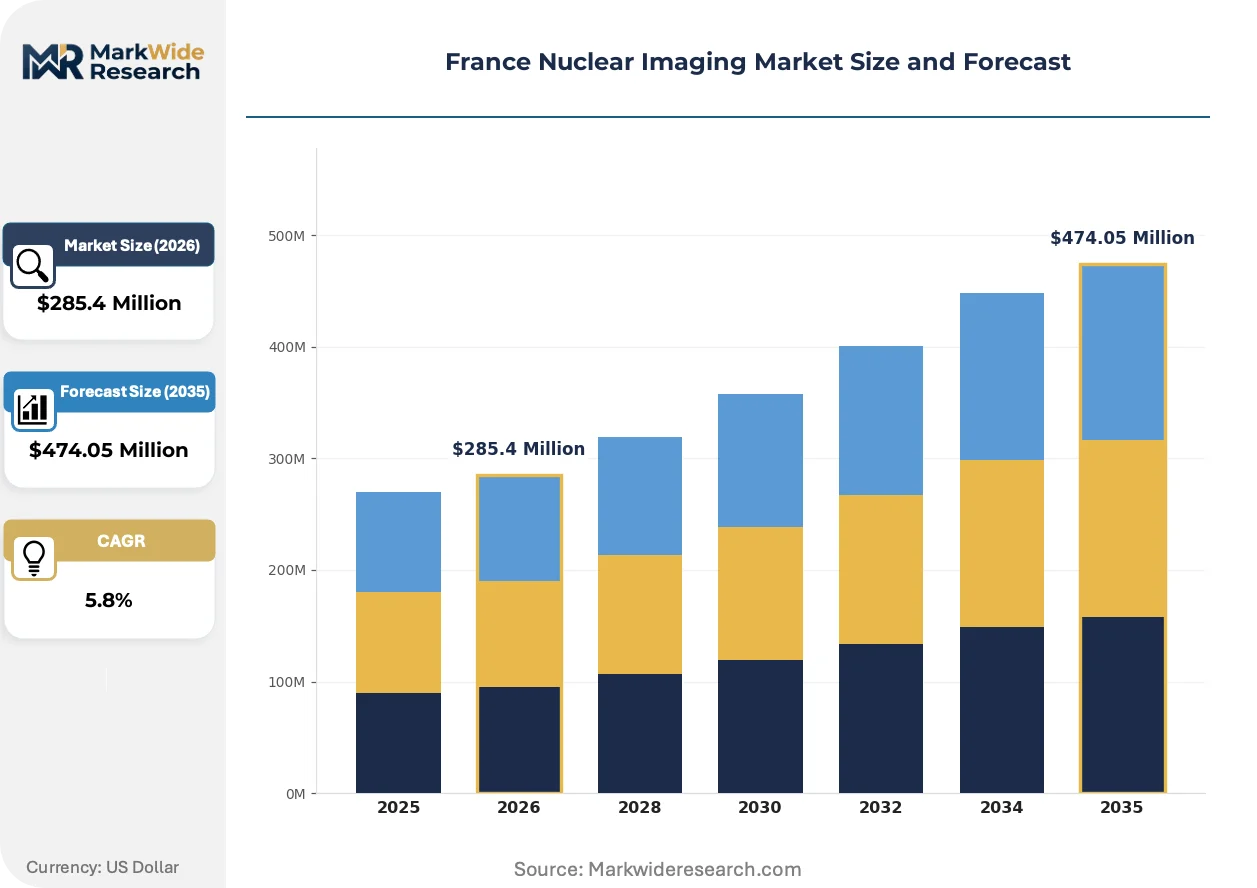
HAS reimbursement acceleration for novel radiopharmaceuticals is compressing market access timelines, while cyclotron production concentration in Val-de-Reuil creates supply vulnerabilities that reshape procurement strategies across French hospital networks.
Growth Catalysts
- Oncology staging protocols:PET-CT utilization expands across AP-HP university hospitals for treatment monitoring, creating sustained tracer demand.
- EU MDR harmonization:Streamlined conformity assessment for hybrid imaging systems reduces registration friction for imported modalities.
- Theranostic pairing:Diagnostic-therapeutic radiopharmaceutical combinations for prostate and neuroendocrine indications broaden clinical application scope.
Market Restraints
- Technetium-99m generator shortages:Reactor-sourced molybdenum supply interruptions expose dependence on aging European production infrastructure.
- Cyclotron licensing density:ASN facility authorization bottlenecks constrain gallium-68 production capacity expansion outside Île-de-France.
- SPECT detector obsolescence:Cadmium-zinc-telluride crystal costs and silicon photomultiplier transition timelines delay replacement cycles in regional clinics.
Strategic Opportunities
- Occitanie production partnerships:Regional cyclotron installations outside Paris basin address supply geography concentration.
- AI-augmented reconstruction:Deep learning algorithms reduce scan acquisition times, expanding throughput-constrained department capacity.
- Mobile PET-CT deployment:Fleet-based service models penetrate underserved Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur territories.
Industry Challenges
- Radiopharmacist workforce scarcity:Specialized compounding expertise shortages delay batch release timelines at decentralized production sites.
- Hybrid system integration complexity:PET-MRI registration protocols require physicist retraining that outpaces institutional education budgets.
- ANSM batch release backlogs:Novel tracer manufacturing authorization queues extend time-to-market for innovative diagnostic agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Nuclear Imaging Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPECT Scanners, PET Scanners, Gamma Cameras, Hybrid Systems Technology: Radioisotope Imaging, Radiopharmaceuticals, Digital Imaging, Tomographic Systems Application: Oncology Diagnosis, Cardiology Evaluation, Neurology Assessment, Endocrinology Monitoring End User: Diagnostic Centers, Research Institutes, Imaging Clinics, Specialty Hospitals |
| Companies Covered | GE Healthcare, Canon Medical Systems, Koninklijke Philips N.V., Bracco Imaging S.p.A., Siemens Healthineers, Curium France SASU, Cardinal Health, Inc., Siemens AG, DOSIsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Nuclear Imaging Market Shifts & Advancements
Digital PET detector architectures and AI-native reconstruction workflows are compressing acquisition windows while elevating diagnostic confidence, forcing incumbent manufacturers to accelerate R&D cycles.
Silicon photomultiplier arrays are replacing conventional photomultiplier tubes in next-generation PET systems, delivering improved timing resolution and magnetic field compatibility. Academic medical centers in Lyon and Paris pilot these configurations for simultaneous PET-MRI protocols. Solid-state photodetection is rendering obsolete vacuum-tube-based signal chains that dominated hybrid imaging for three decades.
France's transposition of EU MDR requirements for radiation-emitting active implantable devices imposes notified body conformity assessment layers beyond prior medical device directives. Manufacturers now face extended technical documentation reviews for CT-integrated gantries. Siemens Healthineers and Canon Medical Systems restructure French regulatory affairs teams to manage parallel ANSM and notified body submissions.
Service-based contracting is displacing capital purchase models among mid-size diagnostic networks seeking PET-CT access without cyclotron ownership. Third-party radiopharmaceutical logistics providers consolidate last-mile cold-chain distribution to regional imaging centers. Equipment-as-a-service penetration concentrates in Nouvelle-Aquitaine and Hauts-de-France where hospital consolidation limits independent capital allocation.
France Nuclear Imaging Market Segmentation
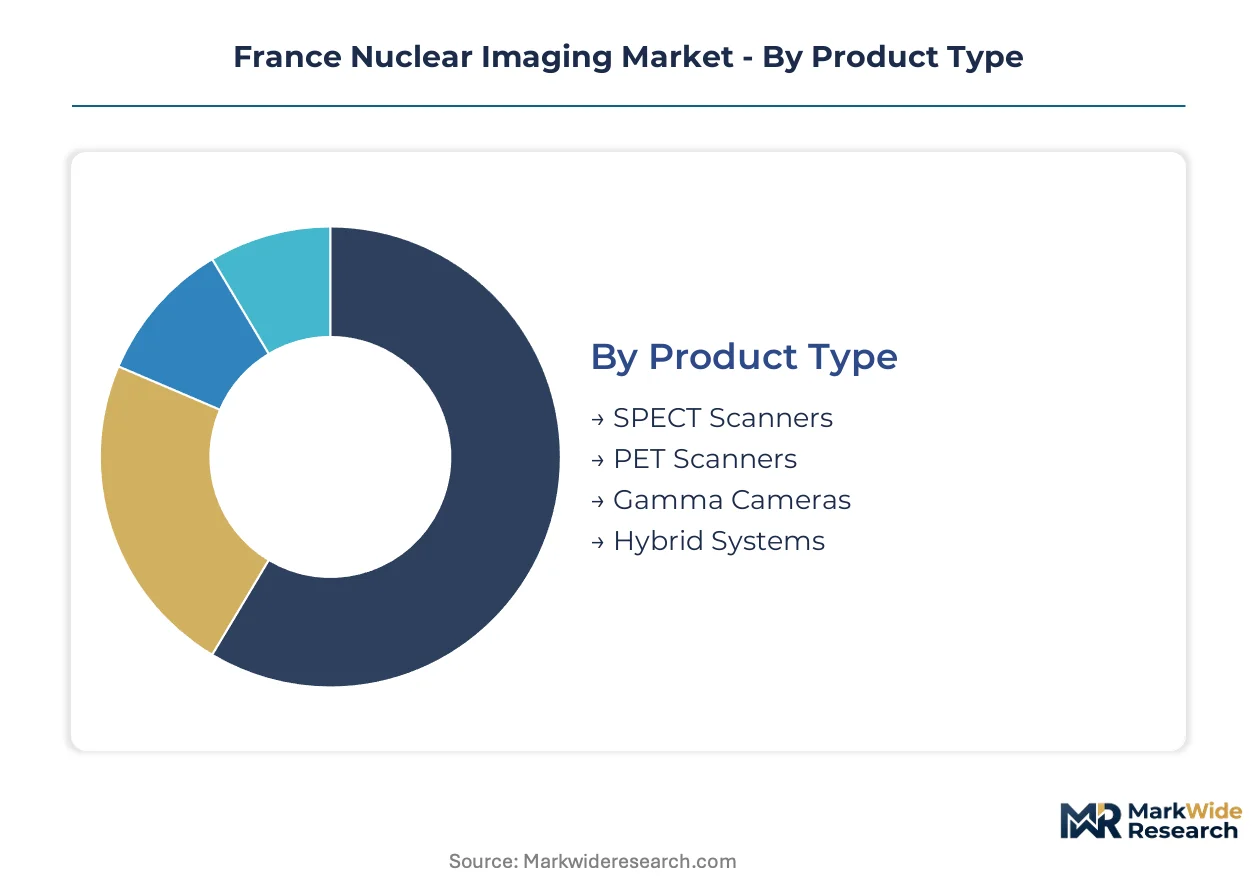
France nuclear imaging segmentation reveals distinct procurement patterns across product types, technologies, applications, and end-user settings. Understanding these divisions illuminates where HAS reimbursement policies and ASN regulatory requirements exert differential pressure on adoption timelines.
Product Type:
Modalities span the functional imaging spectrum from standalone gamma detection to integrated hybrid architectures.
- Hybrid Systems:PET-CT and PET-MRI configurations combine metabolic and anatomical imaging in single acquisition protocols. AP-HP university hospitals in Île-de-France prioritize these for oncology staging, though cyclotron proximity requirements constrain deployment in peripheral regions.
- PET Scanners:Digital detector architectures with silicon photomultiplier arrays deliver sub-300 picosecond timing resolution. Demand concentrates in Lyon and Paris academic centers where theranostic protocols require quantitative tracer kinetics.
- SPECT Scanners:Anger camera geometries with sodium iodide crystals remain prevalent for cardiac perfusion studies. Regional clinics in Auvergne-Rhône-Alpes delay replacement cycles due to cadmium-zinc-telluride cost premiums.
- Gamma Cameras:Single-head and dual-head configurations serve sentinel node mapping and thyroid uptake quantification. Nouvelle-Aquitaine diagnostic centers utilize these for cost-contained endocrinology workflows.
The dominant share belongs to Hybrid Systems, while PET Scanners is closing the gap fastest.
Technology:
Technology segmentation tracks the transition from analog signal chains to solid-state detection and AI-native reconstruction.
- Radiopharmaceuticals:Gallium-68 and fluorine-18 labeled tracers enable prostate-specific membrane antigen and somatostatin receptor imaging. Curium's Val-de-Reuil facility supplies these agents nationwide, though ANSM batch release queues create intermittent availability constraints.
- Radioisotope Imaging:Technetium-99m generator dependence shapes SPECT utilization patterns across cardiology departments. Aging European reactor infrastructure exposes French networks to molybdenum supply interruptions.
- Digital Imaging:AI-augmented reconstruction algorithms reduce acquisition times by 40-60% while preserving diagnostic confidence. Siemens Healthineers deploys these workflows in contracted academic sites.
- Tomographic Systems:Iterative reconstruction methods and time-of-flight capabilities define next-generation PET performance specifications. Canon Medical Systems competes on detector geometry specialization for SPECT replacement markets.
Radiopharmaceuticals commands the largest technology investment, with Digital Imaging expanding most quickly through AI integration mandates.
Application:
Clinical applications reflect disease burden distribution and HAS reimbursement prioritization across French healthcare territories.
- Oncology Diagnosis:PET-CT staging for lung, colorectal, and lymphoma indications drives tracer consumption volume. HAS accelerated reimbursement for prostate-specific membrane antigen imaging expands addressable patient populations.
- Cardiology Evaluation:Myocardial perfusion imaging with technetium-99m sestamibi remains the dominant SPECT application. Regional clinics in Hauts-de-France maintain high examination throughput despite modality age.
- Neurology Assessment:Amyloid and tau tracer protocols for Alzheimer's disease evaluation concentrate in Paris and Lyon memory centers. ANSM manufacturing authorization timelines delay novel agent availability.
- Endocrinology Monitoring:Iodine-131 whole-body scanning and parathyroid scintigraphy serve thyroid carcinoma and hyperparathyroidism indications. Occitanie specialty hospitals combine these with surgical navigation systems.
Oncology Diagnosis retains the dominant application share, though Neurology Assessment is gaining share fastest through dementia care pathway expansion.
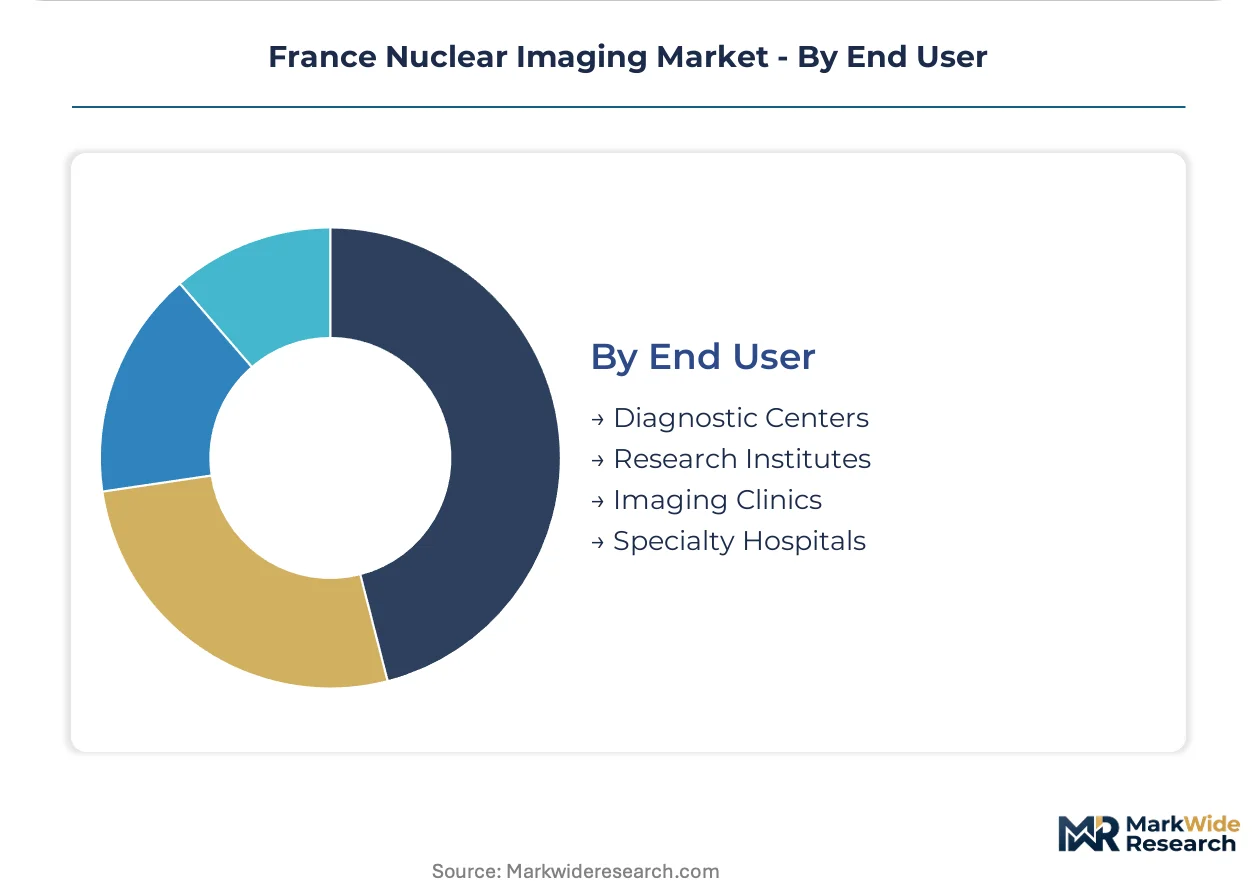
End User:
Procurement authority and capital allocation flexibility vary sharply across institutional categories.
- Specialty Hospitals:AP-HP and regional university hospital centers command hybrid system acquisition budgets and cyclotron partnerships. These institutions define protocol standards that cascade to affiliated networks.
- Diagnostic Centers:Independent imaging facilities in Île-de-France adopt equipment-as-a-service models to access PET-CT without capital ownership. Third-party radiopharmaceutical logistics enables this operational structure.
- Research Institutes:INSERM-affiliated units and academic radiochemistry departments pilot novel tracer synthesis and theranostic pairings. ASN licensing density limits production scale-up beyond experimental batches.
- Imaging Clinics:Private cardiology and nuclear medicine practices in Provence-Alpes-Côte d'Azur maintain SPECT installations for perfusion studies. Mobile PET-CT fleet services penetrate this segment in underserved territories.
Specialty Hospitals hold the dominant procurement volume, while Diagnostic Centers is climbing the fastest through service-based contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France maintains near-complete self-sufficiency in radiopharmaceutical supply through domestic cyclotron networks, though regional distribution imbalances create import dependencies for specific isotope categories in peripheral territories.
Île-de-France
AP-HP university hospital networks and Curium's Val-de-Reuil production facility generate the densest diagnostic ecosystem nationwide. HAS reimbursement protocols for novel tracers propagate from Paris-based clinical trial centers to affiliated regional networks. The Petite-Couronne cyclotron cluster sustains gallium-68 and fluorine-18 output for prostate and neuroendocrine imaging protocols.
Auvergne-Rhône-Alpes
Lyon's academic medical centers pilot silicon photomultiplier PET-MRI configurations for theranostic applications. ANSM manufacturing authorization timelines delay novel agent availability despite strong INSERM-affiliated radiochemistry capacity. The Lyon-Saint-Étienne corridor hosts the second-highest hybrid imaging installation density outside Paris.
Provence-Alpes-Côte d'Azur
Mobile PET-CT fleet services penetrate underserved territories where fixed cyclotron infrastructure remains absent. ASN facility licensing bottlenecks constrain gallium-68 production capacity expansion. Marseille's university hospital network relies on radiopharmaceutical logistics providers for last-mile cold-chain distribution.
Hauts-de-France
Regional clinics maintain high SPECT examination throughput for cardiac perfusion studies despite modality age. Technetium-99m generator dependence exposes networks to molybdenum supply interruptions from aging European reactor infrastructure. Lille's university hospital anchors procurement standards for affiliated diagnostic centers.
Occitanie
Specialty hospitals combine iodine-131 whole-body scanning with surgical navigation systems for thyroid carcinoma pathways. Regional cyclotron installations address supply geography concentration outside the Paris basin. Toulouse's academic radiochemistry departments pilot production scale-up beyond experimental batches.
France Nuclear Imaging Market Competitive Landscape
On the supply side, the industry is consolidating around hybrid imaging system manufacturers with integrated radiopharmaceutical production capabilities. Three strategic archetypes dominate: diversified medical technology conglomerates with full imaging portfolios, specialized radiopharmaceutical producers with cyclotron networks, and detector technology specialists competing on hardware replacement cycles. Capacity expansion through regional production partnerships and technology licensing for AI-native reconstruction algorithms constitute the dominant competitive moves.
Among diversified imaging system manufacturers, Siemens Healthineers and GE Healthcare exemplify the integrated hardware-software archetype, anchoring large academic contracts through hybrid imaging portfolio breadth. Canon Medical Systems occupies a position within the detector specialization tier, competing for SPECT replacement markets. Curium France SASU represents the radiopharmaceutical production archetype, sustaining domestic isotope supply through cyclotron facility ownership.
| Leading Market Players |
|---|
| GE Healthcare |
| Canon Medical Systems |
| Koninklijke Philips N.V. |
| Bracco Imaging S.p.A. |
| Siemens Healthineers |
| Curium France SASU |
| Cardinal Health, Inc. |
| Siemens AG |
| DOSIsoft |
| Others |
Supply & Pricing Matrix
Curium's Val-de-Reuil cyclotron concentration and ASN-licensed production bottlenecks concentrate margin pools with radiopharmaceutical logistics providers and equipment-as-a-service operators downstream. Hospital procurement committees face asymmetric pricing power where tracer availability constraints override cost optimization in acute shortage periods.
Pricing Analysis
Academic medical center buyers anchor three-tier pricing stratification across premium PET-MRI configurations, standard PET-CT installations, and economy SPECT replacement markets. Price differentiation hinges on silicon photomultiplier detector grade and HAS reimbursement certification tier, with ANSM batch release timelines compressing margins for novel tracer introductions. Cost pressure in regional clinic segments intensifies as cadmium-zinc-telluride crystal shortages elevate SPECT detector replacement costs. Diagnostic center networks exhibit highest price sensitivity due to equipment-as-a-service contract structures, while AP-HP university hospitals prioritize availability guarantees over unit economics.
Supply Chain Analysis
Reactor-sourced molybdenum-99 feedstock from Belgium, Netherlands, and South Africa underpins technetium-99m generator availability across French cardiology departments. Solid-state photodetector arrays, lutetium-based scintillation crystals, and helium-3 neutron detection materials draw from specialized semiconductor foundries in Germany, Japan, and the United States. Single-source vulnerability concentrates in gallium-68 generator supply where Curium's domestic production dominates national distribution. Distribution runs through cold-chain radiopharmaceutical logistics networks with four-hour delivery windows from Val-de-Reuil to peripheral imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from service-based contracting displacement of capital purchase models, creating niche entry points for regional production partnerships and AI-augmented workflow specialists outside incumbent hardware portfolios.
For Market Incumbents: Insulate cyclotron production capacity through ASN facility licensing pre-emption in Occitanie and Auvergne-Rhône-Alpes corridors, blocking regional competitor scale-up. Anchor hospital system partnerships via integrated PET-CT-radiopharmaceutical bundle contracts that raise switching costs for diagnostic center networks. Vertical integration into silicon photomultiplier detector manufacturing reduces supply exposure to German and Japanese component shortages. For New Entrants and Emerging Players: Pursue mobile PET-CT fleet deployment in Provence-Alpes-Côte d'Azur and Hauts-de-France territories where fixed cyclotron infrastructure remains absent and HAS reimbursement protocols still propagate from Paris trial centers. Target diagnostic center equipment-as-a-service contracts in Nouvelle-Aquitaine where hospital consolidation limits independent capital allocation. Lead with AI-native reconstruction workflow partnerships that reduce scan acquisition times without requiring full modality replacement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed radiopharmaceutical logistics providers consolidating last-mile cold-chain distribution to regional imaging centers. Five-to-ten-year viability hinges on theranostic pairing expansion beyond prostate and neuroendocrine indications into Alzheimer's amyloid and tau tracer protocols. Monitor ANSM manufacturing authorization queue clearance rates as inflection signal for novel agent time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cyclotron Partnership | Occitanie production installations reduce Île-de-France supply concentration vulnerability for gallium-68 generators. |
| AI-Native Reconstruction Licensing | Deep learning algorithm partnerships expand throughput-constrained department capacity without hardware replacement. |
| Mobile PET-CT Fleet Expansion | Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur penetration addresses underserved territory access gaps. |
| Radiopharmacist Workforce Development | Specialized compounding expertise pipelines accelerate ANSM batch release timelines at decentralized production sites. |
| Silicon Photomultiplier Manufacturing Scale-Up | Domestic detector production reduces dependence on German and Japanese semiconductor foundry supply. |
Research Methodology
A spread of perspectives from nuclear medicine physicians, hospital biomedical engineers, radiopharmaceutical production managers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against ANSM manufacturing authorization databases, HAS reimbursement protocol documentation, and ASN facility licensing records. Bottom-up installation data triangulated against top-down radiopharmaceutical consumption metrics from Curium distribution networks.
Demand-supply balance modeling tracked modality replacement cycles, tracer production capacity constraints, and workforce availability across the projection horizon. Segmentation dimensions included hybrid system architecture, detector technology generation, clinical application protocol, and end-user institutional category. CAGRs derived from equipment shipment data, radiopharmaceutical batch release volumes, and hospital procurement contract values. Forecast inputs incorporated EU MDR transition timelines and HAS accelerated reimbursement pathway expansion for prostate-specific membrane antigen imaging.
Sensitivities concentrate around reactor-sourced molybdenum supply interruptions, ASN cyclotron licensing approval rates, and silicon photomultiplier detector cost trajectories. Forecasts embed assumptions regarding ANSM batch release queue clearance and theranostic protocol adoption velocity that external observers may assess differently. Cross-checking against hospital procurement database benchmarks and European cyclotron installation registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
South America MRI Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Portable MRI Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Americas Interventional Radiology Market