
 Asia Pacific Nuclear Imaging Devices Market | 2026-2036
Asia Pacific Nuclear Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Nuclear Imaging Devices Market Insights
Hospital procurement consolidation across Southeast Asia is realigning vendor relationships toward turnkey service contracts. Siemens Healthineers leverages its regional service infrastructure to anchor long-term maintenance agreements with expanding hospital networks. Canon Medical Systems Corporation competes on digital detector integration across its hybrid imaging platforms. GE Healthcare dominates the high-end positron emission tomography segment through its established distributor presence in Japan and Australia.
Asia Pacific nuclear imaging devices encompass gamma cameras, SPECT systems, PET scanners, and hybrid imaging platforms that detect gamma ray emissions from radiopharmaceutical tracers to reconstruct functional organ and tissue maps, typically operating with spatial resolutions between 4-10 mm and detector sensitivities calibrated to technetium-99m or fluorodeoxyglucose isotope profiles. These systems enable non-invasive metabolic assessment for oncology staging, cardiac perfusion analysis, and neurological disorder diagnosis. Hybrid imaging systems command the highest capital investment per unit while digital detectors represent the fastest upgrade cycle as facilities transition from analog photomultiplier tubes to solid-state cadmium-zinc-telluride arrays. Software analytics for quantitative PET biomarker extraction sits at the margin pool center, with vendors bundling AI-assisted lesion segmentation to defend pricing against hardware commoditization.
Japan's PMDA governs radiopharmaceutical approval timelines and device software validation, while China's NMPA enforces GB standards for electromagnetic compatibility and clinical imaging performance. India's CDSCO and BIS jointly regulate import licensing and quality certification for nuclear medicine equipment, creating multi-layered compliance pathways for foreign manufacturers. Stakeholders must monitor divergence between national radiopharmaceutical supply chains and device regulatory frameworks as localization mandates tighten across the region.
Market Dynamics
Hospital procurement consolidation across Southeast Asia is consolidating purchasing power into multi-hospital networks, forcing device vendors to abandon transactional equipment sales in favor of decade-long service partnerships that bundle hardware, software updates, and radiopharmaceutical logistics.
Growth Catalysts
- India's PLI scheme for medical device manufacturing:Domestic production incentives are attracting component suppliers to establish CZT detector foundries near Bengaluru and Hyderabad, shortening lead times for SPECT system assembly.
- Japan's revised reimbursement frameworks for hybrid imaging:PET-MRI and PET-CT procedures now carry preferential coding in the universal health insurance system, accelerating capital deployment at university hospitals.
- Digital detector transition:Solid-state cadmium-zinc-telluride arrays are replacing analog photomultiplier tubes across China's tier-one oncology centers, driving replacement demand independent of new facility construction.
Market Restraints
- Molybdenum-99 supply concentration:Five aging research reactors in Australia, South Africa, and Europe supply over 80 percent of the parent isotope for technetium-99m generators; scheduled maintenance shutdowns create predictable radiopharmaceutical shortages.
- Capital intensity of hybrid platforms:PET-MRI systems require shielded suites, cryogenic infrastructure, and specialized HVAC, constraining installation to greenfield hospital wings rather than retrofit opportunities.
- CDSCO import licensing timelines:India's dual-track approval for nuclear medicine equipment—device registration plus BIS quality certification—extends commercialization timelines by 14-18 months versus comparable ASEAN markets.
Strategic Opportunities
- Vietnam's underpenetrated diagnostic imaging base:Ho Chi Minh City and Hanoi maintain SPECT scanner density below one unit per million population, creating first-mover advantage for vendors establishing local service depots.
- AI-assisted lesion segmentation software:Quantitative PET biomarker extraction tools command recurring licensing revenue streams that offset hardware margin compression in saturated Japanese and Australian markets.
- Australia's TGA fast-track for breakthrough devices:Novel detector materials and iterative reconstruction algorithms receive priority review, compressing time-to-revenue for next-generation platforms.
Industry Challenges
- Nuclear medicine technologist shortage:Australia's professional accreditation body reports 340 unfilled positions across public hospital networks, constraining scanner utilization rates regardless of installed base expansion.
- Legacy PACS integration complexity:Southeast Asian hospital networks operate heterogeneous imaging archives from multiple vendors, requiring costly middleware development for seamless PET and SPECT data incorporation.
- GB standards electromagnetic compliance testing:China's NMPA mandates in-country testing for all RF-emitting medical devices, duplicating ISO 13485 quality system certifications and extending pre-market preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Nuclear Imaging Devices Market |
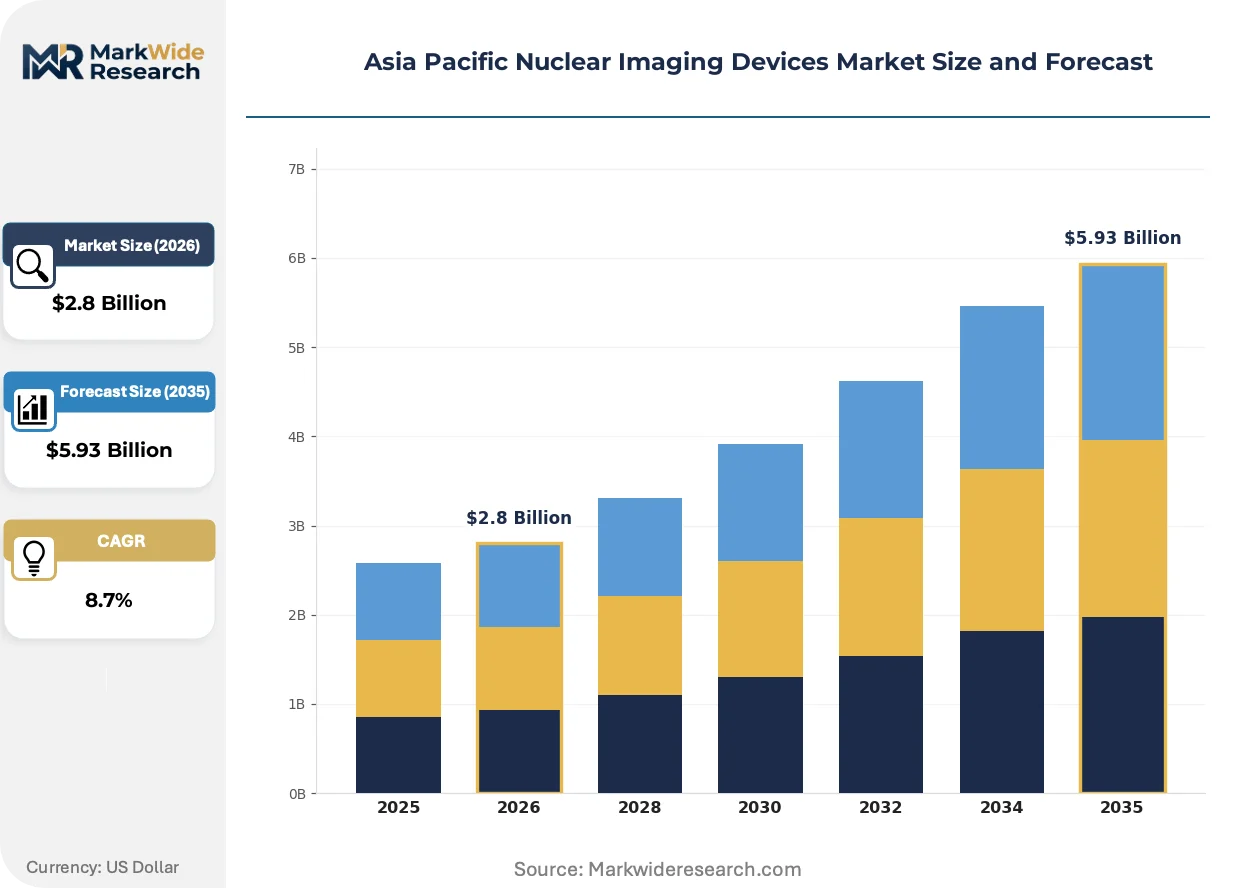
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging Systems, Gamma Cameras End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Clinics Technology: Radiopharmaceutical Systems, Digital Detectors, Imaging Algorithms, Software Analytics Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers, Koninklijke Philips NV, GE Healthcare, Neusoft Medical Systems Co., Ltd., Mindray Medical International, Fujifilm Holdings Corp., Hitachi Healthcare, Shimadzu Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Nuclear Imaging Devices Market Trends and Innovations
Digital detector architectures and AI-native reconstruction algorithms are compressing the traditional hardware replacement cycle while elevating software analytics to the center of vendor competitive strategy across Asia Pacific nuclear imaging.
Solid-state cadmium-zinc-telluride detector arrays are unifying energy resolution and spatial resolution performance in a single sensor platform. China's tier-one oncology centers are adopting these detectors at replacement rates exceeding analog system retirements by three-to-one. This unifying hardware transition is compressing the vendor service revenue model from time-and-materials repairs toward predictive maintenance contracts priced on system uptime guarantees.
Japan's PMDA has tightened software validation requirements for AI-assisted diagnostic algorithms embedded in PET and SPECT workstations. Manufacturers must now submit training dataset documentation and performance benchmarking against reference standards prior to market authorization. High-end hybrid imaging platforms with integrated lesion segmentation tools face the steepest compliance burden, with several vendors withdrawing economy-tier software modules rather than absorbing validation costs.
Consolidated hospital networks in Thailand and Indonesia are unbundling equipment procurement from radiopharmaceutical supply agreements, historically the anchor of vendor lock-in. Third-party logistics providers specializing in cold-chain isotope distribution are capturing margin previously retained by device manufacturers. This disintermediation is most visible in Bangkok's private hospital sector, where two radiopharmacy chains now service seven previously captive Siemens and GE installations.
Asia Pacific Nuclear Imaging Devices Market Segmentation
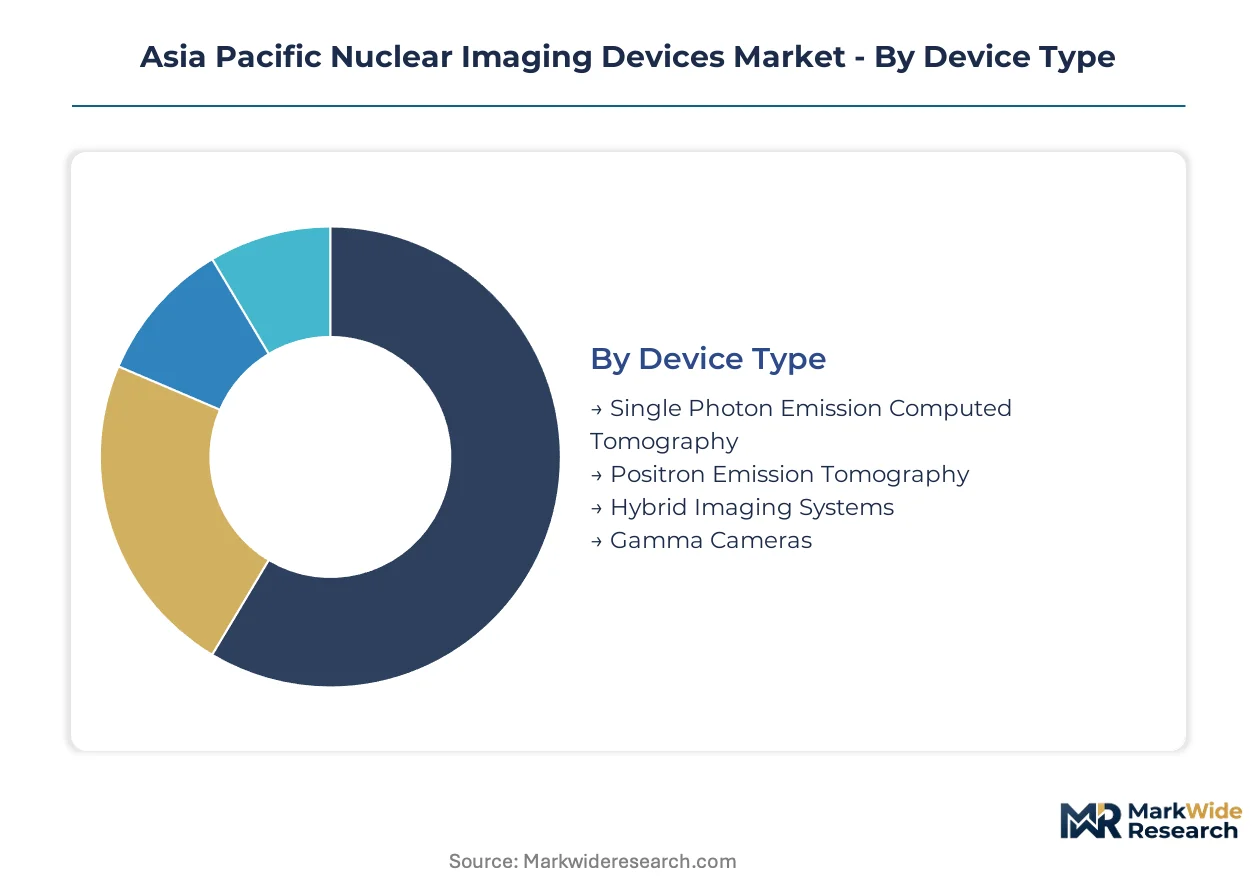
Segmentation in the Asia Pacific nuclear imaging devices market reveals distinct procurement patterns across hardware platforms, end-use settings, and software layers. Each dimension carries different margin profiles and localization pressures under divergent national regulatory frameworks.
Device Type:
Standalone SPECT and gamma camera systems serve cost-constrained facilities, while hybrid platforms demand integrated infrastructure investments across Japan's university hospitals and China's tier-one oncology centers.
- Single Photon Emission Computed Tomography:Analog photomultiplier tube configurations still dominate India's diagnostic imaging center installed base. Solid-state CZT detector retrofits are accelerating at China's metropolitan hospital networks where reimbursement favors quantitative perfusion analysis.
- Positron Emission Tomography:Time-of-flight architectures with lutetium-based scintillators command premium positioning in Japan's universal health insurance system. Australia's TGA fast-track pathway is compressing authorization timelines for novel detector geometries.
- Hybrid Imaging Systems:PET-CT installations concentrate in China's provincial cancer hospitals; PET-MRI remains restricted to greenfield construction given cryogenic infrastructure requirements.
- Gamma Cameras:Portable dual-head systems address Vietnam's underpenetrated provincial hospital network where shielded suite construction is impractical.
Volume placements concentrate in SPECT systems; the faster expansion belongs to hybrid imaging platforms.
End User:
Procurement authority is shifting from individual facilities toward consolidated purchasing networks, altering contract structures and service bundling requirements.
- Hospitals:Southeast Asia's multi-hospital networks are mandating decade-long service partnerships that bundle hardware, software updates, and predictive maintenance. Japan's revised reimbursement frameworks for hybrid imaging are accelerating capital deployment at university hospitals.
- Diagnostic Imaging Centers:India's metropolitan diagnostic chains are driving CZT detector adoption through volume-based procurement agreements with component suppliers near Bengaluru.
- Research Institutions:Australia's nuclear medicine technologist shortage constrains scanner utilization regardless of installed base expansion.
- Outpatient Clinics:Thailand's private hospital sector is unbundling equipment procurement from radiopharmaceutical supply agreements, enabling third-party logistics penetration.
Capital commitment intensity peaks at hospitals; outpatient clinics are gaining share fastest as service models fragment.
Technology:
Software and detector layers are decoupling from hardware platforms, enabling upgrade cycles independent of full system replacement.
- Radiopharmaceutical Systems:Technetium-99m generator supply chains face predictable shortages from scheduled maintenance at Australia's aging research reactor infrastructure.
- Digital Detectors:Solid-state cadmium-zinc-telluride arrays are unifying energy and spatial resolution performance. China's tier-one oncology centers are adopting these at replacement rates exceeding analog retirements by three-to-one.
- Imaging Algorithms:Iterative reconstruction methods are compressing scan times at Japan's PMDA-regulated facilities.
- Software Analytics:AI-assisted lesion segmentation tools command recurring licensing revenue streams that offset hardware margin compression in saturated Japanese and Australian markets.
Detector hardware dominates current procurement volumes; analytics software is climbing the fastest as vendors defend pricing against commoditization.
Application:
Clinical use cases determine isotope selection, scan protocol complexity, and reimbursement coding across national health systems.
- Oncology:FDG-PET staging protocols drive hybrid imaging demand at China's provincial cancer centers where FDG supply localization is accelerating under import substitution policies.
- Cardiology:Myocardial perfusion imaging with technetium-99m tracers remains the volume application across India's diagnostic imaging center network.
- Neurology:Amyloid-beta PET imaging faces restricted reimbursement in Japan's universal health insurance system, constraining adoption despite clinical validation.
- Infectious Diseases:Gallium-67 and labeled white blood cell scans serve tuberculosis and osteomyelitis diagnosis at Vietnam's underpenetrated provincial facilities.
Oncology commands the largest installed base; neurology applications are expanding most quickly as biomarker validation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Lucas Heights research reactor anchors the regional technetium-99m supply chain, creating radiopharmaceutical dependencies that cascade through Southeast Asian procurement networks. This isotope concentration shapes device utilization patterns and vendor contract structures across the Asia Pacific.
China
Provincial cancer hospitals in Beijing and Shanghai are driving PET-CT installations as FDG production localizes under NMPA import substitution mandates. The GB standards electromagnetic compliance testing regime requires in-country RF device validation, extending pre-market timelines. Yangtze River Delta oncology centers are replacing analog photomultiplier tubes with solid-state CZT detectors at rates exceeding three-to-one against system retirements.
Japan
University hospitals are accelerating capital deployment for PET-MRI platforms following METI reimbursement revisions that assign preferential procedure coding. PMDA software validation requirements for AI-assisted diagnostic algorithms have tightened, compelling manufacturers to submit training dataset documentation. Kanto region medical centers face the steepest compliance burden for integrated lesion segmentation tools.
India
Metropolitan diagnostic chains in Bengaluru and Hyderabad are procuring CZT detector components from newly established domestic foundries incentivized under the PLI scheme. CDSCO import licensing plus BIS quality certification creates dual-track approval timelines stretching 14-18 months. Maharashtra's hospital networks are consolidating purchasing power into multi-facility service contracts bundling hardware and predictive maintenance.
Vietnam
Ho Chi Minh City and Hanoi maintain SPECT scanner density below one unit per million population, creating first-mover positioning for vendors establishing local service depots. Provincial hospital networks lack shielded suite infrastructure, favoring portable dual-head gamma camera configurations. Cold-chain isotope distribution remains underdeveloped, constraining technetium-99m utilization rates.
Australia
TGA fast-track authorization for breakthrough detector materials and iterative reconstruction algorithms is compressing time-to-market for next-generation platforms. The national nuclear medicine technologist shortage—340 unfilled positions across public hospital networks—constrains scanner utilization regardless of installed base expansion. Lucas Heights reactor maintenance schedules create predictable isotope shortages that disrupt device scheduling nationwide.
Asia Pacific Nuclear Imaging Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital detector component localization and AI-native software modules. The vendor landscape concentrates around integrated imaging conglomerates with captive radiopharmaceutical logistics capabilities. Three archetypes dominate: full-platform manufacturers bundling hardware and isotope supply, component specialists supplying CZT detector arrays to regional assemblers, and software analytics vendors extracting recurring licensing from quantitative biomarker tools. Competitive positioning hinges on decade-long service partnerships versus transactional equipment sales, with predictive maintenance contracts displacing time-and-materials repair revenue.
Within the full-platform tier, Siemens Healthineers and GE Healthcare anchor long-term maintenance agreements with expanding hospital networks across Southeast Asia. Canon Medical Systems Corporation exemplifies the hybrid imaging specialist archetype, competing on digital detector integration. Among Asia-based manufacturers, Neusoft Medical Systems Co., Ltd. and Mindray Medical International occupy positions serving cost-constrained diagnostic imaging center segments with localized assembly strategies.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| Koninklijke Philips NV |
| GE Healthcare |
| Neusoft Medical Systems Co., Ltd. |
| Mindray Medical International |
| Fujifilm Holdings Corp. |
| Hitachi Healthcare |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
Hybrid-to-standalone system bifurcation drives divergent procurement economics across the Asia Pacific nuclear imaging landscape, with PET-MRI platforms commanding bundled decade-long service contracts while gamma camera transactions remain unbundled and price-sensitive. This tier divergence manifests in supply chain configurations where premium vendors anchor regional distribution centers for cryogenic infrastructure parts, while commodity SPECT suppliers ship directly from assembly plants without local inventory buffers.
Pricing Analysis
Warranty and service-bundling intensity separates pricing tiers decisively, with decade-long predictive maintenance agreements now standard for PET-CT and PET-MRI platforms across Southeast Asian hospital networks. Price differentiation hinges on detector technology tier—solid-state CZT arrays command 40-60% premiums over analog photomultiplier configurations—and regulatory certification burden under Japan's PMDA software validation requirements. Pricing pressure stems from hardware commoditization in saturated Japanese and Australian markets, compressing margins on standalone gamma cameras. Diagnostic imaging centers in India's metropolitan chains exhibit highest price sensitivity, while Japan's university hospitals prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Warehouse-distribution layer concentration centers on Singapore and Hong Kong as regional hubs for detector components and cryogenic spare parts, with secondary depots in Sydney and Mumbai serving national markets. Component sourcing draws from Japan for scintillator crystals, South Korea for semiconductor detector arrays, and Germany for precision mechanical subsystems. Raw material dependencies include lutetium oxyorthosilicate crystals, high-purity germanium for detector calibration, and liquid helium for MRI cryogenics. Single-source vulnerability concentrates in Australia's Lucas Heights reactor for technetium-99m parent isotope supply, with scheduled maintenance creating predictable radiopharmaceutical shortages. Distribution runs through authorized service depots for premium platforms and direct-to-facility logistics for portable gamma cameras.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific nuclear imaging market constitutes a vertical-integration race where radiopharmaceutical supply chain control and AI-native software development represent the decisive upstream and downstream levers. Players capturing both detector manufacturing and isotope logistics will dominate contract structures as hospital procurement consolidates.
For Market Incumbents: Anchor long-term service partnerships with expanding Southeast Asian hospital networks through predictive maintenance contracts priced on uptime guarantees rather than time-and-materials repairs. Defend against software analytics entrants by accelerating PMDA-compliant AI-assisted lesion segmentation validation, absorbing compliance costs that economy-tier competitors cannot sustain. Prioritize backward integration into CZT detector foundries near Bengaluru and Hyderabad to shorten lead times for India's PLI-incentivized domestic assembly. For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated provincial hospital network where SPECT scanner density remains below one unit per million population, establishing local service depots before incumbent logistics networks solidify. Target portable dual-head gamma camera configurations for facilities lacking shielded suite infrastructure, unbundling equipment from radiopharmaceutical supply to capture margin previously retained by full-platform vendors. Pursue Australia's TGA fast-track pathway for novel detector materials to compress authorization timelines against established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in software analytics specialists with FDA-cleared or PMDA-validated quantitative PET biomarker extraction tools, as recurring licensing revenue streams offset hardware margin compression in mature markets. Long-term viability favors targets with captive radiopharmaceutical logistics capabilities or exclusive cold-chain distribution partnerships. Monitor divergence between national localization mandates and actual component sourcing patterns as the primary inflection indicator for regional competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| CZT Detector Foundry Localization | PLI scheme incentives in India shorten SPECT assembly lead times for domestic diagnostic chains. |
| AI-Assisted Lesion Segmentation Validation | PMDA software requirements in Japan create compliance moats against economy-tier competitors. |
| Turnkey Service Contract Expansion | Southeast Asian hospital consolidation favors decade-long partnerships bundling hardware and predictive maintenance. |
| Radiopharmaceutical Logistics Integration | Third-party cold-chain specialists in Thailand capture margin from unbundled equipment procurement. |
| TGA Fast-Track Utilization | Australia's priority review pathway compresses time-to-revenue for novel detector geometries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, biomedical engineers, nuclear medicine technologists, and GPO contracts specialists across China, Japan, India, Australia, and Southeast Asia. Bottom-up triangulation combined installed base audits from hospital procurement databases with top-down validation against NMPA, PMDA, CDSCO, and TGA device registration records. Secondary sources encompassed radiopharmaceutical production reports from Australia's ANSTO, reimbursement coding updates from Japan's METI, and component import manifests from Indian customs authorities.
Granularity-level modeling distinguished hybrid imaging platforms from standalone SPECT and gamma camera systems at the country level, with further disaggregation by detector technology tier and end-user setting across the projection horizon. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and capital expenditure patterns at tier-one oncology centers. Industry-specific forecast inputs included technetium-99m generator supply schedules from research reactor maintenance calendars and PMDA software validation pipeline status for AI-native reconstruction algorithms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under radiopharmaceutical supply disruptions from extended reactor maintenance or accelerated localization mandates that fragment component sourcing networks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Contrast Media Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Mexico Digital X-Ray Devices Market