
 Behcets Disease Market | 2026-2036
Behcets Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Behcets Disease Market Analysis
Multi-source biologics procurement is rebalancing toward in-house manufacturing partnerships as developers seek supply security for complex therapies. AbbVie Inc. leverages its immunology infrastructure to sustain adalimumab positioning across autoimmune indications. Takeda Pharmaceutical Company Limited anchors its rare disease portfolio through biologics specialization in inflammatory conditions. Novartis AG differentiates via ophthalmology-aligned therapy development for ocular Behcet's manifestations.
Behcet's disease constitutes a chronic, relapsing vasculitis characterized by recurrent oral and genital ulcers, ocular inflammation, and systemic vascular involvement driven by HLA-B51 genetic association and neutrophil hyperactivity. Biologics command the highest value intensity within product type segmentation, while immunosuppressants retain volume leadership due to corticosteroid-sparing protocols in maintenance therapy. Hospital treatment settings concentrate acute flare management, whereas specialty pharmacy channels are capturing biologics dispensing as infusion-to-subcutaneous administration shifts accelerate.
FDA orphan drug designation and EMA protocol assistance shape clinical trial incentives and accelerated assessment pathways for novel Behcet's therapies. Japan's PMDA Sakigake designation and Turkey's national rare disease framework further influence regional development priorities and reimbursement access. Stakeholders must monitor biosimilar entry timelines and evolving payer evidence requirements for interleukin-1 and tumor necrosis factor inhibitor categories.
Market Dynamics
Biologics manufacturing complexity is forcing developers toward captive production networks as supply security overrides cost optimization in rare disease therapy deployment.
Growth Catalysts
- FDA orphan drug designation:Accelerated review timelines and tax incentives compress development cycles for novel interleukin inhibitors targeting mucocutaneous manifestations.
- Neutrophil-targeted monoclonal antibodies:Hospital infusion centers are expanding dedicated biologics suites to accommodate subcutaneous administration shifts in maintenance protocols.
- Turkey:The national rare disease framework mandates centralized referral pathways that concentrate diagnosed patient volumes into accredited treatment centers.
Market Restraints
- Plasma-derived protein input costs:Fractionation capacity constraints in European Union member states elevate raw material pricing volatility for antibody production.
- Single-source bioreactor dependency:Contract manufacturing organizations in Switzerland and Ireland control critical mammalian cell culture capacity for late-stage clinical supplies.
- EMA accelerated assessment limitations:Conditional marketing authorization requirements impose post-approval evidence generation burdens that extend payer negotiation timelines.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Priority review vouchers for first-in-class ophthalmic biologics enable nine-month regulatory assessment versus standard twelve-month cycles.
- Telemedicine-integrated specialty pharmacy:Remote therapeutic monitoring platforms are capturing biologics dispensing from traditional hospital outpatient departments.
- Pediatric indication expansion:Juvenile Behcet's cohorts remain underserved as adult-focused trial designs exclude adolescent pharmacokinetic requirements.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization for complex glycosylation patterns requires rare bioprocess engineering talent concentrated in Boston and Basel clusters.
- Multi-regional clinical trial harmonization:Divergent HLA-B51 prevalence stratification requirements between FDA and PMDA protocols fragment patient recruitment efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behcets Disease Market |
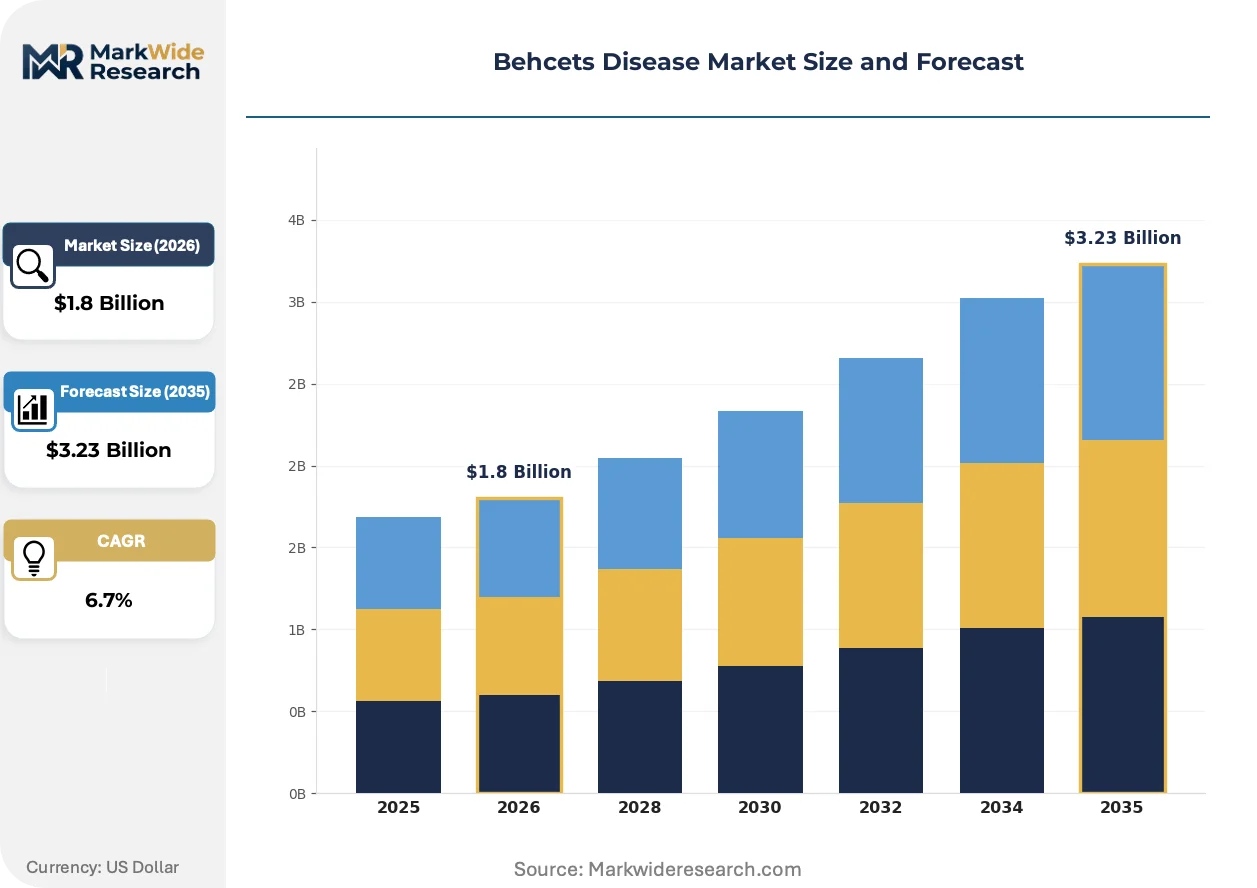
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Antimalarials Treatment Setting: Hospital, Outpatient Clinic, Home Care, Specialty Pharmacy Age Group: Pediatric, Adult, Geriatric, Young Adult Route of Administration: Oral, Injectable, Topical, Infusion |
| Companies Covered | AbbVie Inc., Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd., Johnson and Johnson, Amgen Inc., Eisai Co., Ltd., Takeda Pharmaceutical Company Limited, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behcets Disease Market Emerging Trajectories
Therapeutic development is pivoting toward precision targeting of neutrophil hyperactivity pathways while regulatory agencies converge on adaptive trial designs for small-population indications.
Subcutaneous interleukin-1 beta inhibitors are integrating into maintenance regimens as corticosteroid-sparing alternatives for mucocutaneous disease. Adult patients in United States hospital systems are transitioning from infusion centers to self-administration models within eighteen months of therapy initiation. This modality shift is compressing site-of-care costs while expanding patient eligibility for remote monitoring programs.
EMA protocol assistance and FDA breakthrough therapy designation are converging on streamlined evidence packages for ocular Behcet's indications. European sponsors are submitting integrated quality-efficacy-safety modules that reduce assessment cycles by four to six months. Biologics developers targeting posterior uveitis are prioritizing these pathways over standard marketing authorization applications.
Specialty pharmacy networks are capturing biologics dispensing from hospital outpatient departments as infusion-to-subcutaneous administration accelerates. United States payers are mandating white-bag distribution for maintenance-phase therapies, stripping margin from integrated delivery systems. This channel rotation is most visible in California and Texas markets where pharmacy benefit managers have consolidated regional formulary control.
Behcets Disease Market Segmentation
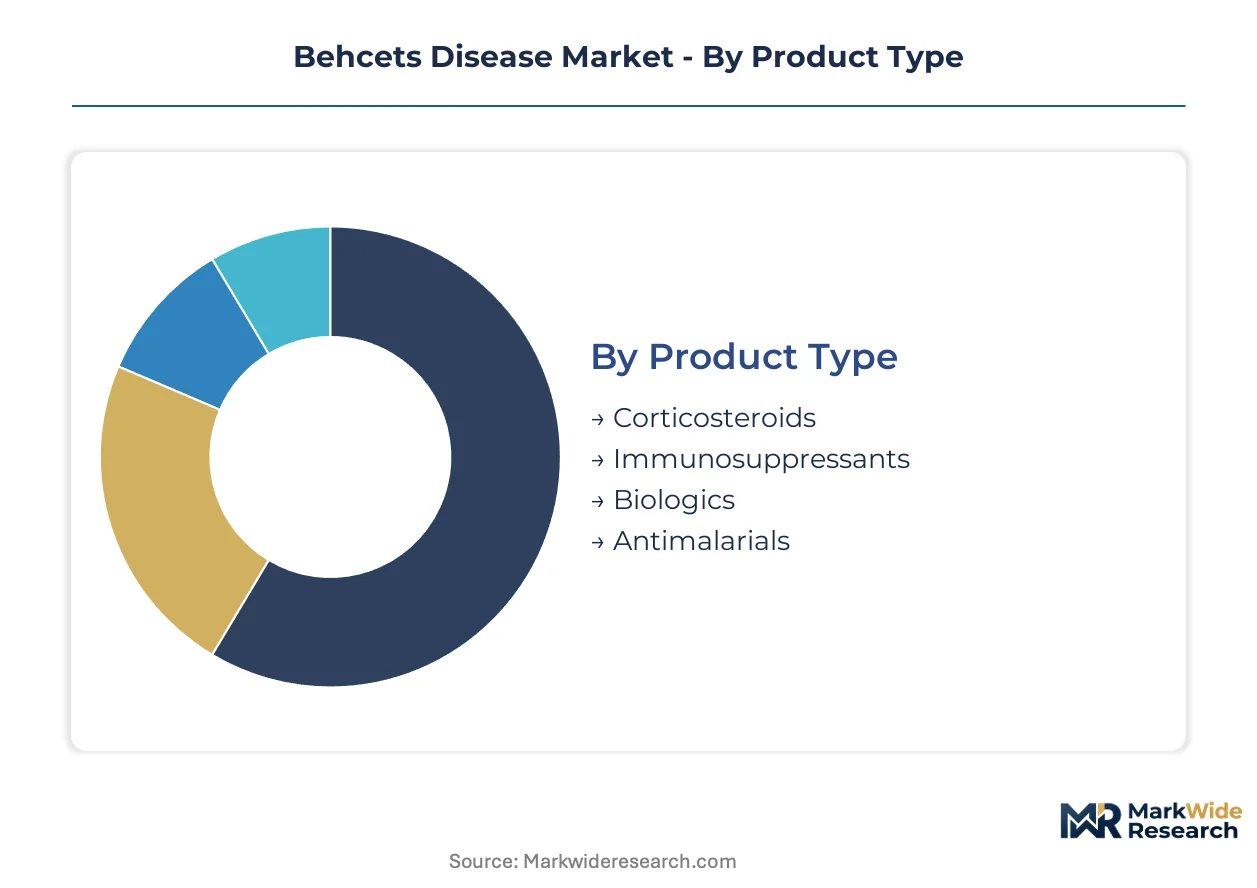
Behcet's disease therapy selection hinges on disease severity, organ system involvement, and corticosteroid-sparing requirements. Segmentation reveals how biologics command premium positioning while immunosuppressants anchor volume, with administration modality shifts reshaping site-of-care economics.
Product Type:
Physicians weigh efficacy-to-safety ratios against reimbursement tiers when selecting pharmacologic classes for mucocutaneous versus systemic manifestations.
- Biologics:Engineered monoclonal antibodies and fusion proteins targeting interleukin-1 beta, tumor necrosis factor-alpha, and interferon-alpha pathways. Hospital systems in the United States and Japan are expanding dedicated biologics suites to accommodate subcutaneous administration shifts that compress site-of-care costs.
- Immunosuppressants:Corticosteroid-sparing agents including azathioprine, cyclosporine, and colchicine that modulate T-cell activation and neutrophil chemotaxis. Turkey's national rare disease framework mandates these as first-line maintenance therapy in accredited treatment centers, sustaining volume leadership despite slower growth.
- Corticosteroids:Systemic and intralesional glucocorticoids for acute flare management.
- Antimalarials:Hydroxychloroquine for mild mucocutaneous disease with photoprotection benefits.
Volume sits with Immunosuppressants; growth tilts toward Biologics.
Treatment Setting:
Reimbursement channel control and administration complexity determine where therapy delivery concentrates across the patient journey.
- Hospital:Acute flare management requiring intravenous corticosteroid pulses, ophthalmologic emergency intervention, and vascular surgery consultation. Centers in Tokyo and Istanbul maintain dedicated vasculitis units that concentrate severe case volumes.
- Specialty Pharmacy:Biologics dispensing with cold-chain integrity, patient education, and remote therapeutic monitoring. United States pharmacy benefit managers in California and Texas markets have consolidated formulary control, stripping margin from integrated delivery systems.
- Outpatient Clinic:Routine disease monitoring and maintenance therapy adjustment.
- Home Care:Self-administered subcutaneous injections with telemedicine oversight.
Revenue concentrates in Specialty Pharmacy; patient volume remains in Hospital settings.
Age Group:
Pharmacokinetic differences and organ system involvement patterns drive pediatric protocol divergence from adult standards.
- Adult:Primary trial population with established dosing for interleukin inhibitors and anti-TNF agents. FDA orphan drug designation incentives have concentrated development here, leaving dosing extrapolation for younger cohorts.
- Pediatric:Juvenile Behcet's with higher parenchymal neuro-Behçet's risk and distinct HLA-B51 association patterns. EMA pediatric investigation plan requirements are forcing sponsors to include adolescent pharmacokinetic sub-studies in new drug applications.
- Young Adult:Transition-age patients with fertility preservation concerns.
- Geriatric:Age-related immunosenescence and cardiovascular comorbidity constraints.
Development investment clusters in Adult; unmet need is deepest in Pediatric.
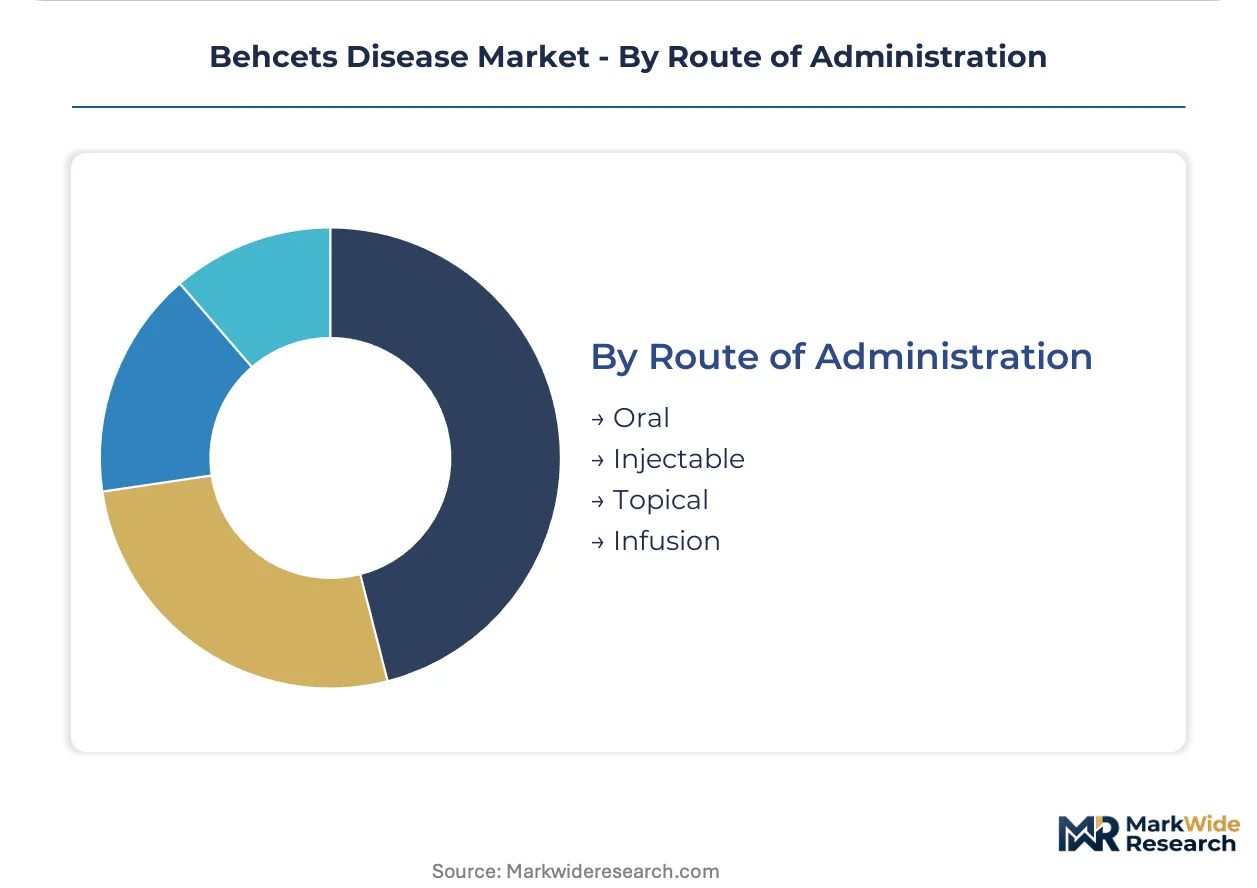
Route of Administration:
Patient self-efficacy and infusion center capacity constraints are accelerating modality migration toward patient-controlled delivery.
- Injectable:Subcutaneous interleukin-1 beta inhibitors and TNF antagonists enabling home administration. Adult patients in United States hospital systems transition from infusion centers to self-injection within eighteen months of therapy initiation.
- Infusion:Intravenous biologics and high-dose corticosteroid pulses for acute severe disease. Switzerland and Ireland-based contract manufacturing organizations control critical mammalian cell culture capacity for clinical supplies.
- Oral:Small-molecule immunosuppressants and corticosteroids for maintenance.
- Topical:Localized therapy for oral and genital ulcerations.
Infusion retains acute-case capture; Injectable gains share fastest in maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity in Ireland and Switzerland anchors biologics supply security for rare disease therapy deployment across developed markets.
United States
FDA orphan drug designation accelerates interleukin inhibitor development timelines for mucocutaneous manifestations. The Inflation Reduction Act shapes reimbursement negotiations for biologics in Medicare populations. Boston's bioprocess engineering cluster concentrates mammalian cell line development expertise for complex glycosylation optimization.
Japan
PMDA Sakigake designation compresses regulatory assessment to nine months for first-in-class ophthalmic biologics. The Ministry of Economy, Trade and Industry prioritizes domestic biologics manufacturing resilience. Tokyo maintains dedicated vasculitis units that concentrate severe Behcet's case volumes into accredited treatment centers.
Turkey
HLA-B51 genetic prevalence drives concentrated patient identification through centralized referral pathways. The national rare disease framework mandates immunosuppressants as first-line maintenance therapy in accredited centers. Istanbul anchors the Middle East treatment corridor for complex ocular and vascular manifestations.
Germany
EMA protocol assistance streamlines integrated quality-efficacy-safety module submissions for ocular indications. REACH compliance elevates raw material traceability requirements for plasma-derived protein inputs. The Basel-Zurich corridor controls critical contract manufacturing capacity for late-stage clinical biologics supplies.
Behcets Disease Market Vendor Landscape
Biologics manufacturing partnerships dominate the current landscape as developers secure captive production networks for complex antibody therapies. The market structures around three tiers: global immunology majors with established rare disease infrastructure, regional biologics specialists with ophthalmology alignment, and emerging neutrophil-targeted therapy developers. Portfolio diversification into corticosteroid-sparing maintenance protocols and geographic expansion into Turkey's centralized referral system represent the dominant competitive vectors.
Within the immunology-major tier, AbbVie Inc. and Novartis AG exemplify contrasting strategic positions. AbbVie leverages its established infrastructure across autoimmune indications to sustain adalimumab positioning. Novartis occupies a specialization vector through ophthalmology-aligned therapy development. Takeda Pharmaceutical Company Limited anchors the Asia-Pacific rare disease portfolio through biologics concentration in inflammatory conditions.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Johnson and Johnson |
| Amgen Inc. |
| Eisai Co., Ltd. |
| Takeda Pharmaceutical Company Limited |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Biologics-immunosuppressant tier divergence splits the Behcet's market into premium interleukin inhibitors and volume corticosteroid-sparing protocols, with each tier commanding distinct manufacturing footprints and reimbursement negotiations across United States, Japan, and Turkey.
Pricing Analysis
Service-bundling separates maintenance-phase subcutaneous biologics from acute hospital infusion protocols, with United States pharmacy benefit managers mandating white-bag distribution that strips integrated delivery system margins. Three-tier pricing structure across premium interleukin inhibitors, standard anti-TNF agents, and economy immunosuppressant maintenance anchors payer formulary design. Price differentiation hinges on FDA orphan drug exclusivity periods and EMA accelerated assessment pathways. Cost compression in the immunosuppressant tier intensifies as Turkey's national rare disease framework mandates centralized procurement. Hospital systems exhibit lowest price sensitivity due to bundled reimbursement; specialty pharmacies face margin pressure from consolidated formulary control.
Supply Chain Analysis
Reverse-logistics for temperature-sensitive biologics demands cold-chain integrity verification from specialty pharmacy networks back to manufacturer quality assurance units in Switzerland and Ireland. Mammalian cell culture capacity concentrates in the Basel-Zurich corridor and Boston clusters, with plasma fractionation drawing from Irish and Swiss fractionation facilities. Raw material dependencies span CHO cell lines, recombinant protein media, and single-use bioreactor components. Single-source contract manufacturing organization vulnerability elevates supply risk for late-stage clinical supplies. Distribution runs through hospital biologics suites for acute induction, shifting to specialty pharmacy direct-to-patient for maintenance self-administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behcet's disease therapy development is consolidating around biologics manufacturing expertise as plasma-derived input costs and regulatory evidence burdens force subscale developers toward partnership or exit.
For Market Incumbents: Cement captive production networks for mammalian cell culture capacity before biosimilar entry compresses interleukin-1 inhibitor margins. Secure EMA protocol assistance and FDA breakthrough therapy designation for ocular indication expansions to extend exclusivity windows against emerging neutrophil-targeted monoclonal antibody developers. For New Entrants and Emerging Players: Enter via pediatric pharmacokinetic studies that adult-focused trials have excluded, exploiting EMA pediatric investigation plan requirements as a regulatory wedge. Target Turkey's centralized referral system for rapid patient recruitment in HLA-B51 stratified protocols, leveraging the national rare disease framework for reimbursement anchoring. For Investors and Strategic Acquirers: Re-rating potential sits with bioprocess engineering specialists given cell line development expertise scarcity in Boston and Basel clusters. Long-term viability favors platforms with ophthalmology-aligned therapy pipelines and existing FDA orphan drug designation portfolios. Monitor PMDA Sakigake designation announcements for inflection signals in Japan's nine-month regulatory pathway.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive bioreactor capacity in Switzerland insulates against CMO single-source risk. |
| Regulatory Approval Pathway | EMA protocol assistance compresses ocular indication assessment cycles. |
| Pipeline Diversification | Neutrophil-targeted monoclonal antibodies address corticosteroid-sparing gaps. |
| Licensing Agreement | Japanese PMDA Sakigake partnerships accelerate ophthalmic biologics entry. |
| Clinical Trial Advancement | Pediatric pharmacokinetic sub-studies unlock EMA-compliant label expansion. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, formulary directors, hospital procurement managers, and payer access specialists. FDA orphan drug designation databases, EMA protocol assistance submissions, ClinicalTrials.gov records, and Turkey's national rare disease framework documentation provided validation anchors. Bottom-up patient volume modeling and top-down therapy value estimation were triangulated against manufacturer capacity disclosures.
Data-stream reconciliation across the analysis window integrated biologics adoption curves, immunosuppressant maintenance protocol persistence, and site-of-care shift velocities. Segmentation dimensions spanned product type, treatment setting, age group, and route of administration, with regional regulatory clusters modeled separately. CAGRs were derived from therapy value intensity trajectories and volume expansion patterns, incorporating PMDA Sakigake designation impact assumptions and biosimilar entry timeline sensitivities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA accelerated assessment rejection or plasma fractionation capacity constraints. Forecasts reflect documented assumptions regarding HLA-B51 prevalence stability and reimbursement tier consolidation. Practitioners should monitor PMDA designation announcements, biosimilar litigation timelines, and Turkish referral pathway expansion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Europe Rett Syndrome Market