
 Dental Diagnostic and Surgical Equipment Market | 2026-2036
Dental Diagnostic and Surgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Diagnostic and Surgical Equipment Market Intelligence
Consolidation among dental service organizations is realigning procurement patterns across North American dental clinics. Danaher Corporation leverages its diagnostics-to-treatment workflow integration to sustain loyalty among high-volume buyers. Dentsply Sirona anchors its position through chairside CAD/CAM ecosystems that dominate premium clinic fit-outs. Planmeca competes by controlling the Nordic imaging market and extending distribution into Central European teaching hospitals.
Dental diagnostic and surgical equipment encompasses electromechanical systems, ionizing and non-ionizing imaging platforms, and computer-navigated fabrication tools designed to detect oral pathology and execute precise hard- and soft-tissue interventions with submillimeter accuracy. The primary commercial purpose is to reduce diagnostic uncertainty and standardize surgical outcomes across outpatient and institutional settings. Imaging Systems generates the largest revenue pool due to replacement cycles triggered by digital radiography mandates, while CAD/CAM Systems represents the fastest-expanding segment as same-day prosthodontics reshapes clinic economics. Laser Technology occupies a narrower but higher-margin niche in periodontics, where tissue-selective ablation commands premium pricing.
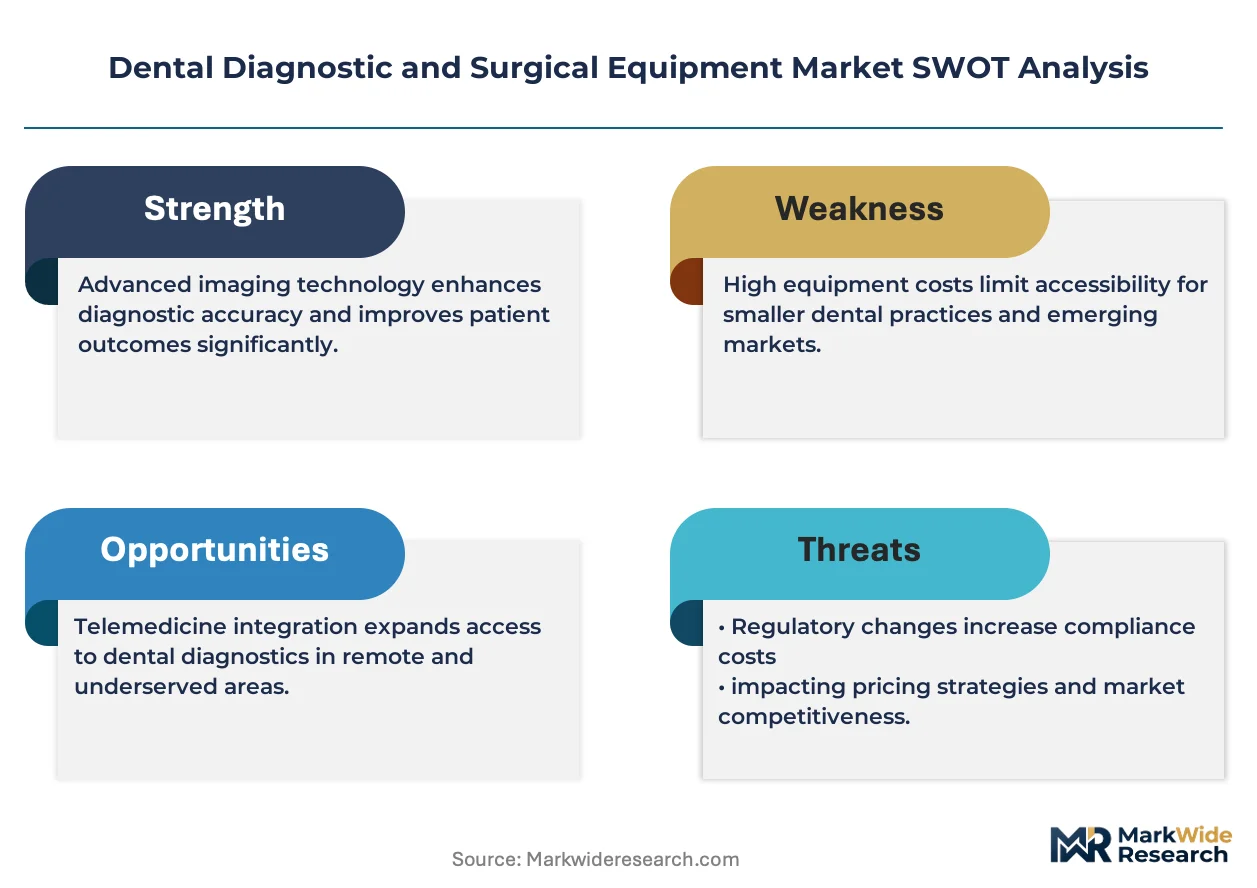
FDA 510(k) clearance timelines shape product launch cadences for US-bound manufacturers, while the EU MDR and CE marking requirements force redesigns of legacy surgical handpieces and imaging software. The EPA regulates dental amalgam separator efficiency, indirectly constraining equipment specifications for US clinic installations. Stakeholders must monitor how FDA artificial-intelligence guidance for radiological devices will reshape software-enabled imaging platforms before committing R&D budgets.
Market Dynamics
Digital radiography mandates in Germany, Japan, and Brazil are compressing replacement cycles for imaging systems while FDA 510(k) clearance pathways in the United States accelerate product launch cadences for software-enabled platforms.
Growth Catalysts
- EU MDR compliance deadlines:European dental clinics face mandatory equipment upgrades to meet revised CE marking requirements for surgical handpieces and imaging software, pulling forward capital expenditure timelines.
- Same-day prosthodontics:Chairside CAD/CAM fabrication is reducing laboratory outsourcing costs for high-volume dental service organizations, creating direct economic incentives for technology acquisition.
- Brazilian digital dentistry adoption:Private dental chains in São Paulo and Rio de Janeiro are replacing legacy film-based systems with cone-beam computed tomography platforms to capture premium patient segments.
Market Restraints
- Capital intensity barriers:Cone-beam CT units require six-figure dollar investments that constrain independent practitioners and slow penetration outside consolidated dental service organizations.
- Component supply concentration:Precision sensor arrays and ceramic milling burs depend on specialized German and Japanese suppliers, exposing manufacturers to input bottlenecks.
- EPA amalgam separator mandates:United States clinic installations must incorporate mercury capture systems that add compliance costs and equipment specification constraints.
Strategic Opportunities
- AI-enabled radiological devices:FDA draft guidance on machine-learning diagnostic tools creates regulatory runway for software vendors to embed automated pathology detection into imaging platforms.
- Peripheral European markets:Teaching hospitals in Poland, Hungary, and the Czech Republic show underpenetrated demand for integrated diagnostic-to-treatment workflows.
- Laser periodontics expansion:Tissue-selective ablation technology is converging with digital treatment planning software to capture premium pricing in aesthetic gum contouring procedures.
Industry Challenges
- Cross-functional talent scarcity:Clinical engineers capable of servicing both electromechanical systems and computer-navigated fabrication tools command wage premiums that strain service department margins.
- Legacy system integration friction:Digital scanning platforms must interface with decade-old practice management software, creating implementation delays and customization costs for mid-sized clinic networks.
- 510(k) clearance timeline variability:FDA artificial intelligence guidance uncertainty is forcing manufacturers to defer R&D commitments until submission pathways stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Diagnostic and Surgical Equipment Market |
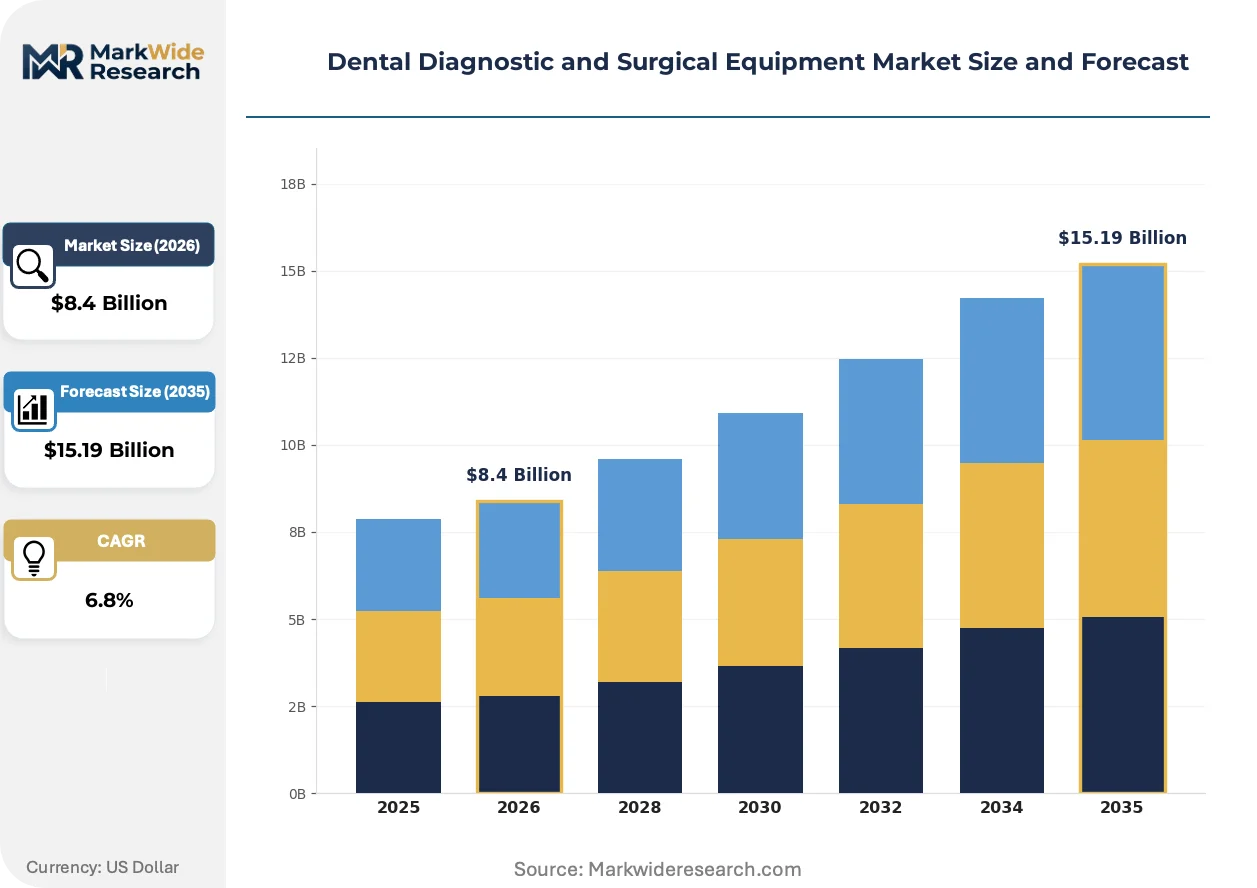
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Surgical Instruments, Dental Chairs, CAD/CAM Systems Technology: X-Ray, 3D Imaging, Laser Technology, Digital Scanning Application: Oral Surgery, Endodontics, Periodontics, Prosthodontics End User: Dental Clinics, Hospitals, Research Laboratories, Academic Institutions |
| Companies Covered | Danaher Corporation, Dentsply Sirona, Carestream Health, KaVo Kerr, Biolase Technologies, Envista Holdings Corporation, Planmeca, Ivoclar Vivadent AG, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Diagnostic and Surgical Equipment Market Strategic Shifts & Innovations
Workflow integration between diagnostic imaging and chairside fabrication is collapsing traditional laboratory intermediaries, while regulatory frameworks for software-enabled devices are rewriting product development priorities.
Intraoral scanning technology is electrifying the transition from physical impressions to digital models. Multisite dental service organizations in the United States are deploying scanners across hundreds of chairs within eighteen-month rollout windows. This compression is eliminating alginate material costs and enabling real-time collaboration with centralized design centers.
EU MDR technical documentation requirements are forcing redesigns of legacy surgical handpieces and imaging software architectures. Manufacturers must submit clinical evidence portfolios that extend clearance timelines by twelve to eighteen months. German and Nordic equipment vendors are absorbing these costs through premium positioning in teaching hospital segments where compliance credibility commands pricing power.
After-sales service unbundling is disrupting traditional equipment financing models. Large dental service organizations now negotiate separate maintenance contracts from capital purchases, pressuring vendors to demonstrate uptime guarantees. This bifurcation is most visible in United States metropolitan markets where procurement teams centralize vendor scorecarding across fifty-plus location networks.
Dental Diagnostic and Surgical Equipment Market Segmentation
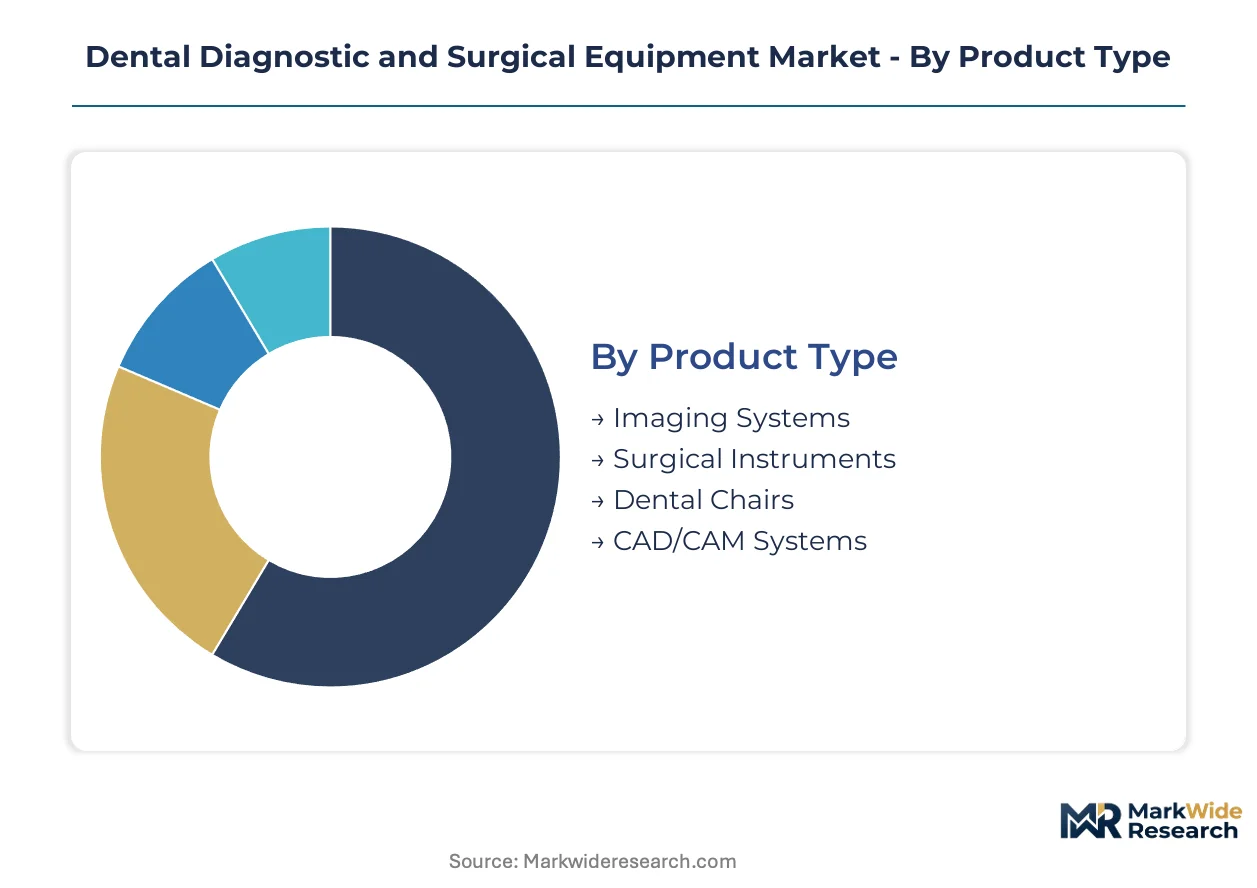
Equipment replacement cycles vary dramatically across dental practices, with digital mandates in Germany and Japan compressing imaging system turnover while CAD/CAM adoption reshapes prosthodontics economics. Segmentation reveals where capital concentrates and which technologies command premium positioning.
Product Type:
Replacement cycles for electromechanical systems accelerate where digital dentistry mandates force clinic infrastructure overhauls.
- Imaging Systems:Ionizing and non-ionizing radiography platforms, including cone-beam CT and panoramic units, dominate capital allocation. German dental clinics under EU MDR compliance deadlines are replacing legacy film-based systems with digital radiography suites, compressing typical replacement windows.
- CAD/CAM Systems:Chairside fabrication units integrate intraoral scanning with ceramic milling for same-day crown production. United States dental service organizations centralize procurement across multisite networks to capture laboratory cost savings, making this the segment gaining share fastest.
- Surgical Instruments:Electromechanical handpieces and implantology kits serve hard-tissue intervention workflows.
- Dental Chairs:Ergonomic patient positioning systems with integrated utility delivery anchor clinic fit-out specifications.
Volume placements concentrate in Imaging Systems; the faster expansion belongs to CAD/CAM Systems.
Technology:
Technology tiers separate premium diagnostic accuracy from cost-optimized screening capabilities.
- 3D Imaging:Cone-beam computed tomography delivers submillimeter volumetric reconstruction for implant planning and endodontic assessment. São Paulo private dental chains deploy these platforms to differentiate premium patient offerings, though six-figure unit costs limit penetration outside consolidated networks.
- Digital Scanning:Intraoral scanners capture optical impressions for restorative workflows. Japanese clinics replace alginate-based methods with real-time digital models, eliminating material costs and enabling centralized design center collaboration.
- X-Ray:Conventional 2D radiography persists in cost-sensitive screening applications.
- Laser Technology:Tissue-selective ablation systems command premium pricing in aesthetic periodontal procedures.
3D Imaging captures the highest unit values; Digital Scanning achieves the broadest clinic penetration.
Application:
Clinical specialization determines equipment specification intensity and service contract complexity.
- Prosthodontics:Restorative workflows demand integrated diagnostic-to-fabrication systems. Chairside CAD/CAM collapses traditional laboratory intermediaries, with United States dental service organizations deploying scanners across hundreds of chairs within compressed rollout windows.
- Oral Surgery:Implantology and extraction procedures require 3D imaging for surgical planning and navigation.
- Endodontics:Microscopic visualization and electronic apex location define equipment standards.
- Periodontics:Soft-tissue management increasingly incorporates laser technology for selective ablation.
Prosthodontics generates the densest equipment clusters; Oral Surgery drives the steepest imaging upgrade cycles.
End User:
Procurement centralization separates institutional buyers from fragmented independent practice purchasing.
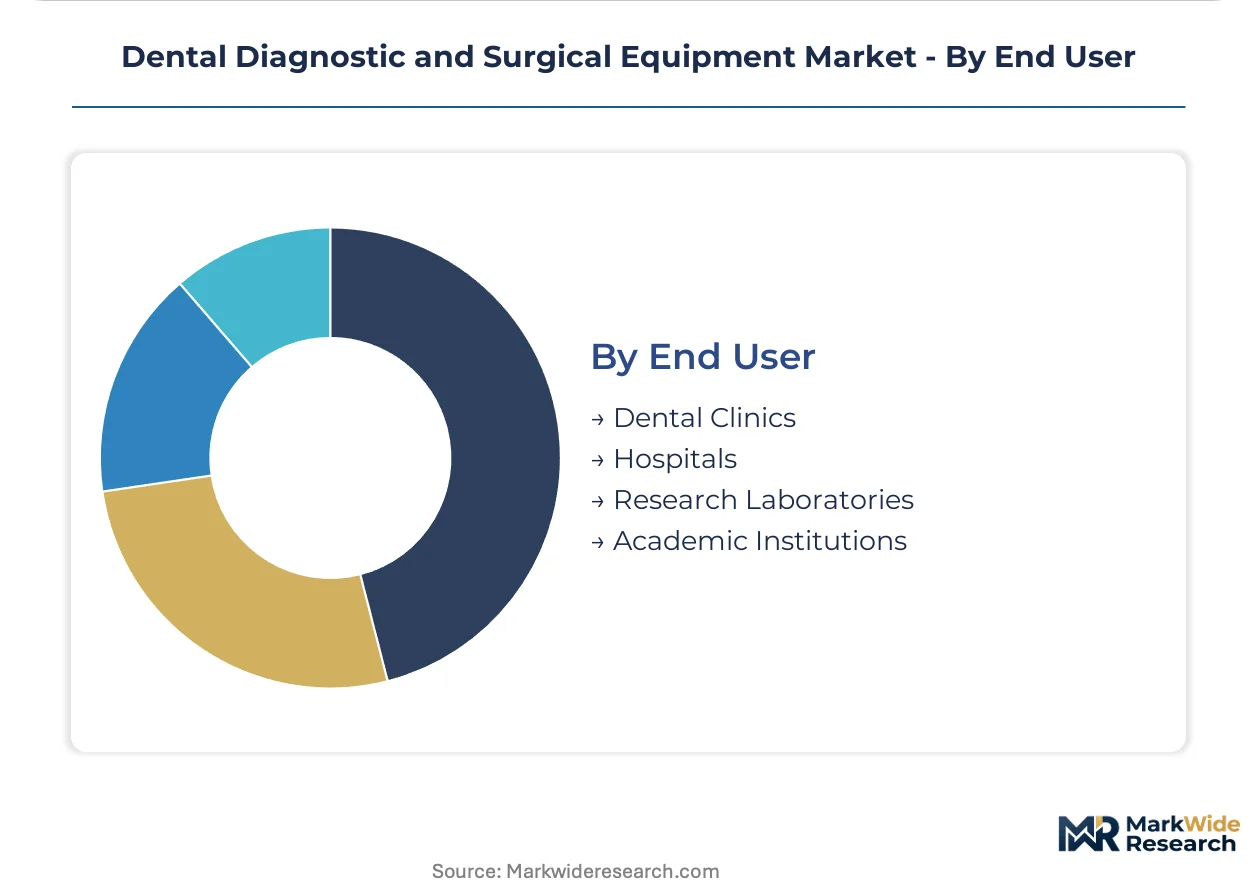
- Dental Clinics:Outpatient facilities range from single-chair independents to fifty-plus location networks. United States dental service organizations unbundle after-sales service from capital purchases, pressuring vendors for uptime guarantees across centralized vendor scorecards.
- Hospitals:Teaching institutions in Poland, Hungary, and the Czech Republic show underpenetrated demand for integrated diagnostic-to-treatment workflows, creating expansion opportunities for Nordic and German equipment vendors.
- Research Laboratories:Specialized facilities drive preclinical imaging and materials testing equipment specifications.
- Academic Institutions:Dental schools anchor training equipment placements with long replacement cycles.
Dental Clinics absorb the highest absolute unit volume; Hospitals present the most concentrated upgrade pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dental service organizations concentrate procurement power across multisite networks, while regulatory divergence across Germany, Japan, and Brazil creates distinct equipment replacement timelines. National imaging mandates and clearance pathways reshape capital deployment patterns in each market.
United States
Large dental service organizations centralize vendor scorecards across fifty-plus location networks, compressing equipment procurement cycles. FDA 510(k) clearance pathways accelerate software-enabled platform launches for manufacturers targeting outpatient clinics. Metropolitan markets in Texas and Florida show densest concentration of cone-beam CT installations serving implantology workflows.
Germany
EU MDR compliance deadlines force clinic infrastructure overhauls, pulling forward capital expenditure for surgical handpieces and imaging software. CE marking requirements under revised medical device regulations extend technical documentation timelines. Teaching hospitals in Bavaria and North Rhine-Westphalia absorb premium equipment from Nordic and domestic vendors seeking compliance credibility.
Japan
Digital radiography mandates eliminate legacy film-based systems, triggering replacement waves across metropolitan dental clinics. METI standards for medical device software interoperability shape procurement specifications for integrated diagnostic platforms. Tokyo and Osaka dental chains deploy intraoral scanners across hundreds of chairs within compressed rollout windows.
Brazil
Private dental chains in São Paulo and Rio de Janeiro replace legacy systems with cone-beam computed tomography platforms to capture premium patient segments. ANVISA device registration requirements govern import pathways for European and North American equipment manufacturers. Southeastern state networks show fastest digital dentistry adoption outside consolidated dental service organization structures.
Dental Diagnostic and Surgical Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-enabled imaging niches and service unbundling models. The market structures around diagnostics-to-treatment workflow integration, with premium positioning anchored in chairside fabrication ecosystems and imaging software architectures. Strategic archetypes include integrated workflow vendors, regional imaging specialists, and laser technology niche players. Dominant competitive moves encompass M&A for digital dentistry capabilities and geographic expansion into underpenetrated Central European teaching hospitals.
Among North American and European equipment manufacturers, Danaher Corporation, Dentsply Sirona, and Planmeca occupy positions across distinct competitive vectors. Danaher Corporation exemplifies the integrated diagnostics-to-treatment archetype through workflow loyalty programs targeting high-volume buyers. Dentsply Sirona anchors the premium chairside fabrication tier with CAD/CAM ecosystem dominance in clinic fit-outs. Planmeca represents the regional imaging specialist model, controlling Nordic markets while extending distribution into Central European institutional segments.
| Leading Market Players |
|---|
| Danaher Corporation |
| Dentsply Sirona |
| Carestream Health |
| KaVo Kerr |
| Biolase Technologies |
| Envista Holdings Corporation |
| Planmeca |
| Ivoclar Vivadent AG |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-cleared imaging platforms and CE-marked surgical handpieces splits pricing power across Atlantic supply corridors, with premium tiers tethered to German sensor arrays and mid-market positioning anchored in Asian component sourcing. This bifurcation concentrates margin capture among vendors controlling both regulatory credentials and precision manufacturing inputs.
Pricing Analysis
Volume placements concentrate in mid-tier digital radiography suites while margin extraction clusters in chairside CAD/CAM ecosystems bundling intraoral scanners with ceramic milling units. Price differentiation rests on FDA 510(k) clearance tier and EU MDR technical documentation depth, with premium positioning commanding multiples over standard CE-marked alternatives. Pricing pressure stems from dental service organization procurement centralization demanding unbundled service contracts and uptime guarantees. Independent practitioners exhibit highest price sensitivity, constraining penetration of six-figure cone-beam CT units outside consolidated networks.
Supply Chain Analysis
Direct-to-clinic distribution channels handle hyperscale demand from United States dental service organizations, while regional distributors serve fragmented European and Latin American markets. Precision sensor arrays draw from German and Japanese suppliers, ceramic milling burs rest on specialized Austrian and Swiss tooling, and electromechanical handpiece motors anchor in Chinese manufacturing. Single-source vulnerability concentrates in CMOS detector substrates and rare-earth doped laser crystals. Distribution runs through authorized service networks requiring factory-trained biomedical engineers for installation and calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races now center on captive control over precision imaging sensors and chairside fabrication workflows, with backward integration into ceramic milling burs and optical calibration standards emerging as decisive margin levers.
For Market Incumbents: Lock in dental service organization loyalty through integrated diagnostics-to-treatment workflow subscriptions bundling hardware, software, and predictive maintenance. Acquire specialized German sensor suppliers to secure CMOS detector supply against Japanese competitor consolidation. Defend against AI-enabled radiology entrants by embedding automated pathology detection into existing imaging platforms before FDA guidance stabilizes. For New Entrants and Emerging Players: Direct-to-specialist digital channels targeting independent periodontists offer lowest competitive density for laser technology penetration. Peripheral European teaching hospitals in Poland and Hungary present underpenetrated demand for integrated diagnostic-to-fabrication systems. Pursue software-only entry through FDA 510(k) predicated clearance for AI-enabled radiological devices, avoiding capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated workflow vendors seeking chairside fabrication capabilities or AI-enabled imaging software. Long-term viability favors targets with established FDA 510(k) portfolios and recurring service revenue streams exceeding thirty percent of total sales. Monitor FDA artificial intelligence guidance finalization as inflection signal for software-enabled platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Software-enabled imaging platforms require FDA validation before United States commercial deployment. |
| EU MDR Technical Documentation | Extended CE marking timelines force twelve-to-eighteen month redesign cycles for surgical handpieces. |
| Dental Service Organization Partnership | Centralized procurement across fifty-plus location networks compresses vendor selection criteria. |
| Chairside CAD/CAM Integration | Same-day crown production collapses laboratory intermediaries and captures recurring consumables revenue. |
| AI-Enabled Radiological Software | Automated pathology detection embedded in cone-beam CT platforms commands premium positioning. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with dental clinic procurement directors, biomedical equipment engineers, GPO contracts managers, and regulatory affairs specialists at imaging device manufacturers. FDA 510(k) submission databases, EU MDR notified body documentation, and ANVISA registration records provided clearance timeline validation. Primary fieldwork with dental service organization executives and teaching hospital purchasing committees cross-checked capital expenditure intentions against secondary shipment data. Bottom-up equipment placement counts triangulated against top-down market value estimates across the analysis window.
Product-level granularity modeled imaging systems, CAD/CAM systems, surgical instruments, and laser technology separately, with technology tiers disaggregated by 3D imaging, digital scanning, and X-ray modalities. End-user segmentation distinguished dental clinics by practice size, hospitals by teaching versus community status, and research laboratories by preclinical versus materials testing focus. CAGRs derived from replacement cycle analysis calibrated to digital radiography mandate timelines in Germany, Japan, and Brazil, cross-referenced against dental service organization expansion trajectories in United States metropolitan markets.
The model holds under stable FDA artificial intelligence guidance and unchanged EU MDR compliance deadlines; deviation in regulatory timeline acceleration or tariff imposition on German sensor imports would shift equipment procurement patterns. Forecasts reflect documented assumptions regarding dental clinic consolidation velocity and software-enabled platform adoption curves. Periodic stress-testing of base assumptions against actual dental service organization capex disclosures is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental CAM Milling Machine Market