
 Brazil Dental Equipment Market | 2026-2036
Brazil Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Dental Equipment Market Outlook
Preventive maintenance contracts and software-enabled service layers is consolidating recurring revenue streams around capital equipment. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to anchor premium positioning across Brazilian metropolitan markets. Institut Straumann AG sustains implant-focused R&D intensity that differentiates its portfolio in the prosthodontics segment. Henry Schein Inc. competes through distribution scale and channel control, extending logistics reach into mid-sized cities beyond São Paulo and Rio de Janeiro.
Dental equipment encompasses mechanical, electronic, and imaging apparatus designed for oral diagnosis, treatment, and surgical intervention, typically operating at rotational speeds exceeding 300,000 RPM for high-speed handpieces and requiring autoclave sterilization compatibility at 134°C saturated steam. These systems serve commercial dental practices, hospitals, and training institutions by enabling restorative procedures, orthodontic alignment, and implant placement with measurable clinical outcomes. Imaging systems command substantial margin pools as practitioners replace legacy panoramic units with cone-beam computed tomography platforms integrating three-dimensional reconstruction. CAD/CAM technology leads growth velocity within digital dentistry as chairside milling reduces laboratory turnaround from weeks to hours. Handpieces represent a mature, replacement-driven category where sterilization protocols and ergonomic design determine purchase cycles.
ANVISA governs medical device registration, classification, and post-market surveillance for dental equipment commercialized in Brazil, requiring in-country testing and quality system documentation that extends market entry timelines for foreign manufacturers. The Brazilian Health Regulatory Agency's alignment with Mercosur harmonization protocols shapes import pathways and technical conformity assessment procedures for multinational suppliers. ANVISA's evolving software-as-medical-device guidance will increasingly determine regulatory obligations for AI-enabled imaging analysis and connected chairside systems. Stakeholders must monitor pending resolution on tele-dentistry reimbursement codes and their downstream effect on remote diagnostic equipment procurement.
Market Dynamics
ANVISA's evolving software-as-medical-device guidance is compressing registration timelines for AI-enabled imaging systems while forcing foreign manufacturers to establish in-country quality infrastructure. This regulatory pivot is concentrating procurement authority among distributors capable of navigating technical conformity assessment and post-market surveillance obligations.
Growth Catalysts
- ANVISA Mercosur Harmonization:Alignment with regional technical standards reduces redundant testing for manufacturers holding Argentine or Paraguayan registrations, accelerating cross-border equipment flows into Brazilian port facilities.
- CAD/CAM Chairside Milling:Prosthodontics practices in São Paulo and Curitiba are replacing laboratory-dependent workflows with same-day crown production, compressing patient turnaround and elevating capital equipment budgets.
- Private Clinic Consolidation:Dental franchise networks across southeastern states are standardizing equipment procurement through centralized buying cooperatives, creating volume pull for integrated imaging and milling platforms.
Market Restraints
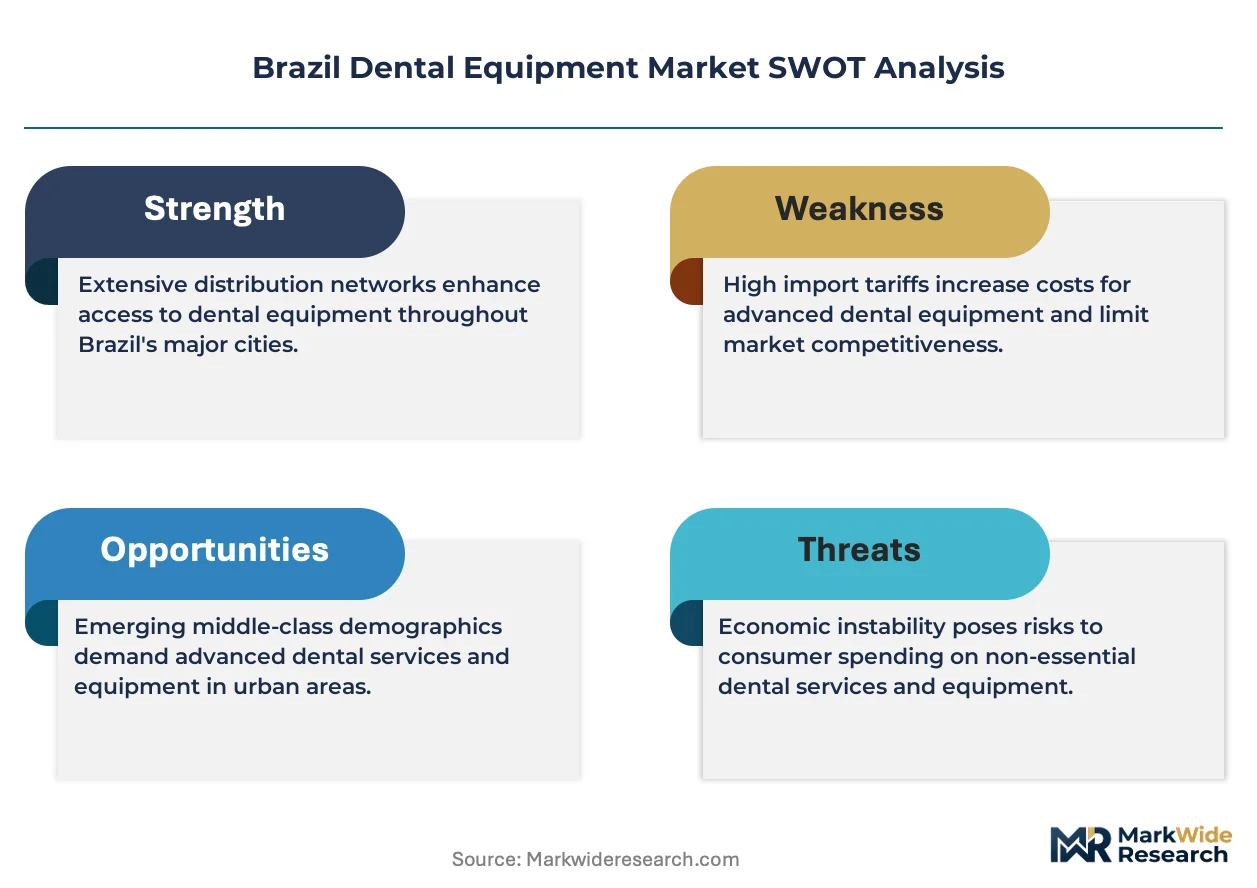
- Import Duty Structure:Industrialized goods taxation on electronic imaging components elevates landed costs for CBCT systems, constraining penetration outside metropolitan reimbursement zones.
- Single-Source Sterilization Supply:Autoclave-compatible handpiece manufacturers depend on concentrated German and Japanese bearing suppliers, exposing replacement part availability to currency volatility and maritime logistics congestion.
- ANVISA Registration Timeline:In-country testing requirements extend market entry by 18-24 months for novel laser dentistry platforms, freezing early-mover advantage for domestic assemblers with established quality system documentation.
Strategic Opportunities
- Northeastern State Penetration:Bahia and Pernambuco exhibit dentist-to-population ratios below national averages, creating whitespace for portable radiography and tele-dentistry diagnostic kits as reimbursement codes formalize.
- Preventive Maintenance Contracts:Equipment vendors are unbundling service layers from capital sales, converting handpiece and imaging system upkeep into recurring revenue streams with 85-90% renewal rates.
- AI-Enabled Imaging Analysis:Machine learning algorithms for caries detection and implant planning are converging with cloud-based PACS infrastructure, enabling subscription monetization beyond hardware margins.
Industry Challenges
- Digital Dentistry Skill Gap:Chairside CAD/CAM operation requires cross-training between clinical and technical staff, with only three specialized institutes in São Paulo offering certified programs at sufficient scale.
- Legacy Analog Integration:Practices upgrading from film-based radiography face workflow reconfiguration costs and staff retraining timelines that delay full digital platform adoption by 12-18 months.
- Software Validation Burden:ANVISA's pending guidance on software-as-medical-device classification is forcing manufacturers to rebuild quality management systems around IEC 62304 documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Dental Equipment Market |
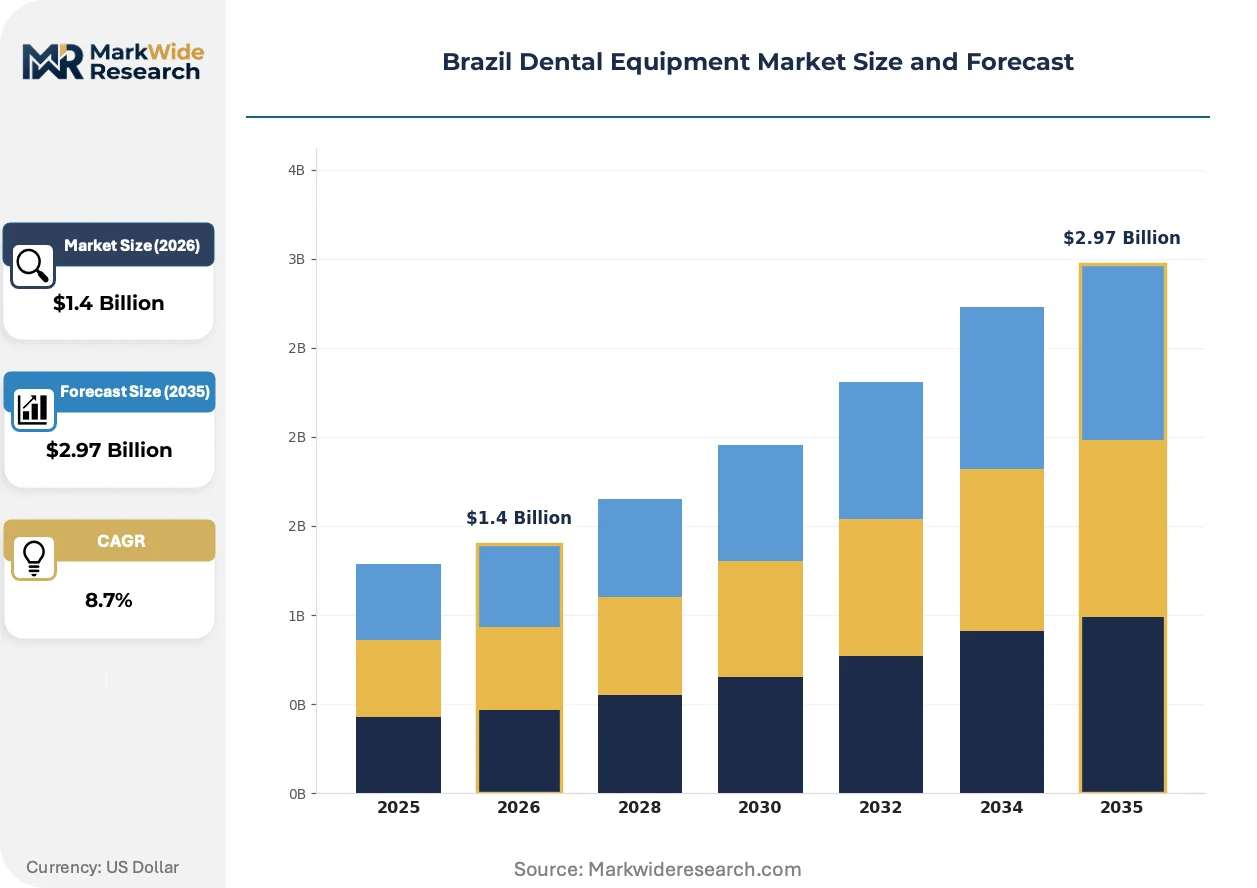
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handpieces, Imaging Systems, Sterilization Equipment, Patient Monitoring Devices End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Technology: Digital Dentistry, CAD/CAM, Laser Dentistry, 3D Printing Application: Orthodontics, Operative Dentistry, Periodontics, Prosthodontics |
| Companies Covered | Angelus Indústria de Produtos Odontológicos S/A, Henry Schein Inc., Dentsply Sirona, EDLO, Maquira, Institut Straumann AG, ZimVie Inc., Implacil De Bortoli, S.I.N. Implant System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Dental Equipment Market Strategic Shifts
Digital dentistry workflows are compressing the boundary between clinical diagnosis and laboratory fabrication, with cloud-connected equipment platforms enabling real-time case collaboration between practitioners and remote milling centers. This integration is reshaping capital allocation priorities across Brazilian dental practices.
Cone-beam computed tomography systems are converging with three-dimensional implant planning software to enable navigated surgical placement with sub-millimeter accuracy. Oral surgery groups in Rio de Janeiro and Belo Horizonte are adopting these platforms at accelerating pace, compressing the traditional referral pathway between general practitioners and specialists while elevating equipment specification requirements for multi-chair facilities.
ANVISA's alignment with Mercosur harmonization protocols is streamlining technical conformity assessment for multinational suppliers holding Argentine registrations. This regulatory convergence reduces redundant in-country testing for imaging systems and sterilization equipment, though post-market surveillance obligations still require established Brazilian legal representation. Foreign manufacturers are responding by partnering with domestic distributors possessing ANVISA-certified quality infrastructure.
Subscription-based equipment access models are displacing outright purchase arrangements among mid-sized practices in Brasília and Porto Alegre. Leasing structures bundle maintenance, software updates, and consumable replenishment into predictable monthly obligations, reducing capital intensity barriers for digital dentistry adoption. This financing innovation is most visible among prosthodontics-focused practices seeking to preserve liquidity for marketing and facility expansion.
Brazil Dental Equipment Market Segmentation
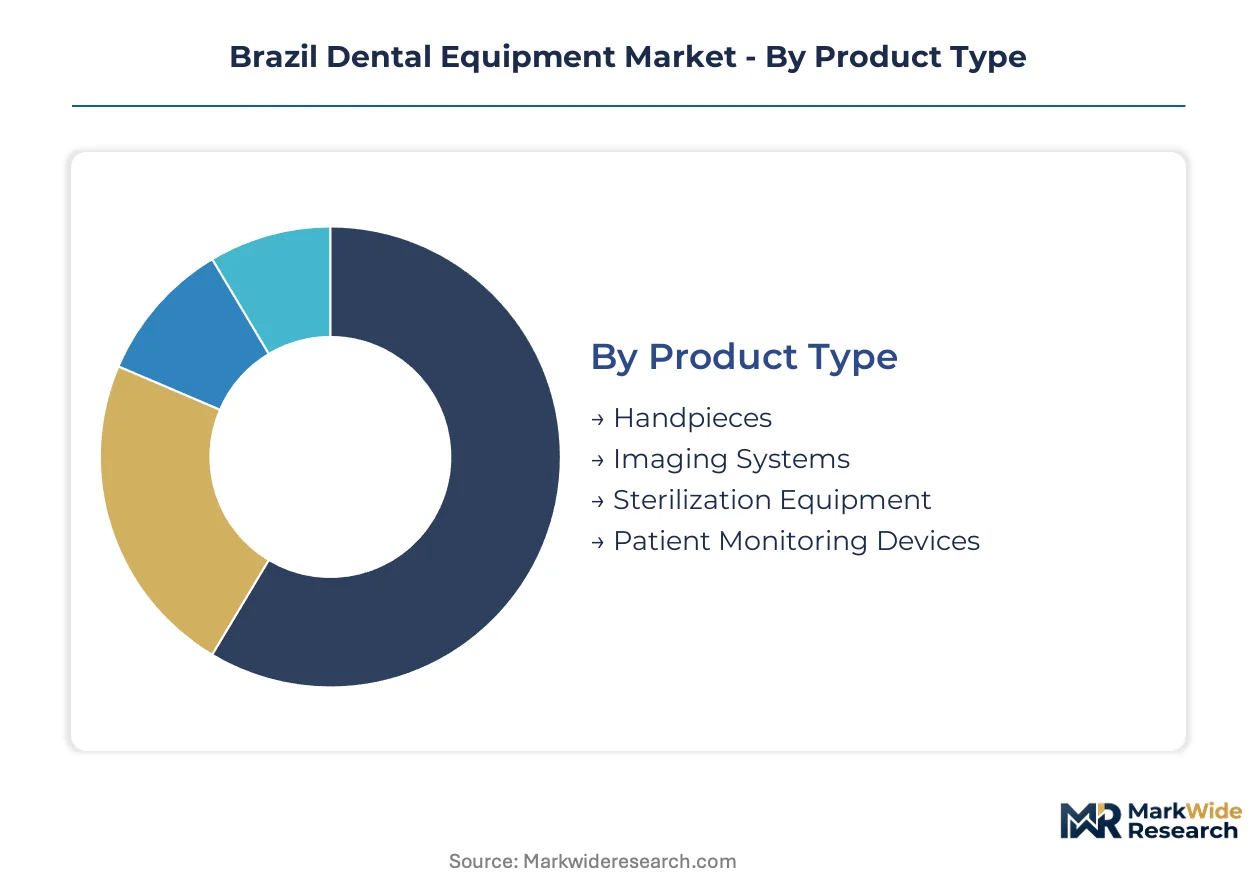
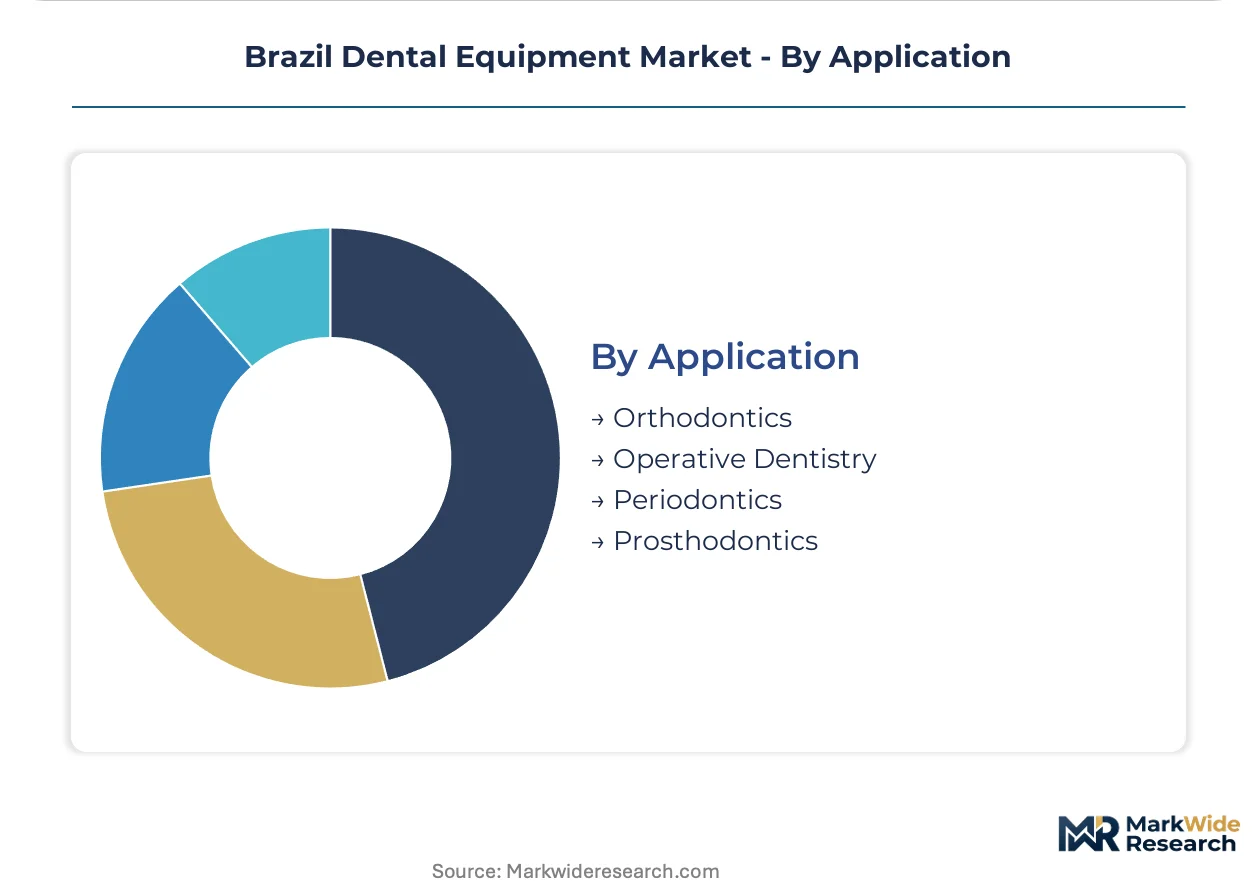
Dental equipment segmentation in Brazil reflects divergent integration pathways: some categories function as standalone capital purchases while others embed within connected digital workflows. Understanding these structural boundaries clarifies where procurement authority concentrates and how vendors configure bundled offerings.
Product Type:
Integration depth varies sharply across this category, with some equipment operating as isolated mechanical devices and others serving as nodes within networked clinical platforms.
- Imaging Systems:Cone-beam computed tomography platforms generate three-dimensional reconstructions with sub-millimeter resolution, serving as the data foundation for implant planning and orthodontic analysis. Demand clusters in São Paulo and Rio de Janeiro surgical centers replacing legacy panoramic units, constrained by elevated landed costs from industrialized goods taxation on electronic components.
- Handpieces:High-speed turbines operate at rotational speeds exceeding 300,000 RPM, requiring autoclave sterilization compatibility at 134°C saturated steam. Replacement cycles dominate procurement in mid-sized cities beyond southeastern hubs, with Brazilian practitioners prioritizing ergonomic grip designs that reduce operator fatigue during extended procedures.
- Sterilization Equipment:Autoclave systems and instrument washers maintain infection control protocols across multi-chair facilities.
- Patient Monitoring Devices:Pulse oximetry and capnography units support sedation dentistry workflows in hospital-affiliated practices.
Handpieces lead volumes today; imaging systems are gaining share fastest.
End User:
Customer type determines capital intensity thresholds and purchasing coordination mechanisms across Brazilian dental care delivery.
- Dental Clinics:Private practices in São Paulo and Curitiba drive CAD/CAM chairside adoption, consolidating procurement through franchise buying cooperatives that standardize equipment specifications across network locations.
- Hospitals:Tertiary care centers in Belo Horizonte and Porto Alegre integrate dental units within broader surgical suites, requiring interoperability with hospital information systems and centralized sterilization departments.
- Research Laboratories:Academic dental schools in São Paulo state maintain equipment fleets for clinical training and biomaterials investigation.
- Educational Institutions:Technical institutes across southeastern states supply pre-clinical simulation units for workforce development programs.
Dental clinics anchor current revenue; hospitals are expanding equipment budgets most rapidly.
Technology:
Technology maturity curves separate proven platforms from emerging modalities still navigating ANVISA registration pathways.
- CAD/CAM:Chairside milling systems compress crown production from laboratory-dependent weeks to same-day delivery, with São Paulo prosthodontics practices leading adoption amid workforce training investments at specialized institutes.
- Digital Dentistry:Cloud-connected platforms enable real-time case collaboration between practitioners and remote milling centers, reshaping capital allocation priorities across Brazilian practices.
- Laser Dentistry:Soft and hard tissue lasers face extended ANVISA registration timelines due to in-country testing requirements.
- 3D Printing:Photopolymer and metal sintering systems produce surgical guides and provisional restorations with accelerating precision.
Digital dentistry platforms command the steepest expansion trajectory; CAD/CAM maintains the largest installed base.
Application:
Clinical specialty boundaries determine equipment specification requirements and reimbursement environment stability.
- Prosthodontics:Implant placement and restoration workflows demand integrated imaging, planning software, and surgical navigation systems, with oral surgery groups in Rio de Janeiro adopting these platforms at accelerating pace.
- Orthodontics:Clear aligner production and bracket placement planning rely on intraoral scanning and three-dimensional cephalometric analysis.
- Operative Dentistry:Restorative procedures utilize high-speed handpieces and curing light systems with established replacement cycles.
- Periodontics:Soft tissue management and regenerative procedures require specialized ultrasonic scalers and surgical instrumentation.
Prosthodontics generates the highest equipment revenue per practitioner; orthodontics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates dental equipment demand more heavily than Argentina, where import restrictions and currency instability constrain capital investment in clinical infrastructure. The Brazilian market's regional fragmentation reflects uneven dentist density and reimbursement geography across its federated states.
São Paulo
Prosthodontics practices in São Paulo and Curitiba drive CAD/CAM chairside adoption, with franchise networks consolidating procurement through centralized buying cooperatives. ANVISA registration requirements shape import pathways for multinational suppliers entering through Santos port facilities. The metropolitan corridor anchors premium equipment demand as practitioners upgrade from analog to connected digital platforms.
Minas Gerais
Belo Horizonte's tertiary care centers integrate dental units within broader surgical suites, requiring interoperability with hospital information systems. ANVISA Mercosur harmonization protocols streamline technical conformity assessment for Argentine-registered imaging systems. Oral surgery groups across the state adopt cone-beam computed tomography platforms at accelerating pace.
Rio de Janeiro
Multi-chair facilities in Rio de Janeiro elevate equipment specifications to support navigated surgical placement with sub-millimeter accuracy. Post-market surveillance obligations require established Brazilian legal representation for foreign manufacturers. The city's dental schools maintain equipment fleets for clinical training and biomaterials investigation.
Rio Grande do Sul
Porto Alegre practices utilize subscription-based equipment access models that bundle maintenance and software updates into predictable monthly obligations. Industrialized goods taxation on electronic imaging components elevates landed costs for CBCT systems. Mid-sized practices in the state preserve liquidity for marketing through leasing structures rather than outright purchase.
Bahia
Dentist-to-population ratios in Bahia and Pernambuco sit below national averages, creating whitespace for portable radiography and tele-dentistry diagnostic kits. Pending resolution on tele-dentistry reimbursement codes will determine procurement timelines for remote diagnostic equipment. Salvador's emerging dental service networks represent early-stage demand for entry-level imaging systems.
Brazil Dental Equipment Market Competitive Environment
Top-tier vendors anchor premium positioning through integrated CAD/CAM ecosystems, while mid-tier distributors compete on logistics reach into secondary cities. The market exhibits tiered concentration with foreign manufacturers partnering domestic distributors possessing ANVISA-certified quality infrastructure. Two strategic archetypes dominate: integrated platform vendors bundling hardware with software subscriptions, and scale distributors controlling channel access across Brazil's federated states. Competitive moves center on preventive maintenance contract unbundling and northeastern state penetration through tele-dentistry diagnostic kits.
Within the integrated platform tier, Dentsply Sirona and Institut Straumann AG represent archetypes of premium positioning through connected equipment ecosystems. Henry Schein Inc. occupies a position among scale-driven distributors extending logistics reach beyond São Paulo and Rio de Janeiro metropolitan cores. These three entities exemplify the structural divide between technology-anchored vendors and channel-controlling distributors shaping procurement authority across Brazilian dental markets.
| Leading Market Players |
|---|
| Angelus Indústria de Produtos Odontológicos S/A |
| Henry Schein Inc. |
| Dentsply Sirona |
| EDLO |
| Maquira |
| Institut Straumann AG |
| ZimVie Inc. |
| Implacil De Bortoli |
| S.I.N. Implant System |
| Others |
Value Chain & Pricing Dynamics
Captive supply of precision bearings from German and Japanese manufacturers anchors both the supply position and pricing power for high-speed handpiece producers serving Brazilian dental clinics. This backward integration choice by original equipment manufacturers concentrates margin capture at the component tier while exposing finished goods pricing to currency volatility and maritime logistics congestion.
Pricing Analysis
Capacity additions in domestic assembly facilities are reshaping price floors for entry-level imaging systems as local producers exploit ANVISA registration advantages. Three-tier pricing structure across premium, standard, and economy levels separates integrated CAD/CAM platforms from standalone panoramic units and basic film-based alternatives. Cost compression in the economy tier is intensifying because import duty structures elevate landed costs for electronic imaging components. Solo practitioners in northeastern states exhibit highest price sensitivity, while franchise networks in São Paulo demonstrate lowest sensitivity due to centralized procurement scale.
Supply Chain Analysis
Single-source vulnerability sits with concentrated German and Japanese bearing suppliers that feed high-speed handpiece manufacturing lines. Component sourcing draws from China for electronic imaging sensors, Germany for precision mechanical assemblies, and Japan for ceramic bearings and turbine cartridges. Tariff exposure runs through industrialized goods taxation on CBCT electronic components that elevates landed costs at Brazilian port facilities. Distribution runs through São Paulo-based distributors possessing ANVISA-certified quality infrastructure that extends logistics reach into mid-sized cities beyond southeastern hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil dental equipment functions as a stable compounder where CAD/CAM workflow penetration drives steady replacement cycles and recurring service revenue. ANVISA regulatory alignment with Mercosur protocols reinforces predictable import pathways for multinational suppliers.
For Market Incumbents: Anticipate margin compression from domestic assemblers exploiting faster registration timelines by deepening backward integration into precision component supply. Prioritize certification investment at specialized São Paulo training institutes to lock in clinician loyalty and create switching costs for rival platforms. Channel control through preventive maintenance contract bundling represents the critical defensive lever against emerging leasing-based entrants. For New Entrants and Emerging Players: Mid-sized practices in Bahia and Pernambuco present the most penetrable buyer archetype given dentist-to-population ratios below national averages and limited incumbent service presence. Tele-dentistry diagnostic kits offer a white-space entry point pending formalization of reimbursement codes. A direct sales model bypassing São Paulo distributor markups enables price positioning against premium-tier imports while preserving margin for localized technical support investment. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks because ANVISA quality infrastructure requirements create barriers to organic entry and reward scale in post-market surveillance compliance. Target acquisition archetypes include mid-tier distributors with established legal representation and certified warehousing in secondary cities. Watch for inflection signals in tele-dentistry reimbursement code resolution that would unlock portable diagnostic equipment procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Quality Infrastructure Investment | Certified warehousing and legal representation accelerates market entry for foreign manufacturers through Santos port facilities. |
| CAD/CAM Training Institute Partnership | Collaboration with São Paulo specialized institutes builds clinician certification dependency and platform switching costs. |
| Preventive Maintenance Contract Unbundling | Recurring service revenue streams with high renewal rates convert capital sales into predictable subscription economics. |
| Tele-Dentistry Diagnostic Kit Development | Portable radiography platforms address whitespace in Bahia and Pernambuco pending reimbursement code formalization. |
| Leasing Structure Introduction | Subscription-based equipment access reduces capital intensity barriers for mid-sized practices in Brasília and Porto Alegre. |
Study Parameters
Coverage spans southeastern states, northeastern expansion zones, and southern regional markets, with primary inputs from each federated region. Primary interviews engaged dental equipment distributors, clinic franchise procurement directors, ANVISA regulatory consultants, biomedical engineers at tertiary hospitals, and GPO contracts managers. Secondary validation drew from ANVISA registration databases, Mercosur technical harmonization protocols, hospital procurement records, and customs import documentation. Bottom-up equipment shipment analysis triangulated against top-down dental practice census data and capital expenditure surveys.
Rate-of-change decomposition across the projection horizon separates volume expansion from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include product type, end user category, technology maturity curve, and clinical application specialty. CAGRs were derived from equipment replacement cycle analysis and digital workflow penetration curves. Forecast inputs incorporated ANVISA registration timeline assumptions and CAD/CAM training institute capacity expansion plans.
Underlying measurement precision varies by segment; imaging systems and CAD/CAM platforms carry tighter precision than handpiece replacement cycles due to more visible import documentation. Forecasts reflect documented assumptions regarding reimbursement code evolution and Mercosur harmonization implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
France Dental Equipment Market