
 Refurbished Dental Lab Equipment Market | 2026-2036
Refurbished Dental Lab Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Dental Lab Equipment Market Outlook
European refurbishment specialists is hardening quality benchmarks for recertified CAD/CAM systems and laboratory furnaces. Henry Schein leverages its distribution network to sustain refurbishment throughput across North American dental service organizations. KaVo Dental anchors its competitive position through specialized remanufacturing protocols for high-speed handpiece integration units. Patterson Companies Inc. competes by controlling secondary-market sourcing channels that feed its certified pre-owned equipment pipeline.
Refurbished dental lab equipment comprises previously owned mechanical, digital, and thermal systems restored to manufacturer-specified performance parameters including tolerance thresholds of 0.02 mm for milling units and ISO-certified biocompatibility for patient-contact surfaces, serving cost-constrained dental laboratories seeking clinical-grade output without capital-intensive procurement. CAD/CAM systems dominate refurbishment value pools due to rapid obsolescence cycles in digital scanning hardware that compress secondary-market depreciation curves. Dental chairs occupy mature refurbishment segments where standardized pneumatic and hydraulic components enable predictable remanufacturing economics. 3D printing units represent the fastest-growing technology category as resin-based and powder-bed systems enter secondary channels following initial wave adoption in developed markets.
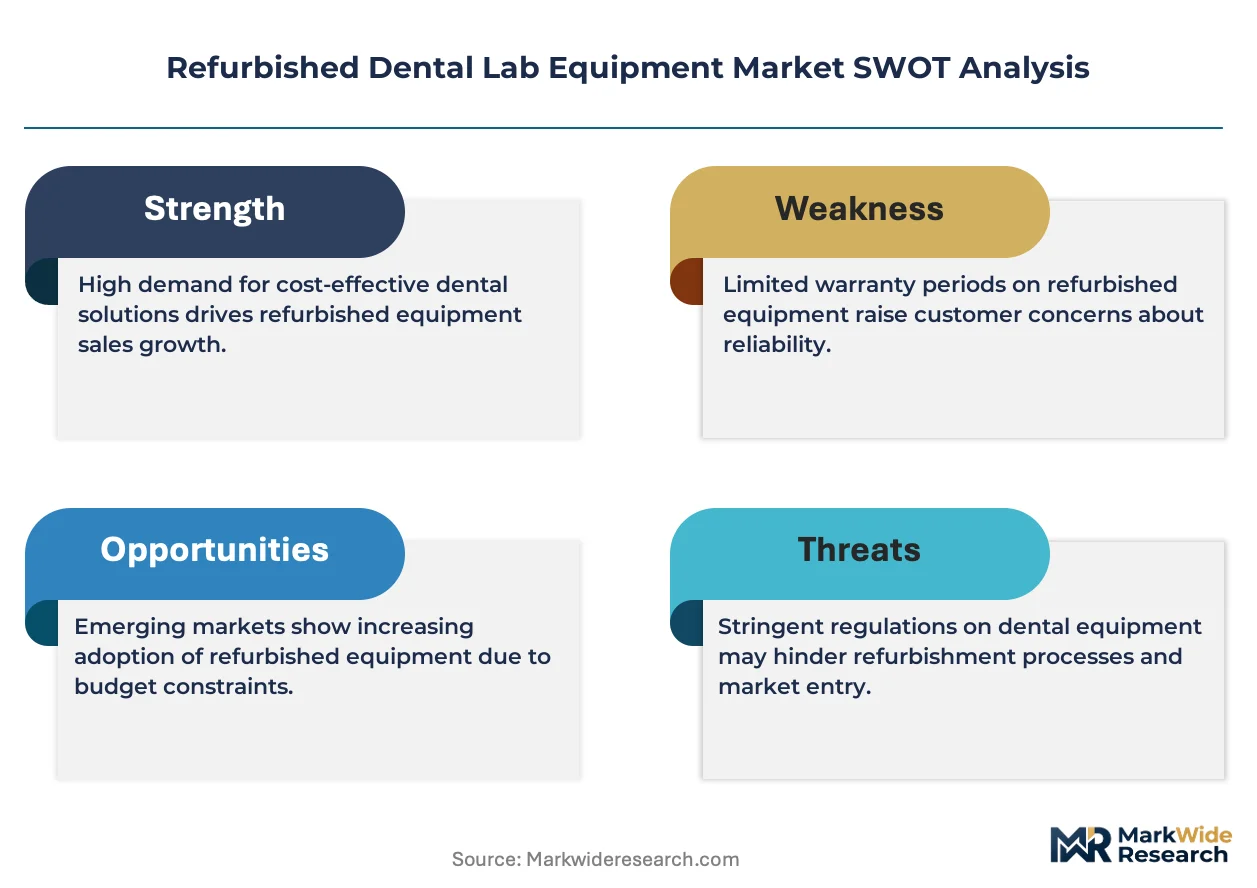
The FDA's 510(k) clearance framework for refurbished medical devices governs recertification pathways in the United States, while the EU Medical Device Regulation imposes conformity assessment obligations on European refurbishment operations. BIS certification requirements in India create compliance thresholds that filter informal refurbishment activity toward organized service providers. Stakeholders must monitor evolving notified-body interpretations of remanufacturing scope under MDR Article 23 as regulators distinguish refurbishment from substantial re-engineering.
Market Dynamics
Capital discipline among dental service organizations is compressing new-equipment procurement cycles and redirecting demand toward certified pre-owned channels, particularly for digital fabrication systems where obsolescence outpaces depreciation.
Growth Catalysts
- India's BIS certification framework:Organized refurbishment providers gain market share as compliance thresholds filter informal operators, accelerating consolidation toward certified channels in Mumbai and Delhi dental laboratory clusters.
- CAD/CAM obsolescence compression:Rapid hardware refresh cycles in intraoral scanning and milling units shorten secondary-market holding periods, expanding inventory velocity for refurbishment specialists.
- Dental service organization expansion:Multi-site clinic networks in the United States standardize on refurbished equipment fleets to preserve capital for chair-side technology investments.
Market Restraints
- Component supply concentration:Precision spindle assemblies and optical sensors for milling units concentrate among German and Japanese original equipment manufacturers, creating refurbishment input bottlenecks.
- FDA 510(k) pathway friction:Recertification documentation requirements for refurbished medical devices extend time-to-market for United States-bound equipment, compressing margin windows.
- Resin material substitution:Next-generation ceramic blocks and hybrid composites for chair-side milling reduce demand for legacy refurbishment of metal-based crown fabrication systems.
Strategic Opportunities
- Brazil's ANVISA pathway development:Formalized refurbishment regulations under South America's largest dental market create first-mover advantage for certified pre-owned equipment pipelines serving São Paulo laboratory networks.
- AI-assisted predictive maintenance:Machine learning diagnostics for handpiece turbine wear and furnace heating element degradation enable outcome-based service contracts alongside equipment sales.
- 3D printer resin convergence:Secondary-market powder-bed and vat-polymerization systems from initial adoption waves in Germany and Japan enter refurbishment channels as dental laboratories upgrade to multi-material platforms.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system assessors for dental device refurbishment concentrate in Western Europe and the United States, creating certification backlogs for Asia-Pacific operators.
- Legacy software integration:Proprietary CAD/CAM file formats from discontinued scanner generations require emulation layers or hardware bridging, complicating multi-vendor laboratory workflows.
- Biocompatibility re-verification:Patient-contact surface recertification under ISO 10993 demands destructive testing protocols that consume refurbished unit inventory and extend fulfillment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Dental Lab Equipment Market |
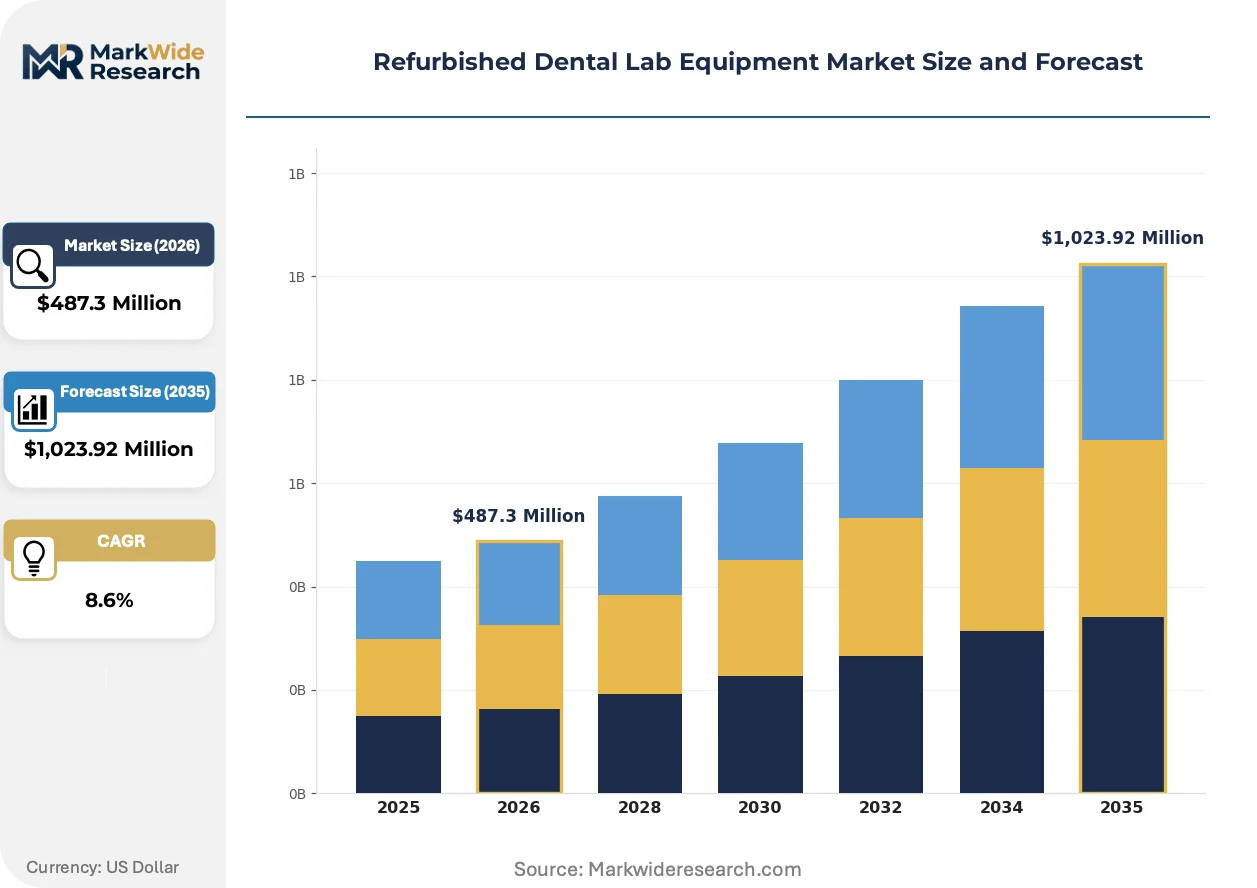
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Chairs, CAD/CAM Systems, Impression Units, Laboratory Furnaces Technology: 3D Printing, Digital Impressions, Laser Sintering, Ultrasonic Cleaning End User: Dental Clinics, Laboratories, Universities, Research Institutions Application: Prosthodontics, Orthodontics, Periodontics, Restoration |
| Companies Covered | Dentsply Sirona, Henry Schein, Patterson Companies Inc., KaVo Dental, GC Corporation, Ivoclar Vivadent, Carestream Dental, A-dec Inc., Dental Equipment Liquidators, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Dental Lab Equipment Market Strategic Shifts
Digital dentistry infrastructure is fragmenting across hardware generations, forcing refurbishment specialists to develop modular upgrade architectures that bridge legacy mechanical systems with contemporary software ecosystems.
Intraoral scanning hardware is converging with cloud-based treatment planning platforms, enabling dental laboratories to source refurbished scanner units while subscribing to current-generation software stacks. Mid-sized laboratories in Spain and Italy adopt this hybrid procurement model to avoid full-platform replacement costs. The convergence is compressing the functional obsolescence of scanning hardware independent of mechanical wear.
EU Medical Device Regulation Article 23 interpretations are hardening distinctions between refurbishment and remanufacturing, requiring notified-body involvement for equipment with replaced critical components. German and French refurbishment specialists invest in regulatory affairs capabilities to navigate conformity assessment variations across national competent authorities. Dental furnace and sterilizer categories face the most stringent reclassification risk under evolving guidance documents.
Subscription-based equipment access is displacing outright ownership among United Kingdom dental laboratories facing post-Brexit capital constraints. Refurbishment providers respond with bundled service offerings that include preventive maintenance and component replacement guarantees. The model concentrates demand in London and Manchester metropolitan laboratory networks where equipment utilization rates support recurring revenue structures.
Refurbished Dental Lab Equipment Market Segmentation
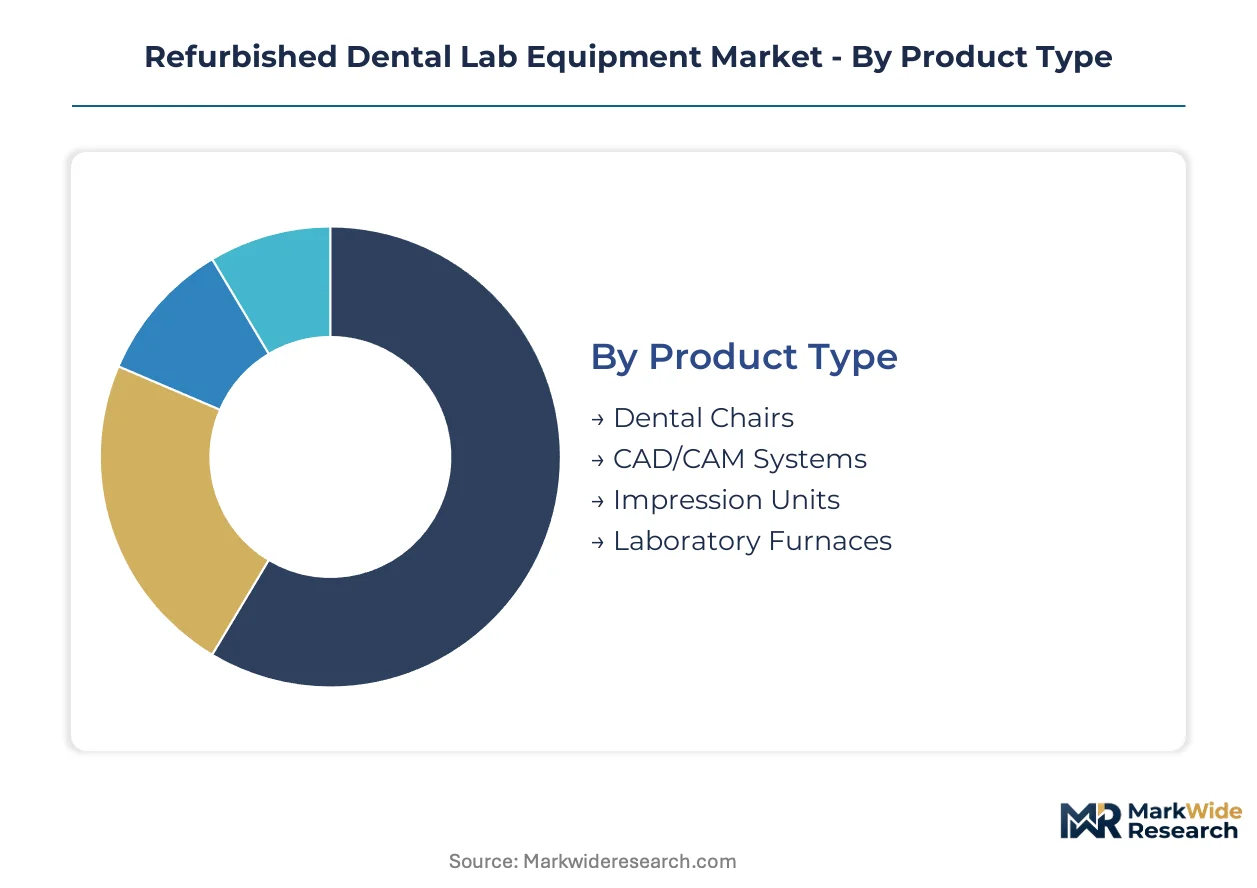
Refurbished dental lab equipment procurement patterns diverge sharply across product generations and end-use workflows. Upgrade cycle timing and capital availability determine which segments absorb secondary-market inventory fastest.
Product Type:
Hardware replacement cycles compress refurbishment demand differently across mechanical, digital, and thermal equipment categories.
- CAD/CAM Systems:Milling units and intraoral scanners with 0.02 mm tolerance thresholds dominate refurbishment value pools. Demand concentrates in Mumbai and Delhi dental laboratory clusters where BIS certification requirements filter informal operators toward organized channels.
- Dental Chairs:Pneumatic and hydraulic component standardization enables predictable remanufacturing economics. United States dental service organizations standardize on certified pre-owned fleets to preserve capital for chair-side technology investments.
- Impression Units:Traditional elastomeric mixing systems serve cost-constrained laboratories in secondary cities.
- Laboratory Furnaces:Zirconia sintering and porcelain firing units face stringent EU MDR Article 23 reclassification risk under evolving notified-body guidance.
Volume placements concentrate in dental chairs; the faster expansion belongs to CAD/CAM systems.
Technology:
Digital fabrication methods reshape which refurbished platforms retain clinical utility across software generations.
- 3D Printing:Resin-based vat-polymerization and powder-bed systems from initial adoption waves in Germany and Japan enter secondary channels. Dental laboratories upgrade to multi-material platforms, releasing single-resin units for refurbishment.
- Digital Impressions:Cloud-based treatment planning convergence compresses functional obsolescence of scanning hardware independent of mechanical wear. Spanish and Italian mid-sized laboratories adopt hybrid procurement models pairing refurbished scanners with current-generation software subscriptions.
- Laser Sintering:Metal powder systems for cobalt-chrome frameworks serve specialized prosthodontic applications.
- Ultrasonic Cleaning:Tank-based and benchtop units occupy mature refurbishment segments with standardized piezoelectric transducer replacement protocols.
Placement density runs highest through digital impressions; steepest expansion trajectory belongs to 3D printing.
End User:
Capital discipline and utilization rates determine which customer categories prioritize certified pre-owned channels over new-equipment procurement.
- Dental Clinics:Cost-sensitive single and multi-site operators scale digital fabrication capacity without new-equipment premiums. India's cost-sensitive dental clinics drive concentrated demand for refurbished milling units and scanners.
- Laboratories:Independent and commercial labs balance output quality against equipment depreciation schedules. United Kingdom laboratories facing post-Brexit capital constraints increasingly favor subscription-based equipment access with bundled maintenance guarantees.
- Universities:Training programs require functional but non-current-generation platforms for student instruction.
- Research Institutions:Experimental workflows utilize refurbished systems for protocol development before capital commitment.
Procurement volume clusters in dental clinics; research institutions expand most quickly as experimental adoption broadens.
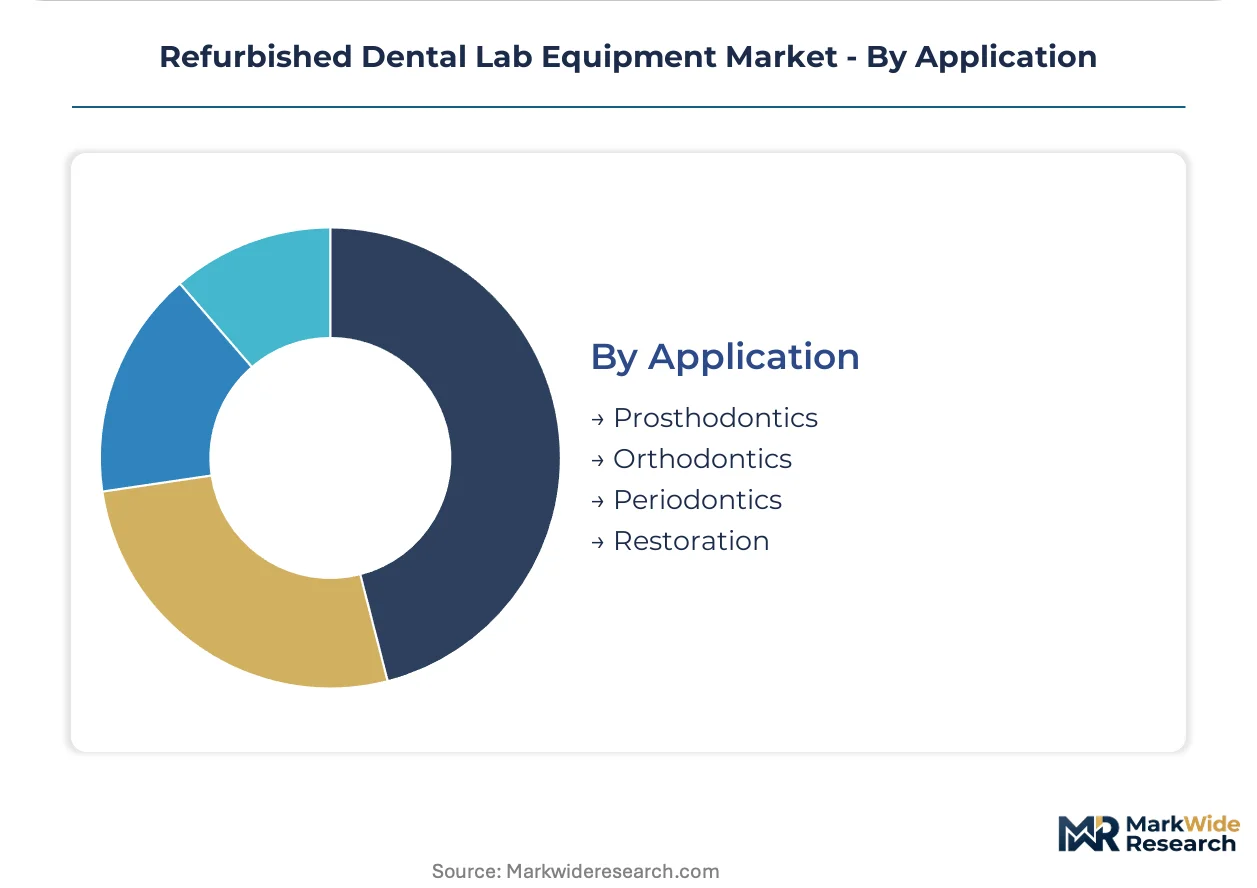
Application:
Clinical workflow requirements dictate tolerance thresholds and biocompatibility verification priorities across refurbished equipment categories.
- Prosthodontics:Crown, bridge, and denture fabrication demands ISO 10993 patient-contact surface recertification. Destructive testing protocols consume refurbished unit inventory and extend fulfillment timelines for laboratories serving prosthodontic workflows.
- Orthodontics:Clear aligner production and model printing drive demand for refurbished vat-polymerization systems. Next-generation ceramic blocks and hybrid composites for chair-side milling reduce demand for legacy metal-based crown fabrication refurbishment.
- Periodontics:Surgical guide printing and regenerative material processing require specialized sterilization protocols.
- Restoration:Direct and indirect restorative workflows span the broadest equipment compatibility range.
Equipment flow concentrates in prosthodontics; orthodontics gains share fastest as aligner manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-component foundries supply spindle assemblies and optical sensors that constrain refurbishment throughput worldwide. Mumbai and Delhi dental laboratory clusters absorb the densest concentration of secondary-market milling units. São Paulo's commercial laboratory networks drive Latin American demand for certified pre-owned CAD/CAM systems.
United States
Dental service organizations operating multi-site clinic networks standardize equipment fleets to preserve capital for chair-side technology investments. FDA 510(k) clearance documentation requirements extend recertification timelines for refurbished medical devices. Dallas and Houston metropolitan laboratory networks concentrate refurbishment demand for digital fabrication systems.
Germany
Specialized remanufacturing protocols for high-speed handpiece integration units sustain competitive positioning among domestic refurbishment specialists. EU Medical Device Regulation Article 23 interpretations harden distinctions between refurbishment and remanufacturing, requiring notified-body involvement for critical component replacement. Stuttgart and Munich industrial clusters host conformity assessment expertise for furnace and sterilizer recertification.
India
Cost-sensitive dental clinics scale digital fabrication capacity without new-equipment premiums, driving concentrated demand for refurbished milling units and scanners. BIS certification requirements filter informal refurbishment activity toward organized service providers. Mumbai and Delhi dental laboratory clusters anchor secondary-market absorption for CAD/CAM systems with 0.02 mm tolerance thresholds.
Brazil
Commercial laboratory networks in São Paulo seek certified pre-owned equipment pipelines as formalized refurbishment regulations develop under ANVISA pathways. ANVISA pathway development creates first-mover advantage for organized refurbishment providers serving South America's largest dental market. São Paulo's prosthodontic and orthodontic laboratory density concentrates demand for recertified 3D printing and milling systems.
United Kingdom
Post-Brexit capital constraints displace outright equipment ownership with subscription-based access models among dental laboratories. Bundled service offerings including preventive maintenance and component replacement guarantees concentrate demand in London and Manchester metropolitan networks. United Kingdom laboratories favor recurring revenue structures where equipment utilization rates support service contracts alongside refurbished hardware deployment.
Refurbished Dental Lab Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent service-contract and subscription-access models. Market structure consolidates around three dominant competitive archetypes: distribution-network incumbents leveraging procurement scale, specialized remanufacturing operators with component-level expertise, and secondary-market sourcing specialists controlling inventory pipelines. Strategic moves concentrate on M&A for regulatory compliance capabilities and geographic expansion into certification-backlogged Asia-Pacific markets.
Among distribution-network incumbents, Henry Schein and Patterson Companies Inc. exemplify archetypes that sustain refurbishment throughput through established procurement relationships and certified pre-owned equipment pipelines. KaVo Dental anchors the specialized remanufacturing tier with protocol-driven approaches to high-precision component integration. Dentsply Sirona occupies a position bridging manufacturer-authorized refurbishment with direct digital fabrication system deployment.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Henry Schein |
| Patterson Companies Inc. |
| KaVo Dental |
| GC Corporation |
| Ivoclar Vivadent |
| Carestream Dental |
| A-dec Inc. |
| Dental Equipment Liquidators, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU MDR Article 23 sustainability and recertification mandates gate qualified supply for premium-tier refurbished dental lab equipment, compressing margins for uncertified operators while elevating pricing power for notified-body-compliant providers serving German and French laboratory clusters.
Pricing Analysis
Extended warranty and preventive maintenance bundling separates premium-tier refurbishment providers from transactional secondary-market sellers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and FDA 510(k) clearance status. Pricing pressure stems from resin material substitution reducing demand for legacy metal-based crown fabrication refurbishment. Dental clinics in India exhibit highest price sensitivity; United States dental service organizations demonstrate lowest sensitivity due to capital preservation priorities.
Supply Chain Analysis
Precision spindle assemblies and optical sensors for milling units rest on German and Japanese original equipment manufacturers. Component inputs include zirconia sintering elements, piezoelectric transducers, and intraoral scanning optics. Single-source vulnerability concentrates in Stuttgart-area precision foundries and Nagoya optical sensor fabricators. Distribution runs through Henry Schein and Patterson Companies Inc. procurement networks feeding North American dental service organization fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refurbished dental lab equipment market sits in a technology-transition phase as AI-assisted predictive maintenance displaces reactive service models and cloud-based treatment planning convergence accelerates hardware obsolescence independent of mechanical wear.
For Market Incumbents: Hedge against CAD/CAM obsolescence compression by acquiring ISO 13485 certification capabilities in Asia-Pacific markets facing auditor scarcity. Deepen backward integration into precision spindle remanufacturing to offset German and Japanese OEM component bottlenecks. For New Entrants and Emerging Players: Dental equipment liquidators' digital auction platforms offer lowest-friction market entry for certified pre-owned inventory aggregation. Target Brazil's São Paulo laboratory networks ahead of formalized ANVISA refurbishment regulations. Pursue subscription-based equipment access models displacing outright ownership in post-Brexit United Kingdom metropolitan clusters. For Investors and Strategic Acquirers: FDA 510(k) clearance pathway friction extending United States recertification timelines is the leading indicator that regulatory compliance capabilities will command acquisition premiums. Five-to-ten-year viability favors notified-body-authorized refurbishment operators with EU MDR Article 23 expertise. Watch ANVISA regulatory development velocity in Brazil as inflection signal for Latin American market formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU MDR Article 23 compliance unlocks notified-body-authorized refurbishment premiums in German and French markets. |
| AI-Assisted Predictive Maintenance Launch | Machine learning diagnostics for handpiece turbine wear enable outcome-based service contracts alongside equipment sales. |
| Backward Integration into Component Remanufacturing | In-house precision spindle restoration reduces dependency on Stuttgart-area OEM supply concentration. |
| Subscription-Based Equipment Access Model | Bundled maintenance guarantees capture London and Manchester laboratory demand under post-Brexit capital constraints. |
| Geographic Expansion into Certification-Backlogged Markets | ISO 13485 auditor scarcity in Asia-Pacific creates first-mover advantage for compliant refurbishment providers. |
Study Parameters
Multi-period observation of refurbishment inventory velocity, recertification timeline extensions, and BIS certification uptake rates anchored the trend analysis, supplemented by interviews with dental laboratory operations directors, biomedical equipment technicians, GPO contracts managers, and aftermarket service heads. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified-body guidance documents, BIS certification registries, and hospital procurement databases. Bottom-up equipment unit economics triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Segment-weighting approaches distributed value pools across CAD/CAM systems, dental chairs, 3D printing units, and laboratory furnaces, with technology-generation stratification capturing obsolescence-cycle compression. CAGRs derived from installed-base replacement modeling and secondary-market inventory turnover rates across the analysis window. Forecast inputs incorporated resin material substitution elasticities and AI-assisted maintenance adoption curves specific to dental laboratory workflows.
The model holds under stable regulatory interpretation of refurbishment scope; deviation in EU MDR Article 23 notified-body guidance or ANVISA pathway formalization would shift competitive positioning toward compliance-heavy operators. A small set of regulatory trigger developments warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Germany Dental Equipment Market