
 Dental Equipment and Maintenance Market | 2026-2036
Dental Equipment and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Equipment and Maintenance Market Outlook
Modular service bundling is repositioning buyer choice in the dental equipment sector. Dentsply Sirona leverages its integrated digital workflow platforms to anchor recurring maintenance revenue streams. Danaher Corporation sustains competitive pressure through specialized diagnostic equipment servicing networks that compete on response-time guarantees. Henry Schein controls distribution channels for replacement parts, which positions the firm to capture margin pools from independent dental practices seeking predictable cost structures.
Dental equipment and maintenance encompasses the physical apparatus, diagnostic instruments, and sterilization systems used in oral healthcare delivery, alongside the scheduled servicing, calibration, and repair protocols that ensure continuous regulatory compliance and clinical accuracy. Autoclaves must achieve specific temperature-pressure parameters to eliminate biological contaminants, while digital imaging systems require periodic calibration against DICOM standards to preserve diagnostic fidelity. Preventive maintenance contracts for dental chairs and handpieces generate the most stable revenue streams, whereas emergency repair services command premium pricing but exhibit irregular demand patterns. CAD/CAM systems represent the fastest-growing technology segment as chairside milling adoption expands, though calibration services for these units remain concentrated among specialized technicians.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation impose stringent documentation burdens on manufacturers of reusable dental instruments, which elevates demand for certified maintenance providers. ISO 13485 quality management standards govern servicing protocols across multiple jurisdictions, creating compliance barriers that favor established service networks over independent repair shops. Stakeholders must monitor how AI-driven predictive maintenance platforms reshape technician deployment models and whether regulatory bodies expand software validation requirements for connected dental devices.
Market Dynamics
Dental equipment servicing is consolidating around specialized third-party providers as clinic chains abandon in-house biomedical engineering teams. FDA 510(k) documentation burdens and EU MDR calibration mandates are compressing margins for independent practices while elevating certified service networks.
Growth Catalysts
- EU MDR calibration mandates:Reusable handpiece manufacturers must maintain ISO 13485-certified service records, driving demand for accredited maintenance providers across Germany and France.
- CAD/CAM chairside milling:Dental clinics in Japan are adopting same-day crown fabrication systems that require quarterly technician calibration, creating recurring revenue anchors.
- United States clinic consolidation:DSOs (Dental Service Organizations) now control over 10,000 locations and prefer standardized preventive maintenance contracts over transactional repair models.
Market Restraints
- Specialized technician scarcity:Calibration protocols for digital imaging systems require DICOM-standard expertise that training programs in the United States cannot produce at sufficient scale.
- Replacement part supply concentration:Handpiece turbine assemblies and autoclave seals originate from a limited supplier base in Germany, exposing service networks to input cost volatility.
- FDA 510(k) documentation friction:Premarket notification requirements for modified sterilization equipment extend product refresh cycles and dampen upgrade demand.
Strategic Opportunities
- AI-driven predictive maintenance:Sensor-integrated dental chairs in Japanese clinics enable failure prediction algorithms that reduce emergency dispatch costs.
- Rural United States penetration gap:Independent practices in non-metropolitan counties lack access to same-day technician response, creating white space for mobile service platforms.
- Reimbursement-linked equipment standards:CMS quality metrics for Medicare Advantage dental benefits are tightening sterilization documentation requirements, favoring certified service providers.
Industry Challenges
- Biomedical engineering talent pipeline collapse:United States technical colleges have shuttered dental equipment-specific training programs, forcing service firms to recruit from general medical device sectors.
- Legacy analog system integration:Clinics retaining film-based radiography cannot upgrade to digital workflows without complete chairside reconfiguration, complicating hybrid maintenance portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Equipment and Maintenance Market |
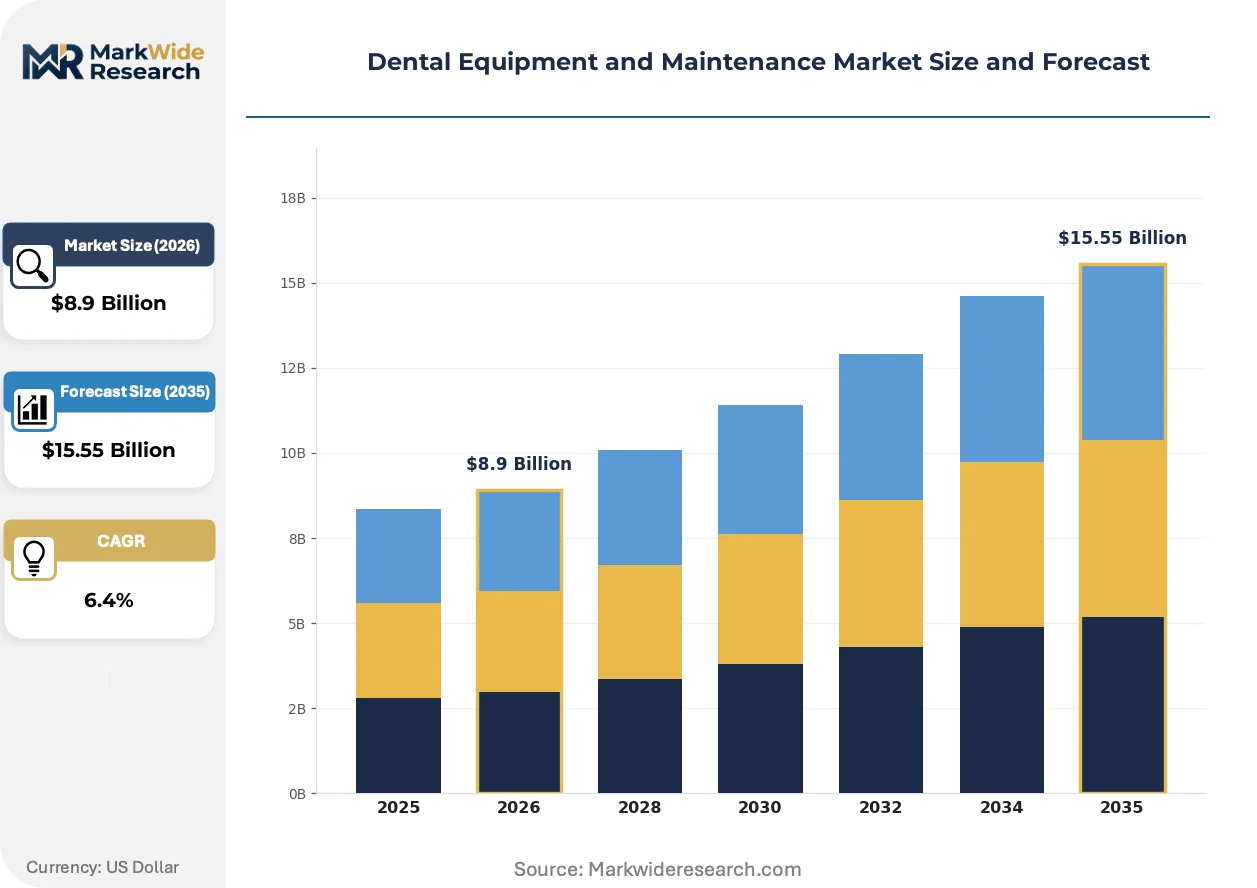
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Chairs, X-Ray Machines, Autoclaves, Handpieces Maintenance Type: Preventive Maintenance, Corrective Maintenance, Emergency Repairs, Calibration Services End User: Dental Clinics, Hospitals, Research Institutions, Academic Institutions Technology: Digital Imaging, CAD/CAM Systems, Laser Dentistry, 3D Printing |
| Companies Covered | Align Technology, Danaher Corporation, Dentsply Sirona, Planmeca Group, 3M Company, A-dec, Envista Holdings, Henry Schein, Straumann Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Equipment and Maintenance Market Strategic Shifts
Digital workflow integration is compressing equipment lifecycles and redefining what "maintenance" encompasses. Service providers now manage software updates, cybersecurity patches, and cloud connectivity alongside mechanical calibration.
AI-powered predictive analytics platforms are rewriting how dental equipment service networks deploy technicians. These systems aggregate vibration, temperature, and usage data from connected chairs and handpieces to forecast component failure before clinical interruption occurs. Large DSOs in the United States are piloting these platforms to shift from scheduled preventive visits to condition-based interventions, reducing truck rolls by targeting only deteriorating assets.
EU MDR Article 10 post-market surveillance requirements are tightening documentation standards for reusable dental instruments. Manufacturers must now maintain systematic data collection on device performance and adverse events, which elevates compliance costs but creates differentiation for firms with integrated quality management systems. German sterilization equipment producers are responding by embedding RFID tracking chips that automatically populate regulatory databases.
Subscription-based equipment access models are displacing capital purchase arrangements among United States startup practices. Young dentists burdened by educational debt prefer predictable monthly payments covering hardware, maintenance, and software licenses over lump-sum acquisition. Henry Schein and Patterson Dental have expanded their equipment-as-a-service portfolios to capture this liquidity-constrained segment, bundling calibration services into per-procedure fees rather than separate maintenance contracts.
Dental Equipment and Maintenance Market Segmentation
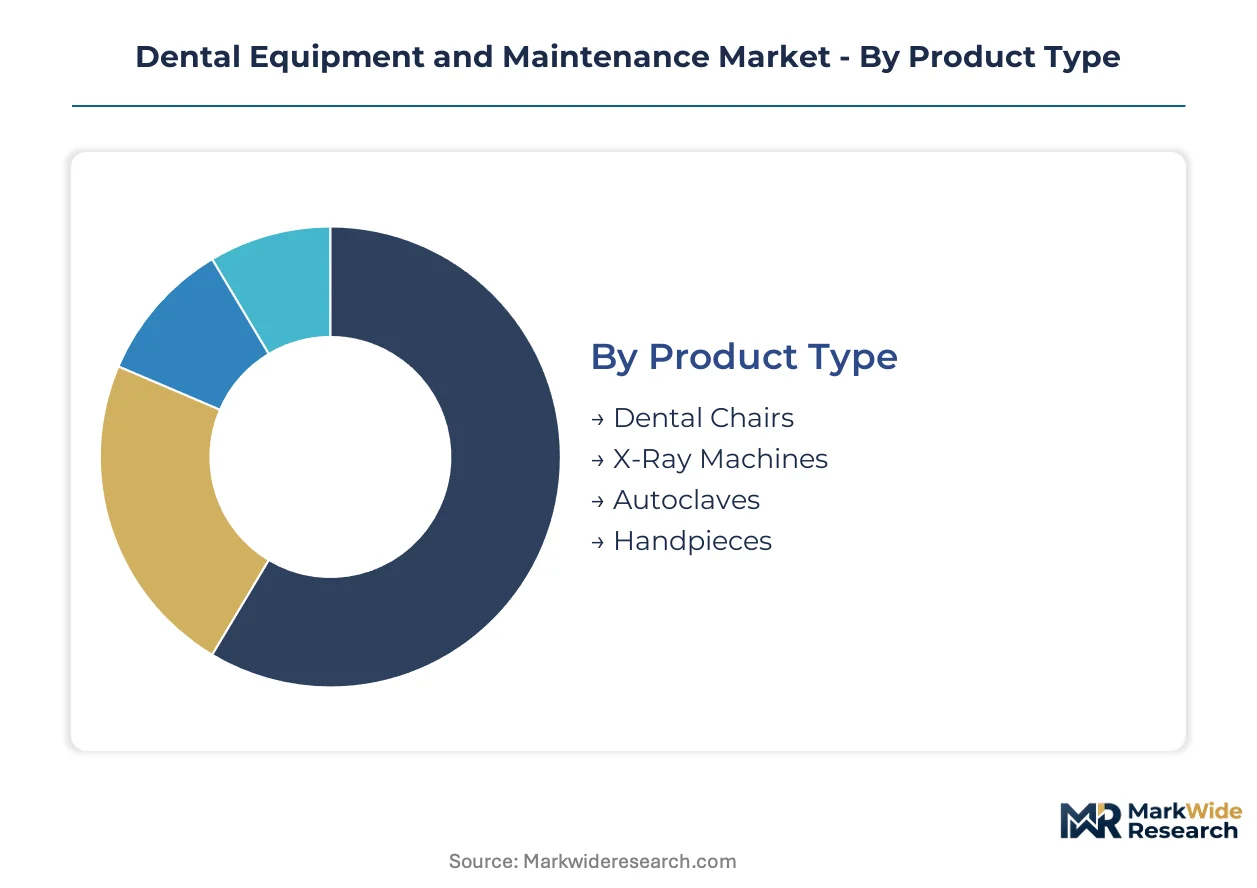
Dental equipment and maintenance segmentation reveals distinct compliance burdens across product categories. FDA 510(k) pathways and EU MDR calibration mandates create tiered certification requirements that reshape procurement decisions for clinic chains and independent practices.
Product Type:
Autoclaves and handpieces carry the heaviest ISO 13485 documentation obligations under EU MDR Article 10, while dental chairs and X-ray systems face divergent electrical safety and radiation control protocols.
- Autoclaves:Steam sterilization chambers must achieve precise temperature-pressure parameters to eliminate biological contaminants. German dental clinic chains demand RFID-tracked maintenance records that auto-populate regulatory databases, driven by EU MDR post-market surveillance mandates.
- Handpieces:Reusable turbine-driven instruments require quarterly calibration and lubrication protocols to preserve rotational precision. United States DSOs outsource servicing to third-party specialists rather than maintaining in-house biomedical teams, compressing margins for independent practices.
- Dental Chairs:Integrated patient positioning systems with sensor arrays enable predictive failure detection in Japanese installations.
- X-Ray Machines:Digital radiography units require DICOM-standard calibration against reference phantoms to preserve diagnostic fidelity.
Leading the category by volume: Dental Chairs. Growing fastest: CAD/CAM-integrated handpiece systems.
Maintenance Type:
Cost tiering separates predictable contractual revenue from volatile emergency dispatch premiums, with calibration services commanding specialist pricing due to technician scarcity.
- Preventive Maintenance:Scheduled servicing protocols for dental chairs and sterilization equipment generate recurring revenue streams through annual contracts. United States clinic consolidation toward DSO ownership standardizes these arrangements across multi-location portfolios.
- Calibration Services:DICOM-standard alignment for digital imaging and CAD/CAM milling units requires certified technicians with scarce training credentials. Japanese same-day crown fabrication adoption drives quarterly technician visits.
- Corrective Maintenance:Component replacement and repair interventions address wear-induced failures outside warranty periods.
- Emergency Repairs:Unplanned clinical interruption response commands premium pricing but exhibits irregular demand patterns concentrated in rural United States counties.
Highest margin capture: Calibration Services. Steepest expansion trajectory: Preventive Maintenance contracts.
End User:
Customer type determines procurement sophistication, with hospital systems leveraging centralized biomedical engineering against fragmented independent practice outsourcing.
- Dental Clinics:Standalone and chain-affiliated oral healthcare facilities represent the dominant demand concentration. United States DSOs controlling over 10,000 locations prefer standardized preventive contracts over transactional repair models.
- Hospitals:Integrated health systems maintain captive biomedical engineering teams for equipment servicing. German hospital networks centralize sterilization equipment maintenance across dental and surgical departments.
- Research Institutions:Academic medical centers with dental schools require specialized calibration protocols for experimental imaging systems.
- Academic Institutions:Dental training programs operate mixed analog-digital equipment fleets complicating maintenance standardization.
Dominant volume share: Dental Clinics. Fastest contract sophistication: Hospital systems.
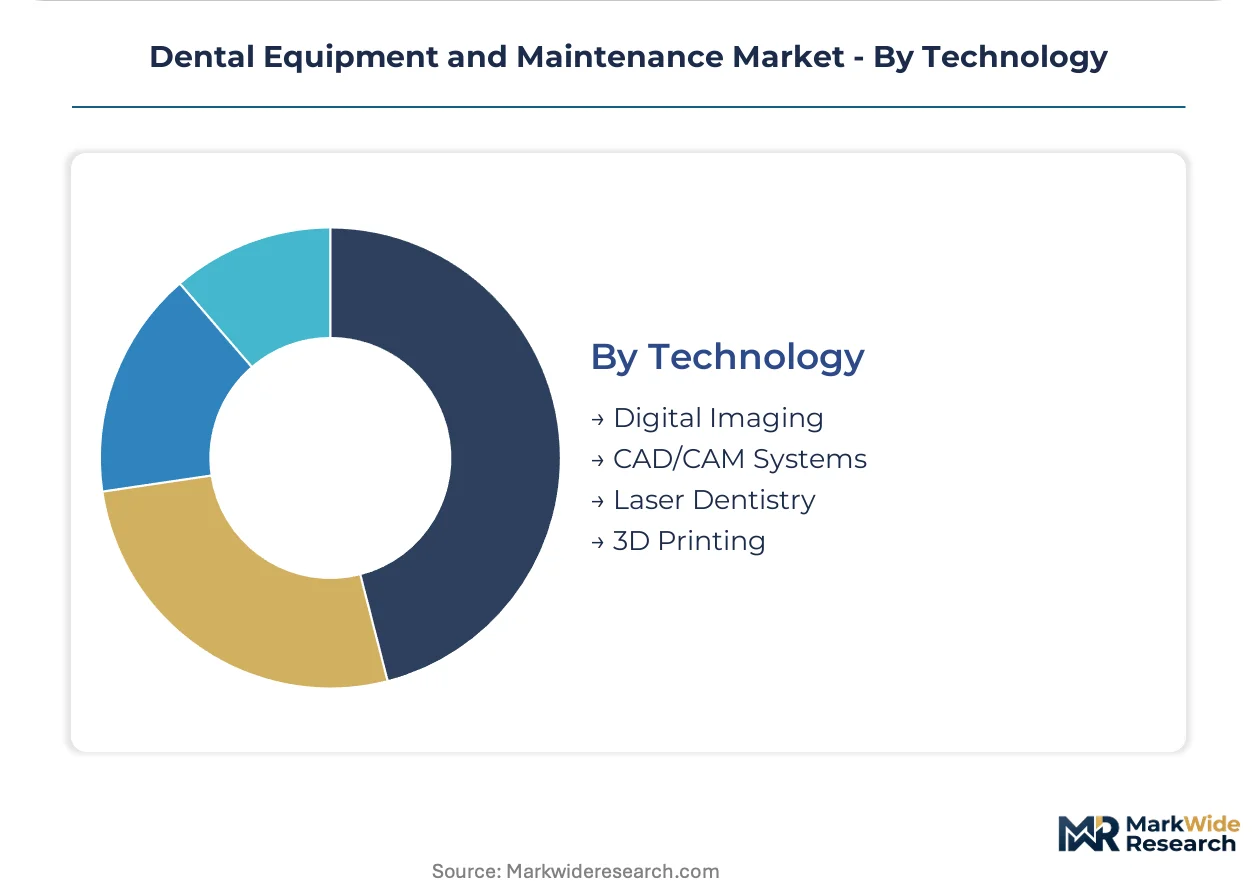
Technology:
Technology maturity stratifies maintenance requirements, with established digital imaging facing commoditized servicing against emerging 3D printing demanding nascent technical expertise.
- CAD/CAM Systems:Chairside milling and digital impression systems require quarterly technician calibration to preserve micron-level fabrication accuracy. Japanese clinic adoption of same-day crown workflows creates recurring revenue anchors for specialized service networks.
- Digital Imaging:Intraoral sensors and panoramic radiography units demand DICOM-standard calibration against reference datasets. United States technician training programs cannot produce certified specialists at sufficient scale.
- Laser Dentistry:Soft and hard tissue laser systems require power output verification and safety interlock testing protocols.
- 3D Printing:Photopolymer and powder-bed dental additive manufacturing systems need resin tank replacement and build platform alignment servicing.
Widest installed base: Digital Imaging. Gaining share fastest: CAD/CAM Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Dongguan concentrate dental equipment component manufacturing, attracting sterilization equipment suppliers seeking tariff advantages and integrated electronics supply chains.
United States
DSOs controlling over 10,000 locations drive standardization of preventive maintenance contracts across multi-state portfolios. FDA 510(k) premarket notification requirements for modified sterilization equipment extend product refresh cycles. Dallas-Fort Worth anchors technician training infrastructure where biomedical engineering programs face enrollment constraints.
Germany
Handpiece turbine assembly suppliers concentrate in Baden-Württemberg, creating input cost volatility for service networks. EU MDR Article 10 post-market surveillance mandates require ISO 13485-certified service records for reusable instruments. Stuttgart industrial clusters embed RFID tracking chips that auto-populate regulatory databases.
Japan
Chairside CAD/CAM adoption generates quarterly calibration demand for same-day crown fabrication systems. METI industrial standards govern sensor-integrated dental chair deployments enabling predictive failure detection. Nagoya manufacturing corridors supply precision milling spindle components to domestic equipment producers.
China
Domestic dental clinic chains expand digital imaging procurement as provincial healthcare infrastructure budgets increase. NMPA medical device registration requirements tighten quality benchmarks for imported sterilization equipment. Shanghai Pudong medical device zones concentrate distribution logistics for Asia-Pacific service parts.
India
Independent dental practices in tier-2 cities outsource equipment servicing due to absent in-house biomedical teams. CDSCO medical device rules impose documentation burdens on imported autoclave manufacturers. Gujarat pharmaceutical special economic zones attract sterilization equipment assemblers serving domestic and export markets.
Dental Equipment and Maintenance Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment manufacturing and third-party servicing tiers. Market structure concentrates around integrated digital workflow providers, specialized diagnostic equipment servicers, and distribution-channel controllers for replacement parts. Three archetypes dominate: full-stack platform owners capturing recurring software-maintenance bundles, response-time specialists competing on technician dispatch guarantees, and parts-centric intermediaries leveraging procurement scale. Consolidation proceeds through DSO-preferred vendor status acquisitions and predictive maintenance technology licensing arrangements.
Within the integrated platform tier, Dentsply Sirona and Danaher Corporation exemplify archetypes anchoring recurring revenue through digital workflow ecosystems and diagnostic equipment servicing networks respectively. Henry Schein occupies a position representing distribution-channel leverage over replacement parts procurement. These three entities illustrate how market positioning stratifies across software-hardware integration depth, technical service specialization, and supply chain intermediation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Align Technology |
| Danaher Corporation |
| Dentsply Sirona |
| Planmeca Group |
| 3M Company |
| A-dec |
| Envista Holdings |
| Henry Schein |
| Straumann Holding |
| Others |
Value Chain & Pricing Dynamics
Handpiece turbine assemblies originating from Baden-Württemberg feed through three-tier pricing structures across premium, standard, and economy levels, with ISO 13485-certified service records commanding specialist premiums while independent practices absorb volatile input costs from concentrated German suppliers.
Pricing Analysis
Margin tightening in preventive maintenance contracts reflects DSO standardization across multi-location portfolios. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression accelerates in emergency repair segments as rural United States practices face limited technician availability. Independent dental practices exhibit highest price sensitivity, while hospital systems with captive biomedical teams show lowest sensitivity due to centralized procurement leverage.
Supply Chain Analysis
Technician training program closures in United States technical colleges constrain service network expansion, forcing recruitment from general medical device sectors. Component manufacturing concentrates in Germany, Japan, and China, with precision milling spindle supply anchored in Nagoya corridors and sterilization equipment assembly clustering in Shenzhen free trade zones. Supply chains draw from handpiece turbines, autoclave seals, and DICOM-calibration reference phantoms. Single-source vulnerability in Baden-Württemberg turbine suppliers exposes networks to input cost volatility. Distribution runs through Henry Schein and Patterson Dental channel networks controlling replacement parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental equipment and maintenance sector is consolidating around backward integration into predictive maintenance software and captive technician training infrastructure as players race to control scarce calibration expertise.
For Market Incumbents: Deepen ISO 13485-certified service network density to defend against emerging AI-driven predictive maintenance platforms. Incumbent service providers should acquire specialized CAD/CAM calibration firms to secure technician talent pipelines collapsed by United States technical college program closures. Channel control over replacement parts procurement remains the priority defensive lever. For New Entrants and Emerging Players: Direct-to-dentist digital platforms offer the lowest-friction entry path into fragmented independent practice segments. New entrants should target rural United States counties lacking same-day technician response, deploying mobile service platforms with subscription-based equipment access models. Telemedicine-integrated calibration support represents the most penetrable go-to-market angle for liquidity-constrained startup practices. For Investors and Strategic Acquirers: DSO-preferred vendor status acquisitions are the leading indicator that consolidation momentum is accelerating toward platform-owning service networks. Long-term viability favors vertically integrated specialists combining equipment distribution with captive maintenance capabilities. Investors should monitor FDA 510(k) clearance velocity for modified sterilization equipment as the signal for upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Predictive Maintenance Platform Launch | Sensor-integrated dental chairs in Japanese clinics enable failure prediction algorithms reducing emergency dispatch costs. |
| ISO 13485 Certification Investment | EU MDR Article 10 mandates elevate compliance barriers favoring accredited service providers over independent repair shops. |
| DSO Preferred Vendor Partnership | United States dental service organizations controlling over 10,000 locations standardize procurement across multi-state portfolios. |
| CAD/CAM Calibration Specialist Acquisition | Quarterly technician demand from Japanese same-day crown fabrication creates recurring revenue anchors for specialized networks. |
| Mobile Service Platform Expansion | Rural United States independent practices in non-metropolitan counties lack access to same-day technician response. |
Study Parameters
Document review covered FDA 510(k) premarket notification databases, EU MDR Article 10 post-market surveillance filings, and ISO 13485 certification registries, complemented by interviews with dental clinic operations directors, biomedical engineering managers at DSOs, third-party service technicians, and sterilization equipment procurement leads at hospital systems. Secondary validation drew from CMS Medicare Advantage dental benefit quality metrics, GPO contract databases, and dental school equipment fleet records. Bottom-up equipment installation counts triangulated against top-down service revenue estimates across the analysis window.
Cross-reference between historical maintenance contract penetration patterns and panel input from service network executives shaped the analytical framework. Segmentation dimensions modeled include product type, maintenance contract structure, end-user sophistication tier, and technology maturity stage. CAGRs were derived from installed base expansion rates and service pricing trajectory assumptions. Forecast inputs incorporated DSO consolidation velocity and CAD/CAM adoption curves from Japanese clinic surveys.
The model holds under stable regulatory enforcement of EU MDR calibration mandates and continued DSO acquisition activity; deviation in FDA 510(k) documentation friction or biomedical engineering training program recovery would shift service network capacity assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market