
 Dental Dust Collector Market | 2026-2036
Dental Dust Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Dust Collector Market Outlook
Aftermarket filter replacement revenue is narrowing toward original equipment suppliers as dental clinics seek validated HEPA cartridge compatibility. Henry Schein Inc. leverages its distribution scale to bundle collector units with preventive maintenance contracts across North American dental service organizations. Vaniman Manufacturing Co. anchors its position in benchtop portable systems for boutique orthodontic practices. Quatro Air Technologies Inc. competes on extraction velocity specifications in Canadian provincial health tenders.
A dental dust collector is an engineered air quality system that captures particulate matter generated during grinding, polishing, and milling of gypsum, ceramics, and metal alloys in dental environments, typically achieving capture velocities of 80–100 feet per minute at the source hood. These units prevent occupational silica and beryllium exposure while protecting precision instrumentation from abrasive dust infiltration. Wet collectors lead the product type landscape due to superior suppression of respirable crystalline silica in high-speed zirconia milling, while portable collectors represent the fastest-growing configuration as mobile dental units proliferate in rural outreach programs. HEPA filtration technology commands premium positioning in oral surgery centers where aerosol control intersects with biological containment protocols.
The US Occupational Safety and Health Administration enforces permissible exposure limits for respirable crystalline silica that directly shape collector specifications in American dental laboratories. The European Union's REACH regulation and CE marking requirements for machinery safety influence filtration material selection and electrical compliance across EU member state imports. Dental clinic operators and equipment procurement officers must weigh total cost of ownership against evolving local exhaust ventilation mandates when specifying dust collector investments.
Market Dynamics
Cyclone separation technology is collapsing the installed base of baghouse filtration in high-throughput dental milling centers, compressing maintenance intervals and redirecting capital toward wet suppression systems that handle zirconia and lithium disilicate dust loads.
Growth Catalysts
- OSHA silica enforcement:The US Occupational Safety and Health Administration's respirable crystalline silica permissible exposure limit mandates source-capture ventilation upgrades across American dental laboratories, forcing equipment replacement cycles.
- Mobile dental expansion:Rural outreach programs in India and Brazil deploy portable collector units aboard mobile clinics, creating demand for lightweight 12V-compatible extraction systems.
- CAD/CAM milling densification:Same-day crown production workflows generate 3-4x particulate volume compared to traditional lab outsourcing, requiring dedicated dust control infrastructure chairside.
Market Restraints
- HEPA cartridge supply concentration:Filter media production clusters in Germany and South Korea expose buyers to extended lead times during regional logistics disruptions.
- Electrical compliance fragmentation:CE marking requirements under EU machinery directives conflict with voltage and grounding standards in Middle Eastern import markets, complicating manufacturer SKU strategies.
- Wet collector wastewater disposal:Gypsum-laden slurry requires hazardous waste handling protocols in jurisdictions with strict dental effluent regulations, elevating operating costs.
Strategic Opportunities
- Teledentistry infrastructure:Remote consultation hubs need compact aerosol control for intraoral scanning stations, opening a channel distinct from traditional lab equipment.
- EU Green Deal alignment:Energy efficiency benchmarks for industrial ventilation create preference for brushless DC motor architectures in public health procurement tenders.
- Orthodontic aligner manufacturing:Direct-to-consumer clear aligner production facilities require high-velocity extraction for thermoplastic trimming operations, a segment with sparse incumbent coverage.
Industry Challenges
- Commissioning expertise scarcity:Proper airflow balancing at source hoods requires certified industrial hygienists, a credential pool concentrated in major metropolitan dental school networks.
- Legacy ductwork incompatibility:Older European clinic buildings with asbestos-containing materials cannot accommodate negative pressure modifications without abatement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Dust Collector Market |
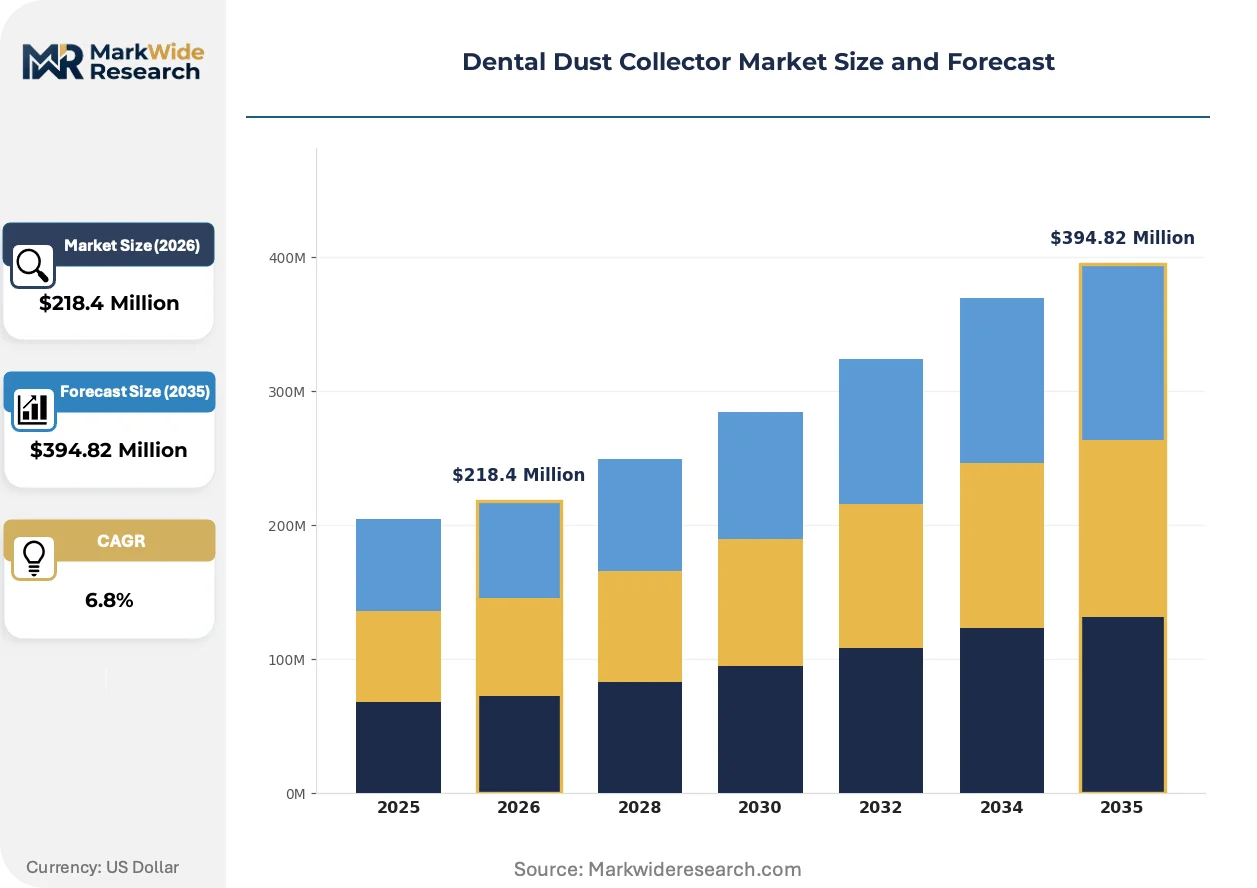
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $394.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Collectors, Dry Collectors, Portable Collectors, Centralized Systems Technology: Cyclone Separation, Filtration Systems, Electrostatic Precipitators, HEPA Filters Application: Dental Clinics, Dental Labs, Orthodontic Practices, Oral Surgery Centers End User: Dentists, Dental Technicians, Orthodontists, Hygienists |
| Companies Covered | Buffalo Dental Manufacturing Co. Inc., Comco Inc., DentalEZ Inc., Handler Manufacturing Company Inc., Henry Schein Inc., Ko-max Co. Ltd., Vaniman Manufacturing Co., Quatro Air Technologies Inc., Ray Foster Dental Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Dust Collector Market Strategic Shifts
Active filtration architectures are converging with IoT-enabled predictive maintenance, transforming dust collectors from passive hardware into monitored nodes within clinic operational workflows.
Cyclone pre-separation stages are collapsing the operational cost structure of high-volume milling operations by extending primary filter life 4-6x compared to direct-to-HEPA configurations. German dental manufacturing clusters in Bavaria and Baden-Württemberg have standardized on two-stage cyclone-wet scrubber combinations for zirconia processing. This technology compression eliminates the consumable filter replacement revenue stream that sustained prior generation business models.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in climate-controlled cleanroom environments where precision milling occurs, indirectly elevating dust collector specifications to compensate for tighter enclosure air handling. Dental equipment importers must now document refrigerant-free climate systems or upgrade extraction capacity to maintain ISO 14644-1 compliance. French and Italian dental lab networks report the steepest compliance cost impacts due to aging HVAC infrastructure.
Consolidated dental service organizations are unbundling preventive maintenance contracts from equipment capital purchases, forcing collector manufacturers to compete on lifecycle service revenue rather than upfront unit margin. Henry Schein Inc. and Patterson Dental have established captive service networks that displace independent HVAC contractors in North American clinic chains. This channel compression is most advanced in Texas and Florida where dental practice aggregation has proceeded fastest.
Dental Dust Collector Market Segmentation
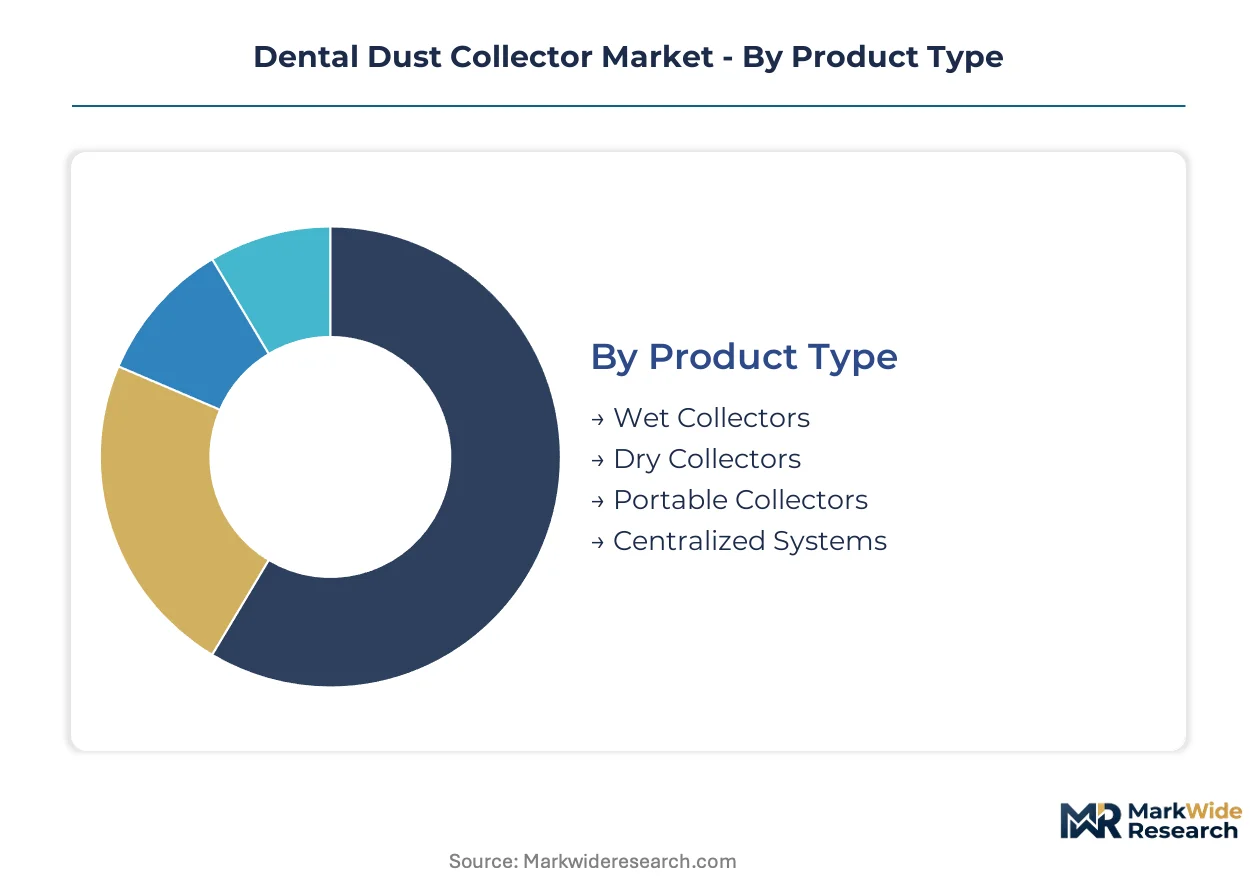
Dental dust collector procurement splits sharply between high-volume milling centers demanding industrial-grade infrastructure and mobile operators prioritizing compact extraction. Understanding these segment boundaries clarifies why cyclone-wet combinations dominate Bavarian manufacturing while portable units penetrate rural outreach programs.
Product Type:
The use-case spectrum spans permanent industrial installations through field-deployable systems, with each configuration matching specific particulate loads and spatial constraints.
- Wet Collectors:These systems suppress respirable crystalline silica through water-based particle agglomeration, achieving superior capture of zirconia and lithium disilicate dust from high-speed milling. Demand concentrates in German dental manufacturing clusters where REACH compliance mandates stringent workplace exposure controls.
- Portable Collectors:Lightweight 12V-compatible units serve mobile dental clinics and rural outreach programs across India and Brazil. Brazilian provincial health tenders specify extraction velocity benchmarks that favor compact designs over centralized alternatives.
- Dry Collectors:Baghouse and cartridge configurations persist in legacy installations where water disposal constraints elevate operating costs.
- Centralized Systems:Multi-station ducted networks serve high-throughput milling centers with dedicated infrastructure budgets.
The dominant share belongs to wet collectors, while portable collectors are closing the gap fastest.
Technology:
Cost tier differentiation separates capital-intensive pre-separation stages from consumable-dependent filtration architectures.
- Cyclone Separation:Centrifugal force pre-separation extends primary filter life fourfold to sixfold compared with direct-to-HEPA configurations. Bavarian dental labs have standardized on two-stage cyclone-wet scrubber combinations for zirconia processing.
- HEPA Filters:H13 and H14 grade media achieve capture efficiencies required for oral surgery center aerosol containment. Supply concentration in German and South Korean filter media production exposes buyers to logistics disruption risks.
- Filtration Systems:Multi-stage cartridge arrangements serve mid-volume operators balancing capital constraints against maintenance predictability.
- Electrostatic Precipitators:Ionization-based capture suits specialized metal alloy grinding with conductive particulate characteristics.
Cyclone separation commands the installed base expansion, though HEPA filtration maintains premium positioning in regulatory-sensitive applications.
Application:
Customer type maturity shapes specification requirements from preventive maintenance contracts through capital procurement cycles.
- Dental Clinics:Chairside CAD/CAM integration generates threefold to fourfold particulate volume versus traditional lab outsourcing. Texas and Florida dental service organizations bundle collector units with preventive maintenance through captive distribution networks.
- Dental Labs:High-throughput milling centers in the Paris metropolitan network drive cyclone-wet specification standardization ahead of stricter EU workplace exposure limits.
- Orthodontic Practices:Boutique operations favor benchtop portable systems for thermoplastic trimming and aligner finishing operations.
- Oral Surgery Centers:Biological containment protocols intersect with aerosol control requirements, mandating validated HEPA cartridge compatibility.
Dental clinics anchor volume demand, while orthodontic practices are expanding most quickly behind direct-to-consumer aligner manufacturing growth.
End User:
Professional credential boundaries determine procurement authority and specification sophistication across installation scales.
- Dental Technicians:Laboratory specialists specify source-capture ventilation for OSHA silica compliance in American milling operations.
- Dentists:Practice owners weigh total cost of ownership against local exhaust ventilation mandates in equipment procurement decisions.
- Orthodontists:Clear aligner production facility operators demand high-velocity extraction for thermoplastic trimming with sparse incumbent supplier coverage.
- Hygienists:Intraoral scanning station operators in teledentistry hubs require compact aerosol control distinct from traditional lab equipment.
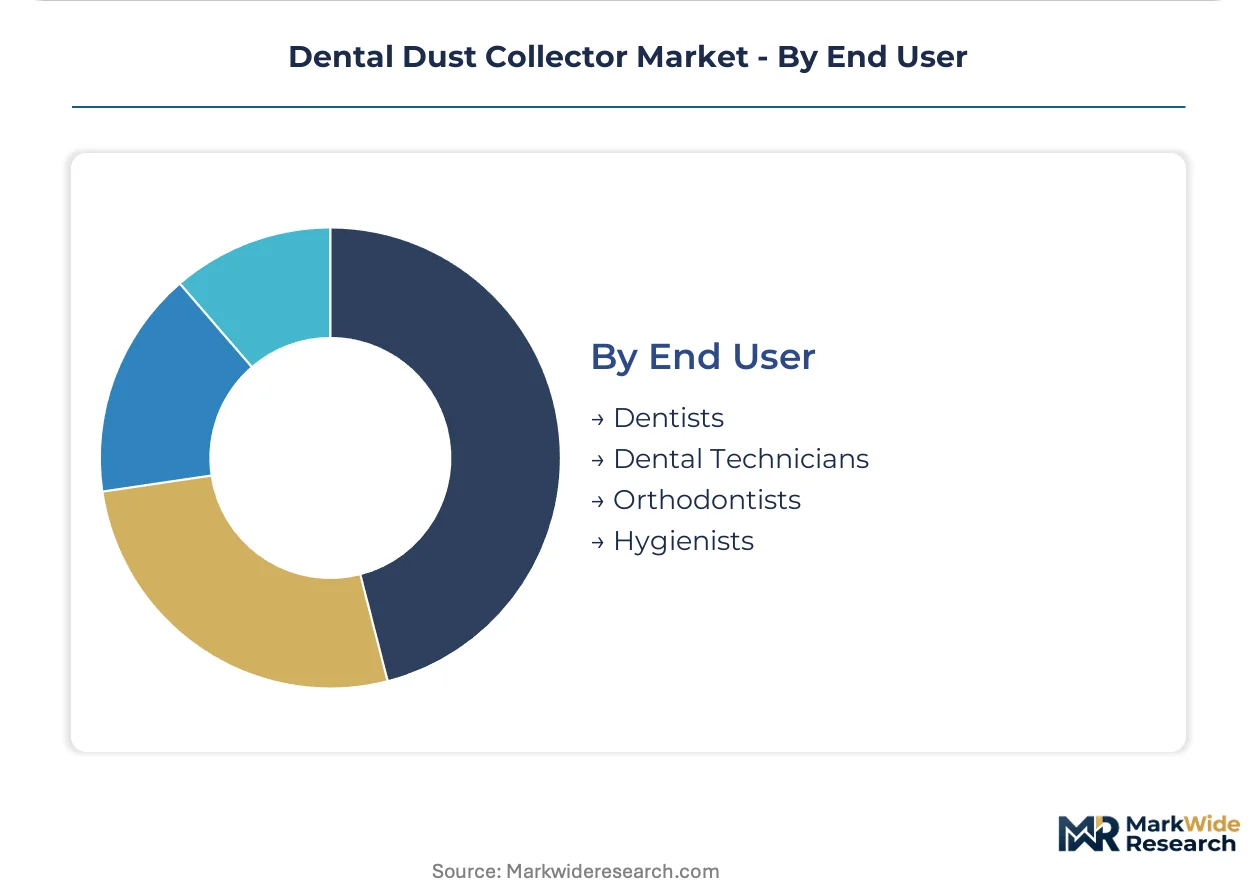
Dental technicians drive specification complexity, while orthodontists are gaining procurement influence fastest through manufacturing verticalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German dental manufacturing clusters show the lowest price elasticity, absorbing cyclone-wet system premiums for REACH compliance, while Brazilian provincial health tenders enforce aggressive extraction velocity benchmarks that compress supplier margins.
Germany
Bavarian dental labs drive cyclone-wet scrubber standardization for zirconia processing ahead of stricter EU workplace exposure limits. ECHA enforcement of REACH workplace exposure controls mandates validated HEPA cartridge compatibility across Baden-Württemberg milling centers. The Stuttgart metropolitan lab network has completed wholesale filtration infrastructure upgrades.
United States
Texas and Florida dental service organizations bundle collector procurement with captive preventive maintenance networks. OSHA silica permissible exposure limits force equipment replacement cycles across American dental laboratories. Greater Houston clinic chains have consolidated dust control vendor relationships under single-source contracts.
France
Paris metropolitan dental labs face the steepest F-Gas Regulation compliance costs due to aging HVAC infrastructure requiring extraction capacity upgrades. ANSM oversight of dental manufacturing hygiene standards intersects with CE marking machinery safety requirements. The Île-de-France aligner production corridor is expanding thermoplastic trimming operations.
Brazil
Provincial health tenders in Minas Gerais specify 12V-compatible portable extraction systems for mobile rural outreach programs. ANVISA medical device regulations shape import compliance for dental equipment distributors. São Paulo's dental manufacturing belt is localizing collector assembly to bypass voltage standard fragmentation.
India
Rural mobile dental clinics across Maharashtra and Gujarat deploy lightweight portable units aboard field-deployable vehicles. BIS certification requirements for electrical safety slow import clearance for non-domestic manufacturers. The Ahmedabad dental equipment cluster is developing indigenous cyclone separation fabrication capacity.
Dental Dust Collector Market Competitive Environment
Capability concentration sits with specialized engineering houses; scale advantage sits with distribution-integrated conglomerates. The market structure fragments across three tiers: captive service networks of dental supply chains, standalone equipment specialists, and regional fabrication shops serving price-sensitive tenders. Strategic archetypes include bundling platform operators, benchtop portable specialists, and wet scrubber engineering houses. M&A activity concentrates in North American service organization consolidation, while technology licensing spreads cyclone-wet combinations from German origins.
Among distribution-integrated conglomerates, Henry Schein Inc. exemplifies the bundling archetype through preventive maintenance contract capture. Vaniman Manufacturing Co. and Quatro Air Technologies Inc. occupy positions within the specialist tier, with the former representing benchtop portable system expertise and the latter anchoring extraction velocity competition in Canadian provincial procurement. Handler Manufacturing Company Inc. sits within the established fabrication tier, reflecting traditional equipment manufacturing lineage.
| Leading Market Players |
|---|
| Buffalo Dental Manufacturing Co. Inc. |
| Comco Inc. |
| DentalEZ Inc. |
| Handler Manufacturing Company Inc. |
| Henry Schein Inc. |
| Ko-max Co. Ltd. |
| Vaniman Manufacturing Co. |
| Quatro Air Technologies Inc. |
| Ray Foster Dental Equipment |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South Korean HEPA filter media production is compressing cartridge availability and elevating replacement pricing for dental clinics dependent on validated compatibility. German cyclone-wet system manufacturers exploit this bottleneck to push premium positioning for consumable-free architectures, reshaping procurement economics across high-volume milling centers.
Pricing Analysis
Aftermarket filter replacement contracts generate lifetime value multiples exceeding original equipment sales for incumbent suppliers. Three-tier pricing structure across premium cyclone-wet systems, standard cartridge-based units, and economy portable configurations segments buyers by compliance burden and throughput scale. Cost compression in standard cartridge tiers is intensifying because Brazilian and Indian provincial tenders enforce aggressive extraction velocity benchmarks without margin protection. Dental service organizations in Texas and Florida show lowest price sensitivity, absorbing bundled preventive maintenance premiums, while rural mobile operators in Maharashtra and Gujarat prioritize capital minimization over lifecycle economics.
Supply Chain Analysis
Tariff exposure between Germany and Middle Eastern import markets complicates electrical compliance SKU strategies for collector manufacturers. HEPA filter media production draws from Germany and South Korea, while cyclone separation fabrication concentrates in Bavarian industrial clusters and emerging Ahmedabad capacity. Single-source vulnerability in brushless DC motor architectures creates procurement risk for EU Green Deal-aligned efficiency tenders. Distribution runs through captive service networks of dental supply conglomerates in North America, displacing independent HVAC contractors in consolidated clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental dust collector market is recovering from pandemic-deferred infrastructure investment as OSHA silica enforcement and EU REACH workplace exposure tightening trigger replacement cycles. Equipment procurement officers face compressed decision timelines between regulatory compliance deadlines and supply chain lead time volatility.
For Market Incumbents: Entrench cyclone-wet technology leadership through backward integration into brushless DC motor production, eliminating exposure to automotive sector demand surges that disrupt dental equipment supply. Lock in dental service organization contracts with outcome-based preventive maintenance guarantees that preempt independent contractor displacement. Certification investment in CE-MDR machinery safety and ANVISA medical device pathways secures tender eligibility across fragmented import markets.
For New Entrants and Emerging Players: Pursue orthodontic aligner manufacturing facilities as the most penetrable white-space segment, where thermoplastic trimming extraction requirements outpace incumbent supplier coverage. Target teledentistry infrastructure hubs for compact aerosol control systems distinct from traditional lab equipment specifications. Channel partnership with clear aligner platform operators provides bypass around established dental supply distribution gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wet scrubber engineering houses with captive service networks in German manufacturing clusters. Long-term viability over the next decade hinges on refrigerant-free climate system alignment as EU F-Gas Regulation tightens milling environment specifications. Acquisition target archetype: regional fabrication shops with indigenous cyclone separation capacity and BIS certification clearance for Indian market access. Signal to watch: provincial health tender language shifting from extraction velocity benchmarks to lifecycle cost-of-ownership scoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Cyclone-Wet Technology Licensing | German-origin two-stage combinations spread to Ahmedabad and São Paulo manufacturing belts. |
| Preventive Maintenance Contract Capture | Henry Schein and Patterson Dental displace independent HVAC contractors in Texas and Florida clinic chains. |
| CE-MDR Machinery Safety Certification | ANSM oversight in France and ECHA enforcement across Baden-Württemberg elevate compliance barriers. |
| Brushless DC Motor Architecture Transition | EU Green Deal energy efficiency benchmarks create preference in public health procurement tenders. |
| Orthodontic Aligner Extraction Partnership | Direct-to-consumer clear aligner production facilities in Île-de-France corridor demand high-velocity thermoplastic trimming control. |
Study Parameters
Desk research of trade customs data, ECHA regulatory filings, and dental equipment distributor catalogs preceded structured interviews with dental clinic procurement officers, biomedical engineers in hospital purchasing committees, aftermarket service heads at supply conglomerates, and industrial hygienists in metropolitan dental school networks. Primary fieldwork with Bavarian milling center operators and Paris metropolitan lab technicians validated secondary estimates of cyclone-wet adoption rates. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing from OSHA enforcement scope and EU workplace exposure limit coverage.
Assumptions held fixed include REACH and OSHA silica permissible exposure limit enforcement intensity, while CAD/CAM milling densification rates and mobile dental clinic deployment trajectories were stress-tested across scenarios. Segmentation dimensions spanned product type, technology architecture, application setting, and professional credential of procurement authority. CAGRs were derived from logistic diffusion curves fitted to equipment replacement cycle data and regulatory compliance deadline clustering. Industry-specific inputs included zirconia processing volume growth from same-day crown workflows and F-Gas Regulation indirect effects on cleanroom extraction specifications.
Sensitivities concentrate around HEPA cartridge supply disruption duration, Brazilian provincial tender specification volatility, and orthodontic aligner manufacturing verticalization pace. Forecasts reflect documented assumptions on regulatory enforcement timing and technology substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
France Dental Equipment Market