
 Dental Lights Market | 2026-2036
Dental Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Lights Market Intelligence
The specialized technical skill in integrating advanced optics and wireless controls into dental operatories is reorganizing the vendor ecosystem. A-dec Inc. leverages its established brand and distribution channels, particularly in the United States. Planmeca Oy differentiates through its focus on comprehensive digital dentistry suites that include lighting systems. Dentsply Sirona sustains a broad market presence with its extensive product portfolio and global service network.
Dental lights are medical illumination devices designed to provide intense, shadow-free light within the oral cavity during procedures. Key performance metrics include a high Color Rendering Index (CRI), often above 90, and adjustable color temperatures to aid in composite shade matching. LED technology has become the dominant product type, displacing legacy halogen systems due to better longevity and lower heat emission. Ceiling-mounted installations represent the largest segment, while portable units cater to mobile dentistry and academic training environments.
Market access is governed by stringent medical device regulations. The FDA in the United States, CE marking under the Medical Device Regulation (MDR) in Europe, and NMPA approval in China are primary gatekeepers for manufacturers. These frameworks dictate standards for electrical safety, performance, and electromagnetic compatibility. A vendor's ability to navigate these diverse compliance requirements while innovating in light quality and digital integration will determine future competitive standing.
Market Dynamics
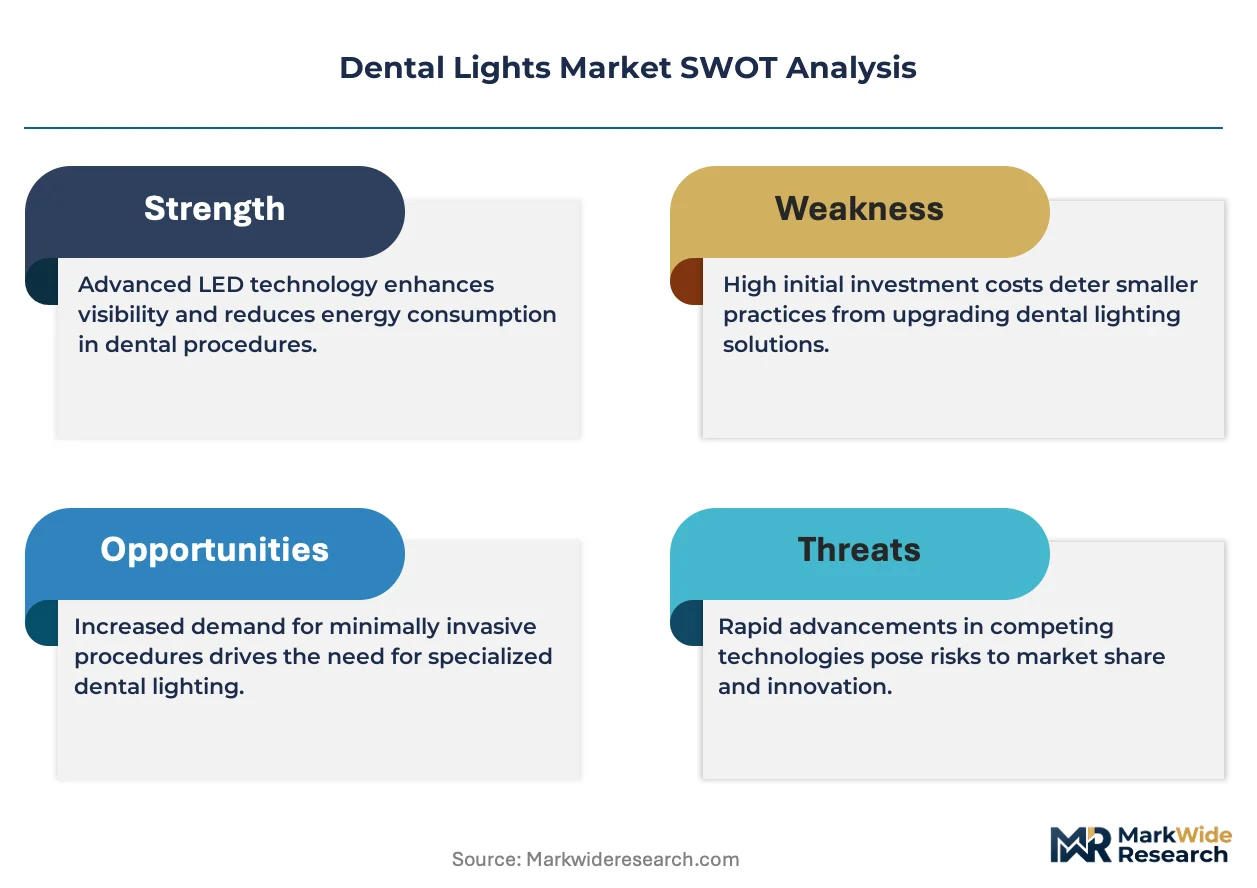
The convergence of stringent medical device regulations with rapid advancements in solid-state lighting technology is the central force shaping the market. This dual pressure compels manufacturers to innovate on performance metrics like color rendering while ensuring global compliance across different jurisdictions.
Growth Catalysts
- LED Technology Adoption:The transition from halogen to LED technology offers superior longevity, reduced heat emission, and better energy efficiency, prompting upgrade cycles in established dental clinics seeking operational improvements.
- Private Clinic Expansion:Growth in private dental practices and cosmetic dentistry elevates the need for high-performance lighting to improve diagnostic accuracy and procedural outcomes, especially in developed economies.
- Enhanced Clinical Standards:An emphasis on precise shade matching in restorative dentistry drives demand for lights with high CRI and adjustable color temperatures, aligning with modern aesthetic treatment protocols.
Market Restraints
- High Initial Investment:The significant capital outlay for premium, ceiling-mounted LED lighting systems can deter smaller clinics or those in emerging markets from upgrading from functional legacy equipment.
- Stringent Regulatory Hurdles:Navigating the divergent requirements of the FDA in the United States, Europe's MDR, and China's NMPA adds substantial cost and time to market entry for manufacturers.
- Competition from Integrated Systems:The rise of all-in-one dental operatory units, which bundle lighting with chairs and other equipment, can limit the standalone market for specialized light producers.
Strategic Opportunities
- Wireless Control and IoT Integration:Developing smart lights with wireless controls, remote diagnostics, and integration into digital dentistry platforms offers a path for product differentiation and higher margins.
- Underpenetrated Mobile Dentistry:The portable dental lights segment presents an opportunity to serve growing mobile dentistry services for aged care facilities, rural communities, and humanitarian programs.
- Specialization in Surgical Lighting:Creating specialized models optimized for oral surgery, with features like deeper focal points and specific light patterns, can capture a high-value niche market segment.
Industry Challenges
- Optical Engineering Talent Scarcity:A limited pool of engineers with specialized expertise in medical-grade optical design and LED thermal management constrains product development capacity for many vendors.
- Integration Complexity:Ensuring seamless interoperability of advanced lighting controls with diverse third-party practice management and imaging software remains a persistent technical hurdle for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Lights Market |
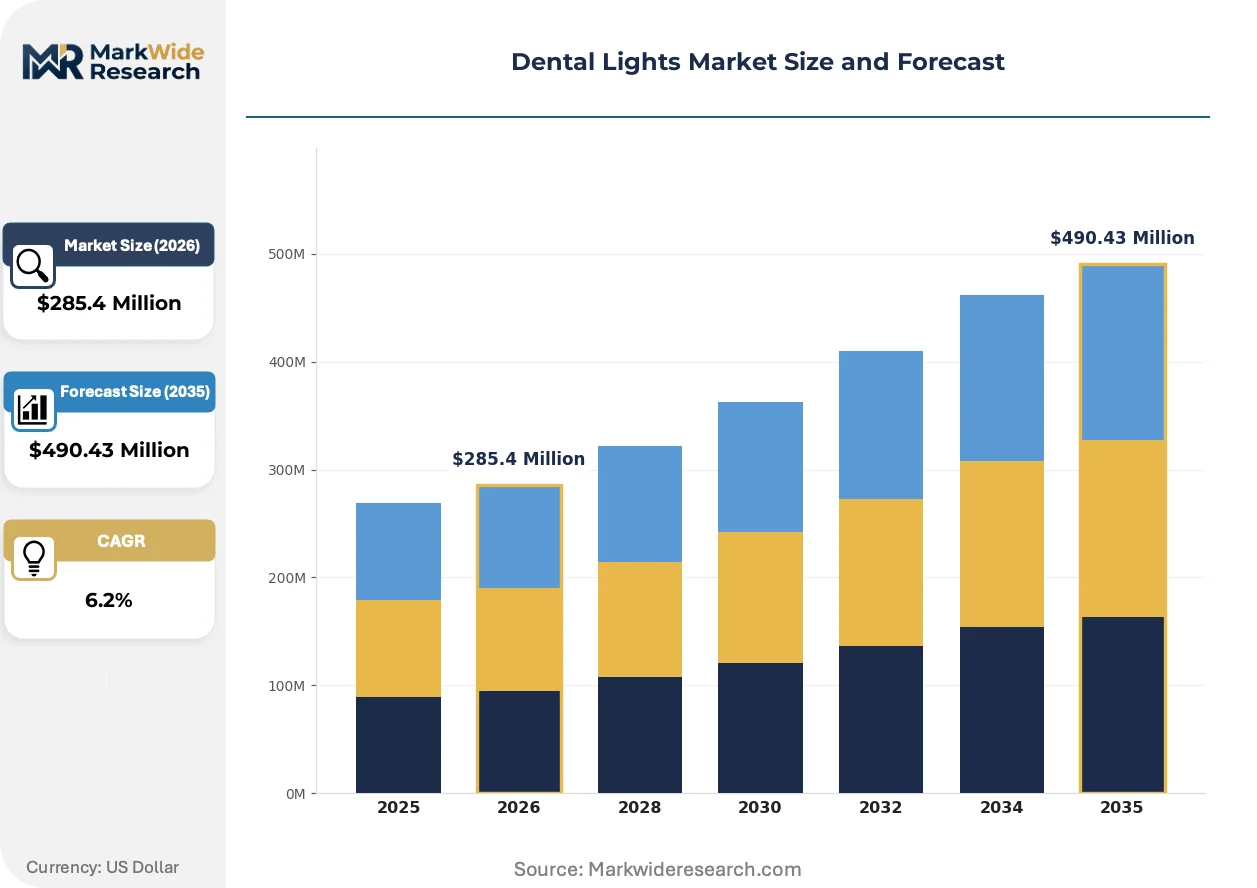
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Installation Type: Wall Mounted, Ceiling Mounted, Portable, Tabletop Technology: Wireless, Adjustable Intensity, Color Temperature Control, Focusable End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions |
| Companies Covered | A-dec Inc., Midmark Corporation, Danaher Corporation, Planmeca Oy, DentalEZ, Flight Dental Systems, Dentsply Sirona, TPC Advanced Technology, Inc., Dr. Mach GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Lights Market Strategic Shifts & Innovations
The convergence of digital workflow integration and material science is defining the next generation of dental illumination. The focus shifts from simple illumination to creating an intelligent, data-connected component within the broader digital operatory, prioritizing procedural efficiency and diagnostic precision.
Advanced LED technology incorporates multi-axis light heads and composite-safe modes that filter specific blue-light wavelengths to prevent premature curing. High-end dental groups and university clinics are the primary adopters, seeking to maximize procedural control and material compatibility. This advancement is bifurcating the market into standard illumination systems and premium, procedure-specific lighting solutions with integrated smart features.
Europe's Medical Device Regulation (MDR) imposes more rigorous clinical evaluation and post-market surveillance. This increases the compliance burden, demanding extensive technical documentation and supply chain traceability. Manufacturers targeting the EU are consequently investing more in regulatory affairs and quality management systems to maintain CE marking for their products.
Purchasing decisions are consolidating within large Dental Service Organizations (DSOs), shifting away from individual practitioner choices. These groups leverage bulk purchasing power to negotiate pricing and demand standardized equipment for operational consistency. This trend is most prominent in the United States, favoring vendors with strong national distribution and service networks.
Dental Lights Market Segmentation
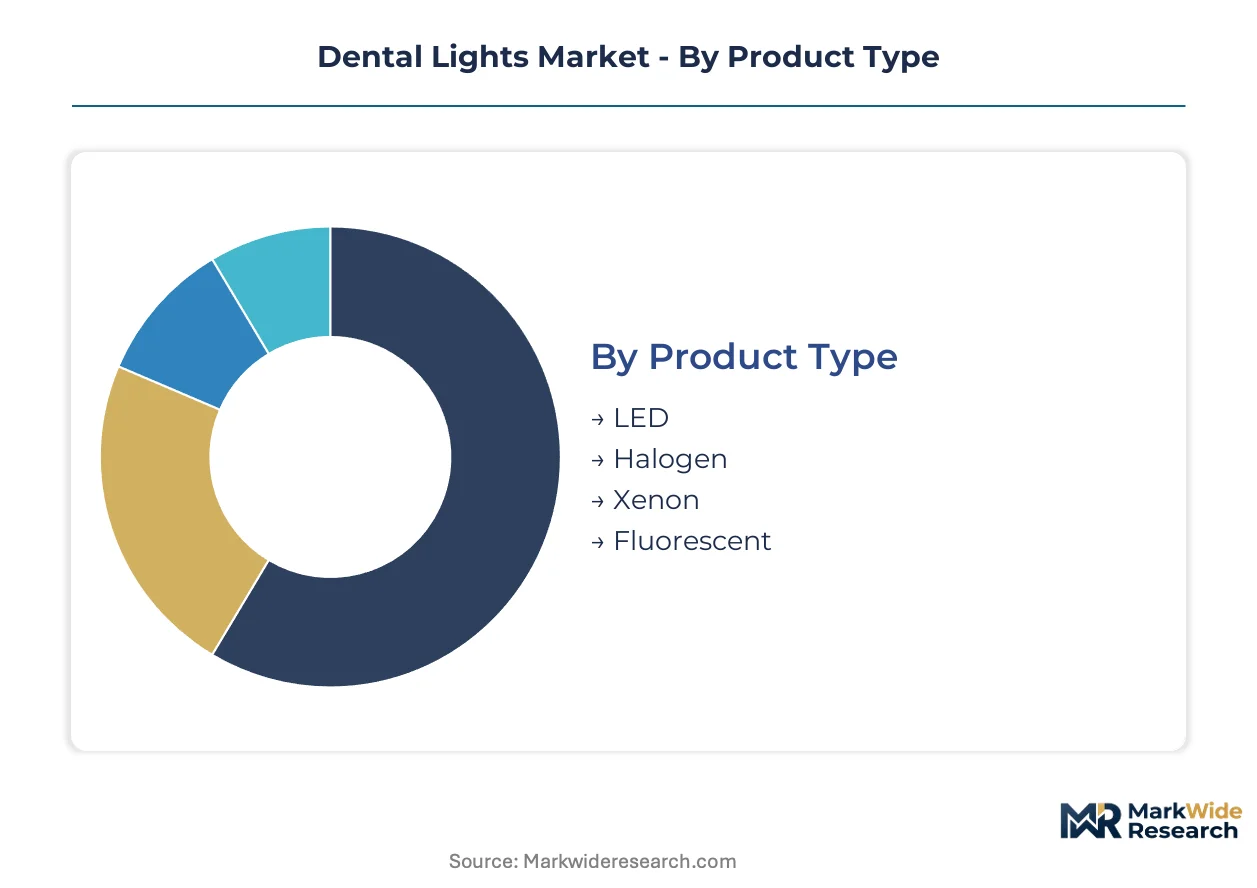
Understanding the distinct segments within the dental lights market reveals varied adoption patterns across different clinical settings. Each category reflects specific operational needs and technological preferences. This segmentation highlights where innovation is most impactful and where legacy systems persist.
Product Type:
Product type segmentation reflects distinct preferences and regulatory landscapes influencing material adoption across national markets.
- LED:These lights utilize light-emitting diodes for illumination, offering superior longevity and energy efficiency compared to traditional sources. Demand for LED technology concentrates in developed markets like Germany and the United States, driven by a desire for enhanced diagnostic accuracy and lower operational costs.
- Halogen:Halogen dental lights employ incandescent bulbs with halogen gas, providing a warm, traditional light spectrum. These systems maintain a presence in cost-sensitive markets and smaller clinics, where initial investment remains a primary purchasing consideration.
- Xenon:Xenon lights offer high-intensity illumination, often found in specialized surgical applications requiring powerful, focused beams.
- Fluorescent:Fluorescent dental lights provide diffuse, broad-spectrum illumination, sometimes used in general examination rooms for ambient lighting.
Halogen commands the established base. The steepest expansion runs through LED.
Installation Type:
Installation type segmentation delineates how different clinical layouts and procedural requirements shape equipment choices across dental practices.
- Ceiling Mounted:These units are fixed to the operatory ceiling, providing stable, shadow-free illumination over the patient's oral cavity. Large dental clinics and hospitals in urban centers prioritize ceiling-mounted systems for their robust performance and ergonomic benefits during complex procedures.
- Portable:Portable dental lights are compact, self-contained units designed for mobility, often battery-powered for flexible deployment. Mobile dentistry services and academic training environments in rural communities increasingly adopt portable solutions for their operational versatility.
- Wall Mounted:Wall-mounted lights attach directly to operatory walls, offering a space-saving solution for clinics with limited floor or ceiling access.
- Tabletop:Tabletop dental lights are smaller, adjustable units suitable for laboratory work or specific examination tasks within a dental practice.
Ceiling Mounted systems represent the core infrastructure choice. Portable units are gaining share fastest among specialized service providers.
Technology:
Technology segmentation highlights the varying levels of digital integration and advanced features that influence purchasing decisions across different clinic tiers.
- Wireless:Wireless dental lights integrate Bluetooth or other radio-frequency controls for remote operation, enhancing operatory workflow and reducing cable clutter. Premium dental groups in the United States increasingly invest in wireless systems for seamless integration into digital dentistry platforms.
- Adjustable Intensity:Adjustable intensity features enable dentists to modify the brightness of the light, reducing eye strain and adapting to various procedural requirements. Restorative dentistry specialists in Europe highly value adjustable intensity for precise aesthetic outcomes and composite compatibility.
- Color Temperature Control:This technology allows dentists to adjust the light's Kelvin temperature, optimizing conditions for shade matching and material curing.
- Focusable:Focusable dental lights allow for adjustment of the light beam's concentration, providing targeted illumination for specific areas during intricate procedures.
Adjustable Intensity remains a foundational capability. Wireless technology is expanding most quickly within high-specification clinics.
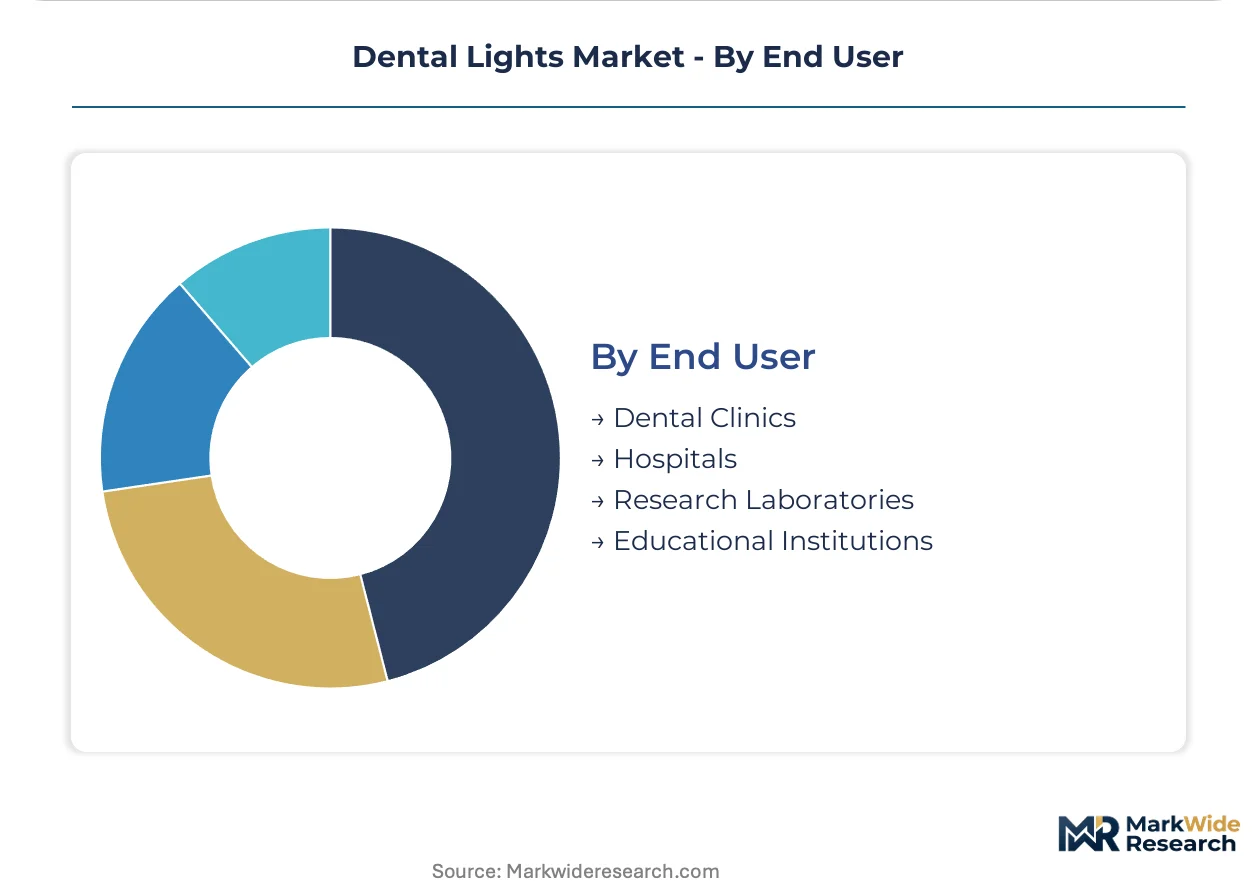
End User:
End-user segmentation illustrates how institutional purchasing power and patient volume shape the scale and sophistication of dental light deployments.
- Dental Clinics:These include private practices and Dental Service Organizations (DSOs), forming the largest end-user segment for general and specialized dental procedures. Private clinics in developed economies like Germany are consistently upgrading to advanced LED lights for enhanced diagnostic capabilities and patient comfort.
- Hospitals:Hospitals integrate dental lights within their oral and maxillofacial surgery departments, requiring robust, often specialized, illumination for complex procedures. Large medical centers in China are investing in high-performance lighting systems to support expanding surgical volumes and advanced treatment protocols.
- Research Laboratories:Research laboratories utilize dental lights for experimental setups and material analysis, demanding precise and consistent illumination for scientific study.
- Educational Institutions:Dental schools and universities employ various dental lights for student training and clinical demonstrations, often prioritizing durability and ease of use.
Dental Clinics represent the dominant demand source. Hospitals are increasing their investments in specialized lighting solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While developed markets prioritize high-specification LED lights for advanced procedures, emerging economies often balance initial investment costs with functional requirements. This dynamic creates distinct regional adoption patterns for dental illumination systems. Regulatory frameworks also influence market access and product development across different geographies.
United States
The United States market demonstrates strong demand for advanced LED lights, driven by extensive private clinic expansion and the integration of wireless control systems. Manufacturers must navigate stringent FDA approval processes for market entry and product commercialization. California's tech hubs actively foster innovation in smart dentistry solutions, including intelligent lighting.
Germany
Germany exhibits a consistent demand for high-specification dental lights, emphasizing enhanced diagnostic accuracy and superior color rendering. Compliance with CE marking under the Medical Device Regulation (MDR) is paramount for manufacturers operating in this market. Bavaria's robust medical device industry concentrates significant research and development efforts in optical engineering.
China
China's market is expanding due to substantial investments in hospital infrastructure and rising oral surgical volumes. Manufacturers must secure NMPA approval to ensure product compliance and market access. Shanghai and Shenzhen serve as crucial manufacturing and distribution hubs for dental equipment across the Asia-Pacific region.
Japan
Japanese dental practices prioritize advanced lighting systems for aesthetic treatment protocols and precise shade matching in restorative procedures. Adherence to PMDA standards is critical for medical device manufacturers in this highly regulated environment. Tokyo's advanced medical research centers actively integrate cutting-edge illumination technology into digital dentistry workflows.
Brazil
Brazilian demand for dental lights stems from the growth of private dental practices and the expansion of mobile dentistry services in rural areas. Compliance with ANVISA regulations is essential for manufacturers to enter and operate within the market. São Paulo serves as a major hub for dental equipment distribution and professional training across Latin America.
Dental Lights Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for dental lights. This market features a tiered competitive landscape with established multinational corporations dominating the premium segment. Strategic archetypes include comprehensive dental solution providers and niche optical engineering specialists. Dominant competitive moves involve portfolio diversification into adjacent dental equipment and targeted geographic expansion into emerging markets.
Among integrated dental equipment providers, A-dec Inc. exemplifies a strong brand presence, leveraging its established distribution channels, particularly within North American markets for its range of high-quality dental lights. Planmeca Oy, a Finnish company, occupies a distinct position as a specialist in comprehensive digital dentistry suites, where advanced lighting systems are seamlessly integrated for optimized clinical workflows. Dentsply Sirona, a multinational corporation with a vast global footprint, anchors a broad market presence with its extensive product portfolio and robust service network, catering to diverse dental segments across continents.
| Leading Market Players |
|---|
| A-dec Inc. |
| Midmark Corporation |
| Danaher Corporation |
| Planmeca Oy |
| DentalEZ |
| Flight Dental Systems |
| Dentsply Sirona |
| TPC Advanced Technology, Inc. |
| Dr. Mach GmbH |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized optical components, particularly high-CRI LEDs, directly influence the pricing power of manufacturers and shape the global supply chain, favoring vertically integrated players with stable component sourcing agreements.
Pricing Analysis
Project-based and contract-based pricing structures dominate the high-end dental lights market, particularly for large DSOs and hospital systems. Price differentiation stems from advanced features like high Color Rendering Index and specific regulatory certifications such as FDA approval or CE marking. Pricing softness reflects the increasing competition from integrated operatory units, which bundle lighting with other equipment. Smaller private clinics and emerging markets exhibit the highest price sensitivity for basic functional units, while premium DSOs prioritize feature sets and brand reputation over initial cost.
Supply Chain Analysis
The scarcity of optical engineering talent and specialized LED component fabrication acts as a chokepoint for advanced dental light production. Geographic supply concentration draws from China for mass manufacturing, Germany for precision optical components, and the United States for advanced R&D. Raw material dependencies include high-brightness LED chips, specialized lens arrays, and wireless communication modules. Regulatory shifts, such as stricter MDR requirements in Europe, pose a structural risk by increasing compliance burdens. Distribution runs through established dental equipment distributors and direct sales channels for major multinational players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a platform-economics inflection, driven by the increasing interoperability of dental lights within comprehensive digital dentistry ecosystems and practice management software.
For Market Incumbents: Secure long-term supply agreements for specialized optical components to mitigate supply chain volatility and maintain production stability. Deepen integration capabilities with leading digital dentistry platforms to counter the threat from all-in-one operatory systems. Invest in advanced R&D for AI-powered diagnostics and predictive maintenance features. Focus on expanding channel control in high-growth developed markets like the United States and Germany.
For New Entrants and Emerging Players: Streamlined CE marking for portable and specialized surgical lighting offers a certification fast-track into the European market. Target underpenetrated mobile dentistry services in rural communities and aged care facilities, leveraging cost-effective, battery-powered solutions. Focus on specialized surgical lighting with features like deeper focal points for oral maxillofacial procedures. A value-based go-to-market strategy emphasizing ease of use and local service support can build initial market share.
For Investors and Strategic Acquirers: Long-term, this sits as a technology consolidation play because digital integration and optical engineering expertise remain fragmented across the vendor landscape. Target niche optical engineering firms with strong intellectual property in advanced LED arrays or wireless control systems. The signal to watch is an increase in M&A activity focused on software companies specializing in dental practice management and imaging integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered diagnostic lighting systems | Enhances diagnostic accuracy and procedural efficiency for clinicians, driving premium adoption in advanced clinics. |
| Form strategic partnerships with digital dentistry platform providers | Ensures seamless integration and interoperability, expanding market reach within modern operatory workflows. |
| Expand into underpenetrated mobile dentistry markets | Captures new demand segments by providing flexible, portable illumination for underserved patient populations. |
| Invest in accelerated NMPA approval for new technologies | Facilitates rapid market entry and competitive advantage within China's expanding hospital and clinic infrastructure. |
| Acquire specialist firms focused on optical engineering | Strengthens core technical capabilities and proprietary technology, reducing reliance on external component suppliers. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. This involved discussions with dental practitioners, hospital procurement managers, R&D engineers, and regulatory affairs specialists. Secondary validation drew from FDA approval databases, CE marking registers, NMPA product lists, and dental association reports, triangulating insights from both top-down and bottom-up analyses.
Sensitivity analysis frames the forecast framework, modeling market behavior across the projection horizon. Segmentation dimensions included product type, installation type, technology, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates of advanced technologies. Key forecast inputs included LED component pricing trends and dental clinic expansion rates in developed and emerging economies.
Underlying assumptions cover current regulatory frameworks and technological trajectories, with deviation risk concentrated in unforeseen shifts in digital dentistry standards. Practitioners should keep alternative scenarios live as global medical device regulations and component supply chains evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Compressors Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market