
 Dental Radiology Equipment Market | 2026-2036
Dental Radiology Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Radiology Equipment Market Analysis
Japanese sensor manufacturers is shifting capacity toward CMOS-based digital intraoral detectors. Dentsply Sirona leverages its integrated CAD/CAM-imaging workflow to dominate North American dental group purchasing. Planmeca Oy anchors Nordic market share through its vertically controlled Helsinki production base. Envista Holdings Corporation differentiates via open-architecture software that interoperates with third-party practice management platforms.
Dental radiology equipment comprises ionizing and non-ionizing imaging systems engineered to capture maxillofacial anatomical structures with spatial resolutions typically ranging from 20 to 80 line pairs per millimeter, serving diagnostic, treatment planning, and post-operative verification functions across oral healthcare delivery. Cone beam systems command premium positioning in oral surgery and implantology workflows where three-dimensional volumetric data replaces multiple two-dimensional exposures. Digital sensors displace analog film in general dentistry applications, while CT scanners concentrate in hospital-affiliated maxillofacial units handling complex trauma and oncology cases.
The FDA enforces 21 CFR 1020.32 performance standards for dental x-ray equipment, mandating beam limitation and exposure control specifications that manufacturers must satisfy for 510(k) clearance. EMA's MDR framework imposes clinical evidence requirements on Class IIa and IIb radiological devices entering European economic area markets. Stakeholders must monitor evolving cybersecurity guidance from FDA and notified bodies as networked imaging systems become standard in connected dental practices.
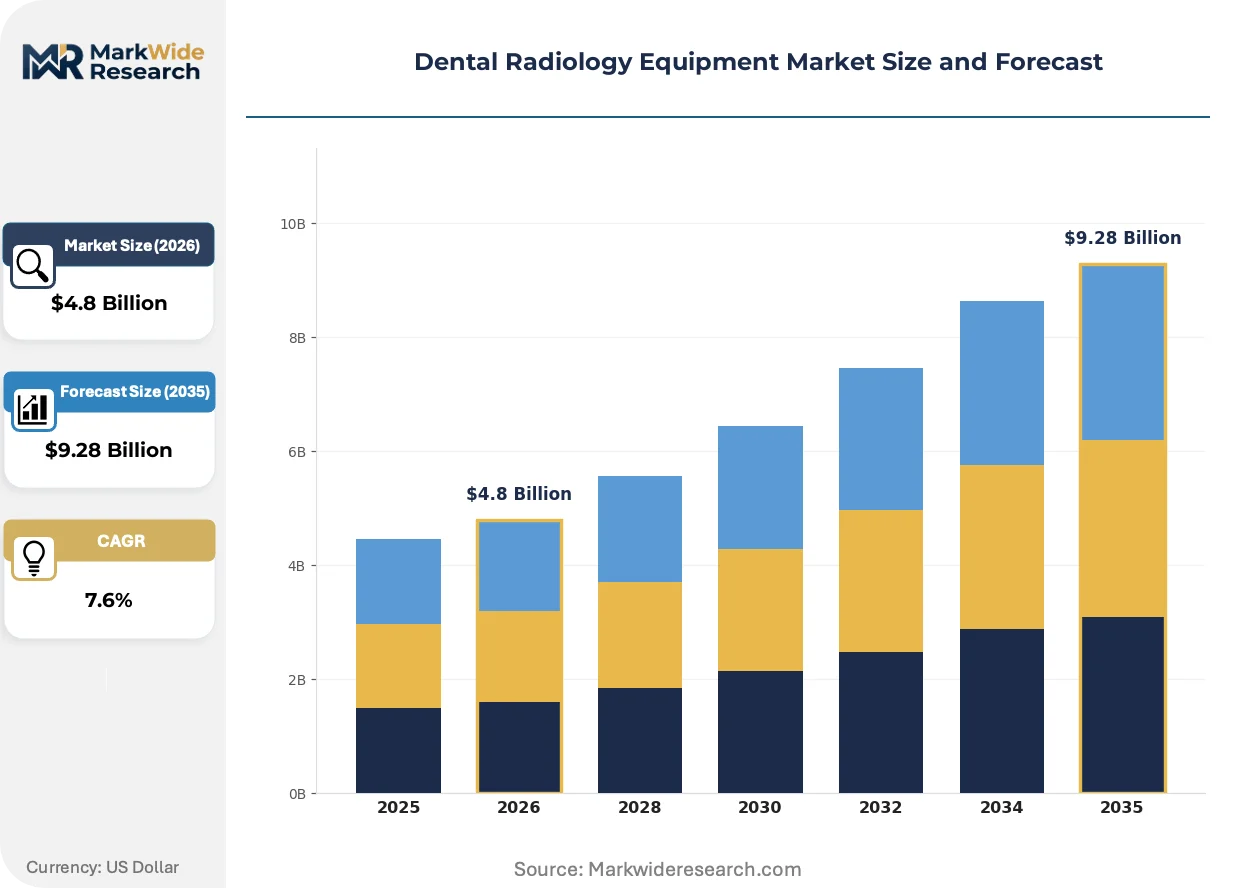
Market Dynamics
Digital intraoral sensors are compressing replacement cycles for analog film systems across dental practices, while CMOS detector manufacturing concentrates in East Asian component hubs. This technology transition is restructuring equipment procurement patterns and vendor relationships throughout oral healthcare delivery.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process for radiological devices accelerates product introductions and reduces time-to-revenue for manufacturers targeting United States dental clinics.
- German Dental Practice Consolidation:Bulk equipment procurement by consolidated practice groups in Germany generates volume demand for integrated imaging systems and multi-unit sensor deployments.
- CMOS Sensor Migration:Japanese manufacturers redirecting capacity toward CMOS-based digital intraoral detectors expand supply availability and drive unit cost reductions for dental radiology hardware.
Market Restraints
- Specialized Component Concentration:X-ray tube and high-voltage generator production concentrates among a limited set of European and Japanese suppliers, creating supply vulnerability for system integrators.
- EMA MDR Clinical Evidence Requirements:The European Medical Device Regulation imposes substantiated clinical performance documentation on Class IIa and IIb radiological devices, extending approval timelines and compliance costs.
- Capital Intensity Barrier:Cone beam computed tomography systems require substantial upfront investment, restricting adoption to hospital-affiliated maxillofacial units and specialized oral surgery centers.
Strategic Opportunities
- Connected Practice Cybersecurity Services:Networked imaging systems in United States dental clinics create demand for HIPAA-compliant data protection and vulnerability management solutions as FDA guidance evolves.
- Open-Architecture Software Integration:Interoperability with third-party practice management platforms enables equipment vendors to penetrate dental group purchasing organizations without mandating full ecosystem lock-in.
- Nordic Vertically Controlled Production:Helsinki-based manufacturing facilities serving Nordic markets demonstrate how captive component supply and final assembly integration can defend margin position against Asian cost competition.
Industry Challenges
- Radiation Safety Certification Complexity:State-level dental board requirements for operator training and equipment registration vary across United States jurisdictions, complicating national rollout strategies for manufacturers.
- Legacy Analog Workflow Integration:Hybrid practices maintaining film-based systems alongside digital sensors require transitional support infrastructure and staff retraining programs that strain vendor service capacity.
- Maxillofacial CT Scanner Installation Logistics:Hospital-affiliated units face extended construction timelines for radiation shielding retrofits and electrical infrastructure upgrades needed for high-output imaging systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Radiology Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, CT Scanners, Cone Beam Systems, Digital Sensors Technology: Analog, Digital, 3D Imaging, Fluoroscopy End User: Dental Clinics, Hospitals, Diagnostic Centers, Research Labs Application: Orthodontics, Periodontics, Oral Surgery, General Dentistry |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, Planmeca Oy, Carestream Dental LLC, VATECH, ACTEON Group, Danaher Corporation, Asahi Roentgen Ind. Co. Ltd, PreXion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Radiology Equipment Market Emerging Trajectories
Sensor technology maturation is compressing price premiums for digital intraoral systems while regulatory frameworks force cybersecurity hardening across connected dental infrastructure. These parallel developments are reshaping vendor competitive positioning and buyer procurement criteria.
CMOS-based digital intraoral detectors are consolidating market share from CCD alternatives in general dentistry applications. Solo and small-group dental practices in the United States and Western Europe are adopting these sensors at accelerated replacement cycles compared to earlier digital transitions. This technology consolidation is compressing mid-tier equipment margins and forcing vendors toward software-anchored differentiation.
EMA's Medical Device Regulation imposes post-market surveillance and clinical evidence maintenance obligations on dental radiology equipment marketed in European Economic Area jurisdictions. Manufacturers must establish systematic vigilance procedures and periodic safety update reporting that extend beyond legacy directive requirements. Class IIb cone beam systems face the most stringent documentation burdens, prompting some vendors to prioritize United States FDA clearance sequencing.
Dental group purchasing organizations are unbundling equipment procurement from exclusive service contracts that historically locked practices into single-vendor ecosystems. Large dental service organizations in the United States now negotiate direct sensor and software licenses separately from maintenance agreements. This purchasing pattern shift is most visible in consolidated markets like Texas and Florida, where multi-location practice groups command sufficient volume to dictate modular commercial terms.
Dental Radiology Equipment Market Segmentation
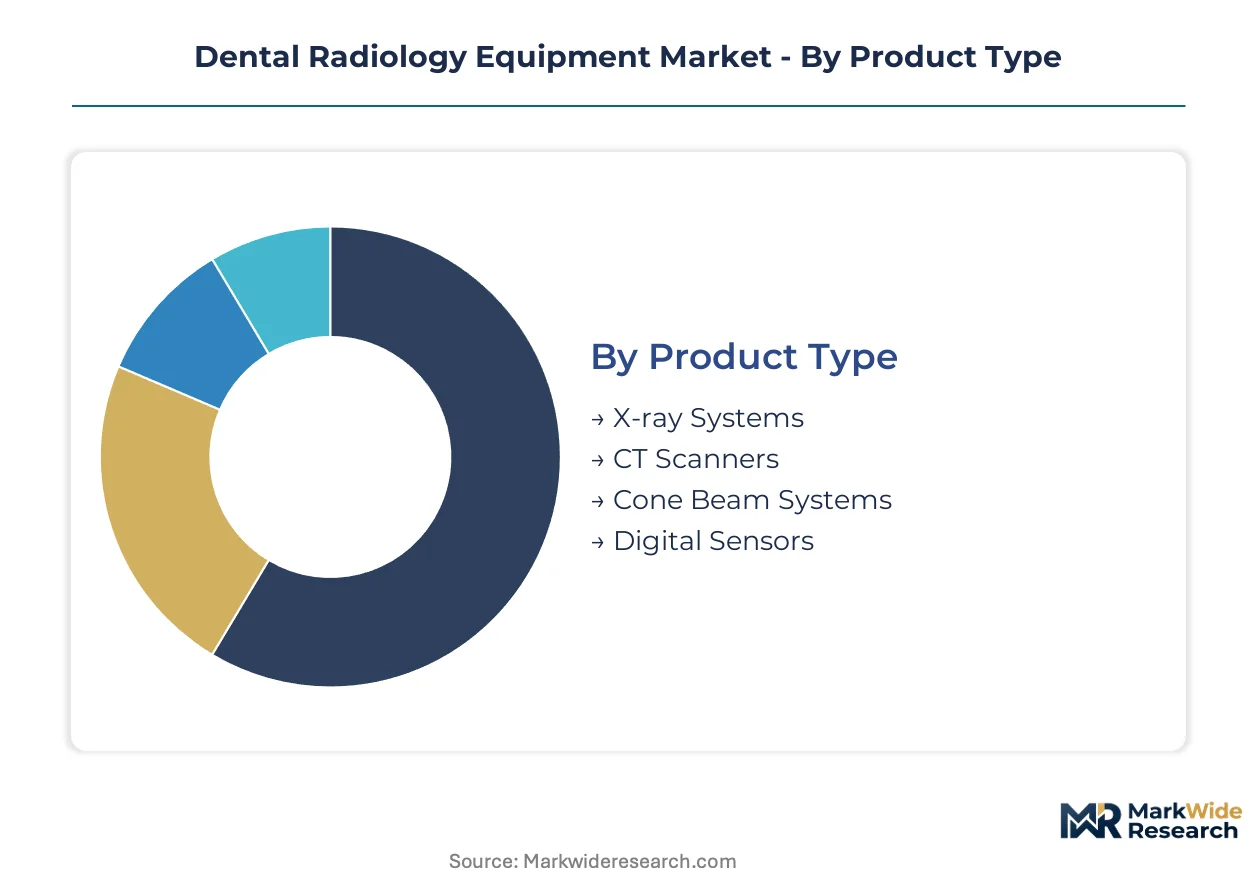
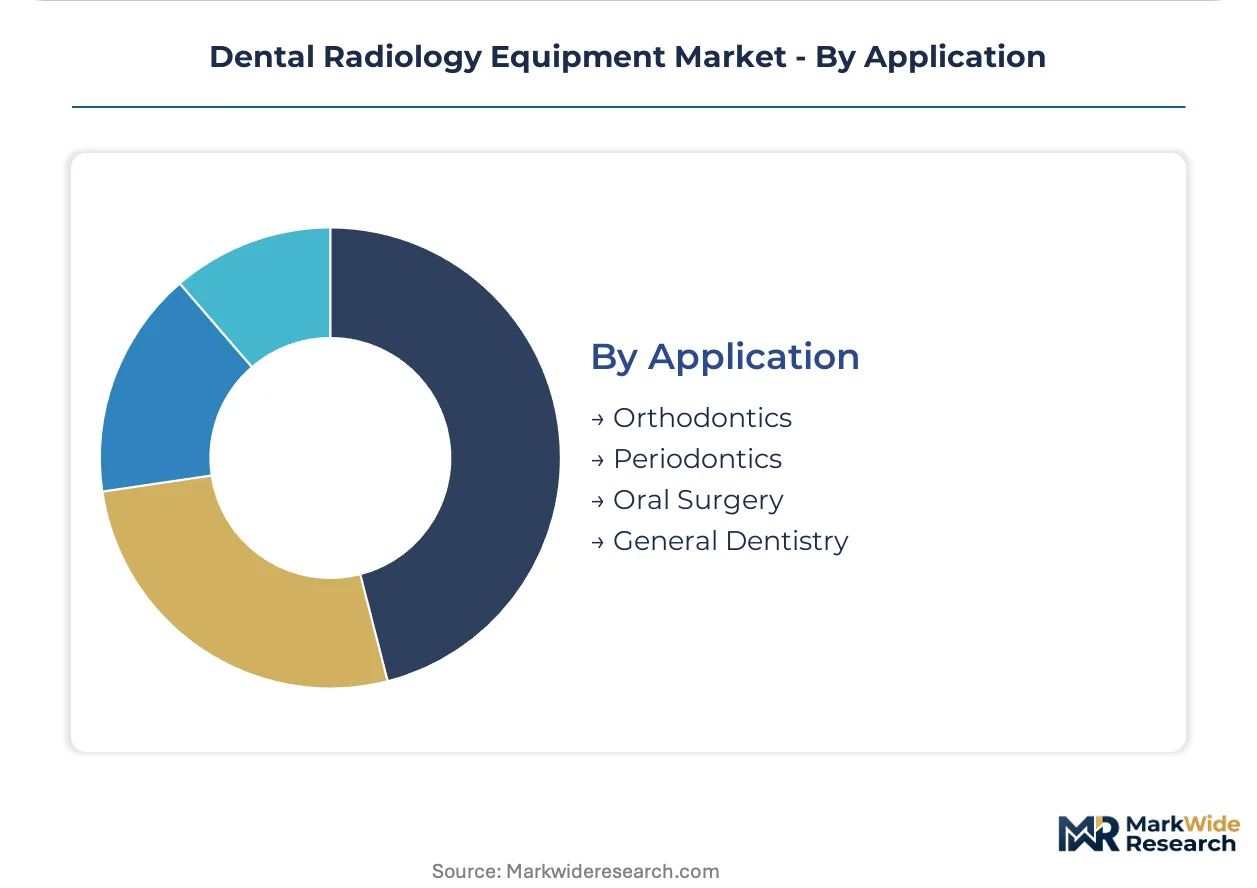
Segmentation reveals how dental practices prioritize capital deployment across imaging modalities. Equipment replacement cycles vary dramatically by technology maturity and clinical application intensity.
Product Type:
Upgrade timelines diverge sharply between established digital sensors and emerging cone beam platforms, with replacement urgency driven by reimbursement alignment and surgical procedure volume.
- X-ray Systems:Conventional intraoral and panoramic units remain the installed base foundation across solo dental practices. Demand concentrates in United States metropolitan markets where state dental boards enforce radiation safety recertification on 10-15 year equipment lifecycles.
- Cone Beam Systems:Volumetric imaging platforms capture maxillofacial anatomy with sub-millimeter isotropic resolution. Oral surgery centers in Germany and implantology-focused group practices in Florida drive procurement as three-dimensional planning becomes standard for complex cases.
- CT Scanners:Hospital-affiliated maxillofacial units deploy high-output systems for trauma and oncology workflows.
- Digital Sensors:CMOS-based intraoral detectors displace analog film in general dentistry settings.
Digital Sensors sits at the top of the volume ranking, with Cone Beam Systems climbing the fastest.
Technology:
Cost tier stratification separates premium 3D platforms from commoditized digital capture, with margin concentration following technical complexity rather than unit shipments.
- Digital:Solid-state detectors with direct radiographic conversion dominate new equipment procurement. Dental clinics in Texas and California prioritize sensor upgrades that integrate with cloud-based practice management platforms.
- 3D Imaging:Cone beam reconstruction algorithms and volumetric rendering engines command substantial software licensing premiums. Oral surgery centers in academic medical centers require FDA-cleared iterative reconstruction for implant navigation accuracy.
- Analog:Film-based systems persist in rural practices and developing market segments with limited capital budgets.
- Fluoroscopy:Real-time dynamic imaging serves specialized temporomandibular joint assessment and guided biopsy procedures.
Digital commands absolute volume leadership, while 3D Imaging expands most quickly through surgical application penetration.
End User:
Customer type determines procurement authority structure, with consolidated dental service organizations extracting volume discounts unavailable to independent practitioners.
- Dental Clinics:Solo and small-group practices generate the highest unit demand for intraoral sensors and panoramic systems. German dental practice consolidation drives bulk equipment procurement with standardized imaging protocols across multi-location networks.
- Hospitals:Academic medical centers and trauma centers deploy CT scanners and cone beam systems for complex maxillofacial reconstruction. Installation requires radiation shielding retrofits and electrical infrastructure upgrades that extend deployment timelines.
- Diagnostic Centers:Independent imaging facilities serve referral markets with specialized interpretation services.
- Research Labs:University dental schools and biomaterials laboratories acquire high-resolution micro-CT systems for ex vivo specimen analysis.
Dental Clinics anchor volume demand, with Hospitals posting the steepest expansion trajectory through trauma center network expansion.
Application:
Clinical specialization intensity dictates equipment specification requirements, with surgical disciplines demanding volumetric data that general restorative workflows cannot justify.
- Oral Surgery:Implantology and orthognathic procedures require sub-millimeter spatial accuracy for surgical guide fabrication. United States oral surgery group practices in Florida and Texas prioritize cone beam systems with integrated CAD/CAM export capabilities.
- Orthodontics:Cephalometric analysis and treatment monitoring drive panoramic and cephalometric unit deployment. Clear aligner therapy expansion accelerates digital impression and radiographic workflow integration in suburban practice clusters.
- Periodontics:Bone loss assessment and regenerative procedure planning utilize periapical and bitewing radiography.
- General Dentistry:Routine caries detection and restorative verification sustain intraoral sensor replacement cycles.
General Dentistry maintains volume dominance, though Oral Surgery gains share fastest through implantology procedure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental practice consolidation generates bulk equipment procurement that contrasts sharply with the fragmented solo-practice landscape dominating United States metropolitan markets. Equipment replacement urgency varies dramatically by regulatory enforcement intensity and reimbursement alignment across national healthcare systems.
United States
Texas and Florida dental service organizations negotiate modular procurement contracts unbundling sensors from maintenance agreements. FDA's 510(k) clearance pathway accelerates product introductions for manufacturers targeting clinic networks. Houston and Dallas-Fort Worth anchor multi-location practice consolidation driving standardized imaging protocol deployment.
Germany
Bulk equipment procurement by consolidated dental groups generates volume demand for integrated imaging systems and multi-unit sensor fleets. EMA's MDR framework imposes clinical evidence requirements on Class IIa and IIb radiological devices entering European markets. Munich and Berlin dental practice networks prioritize standardized cone beam systems across acquired locations.
Japan
CMOS detector manufacturing concentrates in East Asian component hubs serving domestic and export markets. METI industrial policy supports precision electronics manufacturing for medical device applications. Osaka and Nagoya sensor producers redirect capacity toward dental radiology hardware as consumer electronics demand softens.
China
Domestic equipment procurement accelerates as NMPA streamlines review pathways for domestically manufactured radiological devices. Hospital-affiliated maxillofacial units in tier-one cities drive CT scanner demand for trauma and oncology workflows. Shanghai and Beijing academic medical centers deploy high-output systems requiring radiation shielding infrastructure investment.
United Kingdom
Clear aligner therapy expansion accelerates digital impression and radiographic workflow integration in suburban practice clusters. MHRA post-Brexit regulatory autonomy creates divergent approval timelines from EMA-coordinated European processes. London and Southeast England orthodontic group practices prioritize panoramic and cephalometric unit deployment.
Dental Radiology Equipment Market Vendor Landscape
European producers anchor the premium-system tier; East Asian component specialists hold supply-side leverage over detector manufacturing. Market structure concentrates among integrated imaging-workflow vendors and modular equipment suppliers competing for dental group purchasing organization contracts. Three archetypes dominate: full-ecosystem integrators, open-architecture platform vendors, and component-specialist system integrators. Capacity expansion in CMOS sensor fabrication and strategic partnerships for software interoperability represent the dominant competitive vectors reshaping vendor positioning.
Within the integrated-workflow tier, Dentsply Sirona and Planmeca Oy exemplify geographic anchoring strategies—North American and Nordic respectively—defending market position through captive production control. Envista Holdings Corporation occupies a position representing open-architecture differentiation, enabling third-party practice management platform interoperability without mandating full ecosystem commitment. These three entities collectively illustrate how vendor competitive strategy diverges between ecosystem lock-in and modular flexibility approaches.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| Planmeca Oy |
| Carestream Dental LLC |
| VATECH |
| ACTEON Group |
| Danaher Corporation |
| Asahi Roentgen Ind. Co. Ltd |
| PreXion Inc. |
| Others |
Supply Flow & Price Mechanics
CMOS sensor manufacturing migration from CCD-based legacy production to solid-state detector fabrication in Japanese and South Korean facilities is compressing unit economics for digital intraoral systems while simultaneously concentrating supply leverage among East Asian component specialists. This dual restructuring forces system integrators to absorb margin pressure or accelerate backward integration into detector assembly.
Pricing Analysis
Capacity additions in Japan and South Korea are reshaping price floors for CMOS-based digital sensors, enabling tiered pricing stratification across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling. Pricing pressure stems from German dental group purchasing organizations negotiating unbundled procurement contracts. Solo practices in rural United States markets exhibit highest price sensitivity; hospital-affiliated maxillofacial units show least.
Supply Chain Analysis
Direct-to-dental-clinic channels handle high-volume sensor demand from consolidated practice groups, while distributor-mediated routes serve fragmented solo practitioners. Geographic supply concentrates in Japan, South Korea, and Germany. Raw material dependencies include silicon wafers, scintillator crystals, and high-voltage generator assemblies. Single-source vulnerability in x-ray tube production creates supply risk. Distribution runs through dental group purchasing organizations and specialized medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental radiology equipment market compounds steadily as digital sensor replacement cycles compress and oral surgery procedure volumes expand. Equipment vendors and buyers operate within a regulatory environment that rewards clearance velocity and interoperability investment.
For Market Incumbents: Deploy open-architecture software licensing to neutralize ecosystem lock-in threats from full-stack competitors. Capture CMOS detector supply through joint ventures with Japanese component houses. Strengthen service infrastructure in Texas and Florida to defend against modular procurement trends. For New Entrants and Emerging Players: The mid-tier pricing gap between premium cone beam systems and economy panoramic units offers entry opportunity for hybrid 2D-3D platforms. Target orthodontic group practices in suburban United Kingdom clusters with cloud-integrated cephalometric workflows. Pursue CE marking ahead of FDA submission to accelerate European revenue traction. For Investors and Strategic Acquirers: Roll-up economics work for dental software specialists because practice management platform fragmentation creates consolidation arbitrage. Five-to-ten year viability favors vendors with recurring revenue streams over pure hardware plays. Monitor FDA cybersecurity guidance evolution as inflection signal for compliance-cost winners.| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Supply Partnership | Secures detector allocation from Japanese manufacturers for North American clinic networks. |
| FDA 510(k) Cybersecurity Hardening | Positions imaging systems ahead of evolving connected-device guidance from regulators. |
| Open-Architecture Software Launch | Enables interoperability with third-party practice management platforms without ecosystem lock-in. |
| German Dental Group Contracting | Captures bulk procurement volumes from Munich and Berlin consolidation networks. |
| Cone Beam CAD/CAM Integration | Links volumetric imaging to surgical guide fabrication for Florida implantology practices. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental equipment procurement managers, biomedical engineers at hospital-affiliated maxillofacial units, GPO contracts managers, and regulatory affairs specialists at device manufacturers with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and dental practice consolidation records. Bottom-up sensor shipment estimates and top-down equipment revenue analysis were triangulated.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation by product type, technology tier, end-user category, and clinical application. CAGRs were derived from fitted growth curves applied to replacement cycle data and procedure volume trends. Forecast inputs included German dental practice consolidation rates and United States clear aligner therapy expansion.
The model assumes a particular technology adoption path; alternative pathways for CMOS sensor penetration would alter the outlook. Forecasts reflect base-case assumptions regarding regulatory clearance timelines and reimbursement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Engine Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental CAM Milling Machine Market