
 Dental Calipers Market | 2026-2036
Dental Calipers Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Calipers Market Analysis
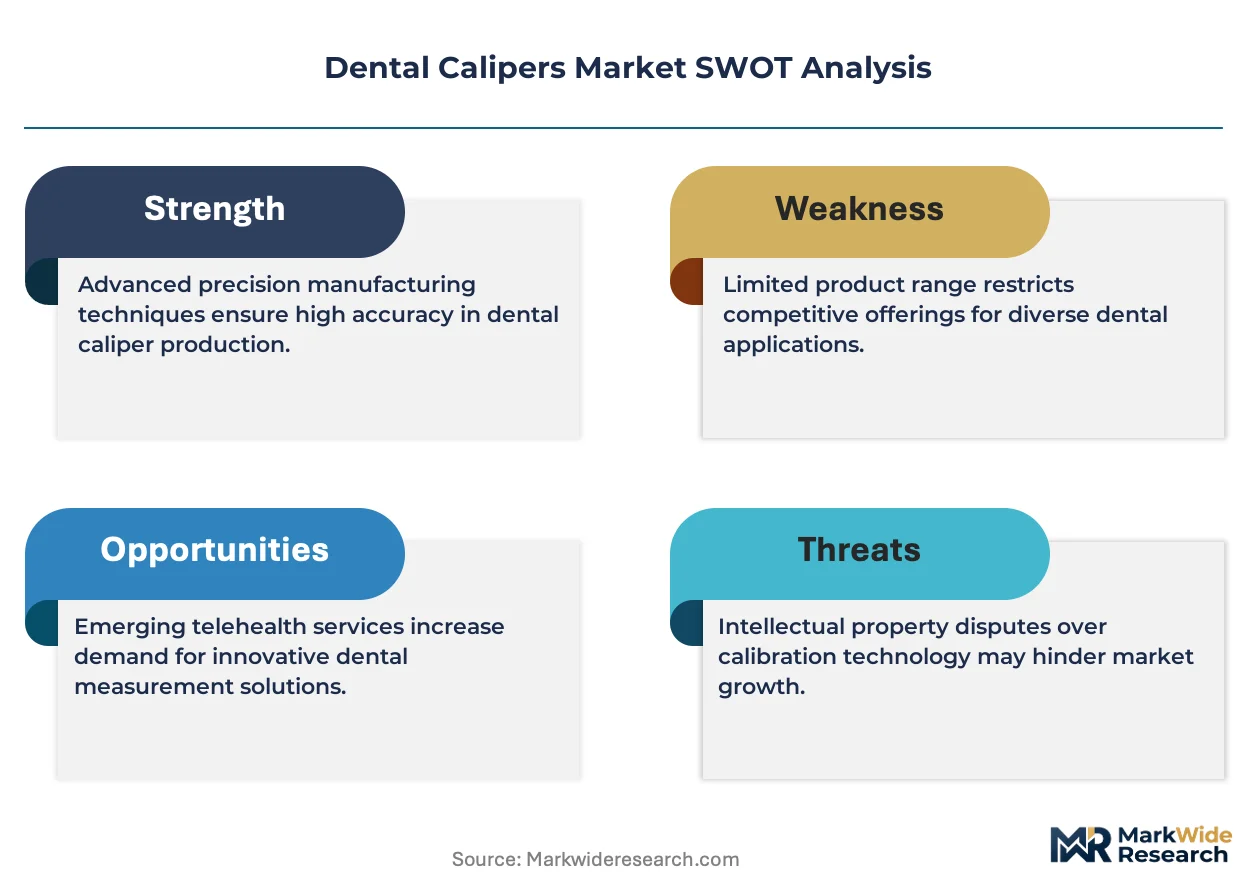
ISO 13485 certification is reorganizing competitive tiers in dental calipers, forcing smaller manufacturers toward contract manufacturing or exit. Kerr Corporation leverages its restorative instrument portfolio to sustain shelf presence in North American dental distributors. Henry Schein Inc. anchors procurement volume through its practice-solutions bundle, while Dentsply Sirona competes via integrated digital workflow ecosystems that incorporate measurement tools.
Dental calipers are precision instruments designed to measure intraoral dimensions such as intercanine width, arch length, and tooth size discrepancy with accuracy typically within 0.1 mm. Stainless steel and carbon fiber variants serve distinct clinical purposes, with manual calipers dominating orthodontic practices due to cost reliability and digital calipers capturing growth in prosthodontics where CAD/CAM integration demands electronic data capture. Specialty calipers for craniofacial analysis occupy a narrow but high-margin niche in research institutions and academic hospitals.
FDA 510(k) premarket notification and EU MDR Class I device requirements shape product development timelines and labeling obligations for manufacturers seeking dual-market access. ISO 13485 quality management systems and CE marking under MDR specifications further stratify supplier eligibility, particularly for digital calipers with embedded software. Stakeholders must monitor evolving harmonization between FDA cybersecurity guidance and EU MDR software validation standards to anticipate compliance cost shifts.
Market Dynamics
ISO 13485 certification requirements are restructuring competitive tiers across dental calipers, forcing smaller manufacturers toward contract manufacturing relationships or market exit while elevating quality thresholds for cross-border suppliers seeking dual-market access.
Growth Catalysts
- CAD/CAM Integration:Prosthodontics practices are accelerating digital caliper procurement to feed measurement data directly into chairside milling workflows, compressing restoration turnaround times.
- Clear Aligner Scaling:Orthodontic labs in Germany and Japan are expanding digital caliper procurement as transparent aligner production volumes multiply.
- Fee-for-Service Reimbursement:United States dental clinics maintain instrument refresh cycles through favorable reimbursement structures that support periodic capital equipment replacement.
Market Restraints
- Stainless Steel Price Volatility:Input cost fluctuations for surgical-grade alloys compress margins for manual caliper producers locked into distributor pricing agreements.
- EU MDR Compliance Burden:Class I device reclassification and enhanced technical documentation requirements extend product development timelines for European market entry.
- Intraoral Scanner Substitution:Direct digital impression systems are capturing measurement functions previously served by mechanical calipers in select restorative applications.
Strategic Opportunities
- Academic Hospital Niche:Craniofacial analysis calipers command premium positioning in research institutions with specialized measurement protocols.
- Cybersecurity Harmonization:Anticipated alignment between FDA software validation guidance and EU MDR embedded system standards creates first-mover advantage for compliant suppliers.
- Carbon Fiber Differentiation:Lightweight radiolucent variants are opening procedural applications where metal interference distorts imaging workflows.
Industry Challenges
- Metrology Skill Deficit:Calibration technician shortages delay ISO 13485 audit readiness for mid-tier manufacturers expanding digital product lines.
- Legacy System Integration:Digital caliper data formats require middleware development to interface with established practice management software in independent clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Calipers Market |
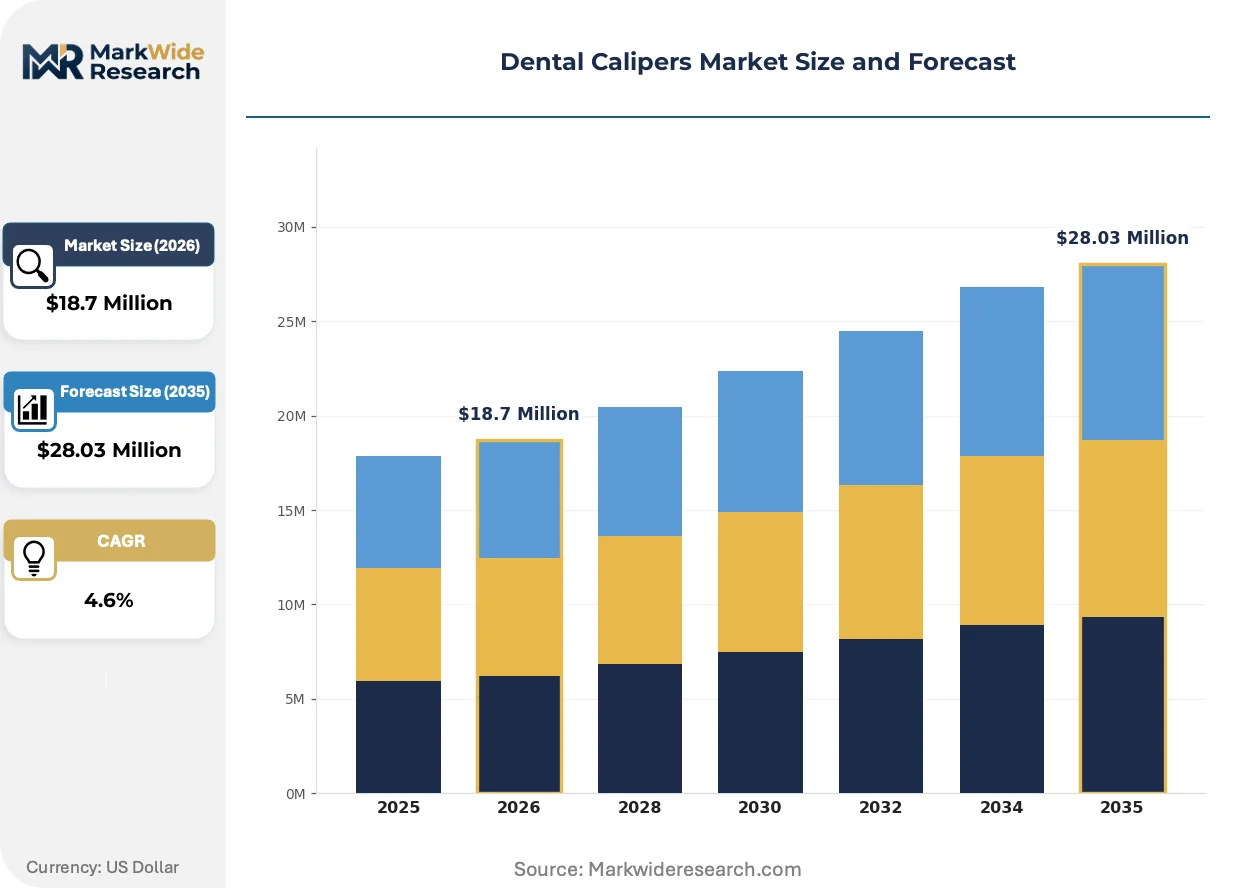
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Calipers, Digital Calipers, Heavy-Duty Calipers, Specialty Calipers Material: Stainless Steel, Plastic, Aluminum, Carbon Fiber Application: Orthodontics, Periodontics, Dental Measurements, Prosthodontics End User: Dental Clinics, Orthodontic Labs, Research Institutions, Educational Facilities |
| Companies Covered | A. Schweickhardt, AR INSTRUMED DEUTSCHLAND, ASA DENTAL, BTI Biotechnology Institute, Renfert, Kerr Corporation, Dentsply Sirona, Henry Schein Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Calipers Market Emerging Trajectories
Measurement digitization is redrawing competitive boundaries across dental calipers, with electronic data capture capabilities becoming the primary axis of product differentiation and procurement preference.
Bluetooth-enabled digital calipers with direct electronic health record transmission are displacing standalone measurement devices in group dental practices. Large multi-site operators in the United States are mandating interoperable instruments to standardize quality metrics across locations. This connectivity requirement is compressing demand for basic digital models lacking API compatibility, forcing manufacturers to prioritize software development over hardware refinement.
EU MDR software validation standards are tightening documentation burdens for calipers with embedded measurement algorithms. Manufacturers must now submit clinical evidence supporting algorithm accuracy claims, extending regulatory timelines by twelve to eighteen months for new product introductions. Digital caliper suppliers with existing MDR technical files are leveraging this friction to defend shelf position against late entrants.
Instrument-as-a-service models are emerging in corporate dental chains, unbundling capital acquisition from maintenance and calibration obligations. Henry Schein Inc. and major distributors are piloting subscription arrangements that include periodic replacement and compliance documentation. This procurement evolution is most visible in United States dental service organizations consolidating supplier relationships across fifty-plus practice locations.
Dental Calipers Market Segmentation
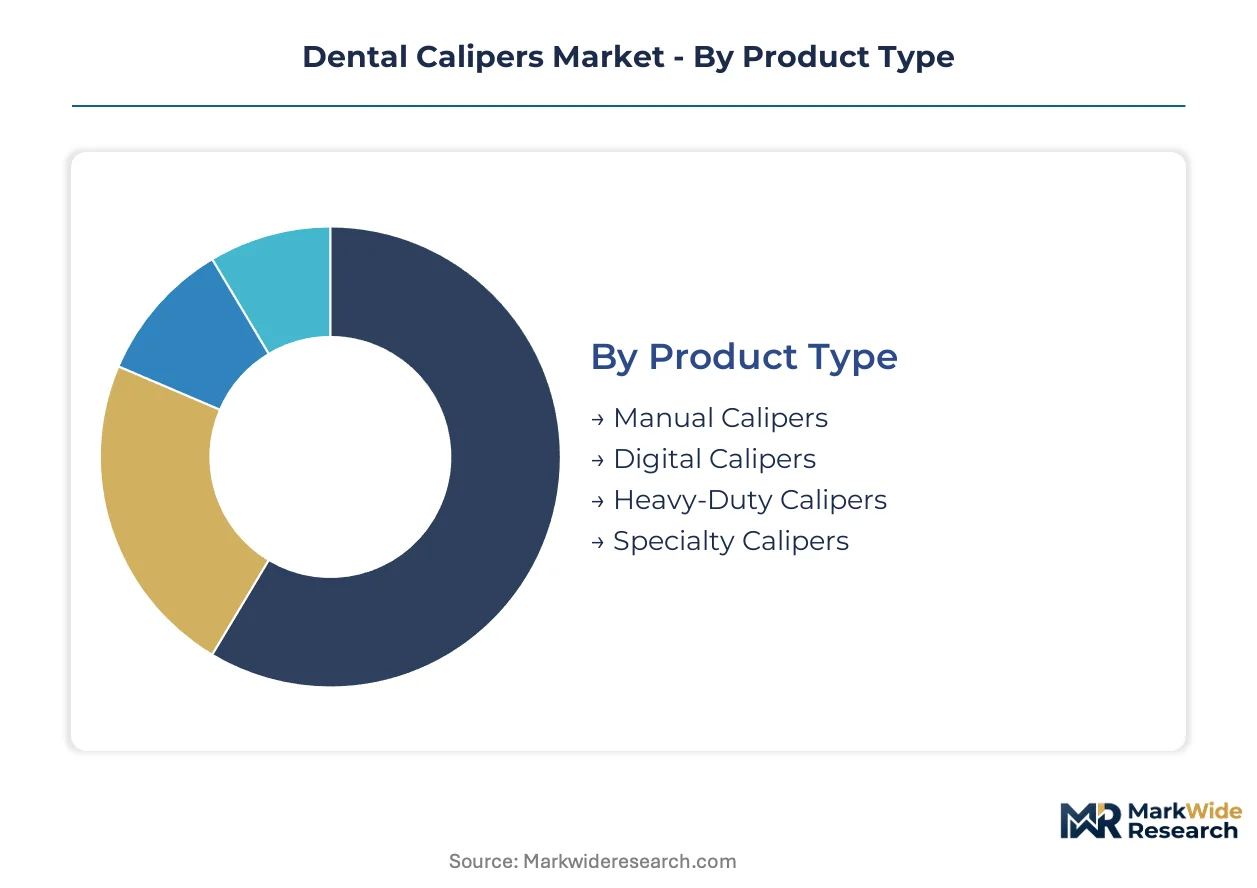
Dental calipers fragment across four distinct dimensions that shape procurement patterns and margin capture. Product type and material composition determine technical specifications and price positioning, while application and end-user concentration direct distribution channel priorities.
Product Type:
Margin pools concentrate in digital variants where embedded software and connectivity command premium pricing, while manual calipers defend volume through cost reliability in high-turnover environments.
- Manual Calipers:Spring-loaded or vernier-scale instruments fabricated from stainless steel deliver 0.1 mm accuracy without power dependency. Demand clusters in orthodontic practices across the United States where instrument refresh cycles align with reimbursement schedules and resident training programs require durable, low-maintenance tools.
- Digital Calipers:Electronic measurement modules with LCD displays and data output ports enable direct CAD/CAM workflow integration. Prosthodontics practices in Germany and Japan are scaling procurement as chairside milling adoption accelerates and clear aligner production demands precise electronic capture of intraoral dimensions.
- Heavy-Duty Calipers:Reinforced frames and extended jaw spans accommodate craniofacial measurement protocols in academic medical centers.
- Specialty Calipers:Boley gauges and Iwanson gauges serve niche orthodontic applications with standardized tip geometries for bracket positioning.
The dominant share belongs to Manual Calipers, while Digital Calipers is closing the gap fastest.
Material:
Cost tier stratification separates surgical-grade alloys from lightweight composites, with radiolucency properties opening procedural applications where imaging interference must be eliminated.
- Stainless Steel:Surgical-grade 420 or 440A alloys provide corrosion resistance and autoclave sterilization compatibility. Manual caliper producers in distributor pricing agreements absorb input cost volatility while defending shelf presence against polymer alternatives.
- Carbon Fiber:Radiolucent carbon fiber composites eliminate metal artifact in CBCT and panoramic imaging workflows. Research institutions with specialized craniofacial analysis protocols are commanding premium positioning for lightweight variants that maintain dimensional stability under thermal cycling.
- Plastic:Single-use or limited-cycle polymers serve infection control protocols in high-throughput screening environments.
- Aluminum:Anodized aluminum balances weight reduction with structural rigidity for portable field kits.
Stainless Steel retains volume leadership, though Carbon Fiber is expanding most quickly in premium research segments.
Application:
Customer type concentration varies sharply across clinical disciplines, with orthodontic volume contrasting prosthodontic value per unit.
- Orthodontics:Arch length analysis, intercanine width measurement, and tooth size discrepancy calculation dominate caliper utilization. Practices in the United States maintain standardized instrument sets for resident training and private practice, with fee-for-service reimbursement supporting periodic replacement.
- Prosthodontics:Crown margin delineation, occlusal clearance verification, and CAD/CAM input data generation require electronic measurement capture. German and Japanese labs scaling clear aligner production are driving digital caliper procurement for direct workflow integration.
- Periodontics:Mucogingival junction mapping and attached gingiva width assessment utilize modified tip geometries.
- Dental Measurements:General diagnostic protocols including overjet and overbite quantification span multiple specialties.
Orthodontics holds the installed base advantage, yet Prosthodontics is gaining share fastest through digital upgrade cycles.
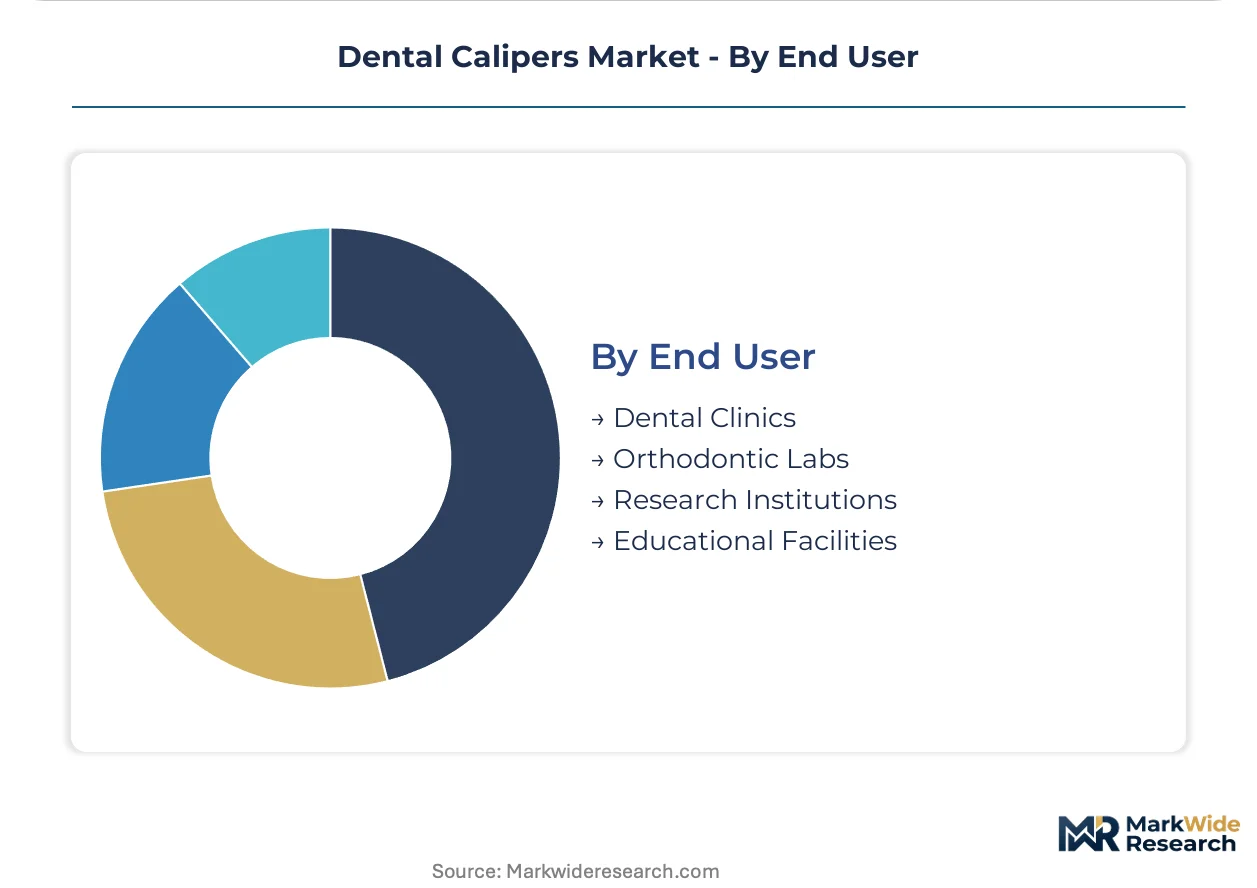
End User:
Procurement authority and volume scale diverge between independent clinical operators and consolidated institutional purchasers.
- Dental Clinics:Independent and group practice operators in the United States drive instrument refresh through capital equipment cycles tied to reimbursement timing. Multi-site dental service organizations are mandating interoperable digital instruments to standardize quality metrics across fifty-plus locations.
- Orthodontic Labs:Clear aligner production facilities in Germany and Japan are expanding digital caliper procurement as transparent aligner volumes multiply and measurement precision directly impacts fit accuracy.
- Research Institutions:Academic hospitals with craniofacial analysis protocols command specialty caliper variants with premium positioning.
- Educational Facilities:Dental schools require durable manual instruments for preclinical training laboratories.
Dental Clinics represent the largest addressable base, while Orthodontic Labs is climbing the fastest on aligner production scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance tightening and EU MDR reclassification are reshaping where dental caliper suppliers concentrate compliance investment and manufacturing footprint.
United States
Fee-for-service reimbursement structures support instrument refresh cycles in independent and group dental practices. FDA 510(k) premarket notification requirements for electronic measuring devices elevate quality thresholds for cross-border suppliers. Multi-site dental service organizations in Texas and Florida are mandating interoperable digital instruments to standardize quality metrics across consolidated networks.
Germany
Orthodontic labs in Bavaria and Baden-Württemberg are scaling digital caliper procurement to feed clear aligner production volumes. EU MDR Class I device reclassification and enhanced technical documentation requirements extend development timelines for European market entry. The Stuttgart industrial cluster anchors precision instrument manufacturing with established metrology supply chains serving dental device producers.
Japan
Clear aligner production facilities in the Kanto region around Tokyo are expanding measurement instrument procurement as transparent aligner volumes multiply. METI industrial standards and PMDA quality frameworks shape product development obligations for domestic and imported devices. Osaka-based orthodontic labs are integrating digital calipers directly into CAD/CAM chairside milling workflows.
China
Domestic dental clinic chains in Shanghai and Beijing are upgrading from manual to electronic measurement tools as prosthodontic service lines expand. NMPA medical device registration requirements and GB standards compliance create regulatory friction for imported digital calipers. The Yangtze River Delta manufacturing corridor supplies stainless steel instrument components to regional caliper assemblers.
India
Private dental colleges in Maharashtra and Karnataka are driving demand for durable manual calipers in preclinical training laboratories. CDSCO medical device rules and BIS quality certification requirements stratify supplier eligibility for institutional procurement. The Delhi-NCR corridor hosts distributor networks consolidating instrument imports for North Indian dental markets.
Dental Calipers Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 13485 quality management systems separating compliant suppliers from contract-manufacturing dependents. The vendor base concentrates around three strategic archetypes: diversified dental conglomerates bundling instruments into practice solutions, precision instrument specialists defending niche measurement protocols, and contract manufacturers serving private-label distributors. M&A activity targets digital calibration capabilities, while strategic partnerships with orthodontic lab networks secure volume commitments for electronic data capture instruments.
Among Germany-based precision instrument fabricators, A. Schweickhardt and AR INSTRUMED DEUTSCHLAND exemplify the specialist archetype serving orthodontic and prosthodontic protocols with established metrology credentials. Henry Schein Inc. occupies a position on the distribution-led vector, anchoring procurement volume through practice-solutions bundles that consolidate supplier relationships across North American dental service organizations.
| Leading Market Players |
|---|
| A. Schweickhardt |
| AR INSTRUMED DEUTSCHLAND |
| ASA DENTAL |
| BTI Biotechnology Institute |
| Renfert |
| Kerr Corporation |
| Dentsply Sirona |
| Henry Schein Inc. |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price differentiation in dental calipers, creating parallel barriers where uncertified manufacturers face contract manufacturing or exit while certified suppliers command premium positioning across North American and European procurement channels.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant premium tiers and uncertified economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, CE marking under EU MDR, and after-sales calibration bundling. Cost compression in manual stainless steel variants is intensifying because surgical-grade alloy price volatility transfers directly to producers locked into distributor pricing agreements. Orthodontic labs in Germany and Japan show lowest price sensitivity due to clear aligner production scaling, while independent dental clinics in India face highest sensitivity given capital equipment refresh constraints.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for precision instrument components sourced from East Asian manufacturing hubs. Supply concentration centers on Germany, Japan, and China, with Stuttgart and Osaka anchoring high-precision fabrication while the Yangtze River Delta supplies stainless steel instrument components. Raw material dependencies span surgical-grade 420/440A alloys, carbon fiber composites, and electronic measurement modules. Single-source vulnerability persists for embedded software chipsets. Distribution runs through Henry Schein Inc. and regional dental distributors consolidating procurement for multi-site dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental calipers are entering a cyclical recovery phase driven by orthodontic lab expansion for clear aligner production, which refreshes instrument replacement demand following pandemic-deferred capital expenditure cycles.
For Market Incumbents: Fortify calibration service capabilities to defend against instrument-as-a-service subscription models piloted by major distributors. Deepen backward integration into surgical-grade alloy sourcing to offset stainless steel price volatility compressing manual caliper margins. Prioritize M&A targeting digital calibration technology to accelerate FDA 510(k) clearance timelines for next-generation electronic measurement devices. For New Entrants and Emerging Players: Differentiate on carbon fiber radiolucency for craniofacial research protocols in academic medical centers, where metal artifact elimination commands premium positioning absent from mainstream orthodontic procurement. Target orthodontic labs in Japan scaling clear aligner production, as these facilities prioritize electronic data capture integration over brand heritage. Pursue direct CAD/CAM workflow partnerships rather than distributor channel dependence. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrument specialists holding ISO 13485 credentials but lacking digital product development bandwidth. Long-term viability hinges on software validation capabilities aligning FDA cybersecurity guidance with EU MDR embedded system standards. Monitor harmonization progress between FDA and EU MDR software requirements as inflection indicator for compliance cost shifts favoring first-mover suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Elevates supplier eligibility for dual-market FDA and EU MDR access while defending premium pricing tiers. |
| Bluetooth-Enabled Digital Caliper Launch | Captures group dental practice procurement mandates for interoperable instruments with EHR transmission capability. |
| Orthodontic Lab Partnership Program | Secures volume commitments from clear aligner production facilities in Germany and Japan scaling measurement instrument procurement. |
| Instrument-as-a-Service Model Pilot | Unbundles capital acquisition from calibration obligations for dental service organizations consolidating fifty-plus locations. |
| Carbon Fiber Material Differentiation | Opens craniofacial analysis applications in academic hospitals where radiolucency eliminates CBCT imaging interference. |
Methodological Framework
The analysis maps manual calipers, digital calipers, heavy-duty variants, and specialty gauges, each validated through orthodontic lab procurement managers, prosthodontics practice owners, dental distributor category buyers, and biomedical engineering directors at academic medical centers. Primary interview findings triangulate against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and GPO pricing benchmarks. Bottom-up segment sizing and top-down market reconciliation ensure consistency across product type, material composition, application, and end-user dimensions.
External benchmark validation against customs trade data for surgical-grade alloy imports and dental instrument export statistics from Germany and Japan confirmed projection consistency. The analytical framework models product type, material grade, clinical application, and end-user concentration across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by reimbursement timing in United States fee-for-service markets and clear aligner production scaling in German and Japanese orthodontic labs.
Decision-makers should treat outputs as directional under assumptions of sustained CAD/CAM adoption in prosthodontics and continued clear aligner volume expansion; material deviation in intraoral scanner substitution rates or EU MDR compliance timeline extensions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Splints Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Needle Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Handpieces Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Global Dental Burs Market
Dental Devices
Dental 3D Printing Market