
 Dental Equipment and Consumables Market | 2026-2036
Dental Equipment and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Equipment and Consumables Market Analysis
Corporate dental chains and multi-location DSOs are gaining procurement share while independent practices is bifurcating the buyer landscape into volume-contracting and equipment-leasing camps. Dentsply Sirona leverages its integrated CAD/CAM workflow to anchor premium positioning across chairside milling and intraoral scanning. Straumann Group specializes in implantology and digital prosthetics, sustaining margin-rich recurring revenue from surgical guides and abutment libraries.
Dental equipment and consumables encompass electromechanical instruments, radiographic systems, treatment furniture, and single-use or short-lifecycle materials employed in oral health diagnosis, intervention, and restoration. Handpieces operate at air-driven speeds exceeding 400,000 RPM and require precision-machined turbine bearings; imaging equipment spans 2D panoramic through 3D cone-beam computed tomography with voxel resolutions below 0.1 mm for implant planning. Imaging equipment commands the highest capital allocation per practice opening, while dental implants within consumables generate the steepest lifetime value through follow-up components and maintenance protocols. Dental chairs represent a mature replacement-cycle segment where ergonomic certifications and infection-control surfaces now determine specification sheets.
FDA 510(k) premarket notification and EU MDR technical documentation requirements govern device commercialization, with ISO 13485 quality management serving as the baseline for supplier qualification across both jurisdictions. The EPA regulates dental amalgam waste discharge through amalgam separator mandates, directly shaping consumable selection in US practices. Stakeholders must monitor reimbursement code revisions from CMS and national health technology assessment bodies, as these determine whether digital workflows convert from pilot investments to standard-of-care requirements.
Market Dynamics
DSO consolidation is compressing procurement cycles and forcing suppliers to reconfigure from product-centric to workflow-anchored commercial models.
Growth Catalysts
- EU MDR compliance deadlines:Accelerated technical documentation requirements are filtering out marginal suppliers and concentrating demand among established manufacturers with notified body relationships.
- Digital chairside workflows:Intraoral scanning and same-day milling adoption among specialty implant clinics is expanding consumable pull-through for surgical guides and provisional restorations.
- China:Provincial reimbursement expansions for preventive dental services are driving first-time equipment procurement in tier-2 and tier-3 cities.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing feedstock for dental implants relies on a narrow supplier base in Germany and Japan, exposing margins to aerospace-industry demand spikes.
- FDA 510(k) pathway congestion:Pre-market notification review timelines for digital imaging systems have extended, delaying product launches and freezing R&D amortization schedules.
- Amalgam separator mandates:EPA discharge regulations impose capital burdens on US practices that compress consumable budgets for discretionary categories.
Strategic Opportunities
- India:CDSCO streamlined medical device registration and PLI scheme incentives for domestic manufacturing are opening import-substitution pathways for mid-range imaging equipment.
- AI-assisted radiographic interpretation:Convergence of machine learning algorithms with CBCT systems creates service revenue streams beyond hardware sales.
- Subscription-based CAD/CAM access:Per-case licensing models lower entry barriers for independent practices in saturated European markets.
Industry Challenges
- Biocompatibility certification complexity:ISO 10993 testing protocols for novel zirconia formulations extend development timelines and strain regulatory affairs capacity.
- Legacy PMS integration:Digital workflow adoption requires middleware development to bridge chairside systems with practice management software, increasing implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Equipment and Consumables Market |
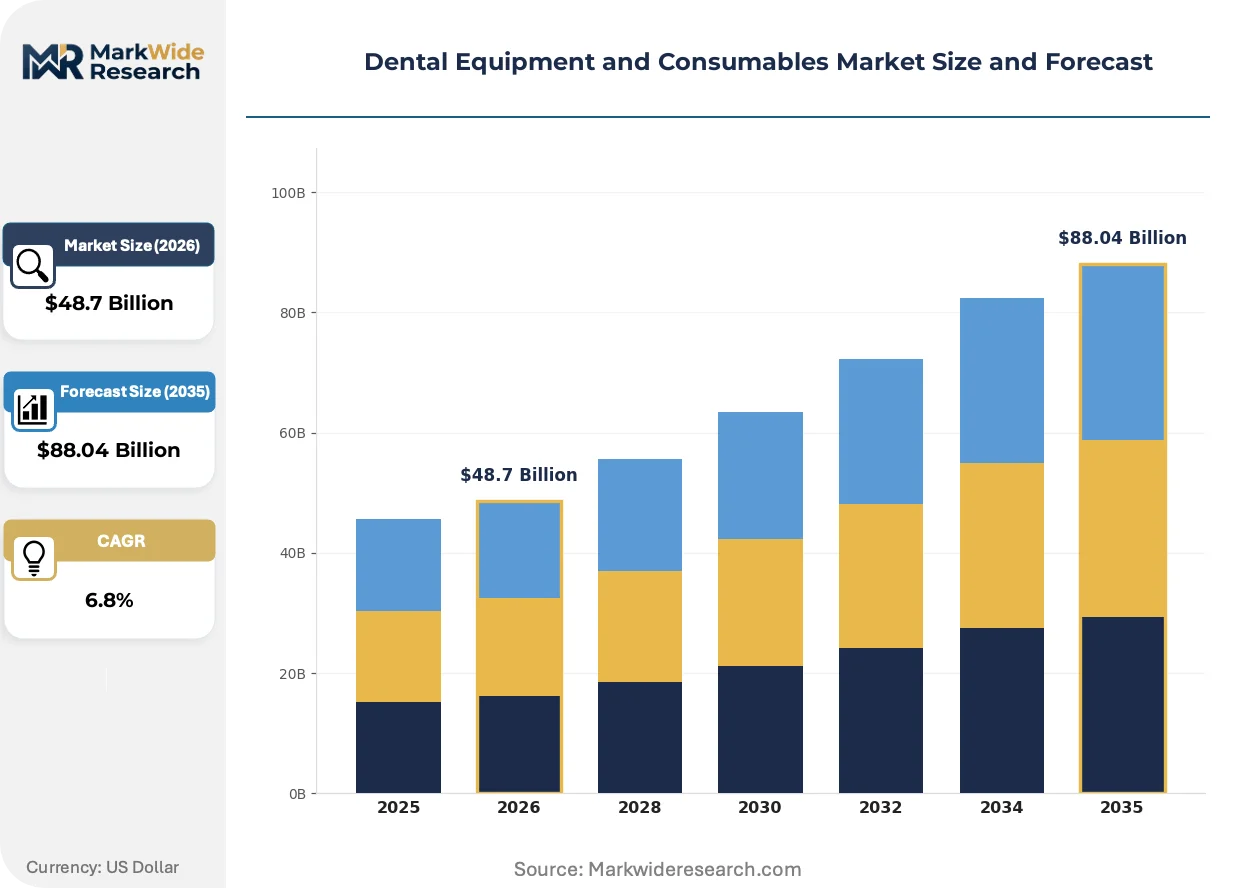
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handpieces, Surgical Instruments, Imaging Equipment, Dental Chairs Consumable Type: Adhesives, Dental Materials, Sterilization Products, Dental Implants End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Application: Oral Surgery, Preventive Care, Restorative Dentistry, Orthodontics |
| Companies Covered | Align Technology, Patterson Companies, Dentsply Sirona, 3M, Envista Holdings, Straumann Group, Zimmer Biomet, Ivoclar, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Equipment and Consumables Market Emerging Trajectories
Workflow digitization is dissolving traditional boundaries between diagnosis, treatment planning, and fabrication, compressing value chains and redistributing margin capture.
Photopolymer resins for 3D-printed dental models and surgical guides are fragmenting the analog dental laboratory segment. DSOs and large group practices are bringing printing in-house, reducing turnaround times from days to hours. This shift is fragmenting the historical outsourcing relationship between clinics and independent labs, concentrating consumable purchasing power with resin and printer OEMs.
EU MDR technical documentation requirements for Class IIa and IIb devices are forcing manufacturers to rebuild quality management systems around clinical evidence generation. The regulation demands post-market surveillance infrastructure that smaller suppliers cannot sustain. German and Swiss implant manufacturers are absorbing compliance costs through premium pricing, while Italian and Spanish distributors face portfolio rationalization.
Leasing structures for capital equipment are displacing outright purchase in North American and Western European markets. Independent practices facing compressed reimbursement are trading ownership for predictable monthly outlays that bundle service and consumables. This pattern is most pronounced in Germany, where dental technician labor shortages make chairside milling economics compelling despite higher per-unit financing costs.
Dental Equipment and Consumables Market Segmentation
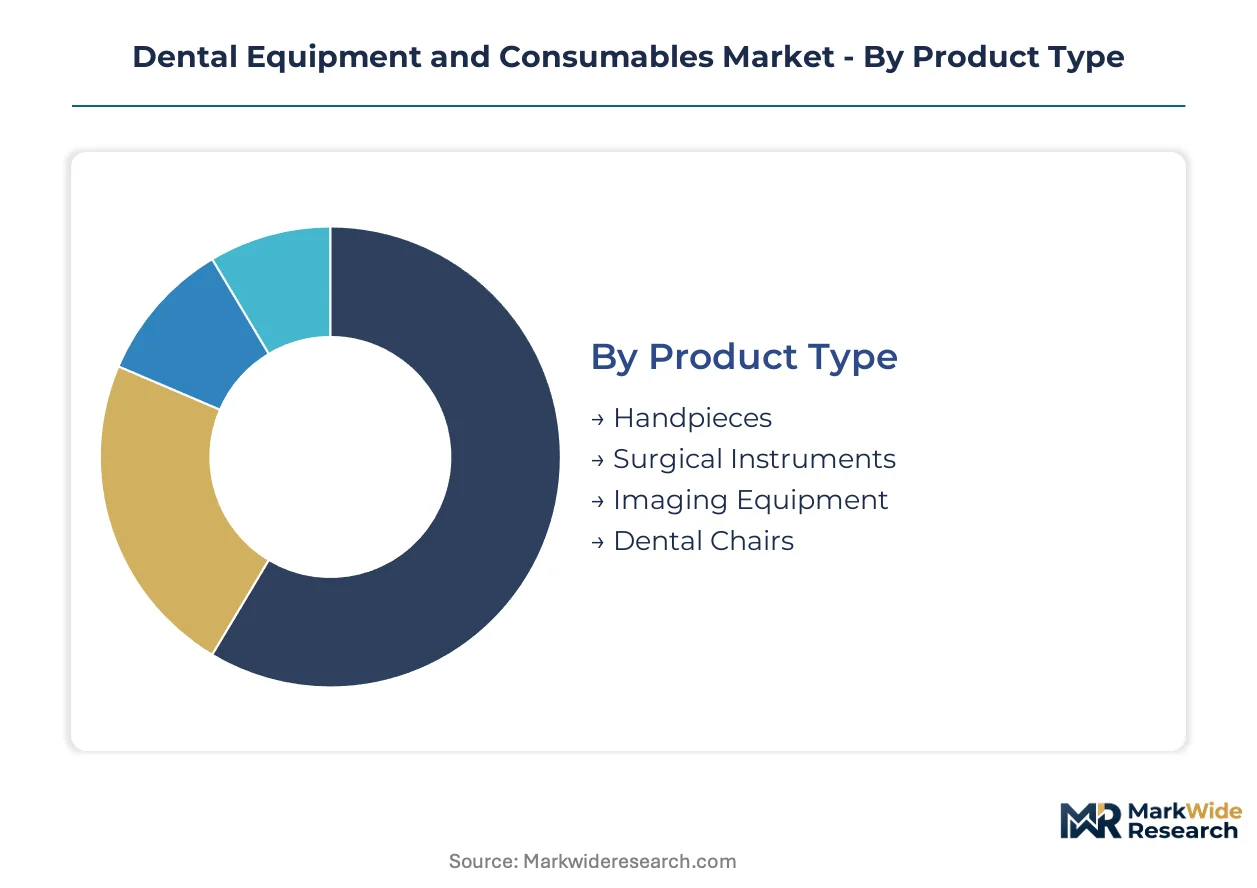
Segmentation in dental equipment and consumables reveals how procurement power concentrates across distinct clinical workflows and capital-intensity thresholds. Equipment categories face replacement-cycle pressures while consumable segments generate recurring revenue streams that reshape supplier relationships.
Product Type:
Substitution pressure runs strongest through imaging equipment as digital modalities displace analog systems and consolidate multiple diagnostic functions into single platforms.
- Handpieces:Air-driven turbines operate above 400,000 RPM with ceramic bearings and fiber-optic illumination channels. Demand clusters with DSOs in the United States and Germany as they standardize procurement across multi-location networks to reduce maintenance contract complexity.
- Surgical Instruments:Precision-machined stainless steel and carbide burs with ergonomic grip designs for extended procedure tolerance. Volume concentrates in specialty implant clinics across China where provincial reimbursement expansions are accelerating surgical service capacity.
- Imaging Equipment:2D panoramic through 3D cone-beam CT systems with sub-0.1 mm voxel resolution.
- Dental Chairs:Ergonomic treatment furniture with infection-control surface certifications.
Imaging equipment retains volume leadership; handpieces hold the steepest expansion curve.
Consumable Type:
Cost tier stratification separates premium biocompatible formulations from commoditized single-use supplies, with reimbursement codes determining which tier gains procurement share.
- Dental Implants:Titanium and zirconia root-form fixtures with proprietary surface treatments for osseointegration acceleration. Demand concentrates in Germany and Switzerland where technician labor shortages push clinics toward chairside provisional restorations and surgical guide workflows.
- Dental Materials:Composite resins, glass ionomers, and ceramic blocks for direct and indirect restorations. Volume clusters with independent practices in saturated European markets adopting subscription-based CAD/CAM access models to lower per-case material costs.
- Adhesives:Bonding agents and cements for restoration fixation and orthodontic attachment.
- Sterilization Products:Instrument wraps, biological indicators, and chemical sterilants for infection control protocols.
Dental materials retain volume leadership; dental implants hold the steepest expansion curve.
End User:
Customer type determines contract structure complexity, with corporate chains extracting volume discounts that independent practices cannot match through traditional distribution.
- Dental Clinics:Solo practices, group partnerships, and DSO-affiliated locations delivering outpatient oral health services. Procurement concentrates in the United States where reimbursement compression is accelerating leasing adoption for capital equipment and bundled consumable contracts.
- Hospitals:Integrated health systems with emergency dental departments and surgical suites for complex interventions. Demand clusters in China as tier-2 and tier-3 cities expand hospital-based dental service capacity under provincial preventive care frameworks.
- Research Laboratories:Academic and commercial facilities conducting biomaterial and device validation studies.
- Educational Institutions:Dental schools and training centers with high-turnover equipment for student technique development.
Dental clinics retain volume leadership; hospitals hold the steepest expansion curve.
Application:
Application maturity varies by procedure reimbursement status, with preventive services gaining public funding support that redirects capital toward diagnostic and early-intervention equipment.
- Preventive Care:Prophylaxis, sealants, fluoride treatments, and early caries detection protocols. Demand concentrates in Germany and the United States where expanded reimbursement codes are converting digital diagnostic workflows from pilot investments to standard-of-care requirements.
- Restorative Dentistry:Direct and indirect fillings, crowns, bridges, and prosthetic rehabilitation. Volume clusters with specialty clinics in China adopting intraoral scanning and same-day milling to compress fabrication turnaround from external laboratories.
- Oral Surgery:Extraction, implant placement, and maxillofacial intervention procedures.
- Orthodontics:Malocclusion correction through fixed appliances, aligners, and retention systems.
Restorative dentistry retains volume leadership; preventive care holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German implant manufacturers export precision-machined titanium fixtures to specialty clinics across Switzerland and Austria, while Chinese imaging OEMs supply tier-2 cities through provincial procurement frameworks.
United States
DSO consolidation drives standardized procurement across multi-location networks, compressing vendor management overhead. FDA 510(k) review timelines for digital imaging systems have extended, freezing product launch schedules. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate new practice openings where leasing structures displace outright equipment purchase.
Germany
Dental technician labor shortages push clinics toward chairside milling and same-day provisional workflows. EU MDR technical documentation requirements filter marginal suppliers from notified body relationships. Stuttgart and Munich industrial corridors host precision-bearing manufacturers supplying air-turbine handpiece OEMs.
China
Provincial reimbursement expansions for preventive services accelerate first-time equipment procurement in tier-2 and tier-3 cities. NMPA streamlined registration pathways compress import-substitution timelines for mid-range CBCT systems. Chengdu and Xi'an municipal health bureaus expand hospital-based dental service capacity under western development frameworks.
Switzerland
Premium implant manufacturers absorb EU MDR compliance costs through proprietary surface-treatment pricing. Swissmedic post-market surveillance requirements demand clinical evidence infrastructure that concentrates among established players. Basel-Zurich corridor facilities export surgical guide libraries to German-speaking implantology clinics.
India
CDSCO streamlined medical device registration and PLI scheme incentives open domestic manufacturing pathways for imaging equipment. Import substitution pressures redirect procurement toward mid-range systems from ASEAN suppliers. Ahmedabad and Hyderabad clusters develop component fabrication for chairside milling units targeting South Asian markets.
Dental Equipment and Consumables Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The vendor base stratifies into three tiers: multinational conglomerates with integrated CAD/CAM workflows, mid-cap regional manufacturers with notified body relationships, and emerging Asian fabricators with cost-optimized component supply. Dominant competitive moves include M&A to capture DSO procurement contracts and strategic partnerships to bridge legacy practice management software with chairside digital systems.
Among US-based diversified healthcare suppliers, Henry Schein and Patterson Companies occupy distribution-centric positions anchoring multi-brand portfolio access for independent practices. Dentsply Sirona exemplifies the integrated-systems archetype, representing workflow-anchored commercial models that bundle hardware, software, and consumable contracts. These three entities sit within distinct competitive vectors—distribution scale, manufacturing integration, and end-to-end workflow control—rather than direct product-for-product rivalry.
| Leading Market Players |
|---|
| Align Technology |
| Patterson Companies |
| Dentsply Sirona |
| 3M |
| Envista Holdings |
| Straumann Group |
| Zimmer Biomet |
| Ivoclar |
| Henry Schein |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates supplier qualification for both FDA 510(k) and EU MDR pathways, concentrating pricing power among manufacturers with established notified body relationships while filtering marginal competitors from premium tier access. This regulatory threshold simultaneously enables price stratification across certification-holding incumbents and forces uncertified suppliers toward commoditized segments where margins compress.
Pricing Analysis
Next-generation intraoral scanners and CBCT systems command 40-60% premiums over prior-generation analog panoramic units, while current-generation chairside milling systems occupy a mid-tier position. Three-tier pricing structure across premium, standard, and economy levels separates Dentsply Sirona workflow bundles from regional European manufacturers and emerging Asian fabricators. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling. Cost compression in economy-tier handpieces is intensifying because DSO procurement standardization extracts volume discounts. Independent practices in saturated European markets exhibit highest price sensitivity; DSO-affiliated chains in the United States demonstrate lowest sensitivity due to leasing structures that obscure per-unit costs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for precision-machined turbine bearings and ceramic components sourced from Japanese and German suppliers. Manufacturing concentration clusters in Germany for handpiece turbines, Switzerland for implant surface treatments, and China for mid-range imaging system assembly. Raw material dependencies span titanium powder from German and Japanese suppliers, zirconia blanks from Japanese ceramic manufacturers, and photopolymer resins from US and European chemical specialists. Single-source vulnerability in titanium powder feedstock exposes dental implant margins to aerospace-industry demand spikes. Distribution runs through Henry Schein and Patterson Companies in North America, Straumann and Ivoclar direct sales in Europe, and provincial procurement frameworks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from 3D-printed surgical guides and in-house resin printing workflows that displace traditional laboratory outsourcing relationships.
For Market Incumbents: Secure DSO procurement contracts through workflow-anchored commercial models that bundle hardware, software, and consumable subscriptions. Deepen backward integration into photopolymer resin formulation to capture margin from in-house printing adoption. Invest in middleware development to bridge chairside systems with legacy practice management software, reducing implementation friction that slows digital workflow conversion. For New Entrants and Emerging Players: Chairside milling service gaps in tier-2 and tier-3 Chinese cities present white-space entry points where incumbent coverage remains thin. Target mid-range imaging equipment in India under CDSCO streamlined registration and PLI scheme incentives. Deploy subscription-based CAD/CAM access models to lower entry barriers for independent practices in saturated European markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure as post-market surveillance requirements demand clinical evidence generation capabilities. Acquisition targets should display established notified body relationships and proprietary abutment libraries that generate recurring consumable pull-through. Monitor FDA 510(k) review timeline trends as inflection indicator for product launch velocity and R&D amortization efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Accelerated compliance deadlines filter marginal suppliers and concentrate demand among established manufacturers with notified body relationships. |
| DSO Procurement Partnership | Multi-location network contracts standardize equipment across practices and reduce vendor management overhead for suppliers. |
| AI-Assisted Radiographic Software Development | Machine learning integration with CBCT systems creates service revenue streams beyond hardware sales for imaging OEMs. |
| Subscription-Based CAD/CAM Access Model | Per-case licensing lowers entry barriers for independent practices in saturated European markets. |
| Backward Integration into Resin Formulation | In-house photopolymer production captures margin from DSOs bringing 3D printing chairside and reducing laboratory outsourcing. |
Methodological Framework
Initial hypotheses were tested against primary input from dental clinic procurement managers, biomedical engineers at hospital systems, GPO contracts specialists, and regulatory affairs leads at implant manufacturers and refined through secondary validation. Primary research drew from structured interviews with DSO operations executives, independent practice owners, and dental laboratory technicians across the United States, Germany, and China. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement code revisions, and hospital procurement contract disclosures. Bottom-up equipment installation data and top-down market sizing triangulated volume estimates.
Variance decomposition across product type, consumable category, end-user archetype, and application maturity informed the analytical framework over the projection horizon. Segmentation dimensions modeled include equipment capital intensity, consumable recurrence rate, buyer consolidation status, and reimbursement code coverage. CAGRs were derived from replacement-cycle analysis and adoption curve modeling. Industry-specific forecast inputs incorporated dental technician labor shortage indices and provincial reimbursement expansion timelines in China.
Forecasts assume regulatory continuity in FDA 510(k) review protocols and EU MDR implementation; material policy shifts would require re-modeling. Assumptions reflect stable titanium powder supply from German and Japanese sources and continued DSO consolidation velocity in North America. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Dust Collector Market