
 Dental Equipment Market | 2026-2036
Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Equipment Market Intelligence
EU Medical Device Regulation is hardening the cost-of-entry calculus for smaller dental equipment manufacturers seeking CE marking. Dentsply Sirona leverages its vertically integrated manufacturing footprint to sustain margin resilience under stricter conformity assessment. Planmeca Oy anchors its competitive position through deep specialization in digital imaging and software-integrated systems.
Dental equipment encompasses mechanically powered instruments, diagnostic imaging platforms, and sterilization systems engineered to rotational tolerances of 0.01 mm in high-speed handpieces, designed for oral cavity diagnosis, treatment, and surgical intervention. Imaging systems command the dominant revenue share as cone beam CT and digital radiography displace analog film across developed markets. Laser technology within the technology dimension posts the fastest expansion trajectory, driven by soft-tissue applications and patient preference for minimally invasive periodontal procedures.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern US market access, while the EU AI Act introduces new conformity obligations for AI-enabled diagnostic imaging software. Japan's PMDA maintains distinct pharmaceutical and medical device classification rules that shape product registration timelines for foreign manufacturers. Stakeholders must monitor regulatory divergence between FDA's software-as-medical-device guidance and EU harmonized standards to optimize dual-market product development strategies.
Market Dynamics
EU Medical Device Regulation (MDR) conformity assessment timelines are compressing market entry windows for non-specialized manufacturers while rewarding pre-certified incumbents with captive notified body relationships. Digital imaging software with AI diagnostic capabilities faces dual scrutiny under both MDR and the EU AI Act, creating a bifurcation between compliant and non-compliant supplier pools.
Growth Catalysts
- EU MDR pre-market pathways:Tighter CE marking requirements accelerate consolidation toward manufacturers with vertically integrated quality management systems and established notified body partnerships.
- Laser periodontal applications:Patient preference for minimally invasive soft-tissue procedures drives replacement cycles for conventional mechanical instrumentation in private clinic chains.
- China tier-one city investment:Shanghai and Beijing private dental groups deploy cone beam CT suites as competitive differentiation against public hospital outpatient departments.
Market Restraints
- Notified body capacity constraints:EU MDR designation bottlenecks delay CE marking for Class IIa and above imaging equipment, extending time-to-revenue by 12-18 months for new entrants.
- High-speed handpiece bearing supply:Swiss and German ceramic bearing manufacturers control critical rotational tolerance components, creating single-source vulnerability for precision spindle assemblies.
- Intraoral scanner substitution:Digital impression systems displace conventional elastomeric materials, compressing revenue pools for alginate and polyether manufacturers without offsetting equipment margins.
Strategic Opportunities
- AI-enabled radiography software:Convergence of convolutional neural networks with cone beam CT reconstruction creates premium pricing tiers for automated pathology detection in endodontic planning.
- India private clinic expansion:Mumbai and Delhi dental chains seek refurbished and mid-tier digital suites as NABH accreditation standards mandate imaging infrastructure upgrades.
- Japan PMDA software guidance:METI reimbursement incentives for AI diagnostic tools create first-mover advantages for imaging OEMs with PMDA pre-certification and domestic clinical validation data.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified lead auditors for medical device quality management systems command premium contracting rates, extending certification preparation timelines for mid-tier manufacturers.
- Legacy PACS integration:Hospital dental departments require DICOM conformance testing with proprietary radiology information systems, adding 6-9 months to imaging platform deployment cycles.
- Autoclave sterilization validation:Steam sterilization qualification for complex handpiece lumens demands specialized biological indicator protocols that strain in-house quality engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Equipment Market |
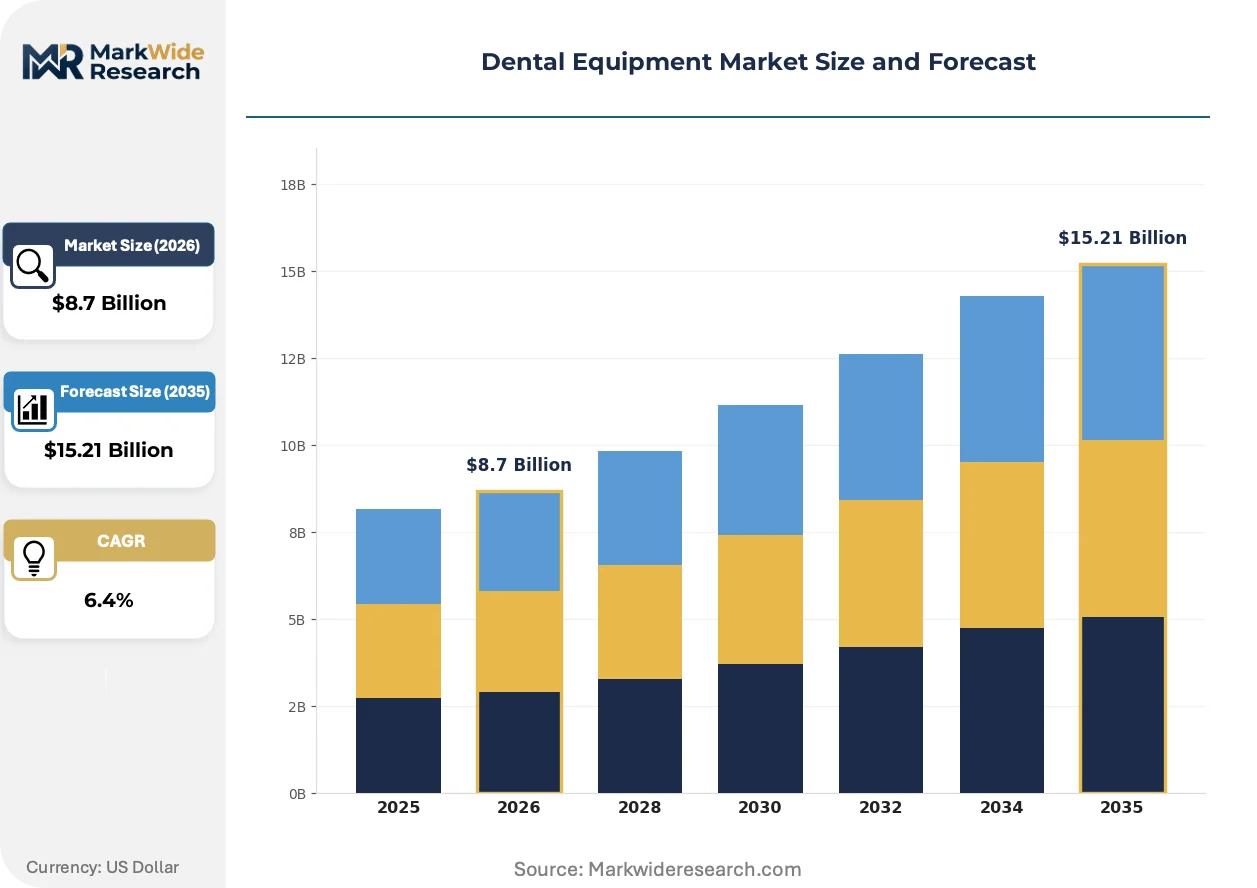
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handpieces, X-ray Equipment, Sterilization Equipment, Imaging Systems Technology: Laser, Digital Imaging, Cone Beam CT, Ultrasonic End User: Dental Clinics, Hospitals, Academic Institutions, Laboratories Application: Orthodontics, Periodontics, Endodontics, Oral Surgery |
| Companies Covered | Dentsply Sirona, Planmeca Oy, Align Technology, Envista Holdings Corporation, A-dec Inc., Carestream Dental, Danaher Corporation, Straumann, Nakanishi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Equipment Market Strategic Shifts & Innovations
Digital workflow integration is collapsing traditional boundaries between diagnostic imaging, treatment planning, and chairside manufacturing. Three distinct vectors are reconfiguring competitive advantage.
Cone beam computed tomography is consolidating diagnostic imaging architecture in high-volume implantology practices. Oral surgery groups in Germany and the United States replace panoramic and periapical systems with single-platform volumetric scanners. This consolidation compresses capital equipment procurement cycles while elevating software subscription revenue as a proportion of lifetime customer value.
The EU AI Act risk classification framework imposes conformity obligations on diagnostic imaging algorithms that automate pathology detection. Manufacturers must maintain technical documentation and post-market surveillance systems distinct from hardware MDR requirements. Imaging software vendors with dual notified body coverage for both device and AI conformity are securing preferred supplier status with EU hospital procurement consortia.
Private clinic chains in China's tier-one cities are unbundling after-sales service from equipment purchase contracts. Shanghai-based dental groups negotiate separate technical service agreements with third-party ISO 13485-certified maintenance providers. This disintermediation pressures OEM service margins while creating certification arbitrage opportunities for independent technical service organizations with multi-brand repair capabilities.
Dental Equipment Market Segmentation
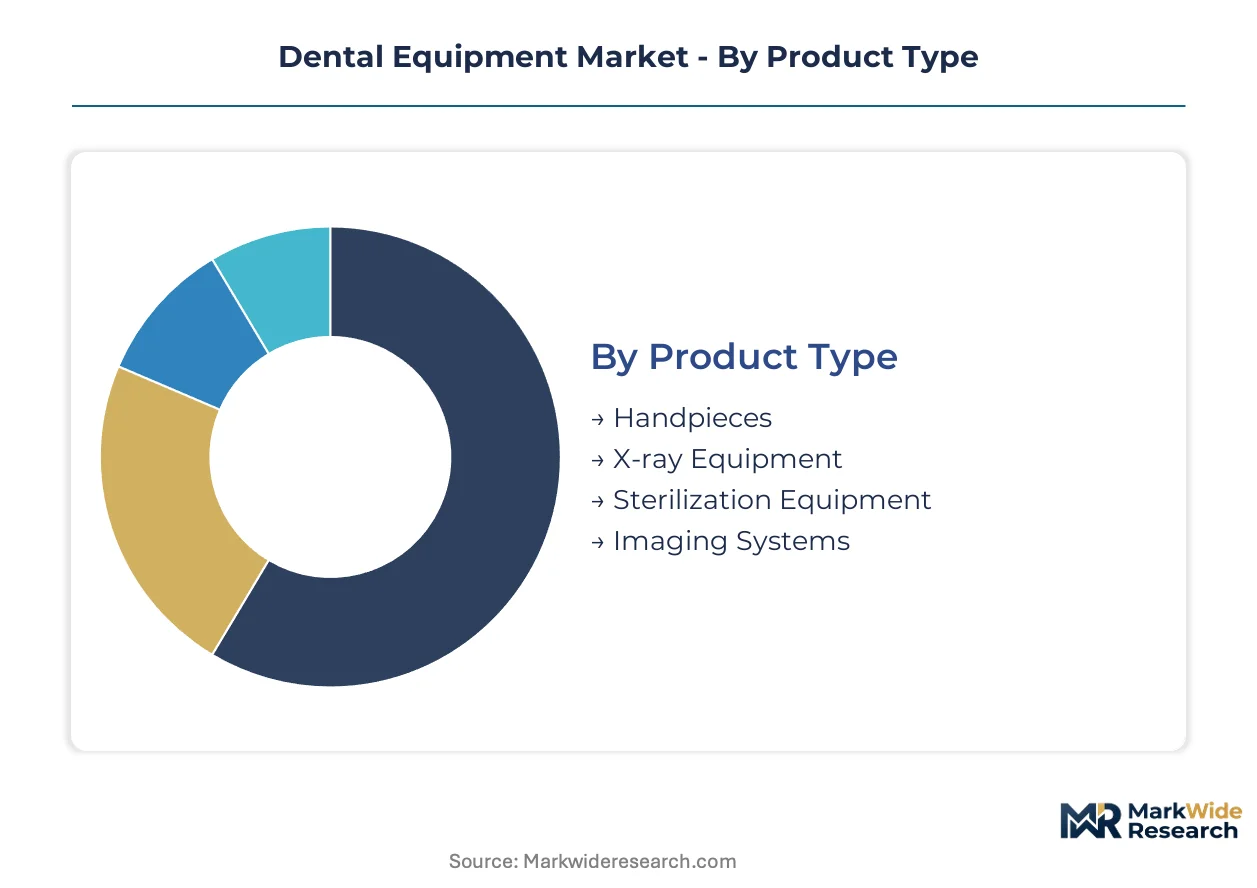
Segmentation in dental equipment reveals distinct procurement patterns across product categories, with replacement cycles and technology upgrade thresholds varying dramatically between high-speed mechanical systems and software-dependent imaging platforms. Understanding these divergent refresh timelines enables manufacturers to align R&D investment with predictable demand windows.
Product Type:
Upgrade cycles compress where digital interfaces replace mechanical precision, extending where ceramic bearing tolerances govern reliability.
- Imaging Systems:Cone beam CT and digital radiography platforms integrate DICOM-compliant software architectures with volumetric reconstruction algorithms. Demand concentrates in Germany's expanding clinic chains as EU MDR tightens pre-market conformity requirements for Class IIa devices.
- X-ray Equipment:Panoramic and intraoral units incorporate solid-state sensors with reduced radiation exposure profiles. China's tier-one city private clinics deploy these suites as competitive differentiation against public hospital outpatient departments.
- Handpieces:Turbine and electric motor systems engineered to 0.01 mm rotational tolerances for cavity preparation and finishing.
- Sterilization Equipment:Steam autoclaves and chemical vapor systems with validated biological indicator protocols for complex instrument lumens.
Imaging Systems sits at the top of the volume ranking, with X-ray Equipment climbing the fastest.
Technology:
Cost tiers separate premium AI-enabled platforms from mid-tier digital suites and economy analog replacements.
- Laser:Diode and erbium systems for soft-tissue incision and periodontal debridement with minimized thermal necrosis zones. Patient preference for minimally invasive procedures drives replacement cycles in US private practice groups.
- Cone Beam CT:Volumetric scanners with sub-millimeter isotropic resolution for implant planning and endodontic morphology assessment. Oral surgery groups in the United States and Germany consolidate diagnostic architecture around single-platform systems.
- Digital Imaging:Intraoral sensors and phosphor plate systems displacing analog film across developed markets.
- Ultrasonic:Piezoelectric scalers for calculus removal and root surface debridement in periodontal maintenance protocols.
Cone Beam CT commands the premium pricing tier, while Laser technology is gaining share fastest.
End User:
Application intensity varies by procedure throughput and capital deployment capacity across institutional settings.
- Dental Clinics:Private group practices and independent operators with concentrated implantology and cosmetic service lines. Shanghai and Beijing chains invest heavily in cone beam CT and laser systems as NABH-equivalent standards mature.
- Hospitals:Integrated dental departments requiring PACS interoperability and proprietary radiology information system conformance. Legacy DICOM integration demands extend deployment cycles by 6-9 months.
- Academic Institutions:Training programs with multi-station simulation requirements and research imaging protocols.
- Laboratories:Digital workflow hubs for CAD/CAM restoration fabrication and orthodontic appliance production.
Dental Clinics represents the dominant procurement volume, with Hospitals expanding most quickly.
Application:
Customer type segmentation distinguishes high-volume surgical centers from preventive-focused general practices.
- Oral Surgery:Implant placement and bone grafting procedures requiring volumetric preoperative assessment and surgical guide fabrication. German oral surgery groups replace panoramic systems with cone beam CT consolidation.
- Endodontics:Root canal therapy with electronic apex locators and operating microscopes for complex morphology cases. AI-enabled radiography software creates premium tiers for automated pathology detection in treatment planning.
- Orthodontics:Clear aligner therapy and fixed appliance treatment with intraoral scanning and cephalometric analysis.
- Periodontics:Soft-tissue management and regenerative procedures with laser and ultrasonic instrumentation.
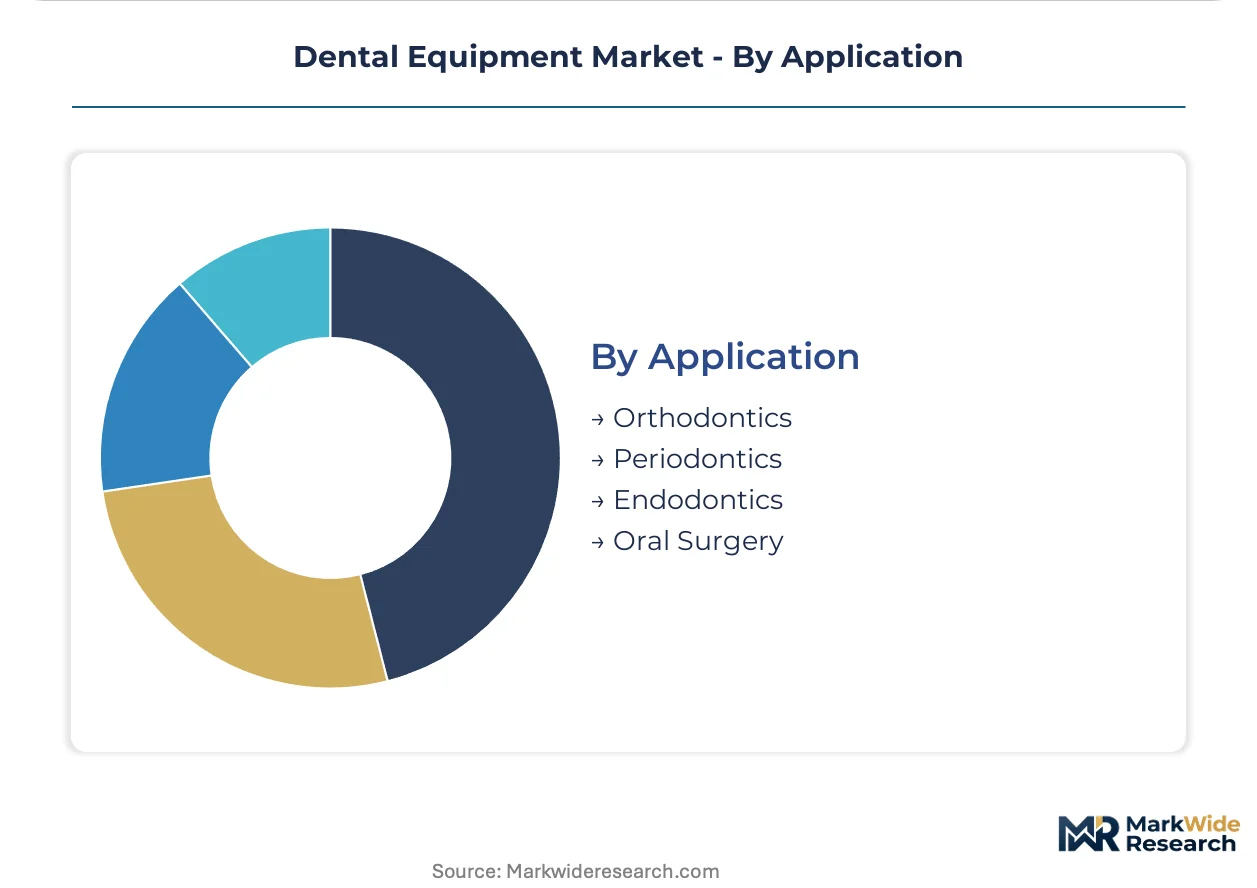
Oral Surgery sits at the top of the volume ranking, with Endodontics climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dental equipment engineers cluster around precision manufacturing hubs in Germany, Switzerland, and Japan, with regulatory compliance specialists concentrated in Brussels and Washington corridors.
Germany
Oral surgery groups in Bavaria and Baden-Württemberg consolidate diagnostic imaging around single-platform cone beam CT systems. EU MDR notified body partnerships determine market access speed for Class IIa imaging devices. Stuttgart's precision engineering corridor supplies ceramic bearing assemblies for high-speed handpiece spindles.
United States
Private dental groups in Texas and Florida drive replacement cycles for laser periodontal systems. FDA 510(k) clearance pathways govern software-as-medical-device classifications for AI-enabled radiography. Minneapolis-St. Paul hosts concentrated technical service operations for multi-brand equipment maintenance.
China
Shanghai and Beijing private clinic chains deploy cone beam CT suites as competitive differentiation against public hospitals. NMPA registration timelines shape product launch sequencing for foreign manufacturers. The Yangtze River Delta corridor concentrates domestic imaging equipment assembly operations.
Japan
Tokyo and Osaka dental chains seek PMDA-pre-certified AI diagnostic tools for endodontic planning. METI reimbursement incentives reward domestic clinical validation data for imaging software. The Chubu region around Nagoya maintains specialized ceramic component supply for precision handpiece manufacturing.
India
Mumbai and Delhi dental chains source refurbished digital suites as NABH accreditation standards mandate imaging infrastructure. CDSCO medical device rules increasingly align with IMDRF guidelines for software-based diagnostics. Gujarat's industrial corridor emerges as a hub for sterilization equipment contract manufacturing.
Dental Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base stratifies between imaging platform integrators, precision mechanical component fabricators, and software-dependent diagnostic tool developers. Three archetypes dominate: vertically integrated equipment OEMs with captive notified body relationships; specialized imaging software vendors with dual MDR-AI Act compliance; and precision component suppliers controlling critical bearing tolerances. Consolidation through M&A accelerates as CE marking timelines compress, while strategic partnerships between hardware OEMs and AI software developers reshape competitive positioning.
Among the diversified equipment manufacturers, Dentsply Sirona and Danaher Corporation occupy positions reflecting scale-driven consolidation strategies. Planmeca Oy exemplifies the focused specialist archetype, anchoring competitive positioning through deep specialization in digital imaging architectures. Envista Holdings Corporation sits within the mid-tier integration category, representing manufacturers balancing portfolio breadth with segment-specific technical depth.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca Oy |
| Align Technology |
| Envista Holdings Corporation |
| A-dec Inc. |
| Carestream Dental |
| Danaher Corporation |
| Straumann |
| Nakanishi Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up dental clinic chains in China's tier-one cities impose unbundled service procurement discipline on OEMs, compressing equipment margins while elevating third-party technical service arbitrage. This ownership pattern concentrates buyer power against fragmented precision component suppliers, forcing pricing discipline through multi-brand maintenance contracts.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled cone beam CT suites from mid-tier digital radiography and refurbished analog replacements. Price differentiation rests on CE marking tier and after-sales bundling status. Cost compression in mid-tier imaging intensifies because Shanghai clinic chains negotiate separate technical service agreements. Price sensitivity peaks among India's NABH-accredited chains sourcing refurbished suites, while German oral surgery groups show lowest sensitivity for MDR-compliant Class IIa devices.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Minneapolis-St. Paul, and the Yangtze River Delta anchor hub-and-spoke patterns for spare parts and consumables. Manufacturing concentrates in Germany, Switzerland, and Japan for precision ceramic bearing assemblies and high-speed handpiece spindles. Raw material dependencies include surgical-grade ceramics, rare-earth laser crystals, and DICOM-compliant sensor substrates. Single-source vulnerability runs through Swiss and German ceramic bearing manufacturers controlling 0.01 mm tolerance components. Distribution runs through OEM-captive service networks and emerging ISO 13485-certified independent technical service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
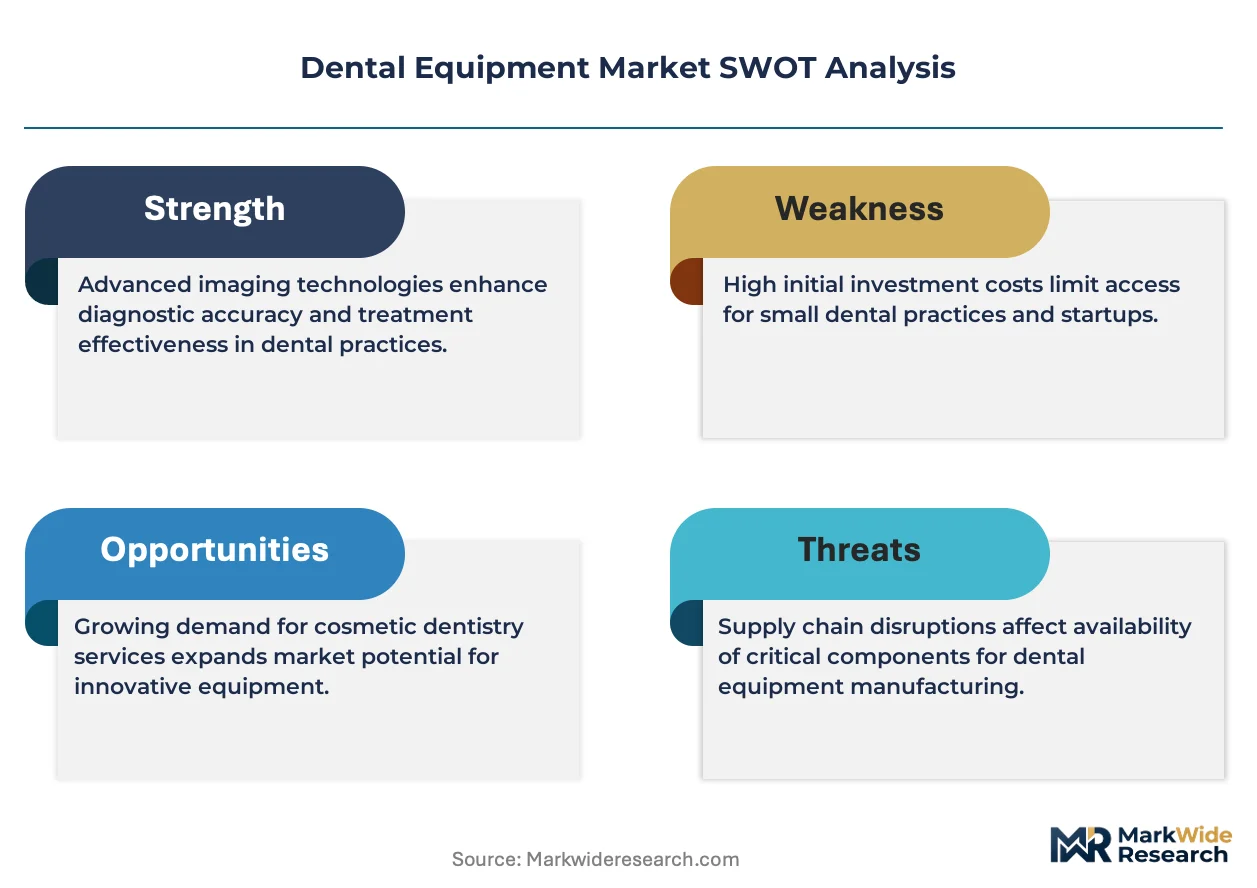
This market reads as a late-cycle quality story. Replacement demand tilts toward premium specifications as EU MDR compliance becomes non-negotiable for hospital procurement consortia.
For Market Incumbents: Extend notified body relationship moats through dual MDR-AI Act certification coverage for imaging software. Consolidate precision component supply through captive ceramic bearing partnerships in Stuttgart and Nagoya corridors. Defend against third-party technical service disintermediation by embedding predictive maintenance subscriptions into equipment contracts. For New Entrants and Emerging Players: Independent technical service organizations with multi-brand ISO 13485 certification represent the most penetrable channel archetype. White-space concentrates in India's refurbished digital suite segment and Japan's PMDA-pre-certified AI diagnostic tools. Pursue certification arbitrage by building NABH-equivalent validation capabilities for Mumbai and Delhi clinic chains. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier imaging OEMs lacking dual notified body coverage. Long-term viability favors specialists with software-hardware integration depth and established EU hospital procurement relationships. Watch EU notified body designation bottlenecks as inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual MDR-AI Act Certification | Imaging software vendors with dual coverage secure preferred supplier status with EU hospital procurement consortia. |
| Independent Technical Service Certification | ISO 13485-certified maintenance providers capture margin from OEM service disintermediation in Shanghai clinic chains. |
| Ceramic Bearing Supply Security | Captive partnerships with Stuttgart and Nagoya precision manufacturers mitigate single-source spindle vulnerability. |
| PMDA Pre-Certification Investment | First-mover OEMs with domestic clinical validation data capture METI reimbursement incentives for AI diagnostic tools. |
| Refurbished Digital Suite Platforms | NABH accreditation mandates in Mumbai and Delhi create structured demand for mid-tier imaging infrastructure. |
Research Approach
Bottom-up dental clinic procurement modeling reconciled against top-down precision component manufacturing tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and independent technical service operators cross-validated secondary sources including FDA 510(k) filings, EU MDR notified body designation records, NMPA registration databases, and hospital procurement contract disclosures.
Input-output matrices map equipment shipments against replacement cycle assumptions across product type, technology tier, end-user category, and application intensity dimensions. CAGRs derive from segmented demand elasticity modeling and supply-side capacity constraints. Forecast inputs incorporate EU MDR transition timelines, China NMPA registration velocity, and Japan METI reimbursement incentive trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body capacity constraints, ceramic bearing supply disruptions, and AI Act enforcement divergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Equipment and Consumables Market