
 Global Dental Milling Machine Market | 2026-2036
Global Dental Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Milling Machine Market Foresight
The EU Medical Device Regulation is restructuring procurement criteria for dental milling equipment across European laboratories and clinics. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to dominate chairside system deployments in North American dental practices. Amann Girrbach sustains its position through specialized laboratory-focused milling architectures that emphasize zirconia and hybrid ceramic processing precision.
Dental milling machines are subtractive manufacturing systems that machine ceramic, resin, and metal blanks into final prosthetic restorations using multi-axis spindles operating at 30,000 to 60,000 RPM with positional accuracy below 5 micrometers. Their primary purpose is to produce patient-specific crowns, bridges, and implant abutments from digital intraoral scan data. Laboratory milling machines anchor the highest volume segment due to centralized production economics and multi-material flexibility, while chairside systems capture the fastest expansion trajectory as single-visit dentistry protocols spread through dental clinic networks. CNC milling technology leads installed capacity, though CAD/CAM-integrated workflows increasingly define new purchase decisions by collapsing design-to-manufacture timelines.
The FDA regulates dental milling equipment as Class II medical devices requiring 510(k) premarket notification, while the EU MDR imposes strengthened clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. Japan's PMDA maintains parallel standards for biocompatibility validation of milled restorative materials that affect import eligibility. Stakeholders must monitor evolving software validation requirements as artificial intelligence-assisted design tools become embedded in milling workflows.
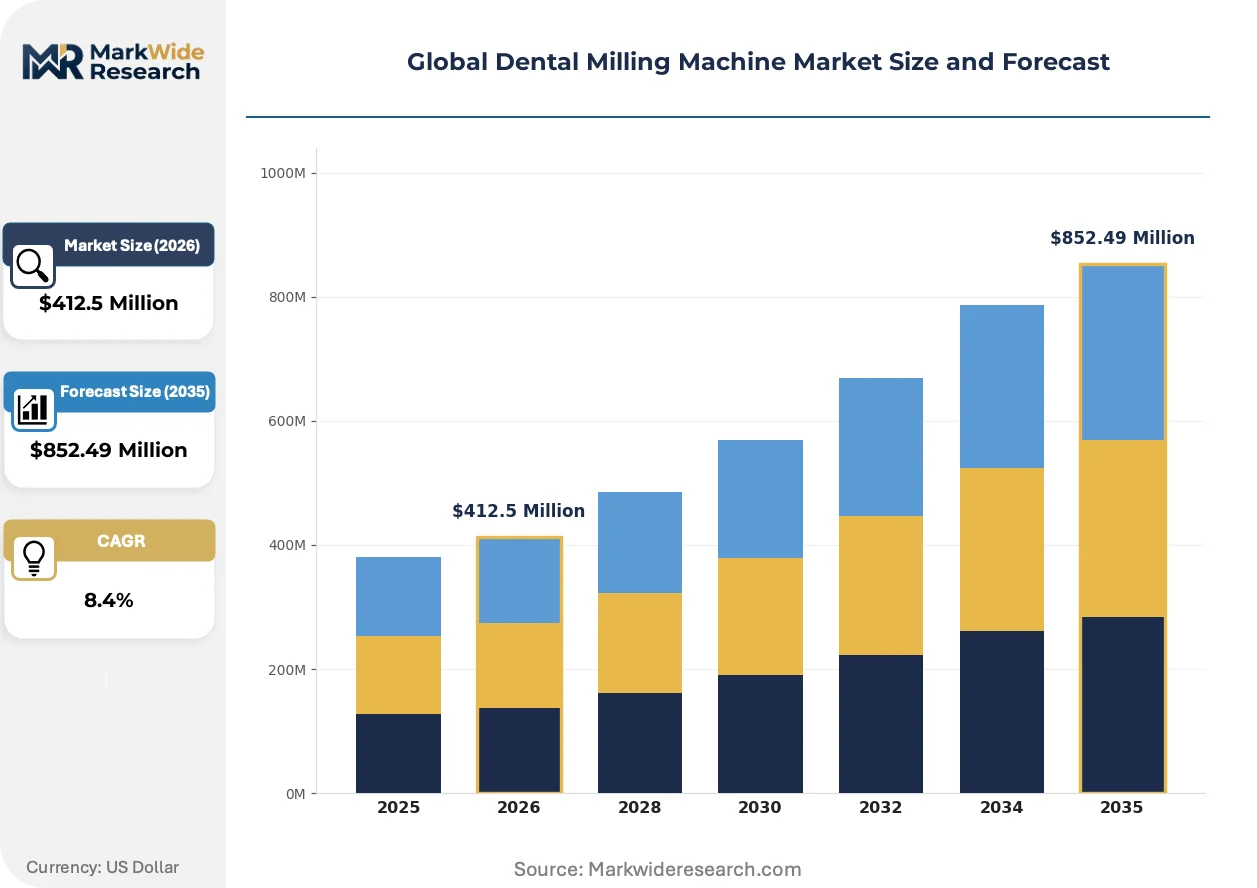
Market Dynamics
EU MDR material traceability mandates are compressing procurement cycles for dental milling equipment as laboratories and clinics revalidate supplier ecosystems against clinical evidence requirements.
Growth Catalysts
- EU MDR compliance deadlines:Laboratories across Germany and France are accelerating equipment upgrades to meet post-market surveillance obligations for permanent restorations.
- Chairside CAD/CAM integration:Dental clinics in the United States are deploying single-visit protocols that collapse crown delivery from two weeks to two hours.
- Zirconia processing precision:Advances in five-axis spindle control enable sub-5-micrometer accuracy for hybrid ceramic restorations previously requiring manual finishing.
Market Restraints
- Capital intensity barriers:Chairside systems require $80,000-$150,000 upfront investment plus annual software licenses that strain independent dental practices.
- Raw material concentration:High-purity zirconia blanks depend on supply chains centered in Japan and China, exposing buyers to export licensing volatility.
- Technical throughput ceilings:Current spindle architectures face thermal deformation limits when machining cobalt-chrome implant abutments at production scale.
Strategic Opportunities
- India dental infrastructure buildout:Government health insurance expansion into tier-2 cities creates first-time demand for laboratory milling capacity outside Mumbai and Delhi.
- AI-assisted design convergence:Machine learning tools embedded in CAD workflows reduce technician training time for complex bridge geometries.
- Subscription service channels:Equipment-as-a-service models bypass capital constraints for Brazilian and Mexican dental clinic networks.
Industry Challenges
- CAD/CAM technician scarcity:Laboratory workflows require cross-trained operators proficient in both digital design validation and physical material handling.
- 510(k) timeline compression:FDA software validation requirements for AI-integrated milling controls extend premarket notification reviews.
- Legacy scanner interoperability:Chairside systems from 2015-2019 lack firmware architectures compatible with current open-format STL protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Milling Machine Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairside Milling Machines, Laboratory Milling Machines, Hybrid Milling Machines, Portable Milling Machines Technology: CAD/CAM, 3D Milling, CNC Milling, Laser Milling, Ultrasonic Milling Application: Crown Fabrication, Bridge Milling, Denture Production, Implant Component Manufacturing, Orthodontic Appliance Creation End User: Dental Laboratories, Dental Clinics, Prosthodontists, Orthodontists, Research Institutions |
| Companies Covered | Dentsply Sirona, Amann Girrbach, Roland DG Corporation, Planmeca, Ivoclar Vivadent, Straumann Group, 3M Company, vhf camfacture, DATRON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Milling Machine Market Shifts & Advancements
Digital dentistry workflows are collapsing traditional boundaries between intraoral scanning, automated design, and subtractive manufacturing. Three interconnected developments are restructuring how restorative prosthetics move from patient mouth to final placement.
Cloud-connected milling units are decentralizing production authority away from centralized dental laboratories toward individual clinic operators. Small-practice dentists in Texas and Florida are deploying chairside systems that machine crowns while patients wait, eliminating courier logistics and laboratory turnaround delays. This spatial redistribution is compressing the addressable market for traditional outsourcing hubs.
Japan's PMDA has tightened biocompatibility validation protocols for milled titanium implant components, requiring extended cytotoxicity testing documentation from foreign manufacturers. Japanese import distributors now demand batch-level material certificates that trace zirconia origins through sintering parameters. Korean and German equipment suppliers are restructuring quality management systems to satisfy these evidentiary requirements.
After-sales service contracts are unbundling from equipment purchases as buyers seek third-party maintenance alternatives. Dental clinic groups in Australia and Canada are negotiating directly with spindle refurbishment specialists rather than accepting captive service terms from original manufacturers. This procurement fragmentation is pressuring vendor margin structures while expanding independent technical service networks.
Global Dental Milling Machine Market Segmentation
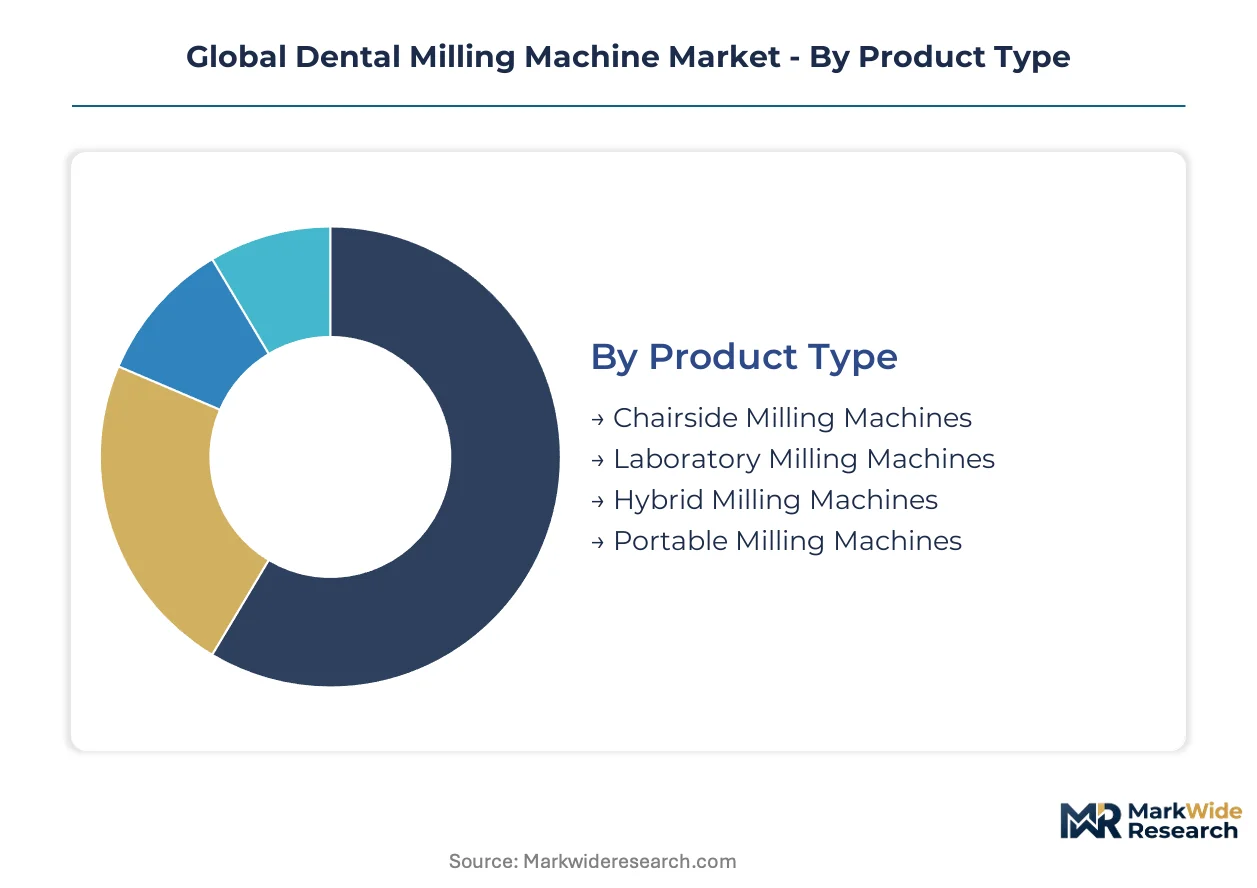
Dental milling equipment segmentation reflects divergent buyer economics across centralized laboratory production and distributed chairside delivery. Procurement criteria split between throughput maximization for high-volume laboratories and space-constrained precision for individual clinic operators.
Product Type:
Laboratories and clinics select equipment scale based on daily restoration volume and available floor space.
- Laboratory Milling Machines:These systems anchor centralized production with multi-material capability across zirconia, titanium, and hybrid ceramics. German and Italian dental laboratories deploy these units for overnight batch processing of 50-plus units, amortizing capital costs through volume economics that chairside systems cannot replicate.
- Chairside Milling Machines:Compact units integrate directly with intraoral scanners to deliver single-visit restorations. Texas and Florida dental clinic networks are expanding deployments to eliminate laboratory outsourcing delays and capture premium fees for same-day crown delivery.
- Hybrid Milling Machines:Dual-purpose architectures bridge laboratory throughput with clinic accessibility for mid-sized group practices.
- Portable Milling Machines:Mobile units serve field dental programs and temporary clinic installations with limited material range.
Laboratory Milling Machines lead on scale; Chairside Milling Machines lead on momentum.
Technology:
Technology selection determines design-to-manufacture integration depth and operator training requirements.
- CAD/CAM:Fully integrated digital workflows collapse restoration design, nesting optimization, and machining execution into seamless sequences. North American dental practices prioritize these systems for reduced technician dependency and predictable quality outcomes across operator skill levels.
- CNC Milling:Standalone numerical control systems dominate legacy laboratory installations with proven spindle reliability. Japanese equipment suppliers maintain installed bases through precision ball-screw architectures that achieve sub-5-micrometer positional accuracy for implant abutment tolerances.
- 3D Milling:Additive-subtractive hybrid approaches enable complex internal geometries for screw-retained restorations.
- Laser Milling:Non-contact material removal reduces thermal deformation in thin-wall crown structures.
- Ultrasonic Milling:Vibration-assisted cutting extends tool life in hard-metal implant component machining.
CNC Milling retains the largest installed base; CAD/CAM claims the steepest expansion trajectory.
Application:
Application focus shapes spindle speed requirements and blank material portfolios.
- Crown Fabrication:Single-unit restorations constitute the highest procedure volume globally, driving demand for rapid turnaround systems. Chinese dental laboratories process crown batches using five-axis machines that machine zirconia blanks in under 15 minutes per unit.
- Implant Component Manufacturing:Titanium and cobalt-chrome abutments require rigid machine structures and specialized coolant systems. German implant manufacturers enforce micron-level tolerances that constrain supplier qualification to equipment with thermal compensation systems.
- Bridge Milling:Multi-unit spans demand extended machining times and precision alignment across connector geometries.
- Denture Production:Acrylic and composite resin bases utilize lower spindle speeds with bulk material removal priorities.
- Orthodontic Appliance Creation:Clear aligner trimming and bracket slot machining require distinct tooling configurations.
Crown Fabrication dominates procedure volume; Implant Component Manufacturing commands the highest equipment specification thresholds.
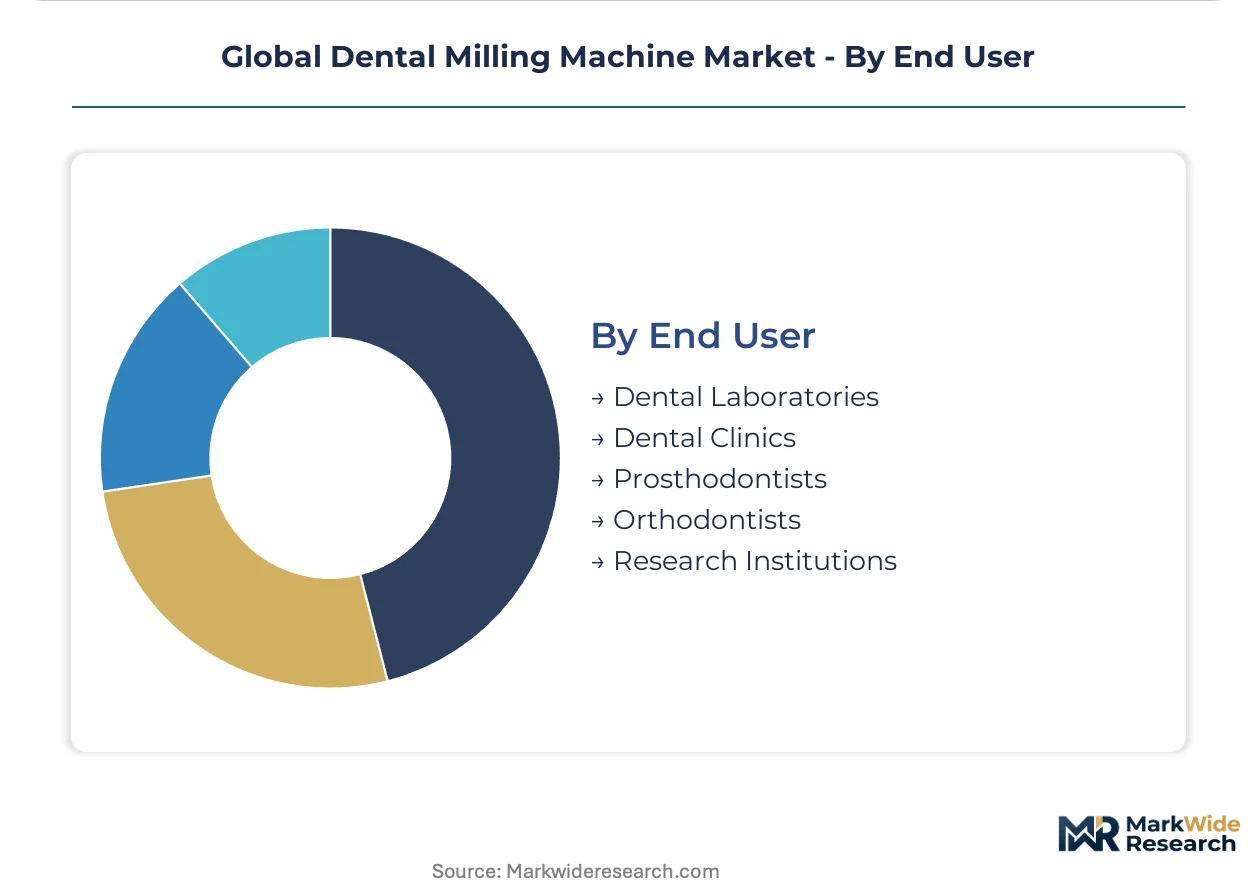
End User:
End-user category determines purchasing authority structure and service contract expectations.
- Dental Laboratories:Commercial production facilities concentrate procurement influence through multi-unit purchasing agreements. French laboratory networks negotiate enterprise pricing for equipment fleets that standardize maintenance protocols across regional hubs.
- Dental Clinics:Individual and group practices prioritize compact footprints and simplified operation interfaces. Brazilian clinic chains are adopting subscription-based equipment access to bypass capital expenditure approval cycles.
- Prosthodontists:Specialist practices demand highest-precision systems for complex full-mouth reconstructions.
- Orthodontists:Appliance-focused operators seek specialized aligner trimming and bracket manufacturing capabilities.
- Research Institutions:Academic and clinical research centers require open-architecture systems for material science experimentation.
Dental Laboratories concentrate purchasing volume; Dental Clinics are expanding their equipment footprint most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering established dental milling as a laboratory discipline during the 1990s, with Japanese spindle technology later enabling the miniaturization required for chairside deployment. Equipment procurement now fragments across regulatory jurisdictions with divergent compliance timelines.
Germany
Dental laboratories in Stuttgart and Munich are upgrading five-axis systems to satisfy EU MDR post-market surveillance documentation for permanent zirconia restorations. The Bundesinstitut für Arzneimittel und Medizinprodukte now requires batch-level material traceability that compresses equipment replacement cycles. Bavarian dental technology clusters around Nuremberg concentrate milling capacity for export to Swiss and Austrian laboratory networks.
United States
Texas and Florida dental clinic chains are deploying chairside systems to capture same-day crown delivery premiums previously lost to laboratory outsourcing. FDA 510(k) premarket notification timelines for AI-integrated milling controls are extending software validation requirements. Dallas-Fort Worth has emerged as a hub for independent technical service networks unbundling from manufacturer captive contracts.
China
Zirconia blank manufacturers in Shenzhen and Guangzhou are integrating downstream into milling equipment distribution to secure captive demand channels. NMPA biocompatibility validation protocols for titanium implant components are tightening import eligibility for foreign equipment suppliers. The Yangtze River Delta dental laboratory corridor around Shanghai processes the highest crown volumes globally using domestically manufactured five-axis machines.
Japan
PMDA cytotoxicity testing documentation requirements for milled titanium implant components are restructuring quality management systems for Korean and German equipment suppliers. Osaka-based dental laboratories maintain sub-5-micrometer tolerance standards that constrain supplier qualification to thermal-compensated spindle architectures. Japanese import distributors now demand sintering-parameter traceability certificates for all zirconia blank origins.
India
Government health insurance expansion into tier-2 cities is creating first-time laboratory milling demand outside established Mumbai and Delhi corridors. CDSCO medical device registration timelines are accelerating as domestic manufacturers seek to substitute imported equipment in price-sensitive segments. Gujarat dental technology clusters around Ahmedabad are scaling CNC milling capacity for acrylic denture base production serving government contract awards.
Global Dental Milling Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision tolerance and software integration depth, with integrated CAD/CAM ecosystems commanding service contract premiums that standalone CNC suppliers cannot replicate. The vendor base stratifies into three tiers: full-workflow integrators, precision spindle specialists, and regional fabrication houses competing on equipment financing terms. Consolidation pressure concentrates among mid-scale laboratory equipment suppliers lacking proprietary design software. Dominant competitive moves include strategic partnerships between milling hardware and intraoral scanner manufacturers, plus geographic expansion through distributor acquisition in emerging dental infrastructure markets.
Within the full-workflow integrator tier, Dentsply Sirona and Planmeca occupy positions defined by captive software ecosystems that collapse design-to-manufacture timelines. Among precision spindle specialists, Roland DG Corporation exemplifies the Japanese equipment archetype emphasizing thermal stability and sub-micrometer repeatability. vhf camfacture represents the German mid-cap specialist model focused on laboratory-scale multi-material flexibility rather than chairside miniaturization. These three anchors illustrate how competitive positioning fragments across integration depth, precision engineering heritage, and scale economics without any single archetype commanding universal preference.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Amann Girrbach |
| Roland DG Corporation |
| Planmeca |
| Ivoclar Vivadent |
| Straumann Group |
| 3M Company |
| vhf camfacture |
| DATRON |
| Others |
Supply & Pricing Matrix
Dental laboratory networks in Germany and France concentrate procurement authority through multi-unit purchasing agreements, anchoring a three-tier pricing structure across premium, standard, and economy levels that stratifies by spindle precision certification and software integration depth. This buyer concentration compresses margin capture for equipment vendors while amplifying price sensitivity among independent dental clinics in Brazil and Mexico.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with differentiation driven by CE marking tier under EU MDR and after-sales service bundling. Cost compression in the economy tier intensifies because Chinese domestic manufacturers are scaling five-axis production for acrylic denture milling. Independent dental clinics in tier-2 Indian cities exhibit highest price sensitivity, while German prosthodontist specialists demonstrate lowest sensitivity due to tolerance-critical applications.
Supply Chain Analysis
CE marking and FDA 510(k) certification gating constrains supplier qualification, with high-purity zirconia blank production anchored in Japan and China and precision spindle manufacturing centered in Germany and Japan. Equipment assembly draws from Taiwanese CNC control systems and Swiss ball-screw components. Single-source vulnerability in Japanese zirconia sintering feedstock exposes buyers to export licensing volatility. Distribution runs through authorized dealer networks with captive service contracts in North America and independent distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France run substantially higher than CDSCO registration expenses in India, creating cost-advantaged production relocation opportunities for mid-scale equipment suppliers.
For Market Incumbents: To counter subscription-based equipment-as-a-service entrants from Brazilian clinic networks, Dentsply Sirona and Amann Girrbach should deepen backward integration into zirconia blank supply through captive partnerships with Japanese sintering specialists. Channel control represents the critical defensive lever, requiring direct service network expansion in Texas and Florida to preempt independent spindle refurbishment competitors. For New Entrants and Emerging Players: Enter via government contract procurement in Gujarat and Maharashtra, where CDSCO-accelerated registration timelines and price-sensitive public health insurance expansion create first-mover laboratory milling demand. The most penetrable segment is acrylic denture base production for tier-2 Indian cities, with go-to-market execution through regional dental technology clusters around Ahmedabad rather than Mumbai-based distributor incumbents. For Investors and Strategic Acquirers: Intraoral scanner manufacturers represent the most active acquirer category in this space, seeking CAD/CAM workflow integration to collapse design-to-manufacture timelines. The five-to-ten-year viability window favors precision spindle specialists with thermal compensation patents over commodity CNC assemblers. Acquisition targets should display proprietary five-axis control software rather than licensed architectures. The signal to monitor is PMDA batch-level material traceability enforcement, which would trigger equipment replacement cycles among Osaka-based laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR post-market surveillance obligations compress equipment upgrade cycles across German laboratory networks. |
| Hospital System Partnership | Dental clinic chains in Texas negotiate enterprise pricing for chairside system fleets with standardized maintenance protocols. |
| Software Companion Development | AI-assisted design tools embedded in CAD workflows reduce technician training time for complex bridge geometries. |
| Backward Integration into Zirconia Supply | Shenzhen blank manufacturers integrate downstream into milling equipment distribution to secure captive demand channels. |
| Reimbursement Strategy Alignment | Government health insurance expansion in Indian tier-2 cities creates first-time laboratory milling procurement authority. |
Research Methodology
Multiple input streams — primary interviews with dental laboratory directors, equipment procurement managers at clinic chains, and biomedical engineers at German precision manufacturing facilities, plus secondary validation against FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and customs trade data — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across the projection horizon applied segmentation modeling by product type, technology architecture, application focus, and end-user category, with additional granularity on regional regulatory cluster and certification tier. CAGRs were derived from equipment shipment trajectories and replacement cycle analysis, incorporating zirconia blank price indices and spindle thermal compensation patent filings as industry-specific forecast inputs.
Inputs from regulatory filings and distributor shipment records were available through the study window; gaps in real-time clinic-level deployment data introduce uncertainty bands around chairside system penetration estimates. Forecasts reflect assumptions on EU MDR enforcement timelines and NMPA biocompatibility validation protocols. A model refresh is warranted upon material change in PMDA cytotoxicity testing documentation requirements for milled titanium implant components.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market