
 Digital Dental Equipment Market | 2026-2036
Digital Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Dental Equipment Market Insights
Zirconia is decoupling from traditional metal-ceramic frameworks in crown and bridge fabrication, compressing unit economics for chairside milling systems. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to dominate North American clinic installations. Planmeca Oy anchors Nordic markets through vertically distributed service networks. 3Shape A/S specializes in open-architecture scanning software that competes against closed hardware-software bundles.
Digital dental equipment encompasses electronically controlled diagnostic, design, and manufacturing systems used in oral healthcare, typically operating at wavelength precision below 10 micrometers for optical scanning and voxel resolutions under 0.3 millimeters for cone beam systems. These technologies enable direct digital workflows from patient anatomy capture to prosthetic fabrication, eliminating physical impression materials and reducing laboratory turnaround intervals. Intraoral scanners now lead product type deployment in developed markets where chairside same-day dentistry commands premium positioning. Dental laboratories represent the fastest-growing end user segment as outsourcing models adopt centralized digital production hubs. Cone beam computed tomography concentrates margin pools among imaging specialists due to higher capital barriers and service contract attachment rates.
The FDA's 510(k) clearance pathway for dental radiological devices shapes product entry timelines for US-bound manufacturers, while the EU Medical Device Regulation imposes clinical evidence requirements that filter smaller scanner vendors from European markets. China's NMPA implements GB standards for medical electrical equipment that foreign OEMs must navigate through local registration holders. Stakeholders must monitor evolving cybersecurity guidance for networked intraoral devices as healthcare IT interoperability mandates expand data connectivity requirements.
Market Dynamics
The transition from physical impressions to optical capture is compressing laboratory turnaround times and forcing equipment vendors to bundle software subscriptions with hardware sales. This shift toward closed digital ecosystems favors manufacturers with captive CAD/CAM software development capabilities.
Growth Catalysts
- CMS Reimbursement Evolution:The Centers for Medicare & Medicaid Services in the United States is expanding coverage verification for digitally documented workflows, accelerating scanner adoption among independent dental clinics seeking guaranteed payment pathways.
- China's Tier-One Hospital Mandates:National health infrastructure directives prioritize cone beam computed tomography upgrades in Beijing, Shanghai, and Guangzhou hospital dental departments, creating concentrated demand for imaging equipment with sub-millimeter voxel resolution.
- Zirconia Milling Precision:Chairside ceramic processing now achieves flexural strength parity with metal-ceramic frameworks, enabling same-day crown delivery that commands premium pricing in fee-for-service practices.
Market Restraints
- EU MDR Recertification Burden:The European Union Medical Device Regulation imposes clinical evidence requirements that extend product approval timelines and filter smaller intraoral scanner vendors from continental markets.
- Capital Intensity Concentration:Cone beam systems require facility modifications for radiation shielding and dedicated electrical infrastructure, limiting deployment to hospital dental departments and large multi-chair group practices.
- Closed Ecosystem Lock-in:Dentsply Sirona's integrated hardware-software bundles create switching costs that deter clinics from adopting open-architecture alternatives despite interoperability advantages.
Strategic Opportunities
- Centralized Laboratory Hubs:Outsourcing models in Germany and the United States are consolidating production into regional digital fabrication centers, creating demand for high-throughput milling systems and automated design software.
- Cybersecurity Compliance Services:FDA guidance on networked device data integrity creates aftermarket revenue streams for manufacturers offering encrypted scanner-to-cloud transmission and audit-ready workflow documentation.
- Service Contract Unbundling:Nordic markets demonstrate appetite for à-la-carte maintenance agreements separate from hardware purchase, allowing third-party technical service providers to capture margin pools previously held by OEMs.
Industry Challenges
- CAD/CAM Operator Training Deficits:Chairside milling requires dental assistants to manage ceramic sintering protocols and toolpath optimization, creating workforce gaps that delay return on equipment investment.
- Cross-Border Data Transfer Complexity:China's NMPA data localization requirements for patient imaging archives complicate cloud-based design collaboration between Chinese clinics and overseas laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Dental Equipment Market |
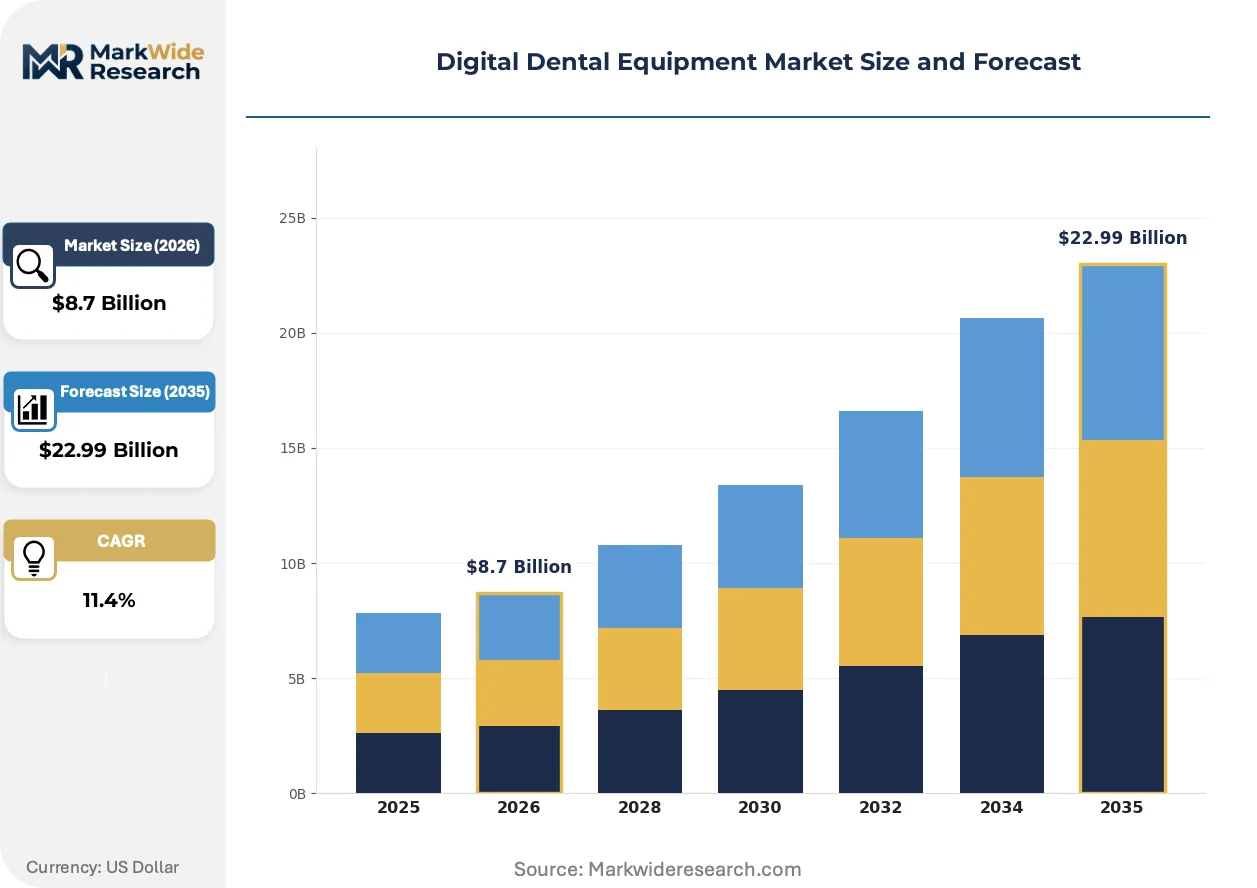
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD/CAM Systems, Intraoral Scanners, Digital X-rays, 3D Printers End User: Dental Clinics, Hospitals, Dental Laboratories, Educational Institutions Technology: Laser Imaging, Cone Beam Computed Tomography, Optical Scanning, Stereolithography Application: Orthodontics, Prosthodontics, Restorative Dentistry, Periodontics |
| Companies Covered | Dentsply Sirona, Align Technology, 3M Company, Planmeca Oy, Envista Holdings Corporation, 3Shape A/S, Ivoclar Vivadent AG, Straumann Group, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Dental Equipment Market Trends and Innovations
Workflow integration is eliminating friction between anatomical capture and prosthetic fabrication. Three developments are compressing the traditional laboratory intermediary role and reshaping competitive positioning among equipment suppliers.
Intraoral scanning hardware is unifying with real-time AI-assisted margin detection to reduce retake rates and chair time. Dental clinics in Germany and the United States are deploying these systems at replacement cycles of four to five years, faster than traditional radiography equipment. This convergence is compressing the market for standalone impression material manufacturers and forcing dental supply distributors to restructure their product portfolios.
The EU Medical Device Regulation's clinical evidence requirements for Class IIa devices are extending scanner approval timelines and favoring manufacturers with established European notified body relationships. Smaller Asian OEMs are redirecting product development resources toward US FDA 510(k) pathways rather than European market entry. This regulatory friction is concentrating European scanner supply among incumbent vendors with pre-MDR legacy certifications.
Chinese hospital procurement is consolidating around state-approved vendor lists that prioritize domestic equipment manufacturers for cone beam systems under national health infrastructure mandates. Foreign OEMs are responding by forming joint ventures with local registration holders to maintain access to tier-one city hospital dental departments. This state-directed purchasing behavior is displacing open competitive tendering in the world's second-largest equipment market.
Digital Dental Equipment Market Segmentation
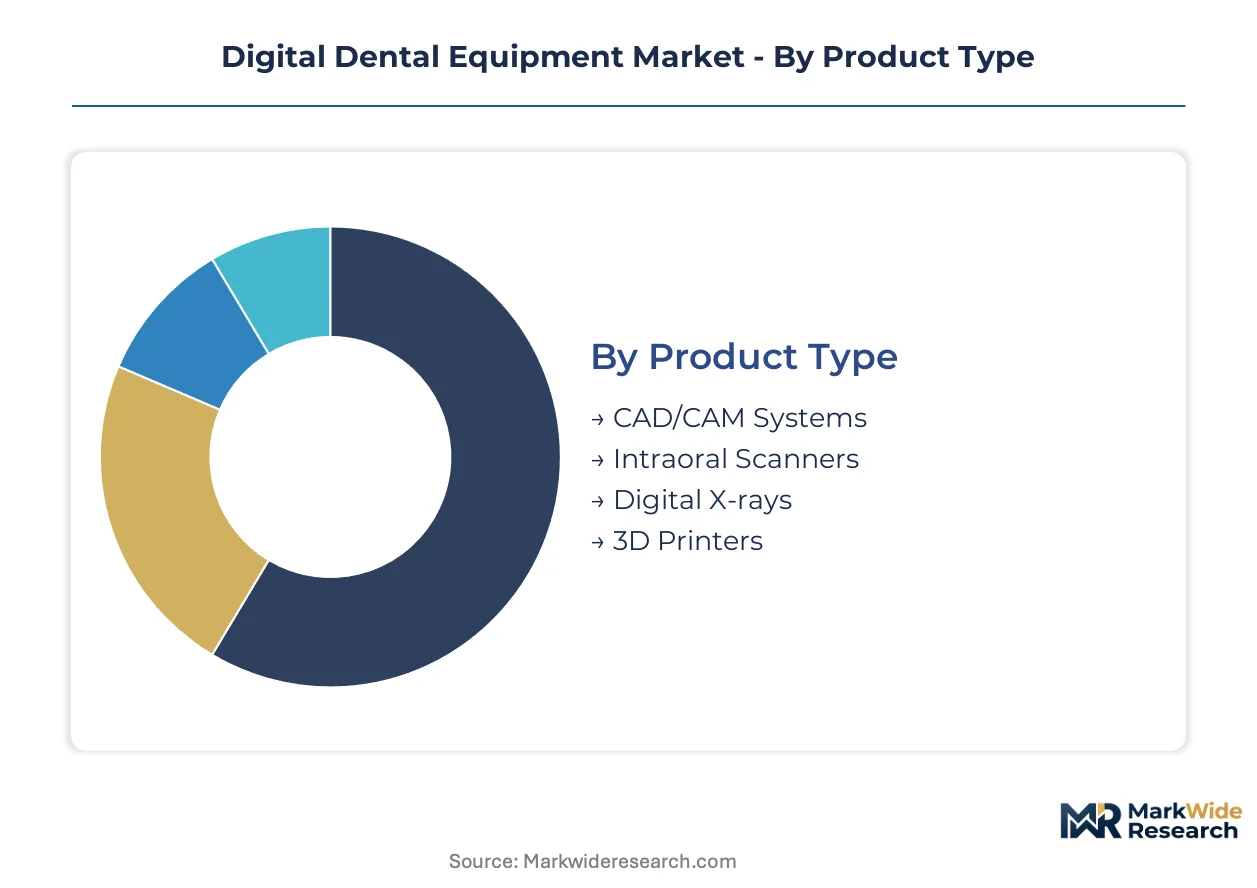
Equipment segmentation in digital dentistry reveals divergent capital requirements and workflow integration challenges. Each category maps distinct investment thresholds to specific clinical or laboratory environments, shaping vendor go-to-market priorities and service contract structures.
Product Type:
Capital intensity varies dramatically across hardware categories, with imaging infrastructure demanding facility modifications while chairside fabrication units require consumable supply chains.
- CAD/CAM Systems:Integrated design-and-milling platforms process zirconia, lithium disilicate, and composite blocks through 5-axis machining centers with toolpath optimization software. Hospital dental departments in China and large US group practices deploy these for same-day crown delivery, though ceramic sintering furnaces add secondary electrical load requirements.
- Intraoral Scanners:Optical capture devices operating at wavelength precision below 10 micrometers generate STL files for immediate design workflow. Independent dental clinics in Germany and the United States drive replacement cycles every four to five years as CMS reimbursement verification expands for digitally documented impressions.
- Digital X-rays:Solid-state sensors and phosphor plate systems replace analog film with immediate image display.
- 3D Printers:Photopolymerization and powder-bed fusion systems fabricate surgical guides and temporary restorations.
Most installed capacity flows through Intraoral Scanners. Expansion is steepest in CAD/CAM Systems.
End User:
Procurement authority concentrates differently across settings, with hospital purchasing committees managing multi-year capital budgets while independent clinics prioritize monthly payment financing.
- Dental Clinics:Single-chair and small-group practices prioritize compact footprint equipment with minimal facility modification. China's tier-one cities and US metropolitan areas concentrate demand for chairside milling as fee-for-service models reward reduced appointment counts.
- Hospitals:Academic medical centers and community hospital dental departments manage radiation shielding infrastructure and service contract portfolios. Beijing, Shanghai, and Guangzhou hospital procurement follows state-approved vendor lists prioritizing cone beam systems with sub-millimeter voxel resolution.
- Dental Laboratories:Centralized production hubs in Germany and the United States consolidate high-throughput milling capacity.
- Educational Institutions:Dental schools require training-compatible equipment with extended warranty terms.
Volume concentrates in Dental Clinics. Dental Laboratories are gaining share fastest.
Technology:
Technical architecture determines regulatory pathway complexity, with ionizing radiation systems facing distinct approval timelines from optical non-contact methods.
- Cone Beam Computed Tomography:Volumetric imaging systems achieve voxel resolutions under 0.3 millimeters for implant planning and endodontic assessment. Hospital dental departments in China and large US group practices justify capital expenditure through radiation shielding infrastructure and dedicated electrical supply requirements.
- Optical Scanning:Structured light and confocal microscopy systems capture surface topology without patient exposure. German and US clinics deploy these for orthodontic monitoring and restorative workflows where rapid scan-repeat cycles reduce chair time.
- Laser Imaging:Coherent light detection enables caries diagnosis and soft tissue assessment.
- Stereolithography:Layered photopolymerization constructs surgical guides and dental models.
Deployment concentrates in Optical Scanning. Cone Beam Computed Tomography shows the steepest expansion trajectory.
Application:
Clinical specialty determines equipment utilization rates and consumable attachment, with high-volume restorative procedures amortizing capital costs faster than specialized periodontal applications.
- Prosthodontics:Crown, bridge, and implant restoration workflows integrate intraoral scanning with CAD/CAM fabrication or laboratory outsourcing. US fee-for-service practices and German private clinics command premium pricing for same-day ceramic delivery.
- Orthodontics:Clear aligner therapy and bracket positioning rely on digital model accuracy for treatment planning. China's tier-one cities concentrate demand as hospital dental departments expand orthodontic service lines under national health infrastructure mandates.
- Restorative Dentistry:Direct and indirect filling procedures utilize digital impression verification.
- Periodontics:Soft tissue assessment and regenerative procedures employ specialized imaging modalities.
Procedure volume concentrates in Prosthodontics. Orthodontics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Mittelstand dental technology cluster anchors European equipment innovation through precision manufacturing ecosystems in Baden-Württemberg and Bavaria. National procurement patterns diverge sharply across regulatory environments, with reimbursement frameworks and hospital purchasing mandates reshaping vendor access.
United States
Independent dental clinics in metropolitan corridors drive intraoral scanner replacement cycles every four to five years as CMS reimbursement verification expands for digitally documented workflows. FDA 510(k) clearance pathways for dental radiological devices shape product entry timelines for manufacturers targeting US-bound distribution. Greater Boston and Pacific Northwest clusters concentrate CAD/CAM adoption among fee-for-service practices commanding premium pricing for same-day ceramic delivery.
Germany
EU MDR clinical evidence requirements for Class IIa devices extend scanner approval timelines and filter smaller vendors from continental markets. Medical Device Regulation alignment accelerates product recertification timelines for manufacturers serving European practices. Bavaria and North Rhine-Westphalia hospital dental departments prioritize cone beam systems through state-level procurement frameworks that favor established notified body relationships.
China
Beijing, Shanghai, and Guangzhou hospital dental departments concentrate demand for imaging equipment with sub-millimeter voxel resolution under national health infrastructure mandates. NMPA implements GB standards for medical electrical equipment that foreign OEMs navigate through local registration holders. Yangtze River Delta and Pearl River Delta procurement committees consolidate around state-approved vendor lists prioritizing domestic manufacturers for cone beam systems.
Japan
PMDA regulatory pathways for medical devices maintain rigorous clinical evidence standards that favor incumbent vendors with established quality management systems. METI industrial policy supports precision optics manufacturing for dental scanning applications through regional technology clusters. Kanto and Kansai metropolitan areas concentrate private clinic demand for chairside milling systems as aging demographics expand prosthodontic procedure volumes.
South Korea
MFDS medical device approval frameworks align with international harmonization initiatives while maintaining distinct documentation requirements for software-enabled dental equipment. Seoul Capital Area hospital networks drive cone beam adoption through centralized capital budgeting for radiation-shielded imaging infrastructure. Busan-Ulsan manufacturing corridors supply precision optical components for intraoral scanner assembly serving Asia-Pacific distribution channels.
Digital Dental Equipment Market Competitive Landscape
Global majors compete with regional champions across integrated ecosystem versus open-architecture positioning. The vendor base stratifies into three tiers: full-stack platform operators controlling hardware-software bundles, specialized component suppliers licensing scanning engines to third-party fabricators, and regional service-anchored distributors maintaining technical support networks. Consolidation pressure intensifies as CAD/CAM workflow integration demands captive software development capabilities. Strategic moves center on M&A targeting design software assets and geographic expansion through joint venture structures in regulated Asian markets.
Within the integrated platform tier, Dentsply Sirona and Planmeca Oy represent contrasting geographic anchoring strategies—US-based full-stack dominance versus Nordic service-network penetration. Among open-architecture specialists, 3Shape A/S exemplifies software-centric positioning that competes against closed hardware-software bundles. Envista Holdings Corporation occupies a position between these archetypes, reflecting mid-scale portfolio diversification across imaging and fabrication segments.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Align Technology |
| 3M Company |
| Planmeca Oy |
| Envista Holdings Corporation |
| 3Shape A/S |
| Ivoclar Vivadent AG |
| Straumann Group |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
Zirconia milling precision improvements simultaneously compress unit economics for chairside fabrication and concentrate supply power among integrated CAD/CAM platform operators. This dual restructuring forces independent scanner vendors to absorb ceramic block cost volatility while full-stack manufacturers capture margin through captive consumable supply.
Pricing Analysis
Input-cost pass-through from optical component shortages and rare-earth magnet supply constraints shapes tiered hardware pricing. Premium-mid-economy pricing differentiation separates FDA-cleared systems from CE-marked alternatives and unregistered Asian imports. Pricing pressure stems from Chinese domestic manufacturers undercutting foreign OEMs in tier-one hospital procurement. Independent dental clinics in Germany exhibit highest price sensitivity due to fragmented purchasing power, while US group practices accept premium positioning for same-day workflow guarantees.
Supply Chain Analysis
Reverse-logistics networks for intraoral scanner refurbishment and milling spindle remanufacturing concentrate service revenue among Nordic and German technical providers. Component sourcing draws from German precision optics manufacturers, Japanese solid-state sensor fabricators, and Chinese rare-earth processing facilities. Single-source vulnerability sits with CMOS image sensor foundries in East Asia. Distribution runs through dental supply distributors restructuring portfolios around digital workflow bundles rather than standalone consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
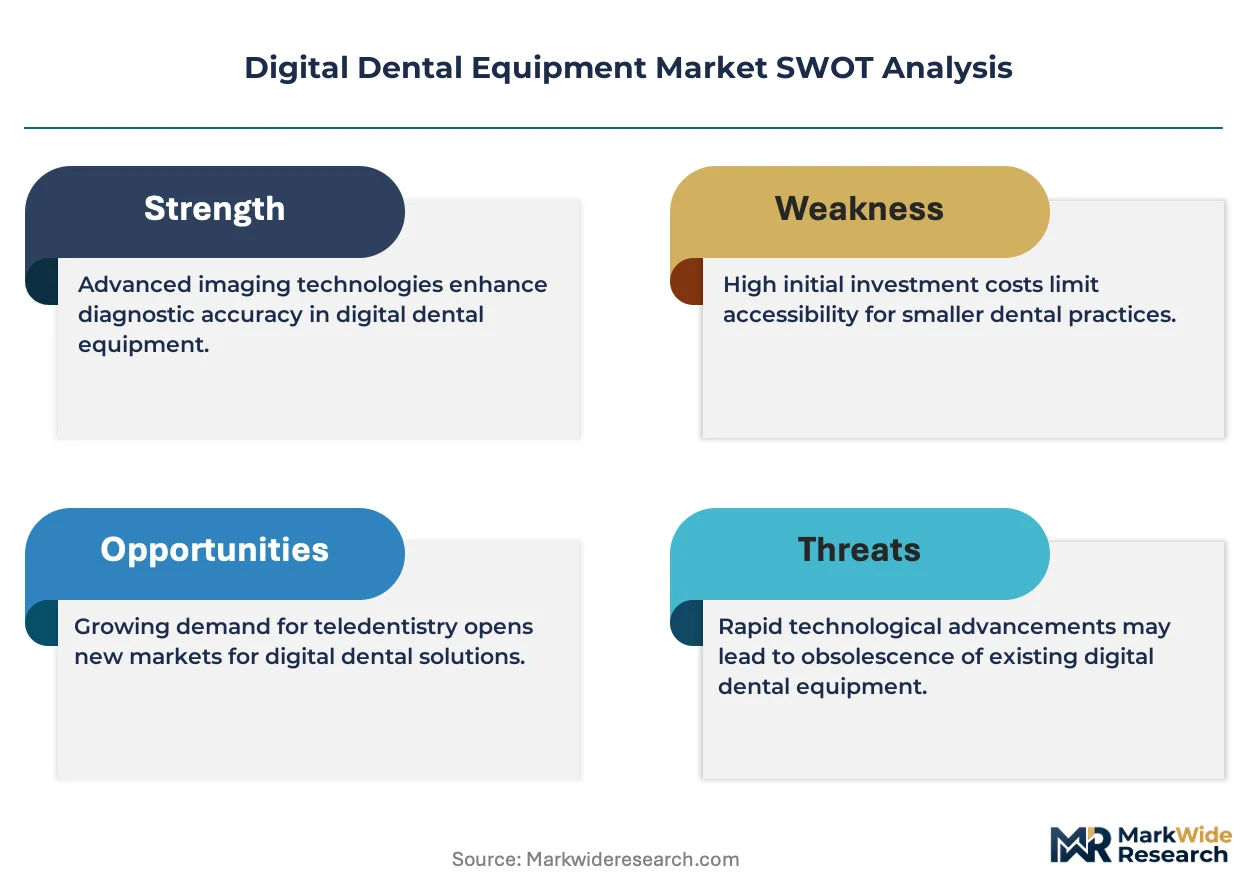
The Digital Dental Equipment Market represents a late-cycle quality story as fee-for-service practices prioritize sub-10-micrometer optical precision and same-day ceramic delivery over cost-minimized alternatives.
For Market Incumbents: Cement ecosystem lock-in through mandatory software subscription bundling with hardware replacement cycles. Deepen backward integration into zirconia blank manufacturing to offset ceramic supplier margin capture. Defend against open-architecture specialists by accelerating AI-assisted margin detection feature releases that increase switching costs.
For New Entrants and Emerging Players: FDA 510(k) clearance pathway streamlining opens a window for focused scanner vendors targeting US independent clinic replacement demand. Target dental laboratory outsourcing hubs in Germany and the United States with high-throughput milling systems designed for centralized production. Pursue joint venture structures with Chinese local registration holders to access tier-one hospital procurement under NMPA GB standards compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among open-architecture software specialists lacking captive hardware manufacturing. Five-to-ten year viability favors vendors with demonstrated notified body relationships for EU MDR Class IIa recertification. Monitor CMS reimbursement verification expansion velocity as inflection indicator for scanner replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Platform Integration | Closed ecosystems capture consumable recurring revenue from chairside milling workflows. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements filter smaller competitors from continental market access. |
| Hospital System Partnership | State-approved vendor lists in China concentrate procurement authority among joint venture operators. |
| Software Companion Development | AI-assisted margin detection reduces retake rates and compresses chair time for competitive differentiation. |
| Reimbursement Strategy | CMS digitally documented workflow verification accelerates scanner adoption among payment-sensitive clinics. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with dental equipment procurement managers, biomedical engineers at hospital dental departments, GPO contracts administrators, and CAD/CAM workflow specialists. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body certification records, CMS reimbursement policy releases, and NMPA registration filings. Bottom-up equipment unit estimates and top-down market size triangulation cross-verify segmentation outputs.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions model product type, end user setting, technology architecture, and clinical application with regional regulatory cluster overlays. CAGR derivation incorporates equipment replacement cycle dynamics, reimbursement policy elasticity, and hospital capital budget allocation patterns specific to dental infrastructure mandates.
Revisions become necessary when cybersecurity guidance for networked devices, data localization enforcement, or ceramic material supply disruptions materialize outside baseline assumptions. Practitioners should monitor CMS reimbursement verification expansion, EU MDR recertification completion rates, and Chinese state-approved vendor list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Lights Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Global Dental Light Curing Equipment Market