
 Europe Dental Equipment Market | 2026-2036
Europe Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Equipment Market Foresight
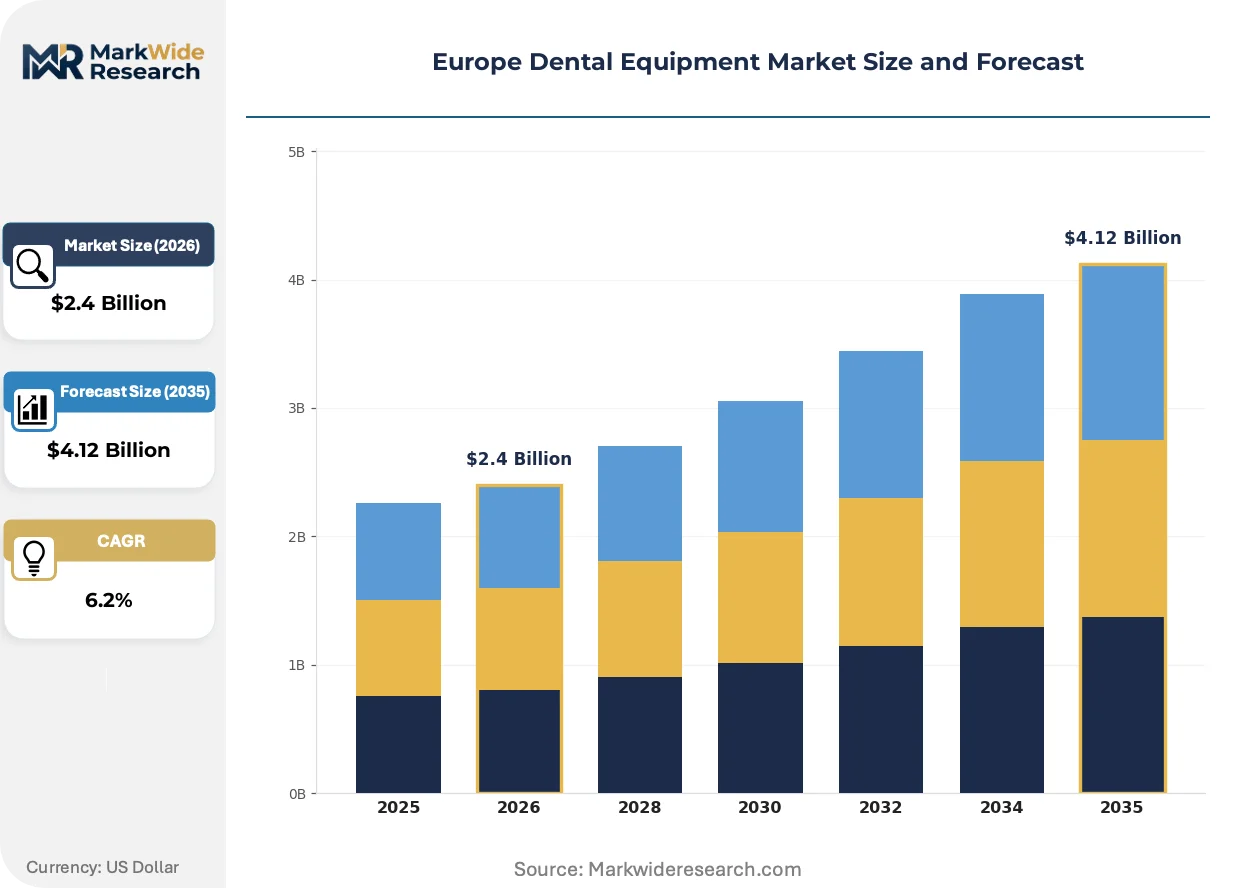
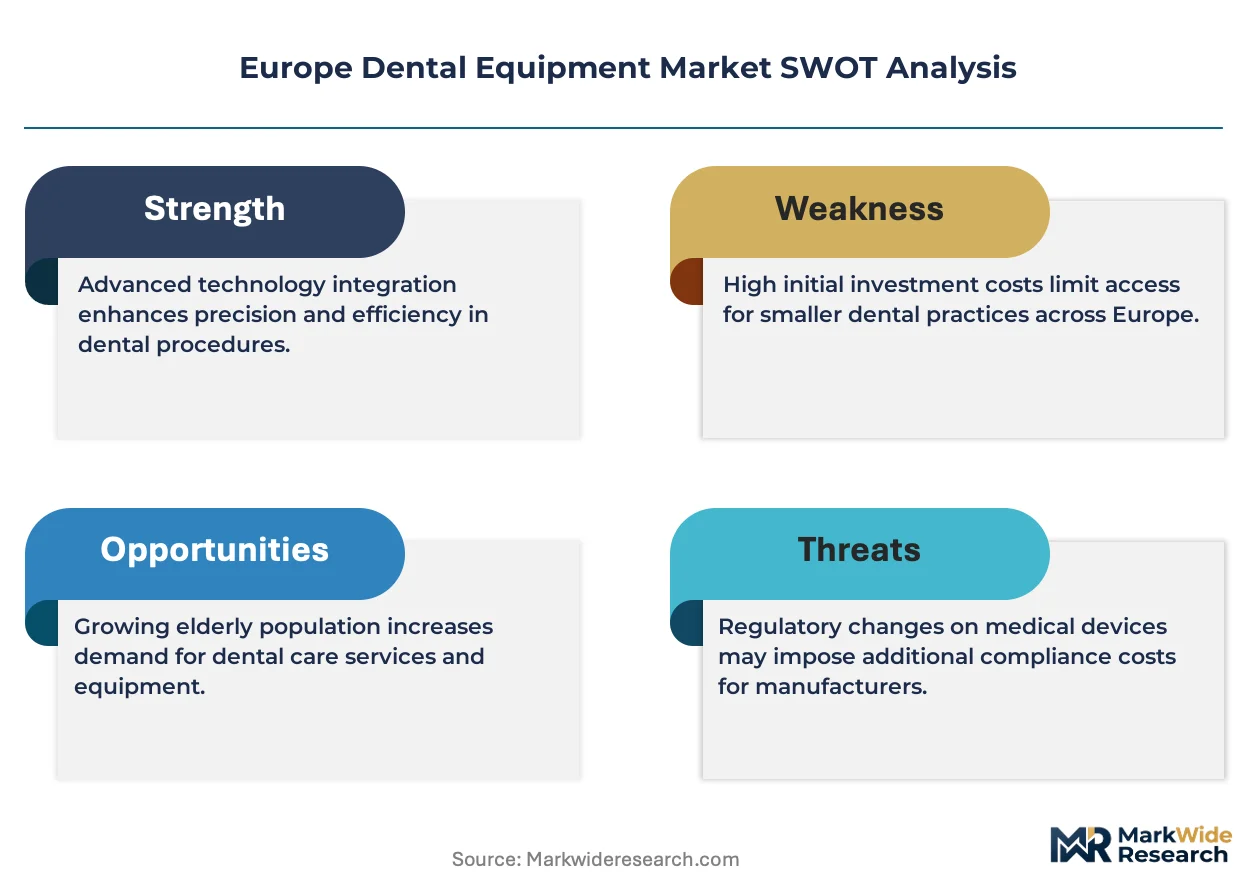
The EU Medical Device Regulation is restructuring procurement criteria across European dental practices. Dentsply Sirona leverages its digital dentistry ecosystem to sustain installed-base loyalty across German and French clinics. Planmeca Oy anchors Nordic market share through integrated imaging and software platforms. Ivoclar Vivadent AG differentiates via materials science leadership in chairside restorative workflows.
Europe dental equipment encompasses electromechanical systems, diagnostic imaging platforms, and consumable-driven instruments designed for intraoral intervention, with precision tolerances typically measured in micrometers for CAD/CAM milling units and handpiece rotational speeds exceeding 300,000 RPM. Dental chairs and imaging equipment represent mature installed-base segments where replacement cycles generate predictable revenue pools, while 3D printing and laser technology categories attract accelerated capital allocation as clinics pursue same-day restoration capabilities. Digital impressions and computer-aided design tools command premium positioning by compressing chair time and laboratory turnaround.
EMA and notified body frameworks under MDR enforce biocompatibility and clinical evidence standards that lengthen product registration timelines but elevate barriers for non-compliant suppliers. CE marking requirements and GDPR protocols for patient imaging data shape both hardware design and cloud-connected service architectures. Stakeholders must monitor evolving EU AI Act applicability to diagnostic algorithms embedded in intraoral scanners and radiographic analysis software.
Market Dynamics
EU Medical Device Regulation compliance timelines are compressing procurement cycles across European dental practices, forcing clinics to accelerate digital infrastructure investments before legacy equipment loses CE marking validity under MDR transition deadlines.
Growth Catalysts
- MDR compliance mandates:The EU Medical Device Regulation requires renewed clinical evidence and biocompatibility documentation for Class IIa and above devices, creating replacement demand for aging installed bases across German and French clinics.
- Same-day restoration workflows:Chairside CAD/CAM milling and 3D printing are absorbing capital allocations from traditional laboratory outsourcing, compressing treatment timelines from weeks to hours in Nordic private practices.
- Italy:Dental tourism clusters in Milan and Rome are upgrading imaging and sterilization equipment to attract cross-border patients from Switzerland and Austria, driving premium equipment imports.
Market Restraints
- Notified body bottlenecks:EMA-designated conformity assessment organizations face capacity constraints, extending MDR certification timelines to 18-24 months for novel laser and imaging systems.
- Titanium and cobalt-chrome price volatility:Raw material input costs for milling blanks and implant components fluctuate with aerospace sector demand, squeezing gross margins for chairside restoration providers.
- Legacy analog handpiece installed base:Decades-old pneumatic turbine systems in Southern European public clinics resist digital workflow integration, delaying ecosystem lock-in for integrated platform vendors.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated private dental networks in Central Europe present whitespace for mid-tier digital impression and basic CAD/CAM systems as disposable incomes rise.
- EU AI Act applicability:Diagnostic algorithms embedded in intraoral scanners and radiographic analysis software face emerging conformity requirements, creating first-mover advantage for vendors with pre-validated machine learning pipelines.
- Subscription-based equipment access:Pay-per-use models for 3D printers and milling units are displacing capital purchase patterns among Spanish and Portuguese group practice chains, lowering barrier-to-entry for advanced technology.
Industry Challenges
- Digital dentistry technician scarcity:CAD/CAM design and 3D printing operation skills lag equipment deployment rates, forcing clinics to retain external laboratory partnerships despite chairside hardware investments.
- GDPR imaging data architecture:Cloud-connected intraoral scanners and treatment planning software require patient data localization compliance, complicating multi-clinic network deployments across German Länder with varying interpretation of federal privacy standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Equipment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Chairs, Imaging Equipment, Handpieces, Sterilization Equipment End User: Dental Clinics, Hospitals, Research Institutions, Dental Laboratories Technology: 3D Printing, Laser Technology, Digital Impressions, Computer-Aided Design Application: Oral Surgery, Orthodontics, Prosthodontics, Periodontics |
| Companies Covered | Ivoclar Vivadent AG, DÜRR DENTAL, Dentsply Sirona, Carestream Health, A-dec Inc., Planmeca Oy, Henry Schein Dental, 3M, Straumann Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Equipment Market Shifts & Advancements
Digital workflow convergence is restructuring how European dental practices source, operate, and monetize clinical equipment, with regulatory pressure and patient expectation shifts acting as twin accelerants.
Intraoral scanners are absorbing the diagnostic and impression-taking functions previously distributed across multiple analog devices, compressing chair time and laboratory communication overhead. German and French group practices are standardizing on single-vendor scanner ecosystems to lock in software upgrade paths and training efficiencies. This technology absorption is enabling same-day restorative workflows that bypass traditional physical model shipping and casting delays.
EU AI Act risk classification requirements are reshaping development roadmaps for diagnostic software embedded in imaging platforms. Vendors must now document algorithmic transparency and clinical validation datasets before CE marking, extending product launch timelines but elevating barriers for non-compliant competitors. Intraoral scanner and panoramic radiography segments face the steepest compliance recalibration as computer-aided detection features proliferate.
Spanish and Portuguese dental group chains are unbundling after-sales service contracts from equipment purchases, preferring third-party maintenance providers or in-house biomedical technician training. This procurement fragmentation is pressuring incumbent vendors to modularize service offerings and compete on response-time guarantees rather than bundled warranty premiums. The shift is most visible in high-velocity replacement categories like handpieces and curing lights where downtime tolerance is minimal.
Europe Dental Equipment Market Segmentation
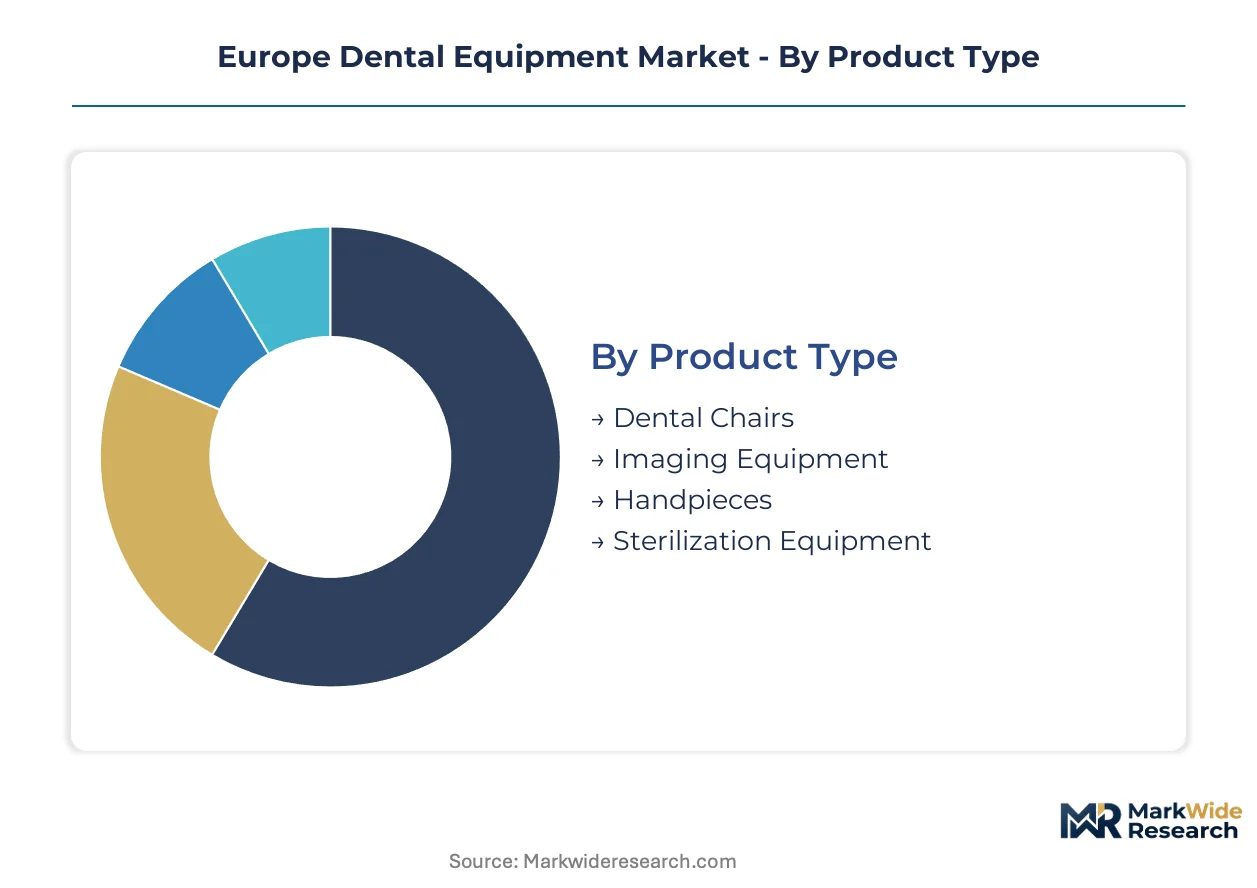
Equipment procurement patterns across European dental practices diverge sharply by clinical workflow intensity and regulatory exposure. Segmentation reveals where MDR compliance costs concentrate replacement demand versus where emerging technologies capture capital reallocation.
Product Type:
Capital allocation decisions pivot on replacement cycle predictability and digital integration potential.
- Dental Chairs:Electromechanical platforms with integrated delivery systems and patient positioning controls. German group practices drive demand for modular upgrade paths that preserve chassis investments while swapping upholstery and instrumentation modules.
- Imaging Equipment:Panoramic radiography and cone-beam computed tomography systems with micrometer-resolution detectors. French clinics concentrate purchases here to satisfy MDR clinical evidence requirements for diagnostic device recertification.
- Handpieces:High-speed turbine and electric micromotor instruments exceeding 300,000 RPM rotational speeds. Italian private networks prioritize cordless battery platforms for operatory flexibility.
- Sterilization Equipment:Autoclave and chemiclave systems for instrument reprocessing compliance. Spanish dental tourism clusters upgrade capacity to handle elevated patient throughput.
Volume sits with Dental Chairs; growth tilts toward Imaging Equipment.
End User:
Procurement scale and technology sophistication separate institutional buyers from independent operators.
- Dental Clinics:Private practice networks and solo practitioners delivering chairside care. Nordic group chains concentrate CAD/CAM investments to compress laboratory turnaround and capture margin.
- Hospitals:Academic medical centers and public health institutions with multi-specialty dental departments. German university hospitals anchor demand for research-grade imaging platforms with AI-embedded diagnostic software.
- Research Institutions:Universities and dental schools conducting clinical validation studies. EMA-designated notified bodies reference their biocompatibility testing protocols for MDR submissions.
- Dental Laboratories:Independent and clinic-captive fabrication centers producing crowns, bridges, and appliances. Polish laboratories absorb mid-tier 3D printer deployments as chairside milling displaces traditional casting.
Procurement volume clusters with Dental Clinics; steepest expansion trajectory belongs to Dental Laboratories adopting distributed manufacturing.
Technology:
Workflow compression capabilities determine premium positioning and vendor ecosystem lock-in.
- 3D Printing:Photopolymer and metal powder bed fusion systems producing surgical guides and provisional restorations. Portuguese group practices deploy chairside units to eliminate external laboratory shipping delays.
- Laser Technology:Erbium and diode wavelength platforms for soft-tissue surgery and caries preparation. Italian aesthetic dentistry clinics concentrate demand for minimally invasive applications.
- Digital Impressions:Intraoral scanners capturing sub-10-micron accuracy surface data. GDPR patient data localization requirements complicate cloud-connected deployments across German Länder.
- Computer-Aided Design:Treatment planning and restoration design software with integrated milling machine communication. French clinics standardize on single-vendor stacks to streamline training and upgrade paths.
Installed base concentrates in Computer-Aided Design; adoption velocity peaks with 3D Printing.
Application:
Clinical specialty requirements dictate equipment specification and reimbursement environment.
- Oral Surgery:Implant placement and bone grafting procedures requiring surgical guides and piezoelectric instruments. Swiss border clinics serving dental tourists invest in navigation-enabled implantology suites.
- Orthodontics:Clear aligner therapy and fixed appliance systems. Czech private practices expand intraoral scanner penetration to capture aligner case volume from laboratory competitors.
- Prosthodontics:Crown, bridge, and denture fabrication with chairside milling or laboratory outsourcing. Austrian clinics balance CAD/CAM investments against technician scarcity constraints.
- Periodontics:Soft-tissue management and regenerative procedures. Laser technology adoption concentrates here for patient comfort differentiation.
Revenue pools concentrate in Prosthodontics; technology refresh cycles accelerate fastest in Orthodontics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors dental tourism infrastructure investment across Southern Europe, with Swiss and Austrian cross-border patients driving premium equipment procurement in Lombardy clinics. The EU Medical Device Regulation compliance deadlines are compressing replacement cycles unevenly across national markets.
Germany
German group practices concentrate CAD/CAM investments in Bavaria and North Rhine-Westphalia to compress laboratory turnaround. CE marking renewal requirements under MDR force accelerated imaging equipment replacement in academic medical centers. Frankfurt and Munich dental clusters standardize on single-vendor digital ecosystems to streamline training overhead.
France
French private clinics absorb chairside milling systems to capture prosthodontic margin from external laboratories. ANSM biocompatibility documentation requirements extend product registration timelines for novel laser platforms. Paris and Lyon metropolitan practices drive demand for AI-embedded diagnostic software ahead of EU AI Act implementation.
Italy
Italian aesthetic dentistry clinics concentrate erbium laser adoption in Rome and Milan for minimally invasive differentiation. MDR transition deadlines force sterilization equipment upgrades in dental tourism corridors serving Swiss patients. Northern Italian private networks prioritize cordless handpiece platforms for operatory flexibility.
Poland
Polish dental laboratories absorb mid-tier 3D printer deployments as chairside milling displaces traditional casting workflows. Rising disposable incomes in Warsaw and Krakow private practices drive intraoral scanner penetration. The country's notified body capacity constraints delay MDR certification for imported imaging systems.
Spain
Spanish dental group chains unbundle service contracts from equipment purchases, preferring third-party maintenance or in-house biomedical technician training. GDPR patient data localization requirements complicate cloud-connected scanner deployments across autonomous communities. Barcelona and Madrid clusters lead subscription-based access models for milling units.
Europe Dental Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across digital integration depth and installed-base loyalty dimensions. The vendor landscape consolidates around integrated platform ecosystems versus point-solution specialists. Three archetypes dominate: full-stack digital dentistry providers, materials-science specialists, and distribution-anchored service integrators. M&A activity concentrates on software capabilities and regional service networks, while portfolio diversification targets chairside workflow compression.
Among Switzerland-based materials specialists, Ivoclar Vivadent AG exemplifies the restorative workflow archetype. German fabricator DÜRR DENTAL occupies a position within the infection control and imaging equipment tier. Finnish platform provider Planmeca Oy represents the integrated imaging-software ecosystem model. These three anchors illustrate how geographic concentration around Lake Constance, Southern Germany, and the Nordic region shapes competitive clustering.
| Leading Market Players |
|---|
| Ivoclar Vivadent AG |
| DÜRR DENTAL |
| Dentsply Sirona |
| Carestream Health |
| A-dec Inc. |
| Planmeca Oy |
| Henry Schein Dental |
| 3M |
| Straumann Group |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up dental group chains across Spain and Portugal are consolidating procurement leverage to extract service unbundling concessions from incumbent vendors, compressing aftermarket margins while redirecting capital toward subscription-based equipment access models that lower upfront barriers for chairside technology.
Pricing Analysis
Outcome-based pricing anchors equipment procurement decisions, with German group practices paying premium rates for guaranteed uptime clauses in CAD/CAM service contracts while Southern European public clinics prioritize lowest capital outlay for sterilization and handpiece categories. Price differentiation separates MDR-certified imaging platforms from legacy analog equipment facing CE marking expiration, with certification tier and after-sales bundling as primary drivers. Pricing pressure stems from titanium and cobalt-chrome milling blank cost volatility feeding through to chairside restoration margins. Public sector buyers in Italy and Spain exhibit highest price sensitivity; private Nordic networks tolerate premium positioning for same-day workflow compression.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision component fabricators supplying high-RPM turbine bearings and micrometer-grade optical sensors for intraoral scanners. Manufacturing concentration in Germany, Switzerland, and Finland feeds European demand for imaging detectors and CAD/CAM milling spindles. Raw material dependencies encompass aerospace-grade titanium alloys, rare-earth optical glass, and photopolymer resins for 3D printing applications. Supply chain risk centers on EMA-designated notified body capacity constraints extending MDR certification timelines for novel laser platforms. Distribution runs through specialized dental dealer networks with regional service capabilities, though direct manufacturer relationships are penetrating large group practice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body bottlenecks are constraining MDR certification throughput for imaging and laser systems, propping pricing power for vendors with pre-validated product portfolios as clinics face compressed replacement deadlines.
For Market Incumbents: Deploy ecosystem lock-in strategies by bundling intraoral scanner hardware with proprietary CAD/CAM software upgrade paths that raise switching costs for German and French group practices. Deepen backward integration into milling blank production to buffer titanium price volatility squeezing chairside restoration margins. Counter third-party maintenance encroachment in Spain and Portugal with response-time guarantees rather than bundled warranty premiums. For New Entrants and Emerging Players: Mid-tier private dental networks in Poland and the Czech Republic represent whitespace for digital impression systems as disposable incomes rise and laboratory outsourcing costs climb. Target subscription-based equipment access models for Portuguese and Spanish group practice chains seeking to lower capital barriers for 3D printing and milling technology deployment. Partner with regional dental schools to embed training protocols that address CAD/CAM technician scarcity constraining chairside utilization. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier imaging specialists with MDR certification pipelines stalled by notified body capacity constraints across Germany and France. Long-term viability hinges on software-enabled recurring revenue streams rather than transactional equipment sales. Monitor EU AI Act implementation timelines as inflection indicator for diagnostic algorithm validation costs reshaping competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pipeline Investment | EMA notified body relationships accelerate market access for imaging platforms ahead of legacy equipment expiration deadlines. |
| Subscription-Based Equipment Access | Pay-per-use models for 3D printers lower barrier-to-entry for Spanish and Portuguese group practice chains. |
| Backward Integration into Milling Blanks | In-house titanium alloy sourcing buffers aerospace demand volatility squeezing chairside restoration margins. |
| AI-Embedded Diagnostic Software Development | Pre-validated machine learning pipelines create first-mover advantage under emerging EU AI Act conformity requirements. |
| Regional Service Network Expansion | Third-party maintenance capabilities capture procurement fragmentation as clinics unbundle service from equipment purchases. |
Research Methodology
Document review covered EMA MDR transition guidance, ANSM biocompatibility documentation requirements, and CE marking renewal databases, complemented by interviews with dental clinic procurement directors, biomedical equipment engineers, GPO contracts managers, and dental laboratory operations heads. Secondary validation drew from customs trade data for imaging equipment imports, hospital procurement registries, and notified body certification disclosure records. Bottom-up equipment deployment estimates triangulated against top-down market sizing derived from manufacturer revenue disclosures and dealer network capacity assessments.
Segment-level projections across product type, end user, technology, and application dimensions fed into analytical framework outputs spanning the projection horizon. CAGRs were derived from replacement cycle analysis, MDR compliance deadline impact modeling, and digital workflow adoption curve fitting. Industry-specific forecast inputs encompassed titanium and cobalt-chrome price elasticity coefficients, intraoral scanner penetration rates by practice size tier, and laser technology reimbursement pathway development across national markets.
Revisions become necessary when notified body capacity expansion materially accelerates MDR certification timelines, when EU AI Act diagnostic algorithm requirements shift validation cost structures, or when raw material price volatility disrupts milling blank supply economics. Forecasts reflect documented assumptions regarding regulatory transition pacing and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market