
 Veterinary Dental (Dentistry) Equipment Market | 2026-2036
Veterinary Dental (Dentistry) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Dental (Dentistry) Equipment Market Analytics
A shift from single-source equipment procurement to multi-vendor platform sourcing is expanding as veterinary groups consolidate purchasing across dental, imaging, and surgical suites. Henry Schein, Inc. leverages its distribution density to bundle dental units with consumables and service contracts. Planmeca Oy anchors the high-value imaging tier with panoramic and intraoral radiography systems engineered for veterinary anatomy. Midmark Corporation competes through ergonomic dental delivery systems optimized for multi-species practices.
Veterinary dental equipment encompasses specialized instruments, diagnostic imaging systems, treatment units, and powered devices designed for oral cavity procedures in companion and production animals, typically operating at frequencies between 18 kHz and 45 kHz for ultrasonic scalers and requiring species-specific mouth speculums. Its primary commercial purpose is to enable veterinary practitioners to diagnose periodontal pathology, perform extractions, and deliver preventive prophylaxis with precision comparable to human dentistry. Ultrasonic scalers and dental X-rays together constitute the revenue core, with extraction instruments capturing disproportionate margin contribution from emergency and referral caseloads. Digital imaging within the technology dimension is displacing film-based radiography fastest among university-affiliated hospitals and specialty dentistry practices.
The US Food and Drug Administration regulates veterinary dental devices as animal health equipment, while the EU Medical Device Regulation imposes conformity requirements on manufacturers exporting imaging and laser systems into European veterinary markets. ISO standards for veterinary medical electrical equipment shape baseline safety and electromagnetic compatibility expectations for product design teams. Stakeholders must monitor how evolving state-level veterinary practice acts in California, Texas, and New York define scope-of-service boundaries for dental procedures performed by non-veterinary technicians.
Market Dynamics
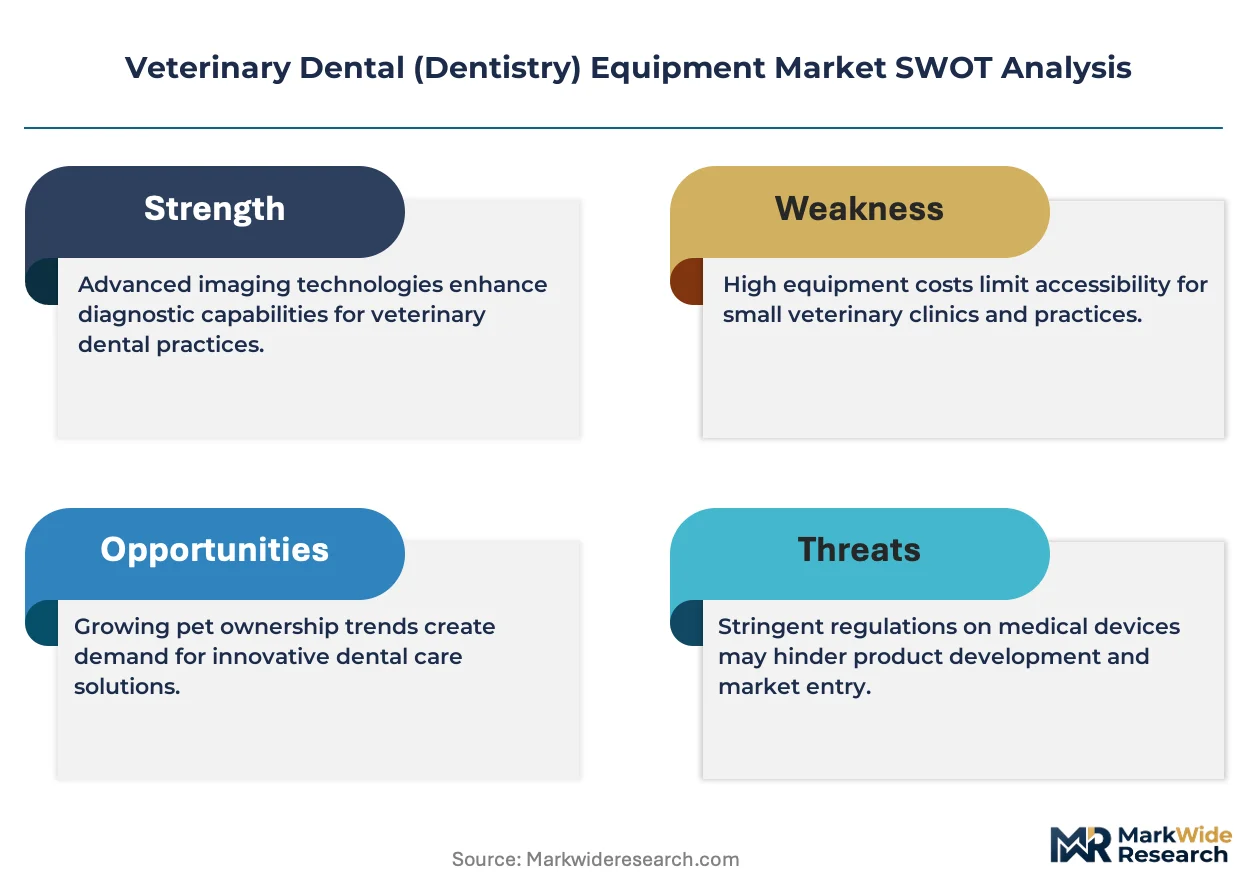
Digital radiography systems are compressing diagnostic timelines while expanding service capacity at specialty veterinary clinics, forcing capital equipment refresh cycles that favor integrated platform vendors over standalone instrument suppliers.
Growth Catalysts
- Pet insurance expansion:Broader coverage for periodontal procedures in the United States and Western Europe is converting preventive dental visits from out-of-pocket expenses to reimbursable care, lifting procedure volumes.
- ISO 60601-1 alignment:Harmonized electrical safety standards for veterinary medical equipment are streamlining cross-border certification, reducing time-to-market for imaging and laser system manufacturers.
- Ultrasonic scaling frequency optimization:Equipment operating between 25 kHz and 45 kHz is reducing thermal damage risk during periodontal debridement, improving clinical outcomes and driving replacement demand.
Market Restraints
- High-grade stainless steel supply concentration:Surgical instrument manufacturers depend on German and Japanese metallurgical suppliers, exposing production schedules to alloying element price volatility.
- Veterinary technician scope limitations:State-level veterinary practice acts in California, Texas, and New York restrict dental prophylaxis delegation, constraining clinic throughput and equipment utilization rates.
- Analog radiography residual base:Film-based systems persist in rural and mobile practices where digital infrastructure investment remains prohibitive, fragmenting aftermarket service requirements.
Strategic Opportunities
- Telemedicine-integrated imaging:Cloud-connected intraoral radiography systems enable remote specialist consultation, opening referral networks for general practices in underserved Japanese prefectures.
- Laser dentistry convergence:Erbium and diode laser platforms combining soft tissue surgery with periodontal therapy are creating procedure bundling opportunities previously requiring separate capital investments.
- EU MDR transition:Stricter conformity assessment requirements for imaging equipment are accelerating consolidation among notified bodies, favoring established manufacturers with regulatory infrastructure.
Industry Challenges
- Veterinary dental specialist scarcity:Board-certified practitioners remain concentrated in university hospitals and major metropolitan areas, limiting equipment deployment in community practice settings.
- Multi-species ergonomic adaptation:Delivery system manufacturers must engineer adjustable configurations spanning feline, canine, and equine anatomies without compromising operator workflow efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Dental (Dentistry) Equipment Market |
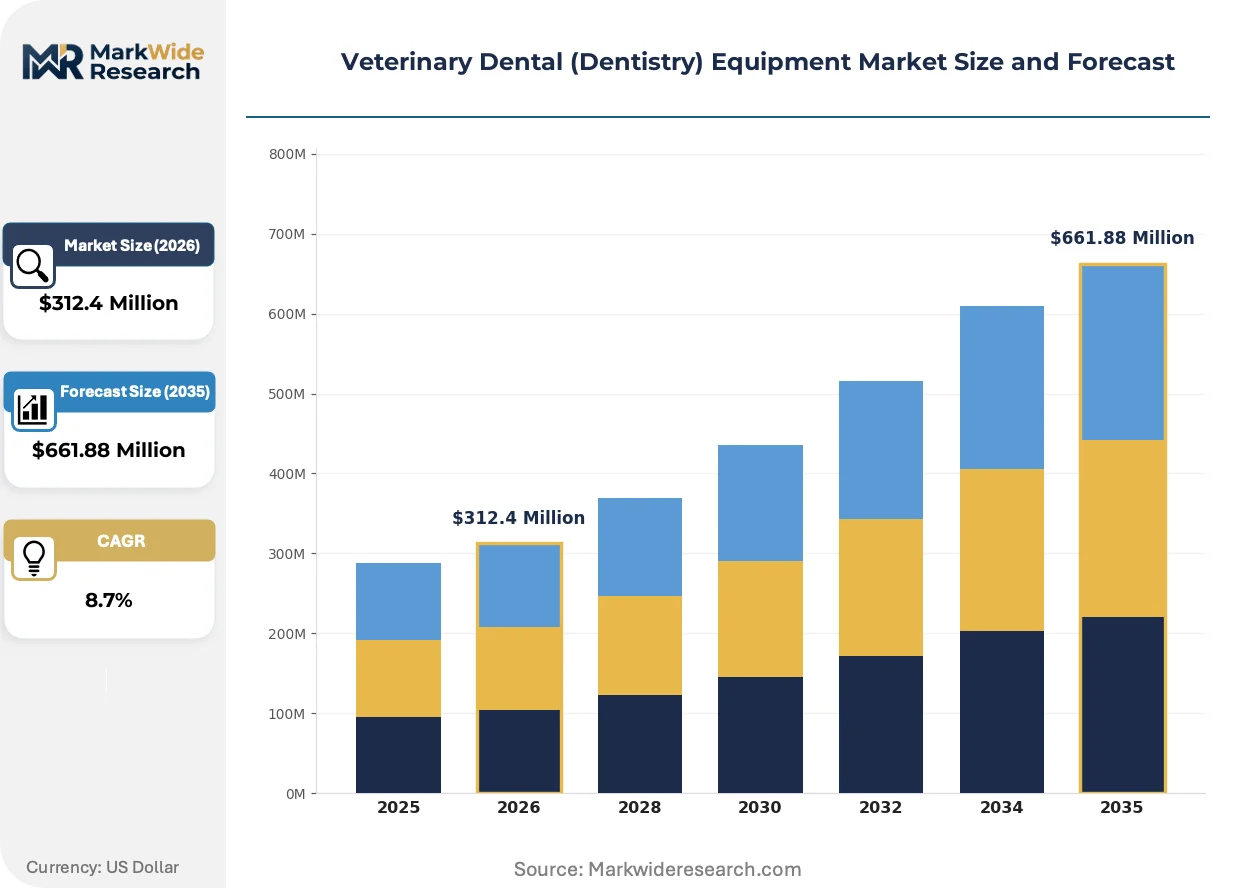
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Scalers, Dental X-rays, Extraction Instruments, Dental Chairs End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Mobile Veterinary Services Application: Periodontal Disease Treatment, Oral Surgery, Preventive Care, Diagnostic Imaging Technology: Digital Imaging, Laser Dentistry, Sedation Techniques, Handheld Instruments |
| Companies Covered | Planmeca Oy, Dentalaire Products International, Henry Schein, Inc., Acteon Group, Integra LifeSciences Corporation, Midmark Corporation, iM3 Inc., Dentsply Sirona Inc., Patterson Companies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Dental (Dentistry) Equipment Market Evolving Landscape
Artificial intelligence is penetrating diagnostic workflows while sustainability pressures reshape material selection and equipment lifecycle planning across veterinary dental supply chains.
Cone-beam computed tomography is automating three-dimensional oral pathology assessment, reducing reliance on two-dimensional radiographic interpretation. University-affiliated referral hospitals in Germany and Japan are deploying these systems for complex maxillofacial trauma and neoplasia cases. The technology is automating pre-surgical planning workflows that previously required multiple imaging modalities and specialist consultation delays.
The EU Medical Device Regulation is imposing stricter post-market surveillance and clinical evidence requirements on imaging and laser equipment exported into European veterinary markets. Manufacturers must maintain technical documentation and vigilance systems comparable to human medical device standards. Specialty practices in France and the Netherlands are prioritizing CE-marked equipment with established MDR compliance to avoid supply interruption.
Subscription-based equipment access is displacing outright purchase for high-value imaging systems among independent practice owners. Leasing arrangements bundling maintenance, software updates, and consumables are capturing preference in the United States where capital constraint meets demand for technology refresh. This model concentrates most visibly in California and Texas metropolitan corridors where practice valuation multiples incentivize cash flow preservation over asset ownership.
Veterinary Dental (Dentistry) Equipment Market Segmentation
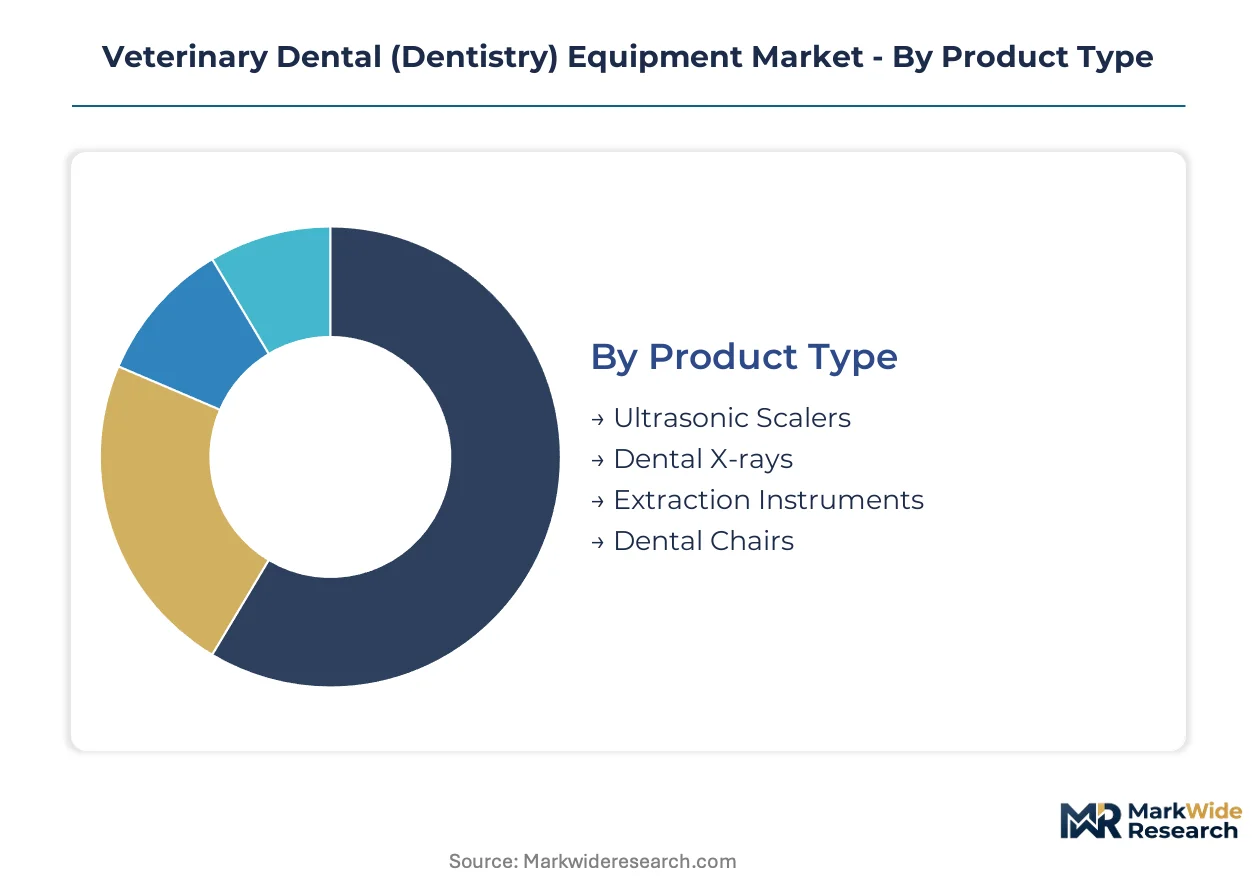
Veterinary dental equipment segmentation reveals distinct procurement patterns across practice types and clinical applications. Equipment specifications diverge sharply between high-volume general practices and referral hospitals managing complex oral pathology.
Product Type:
Ultrasonic scalers and dental X-rays anchor the volume tier through replacement cycles and new clinic formations, while extraction instruments command premium pricing in emergency and specialty settings.
- Ultrasonic Scalers:Operating between 25 kHz and 45 kHz, these devices reduce thermal damage during periodontal debridement. Demand concentrates in high-throughput veterinary clinics across the United States and Germany where preventive dental volumes are lifting equipment utilization rates.
- Dental X-rays:Digital radiography systems compress diagnostic timelines while expanding service capacity. University-affiliated hospitals in Japan and specialty practices in Western Europe are driving displacement of film-based systems through integrated platform procurement.
- Extraction Instruments:High-grade stainless steel forceps and elevators designed for multi-species adaptation capture disproportionate margin contribution from emergency caseloads.
- Dental Chairs:Ergonomic delivery systems with adjustable configurations span feline, canine, and equine anatomies without compromising operator workflow.
Mature deployment sits with ultrasonic scalers. Newer deployment is concentrated in digital radiography systems.
End User:
Procurement authority and capital constraint levels create divergent equipment specifications across practice ownership structures.
- Veterinary Clinics:Independent and group-owned general practices prioritize ultrasonic scalers and handheld instruments for routine prophylaxis, with leasing arrangements capturing preference where capital constraint meets technology refresh demands.
- Animal Hospitals:Multi-specialty referral centers in metropolitan corridors deploy cone-beam computed tomography and laser dentistry platforms for complex maxillofacial trauma and neoplasia cases.
- Research Laboratories:University-affiliated facilities drive validation of emerging imaging modalities and sedation protocols before commercial scaling.
- Mobile Veterinary Services:Portable equipment configurations address rural access gaps where digital infrastructure investment remains prohibitive.
Equipment refresh cycles run longest in mobile services. Technology adoption velocity peaks in university-affiliated animal hospitals.
Application:
Reimbursement expansion for periodontal procedures is shifting procedure mix toward preventive and diagnostic categories.
- Periodontal Disease Treatment:Scaling and root planing procedures constitute the volume core as pet insurance coverage broadens for reimbursable care in the United States and Western Europe.
- Oral Surgery:Extraction and maxillofacial reconstruction demand precision instrumentation and advanced imaging, with board-certified specialists concentrated in major metropolitan areas.
- Preventive Care:Prophylaxis volumes are climbing fastest where insurance conversion reduces out-of-pocket friction for routine dental visits.
- Diagnostic Imaging:Intraoral and panoramic radiography enable pathology detection before clinical presentation, supporting early intervention protocols.
Preventive care is expanding most quickly. Oral surgery maintains the steepest equipment specification requirements.
Technology:
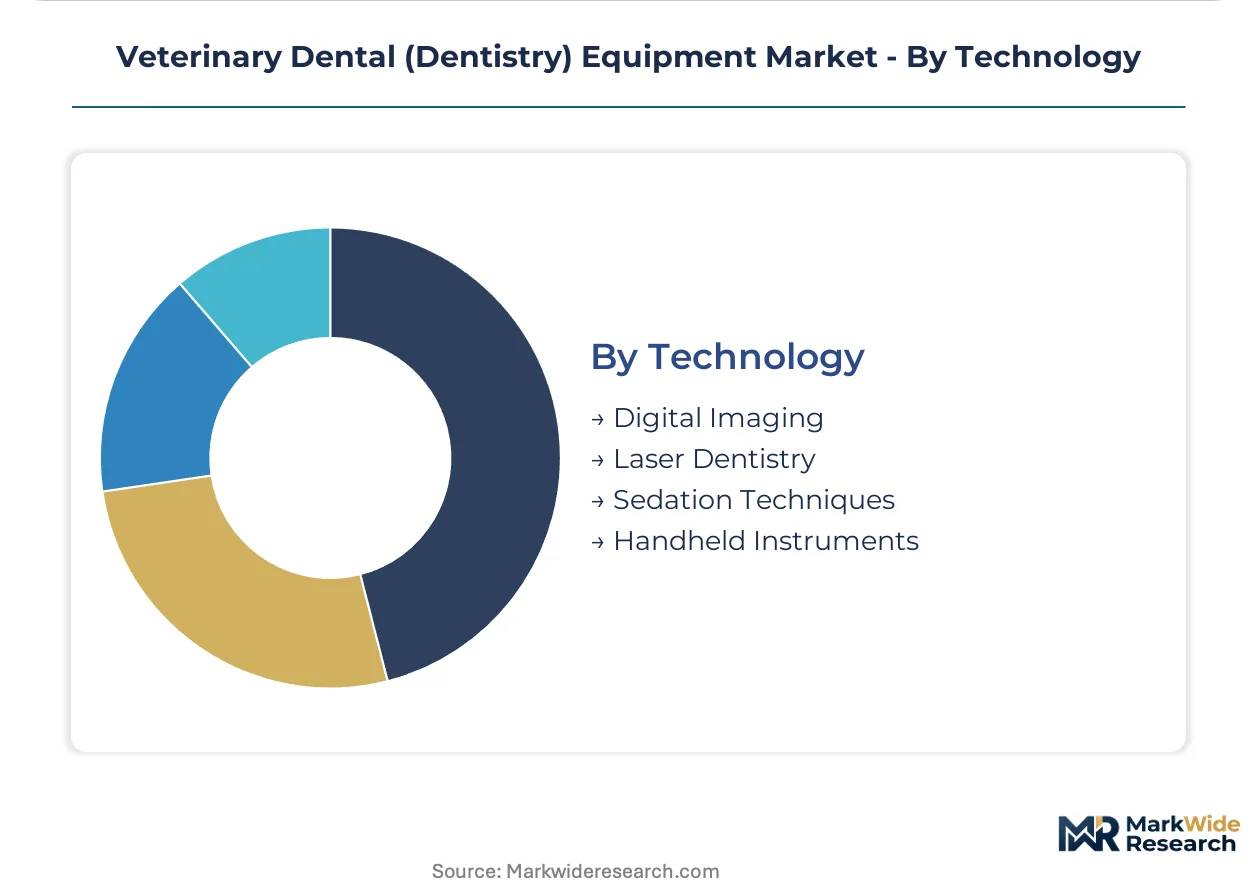
Digital infrastructure maturity determines technology penetration depth across practice settings.
- Digital Imaging:Cloud-connected intraoral radiography systems enable remote specialist consultation, opening referral networks for general practices in underserved prefectures.
- Laser Dentistry:Erbium and diode platforms combining soft tissue surgery with periodontal therapy create procedure bundling opportunities previously requiring separate capital investments.
- Sedation Techniques:Monitoring equipment and delivery systems support anesthesia protocols tailored to species-specific cardiovascular risk profiles.
- Handheld Instruments:Curettes, scalers, and probes remain essential for practices without digital infrastructure or as backup systems.
Handheld instruments represent baseline deployment. Digital imaging is gaining share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for veterinary dental equipment concentrates in the United States, Germany, and Japan, where companion animal ownership rates and discretionary veterinary spending run highest. Specialty veterinary clinics in these markets are scaling dental service lines as pet insurance coverage broadens. Digital imaging and laser dentistry technologies are replacing legacy handheld tools in premium practices across all three countries.
United States
Pet insurance expansion for periodontal procedures is converting preventive dental visits from out-of-pocket expenses to reimbursable care, lifting procedure volumes in California and Texas metropolitan corridors. The FDA regulates veterinary dental devices as animal health equipment, requiring 510(k) clearance for powered instruments and imaging systems. Veterinary groups in Greater Boston and the Pacific Northwest are consolidating purchasing across dental, imaging, and surgical suites through multi-vendor platform sourcing.
Germany
University-affiliated referral hospitals in Bavaria and North Rhine-Westphalia are deploying cone-beam computed tomography systems for complex maxillofacial trauma cases. The EU Medical Device Regulation imposes conformity assessment requirements on manufacturers exporting imaging and laser systems into German veterinary markets, accelerating consolidation among notified bodies. ISO 60601-1 alignment for electrical safety standards is streamlining cross-border certification for equipment operating between 25 kHz and 45 kHz.
Japan
Cloud-connected intraoral radiography systems are enabling remote specialist consultation, opening referral networks for general practices in underserved prefectures. METI standards for medical electrical equipment shape baseline safety and electromagnetic compatibility expectations for product design teams. Specialty practices in the Kanto region around Tokyo are prioritizing CE-marked equipment with established MDR compliance to avoid supply interruption.
United Kingdom
Subscription-based equipment access is displacing outright purchase for high-value imaging systems among independent practice owners in London and the Southeast. The Veterinary Medicines Directorate works alongside MHRA to regulate veterinary medical devices entering the UK market post-Brexit. Leasing arrangements bundling maintenance, software updates, and consumables are capturing preference where capital constraint meets demand for technology refresh.
France
Erbium and diode laser platforms combining soft tissue surgery with periodontal therapy are creating procedure bundling opportunities in Île-de-France and Auvergne-Rhône-Alpes. ANSM vigilance systems require post-market surveillance comparable to human medical device standards for imaging equipment. Specialty practices in Lyon and Marseille are scaling dental service lines as pet insurance coverage broadens for reimbursable periodontal care.
Veterinary Dental (Dentistry) Equipment Market Competitive Landscape
Portfolio diversification dominates the current landscape as established veterinary suppliers expand beyond single-product lines into integrated platform offerings. The vendor base spans multinational healthcare distributors, specialized veterinary equipment manufacturers, and human dental technology adapters serving the animal health segment. Three strategic archetypes define competitive positioning: distribution-anchored bundlers leveraging service density, imaging-technology specialists commanding premium pricing, and ergonomic-system engineers optimizing multi-species workflows. M&A activity and strategic partnerships represent the dominant competitive moves, with consolidation accelerating among notified bodies under stricter EU regulatory requirements.
Among Finland-based imaging specialists, Planmeca Oy occupies a position exemplifying the high-value diagnostic tier. Henry Schein, Inc. and Patterson Companies, Inc. represent the distribution-anchored archetype, with both firms sitting within the consolidated healthcare supply segment where bundling dental units with consumables and service contracts reinforces customer retention. Midmark Corporation anchors the ergonomic-system engineering vector, with the company exemplifying design philosophy optimized for multi-species practice workflows.
| Leading Market Players |
|---|
| Planmeca Oy |
| Dentalaire Products International |
| Henry Schein, Inc. |
| Acteon Group |
| Integra LifeSciences Corporation |
| Midmark Corporation |
| iM3 Inc. |
| Dentsply Sirona Inc. |
| Patterson Companies, Inc. |
| Others |
Value Network & Pricing Analysis
Board-certified veterinary dental specialist concentration in university hospitals and major US metropolitan areas creates labor-cost differentials that widen pricing-tier spreads between community practices and referral centers. Equipment procurement patterns diverge sharply as premium-tier buyers absorb bundled service premiums while price-sensitive segments strip warranties to preserve capital.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier digital imaging systems from unbundled economy configurations where service contracts carry separate line-item pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 60601-1 certification grade and after-sales support density. Cost compression in the economy tier intensifies as mobile veterinary services strip non-essential features to hit acquisition targets. Mobile veterinary services exhibit highest price sensitivity; university-affiliated referral hospitals demonstrate lowest.
Supply Chain Analysis
Precision-machining workforce availability in Germany, Japan, and the United States constrains production capacity for high-grade stainless steel extraction instruments. Supply chains draw from German and Japanese metallurgical suppliers for surgical-grade alloys, from Taiwanese electronics manufacturers for imaging sensor components, and from Chinese assembly facilities for handheld instrument production. Single-source vulnerability in specialty alloying elements exposes production schedules to commodity price volatility. Distribution runs through veterinary group purchasing organizations and specialized dental equipment distributors serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over imaging software development and consumables supply determines margin capture. Players are pursuing downstream service revenue to offset capital equipment commoditization.
For Market Incumbents: To counter subscription-based equipment access models from specialized lessors, deepen backward integration into imaging software development and establish captive consumables manufacturing. Prioritize MDR certification infrastructure investment to accelerate consolidation among notified bodies and exclude undercapitalized competitors. Lock in veterinary group purchasing organization contracts before regional consolidation completes.
For New Entrants and Emerging Players: Veterinary technician training institutions represent the most penetrable channel partner type for portable equipment configurations targeting rural access gaps. Target mobile veterinary services in underserved Japanese prefectures and Australian regional markets where digital infrastructure investment remains prohibitive. Pursue telemedicine-integrated imaging partnerships with general practices seeking referral network access.
For Investors and Strategic Acquirers: Re-rating potential sits with ergonomic-system engineering specialists given multi-species workflow optimization demands from consolidating veterinary groups. Long-term viability over the medium-term horizon favors targets with established regulatory infrastructure across FDA and EU MDR frameworks. Monitor state-level veterinary practice act liberalization in California, Texas, and New York as inflection indicator for technician-delegation throughput expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates consolidation among notified bodies favoring established manufacturers. |
| Hospital System Partnership | University-affiliated referral hospitals in Germany and Japan validate emerging imaging modalities. |
| Software Companion Development | Cloud-connected intraoral radiography enables remote specialist consultation for underserved prefectures. |
| Reimbursement Strategy | Pet insurance expansion for periodontal procedures lifts procedure volumes in California and Texas. |
| Backward Integration | In-house production of high-grade stainless steel instruments reduces exposure to alloying element volatility. |
Research Methodology
Independent corroboration across veterinary dental equipment manufacturers, veterinary group purchasing organizations, and university-affiliated referral hospitals underwrites the qualitative findings. Primary interviews with veterinary dental specialists, biomedical engineers at equipment manufacturers, GPO contracts managers, and regulatory affairs leads at imaging system suppliers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records. Bottom-up equipment shipment analysis and top-down veterinary spending estimates triangulate market sizing.
Comparable-period anchoring to historical replacement cycles and capital expenditure patterns across the projection horizon shaped forecast calibration. Segmentation dimensions modeled include product type, end-user ownership structure, clinical application, and technology infrastructure maturity. CAGRs were derived from equipment refresh cycle analysis and procedure volume elasticity to reimbursement expansion. Forecast inputs incorporated pet insurance penetration trajectories and state-level veterinary practice act evolution.
Caveats apply where regulatory enforcement intensity, alloying element supply disruptions, or telemedicine reimbursement policy shifts could materially shift the outlook. Forecasts reflect documented assumptions about technician delegation liberalization and digital infrastructure investment rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market