
 Japan Dental Equipment Market | 2026-2036
Japan Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dental Equipment Market Foresight
Modular chairside unit configurations is pivoting how Japanese dental clinics evaluate capital purchases, shifting preference from integrated turnkey systems toward componentized setups that allow phased technology upgrades. Takara Belmont anchors the premium ergonomic segment through its longstanding domestic manufacturing footprint. J. Morita Mfg. Corp. specializes in precision handpiece engineering that sustains its position in high-speed turbine supply. GC Corporation differentiates through its integrated restorative material and equipment ecosystems that extend clinician loyalty beyond hardware cycles.
Japan dental equipment encompasses electromechanical devices, diagnostic imaging platforms, and laser-based therapeutic instruments engineered to ISO 13485 quality management standards with sterilization protocols typically requiring autoclave compatibility at 121 degrees Celsius. These systems serve the core commercial purpose of enabling preventive, restorative, and surgical oral healthcare delivery in outpatient settings. Imaging systems dominate current revenue flows due to mandatory radiation safety inspections and replacement cycles tied to PMDA device registrations. CAD/CAM technology represents the fastest-expanding technology segment as chairside milling reduces laboratory outsourcing dependency for crown and bridge fabrication. Dental clinics constitute the primary end-user channel, absorbing the majority of unit volume through individual practitioner purchases and small-group practice networks.
PMDA governs pre-market approval pathways for dental devices under Japan's Pharmaceutical and Medical Device Act, while METI coordinates industrial policy incentives that subsidize domestic digital manufacturing adoption. JIS standards establish electrical safety and electromagnetic compatibility benchmarks that foreign suppliers must satisfy for market access. Stakeholders must monitor reimbursement rate adjustments from the Central Social Insurance Medical Council and align product development timelines with the ministry's periodic fee schedule revisions.
Market Dynamics
Japan's dental equipment sector faces a structural pivot where modular chairside configurations are displacing integrated turnkey systems, forcing manufacturers to reconfigure product architectures around phased upgrade pathways rather than single-cycle capital deployments.
Growth Catalysts
- METI Digital Manufacturing Subsidies:Industrial policy incentives reduce capital barriers for domestic clinics adopting CAD/CAM milling systems, accelerating chairside production adoption.
- Ministry of Health, Labour and Welfare Reimbursement Revisions:Expanded fee schedules for advanced restorative procedures incentivize clinics to invest in cone beam CT and digital impression systems.
- Tokyo-Osaka-Nagoya Metropolitan Concentration:Patient purchasing power and clinic density in these corridors sustain replacement cycles for premium diagnostic imaging platforms.
Market Restraints
- PMDA Registration Timelines:Pre-market approval pathways for Class III and IV dental devices extend 12-18 months, compressing product launch windows against technology obsolescence.
- Domestic Handpiece Component Supply:Precision turbine manufacturing concentrates among a limited supplier base in Osaka and Aichi prefectures, creating vulnerability to production disruptions.
- Autoclave Sterilization Compatibility:ISO 13485 quality mandates require 121°C steam sterilization resilience, eliminating materials and designs common in European markets with alternative protocols.
Strategic Opportunities
- Kyushu and Tohoku Clinic Networks:Underpenetrated regional markets outside Kanto-Kansai corridors present whitespace for mid-tier equipment configurations.
- Laser-Therapeutic Convergence:Integration of erbium and diode laser platforms with existing chairside units opens procedural expansion into soft-tissue applications.
- Small-Group Practice Procurement Consortia:Emerging purchasing cooperatives among 3-5 clinic networks create volume aggregation channels bypassing traditional distributor markups.
Industry Challenges
- CAD/CAM Technician Training Pipeline:Chairside milling adoption outpaces certified operator supply, forcing clinics to absorb training costs or retain laboratory outsourcing.
- Legacy Analog System Integration:Digital impression systems must interface with existing pneumatic handpiece infrastructure, complicating retrofit specifications.
- JIS Electromagnetic Compatibility Certification:Foreign suppliers face extended testing cycles for electrical safety benchmarks, delaying market entry against domestic competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dental Equipment Market |
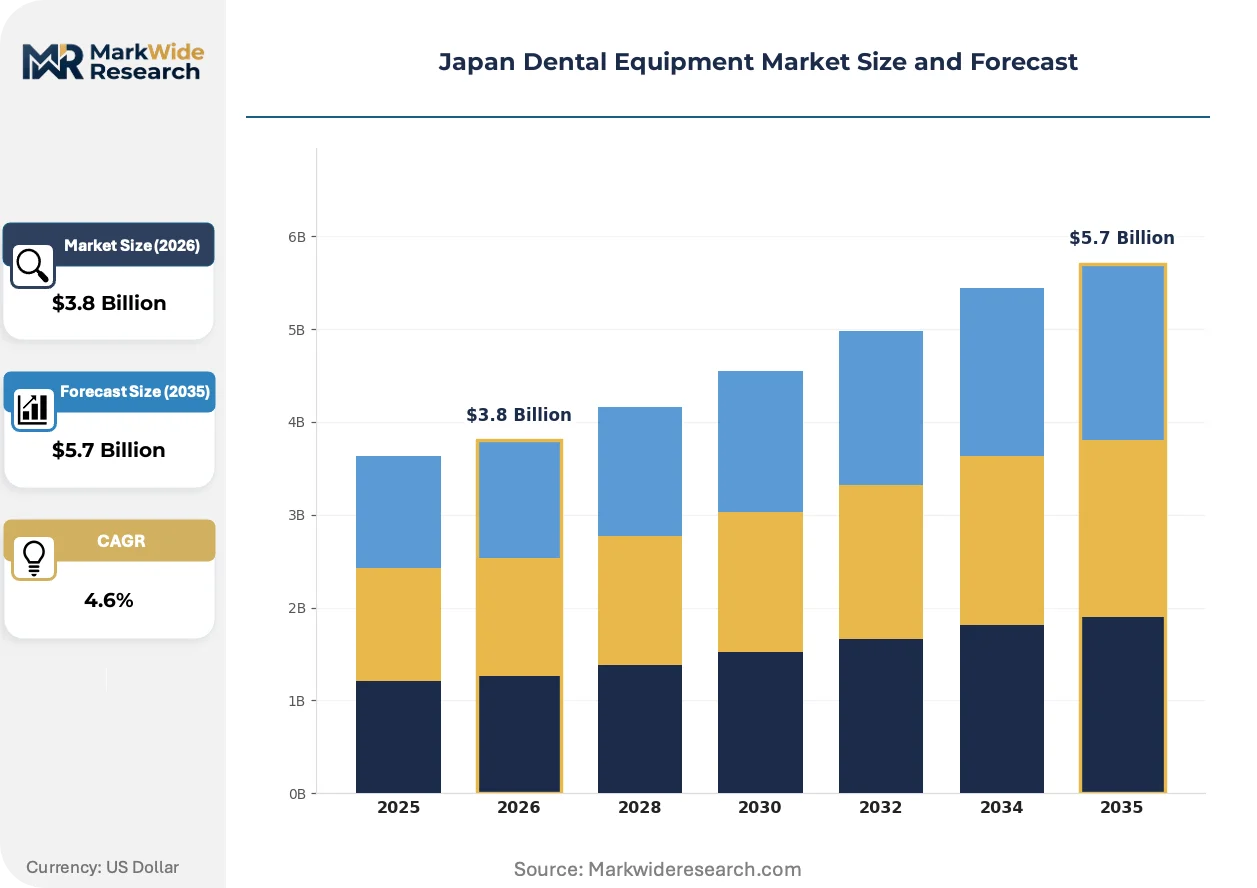
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Lasers, Imaging Systems, Handpieces, Sterilization Equipment Technology: CAD/CAM, 3D Printing, Digital X-ray, Cone Beam CT End User: Dental Clinics, Hospitals, Research Institutions, Academic Centers Application: Orthodontics, Implantology, Periodontics, Cosmetic Dentistry |
| Companies Covered | Dentsply Sirona, Takara Belmont, J. Morita Mfg. Corp., Mani Inc., GC Corporation, Dentech Corporation, Nakanishi Inc., KaVo Dental, The Yoshida Dental Mfg. Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dental Equipment Market Shifts & Advancements
Japan's dental equipment landscape is undergoing active reconfiguration around three vectors: hardware modularity, regulatory-driven digital adoption, and procurement model fragmentation that separates capital acquisition from service delivery.
Chairside CAD/CAM milling technology is integrating into compact unit configurations that occupy under two square meters of operatory floor space. Private dental clinics in Tokyo and Osaka are deploying these systems at replacement-cycle intervals of 5-7 years. This footprint compression is enabling single-practitioner operations to bring crown and bridge fabrication in-house, reducing laboratory outsourcing dependency.
METI's digital health infrastructure mandates are accelerating PMDA approval pathway reforms for software-as-medical-device platforms. The industrial consequence is a surge in cloud-connected diagnostic imaging systems requiring cybersecurity validation alongside traditional safety testing. Imaging equipment manufacturers are responding by embedding domestic data residency features to satisfy Japan's Pharmaceutical and Medical Device Act amendments.
Clinic procurement patterns are fragmenting across three distinct models: direct manufacturer relationships for premium ergonomic chairs, distributor-mediated purchases for consumables, and equipment-as-service arrangements for high-value imaging systems. Small-group practice networks in Nagoya are pioneering this unbundled approach, separating hardware ownership from maintenance and upgrade obligations. This behavioral shift is most visible among practices with 3-8 dentists seeking to preserve capital flexibility.
Japan Dental Equipment Market Segmentation
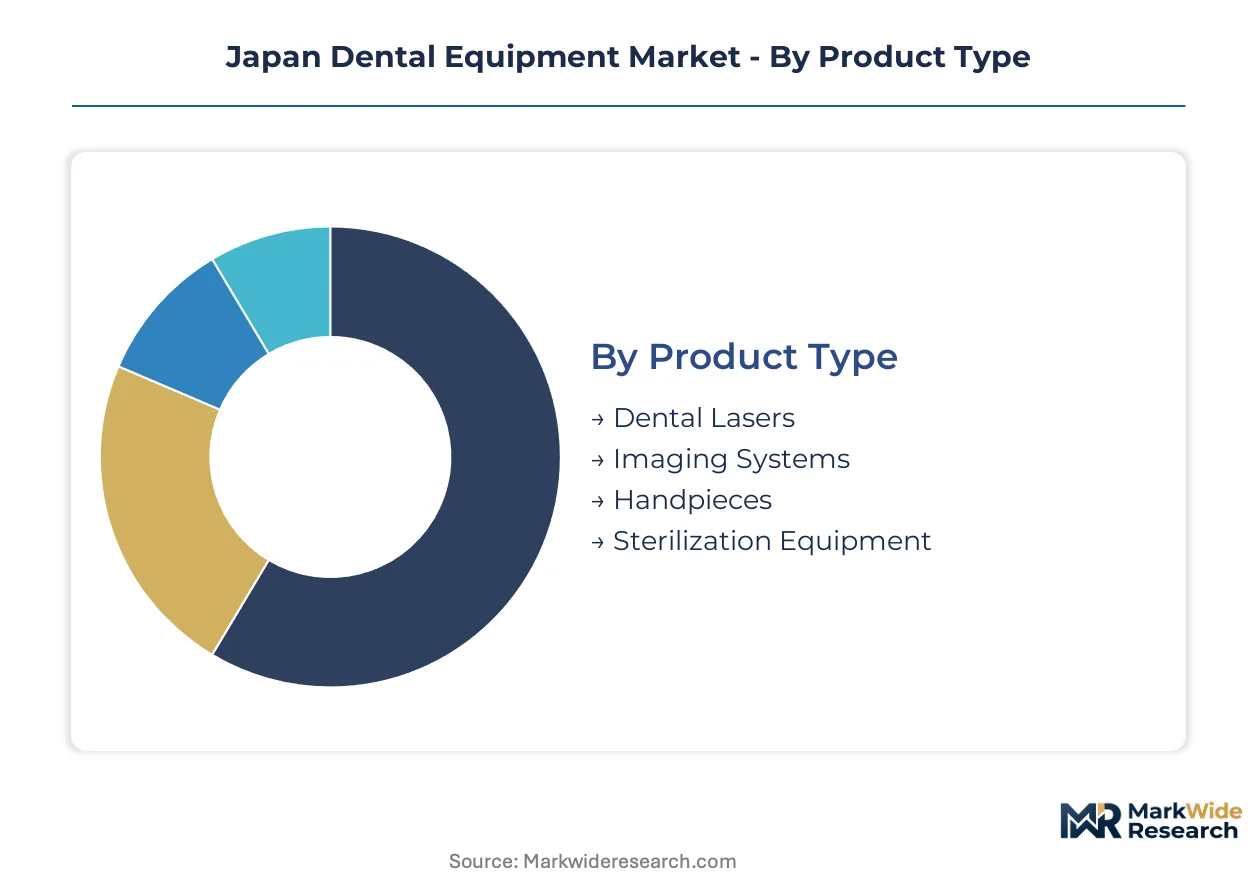
Japan's dental equipment market fragments across four functional axes that determine procurement priorities and technology adoption cycles. Each segmentation layer reveals distinct concentration patterns between metropolitan clinic networks and institutional healthcare systems, with regulatory pathways from METI and PMDA shaping viable product configurations.
Product Type:
Technical specification and sterilization protocol compatibility define procurement decisions across hardware categories.
- Imaging Systems:Cone beam CT and digital radiography platforms engineered to PMDA radiation safety standards with mandatory inspection cycles. Tokyo and Osaka dental clinics drive replacement demand where patient volume justifies diagnostic throughput investment and METI digital health subsidies reduce capital barriers.
- Handpieces:Precision turbine and electric motor assemblies manufactured to JIS electromagnetic compatibility benchmarks with 121°C autoclave resilience requirements. Osaka and Aichi prefectures concentrate domestic component supply, creating geographic vulnerability in precision bearing procurement.
- Dental Lasers:Erbium and diode wavelength platforms for soft-tissue and hard-tissue applications requiring PMDA Class III device registration.
- Sterilization Equipment:Steam autoclave and chemical vapor systems mandatory under ISO 13485 quality management protocols for clinic accreditation.
Mature deployment sits with Imaging Systems. Newer deployment is concentrated in Dental Lasers.
Technology:
Digital workflow integration intensity separates capital investment tiers across Japanese dental practices.
- CAD/CAM:Chairside milling and digital impression systems compacted under two square meters of operatory footprint. Private clinics in Nagoya and Kansai corridors adopt these at 5-7 year replacement intervals, reducing laboratory outsourcing dependency for crown fabrication.
- Cone Beam CT:Volumetric imaging platforms with expanded Ministry of Health, Labour and Welfare reimbursement coverage for implantology planning. Metropolitan clinics with implant-focused practices concentrate demand where procedure volume amortizes equipment cost.
- Digital X-ray:Sensor-based intraoral and panoramic systems replacing analog film infrastructure.
- 3D Printing:Photopolymer and resin-based additive manufacturing for surgical guides and provisional restorations.
Established workflow integration characterizes Digital X-ray. Steepest expansion trajectory belongs to CAD/CAM.
End User:
Procurement scale and decision-making authority vary sharply across institutional settings.
- Dental Clinics:Individual practitioner and small-group practices comprising the dominant volume channel. Kanto and Kansai metropolitan networks favor modular chairside configurations enabling phased technology upgrades without single-cycle capital commitment.
- Hospitals:Integrated medical-dental departments with centralized purchasing and maintenance infrastructure. Academic medical centers in Tokyo and Osaka concentrate demand for high-throughput imaging platforms.
- Research Institutions:Specialized facilities driving experimental technology validation prior to PMDA commercial approval pathways.
- Academic Centers:Dental schools with training-mission procurement prioritizing equipment standardization across student operatories.
Volume concentration rests with Dental Clinics. Technology validation function concentrates in Research Institutions.
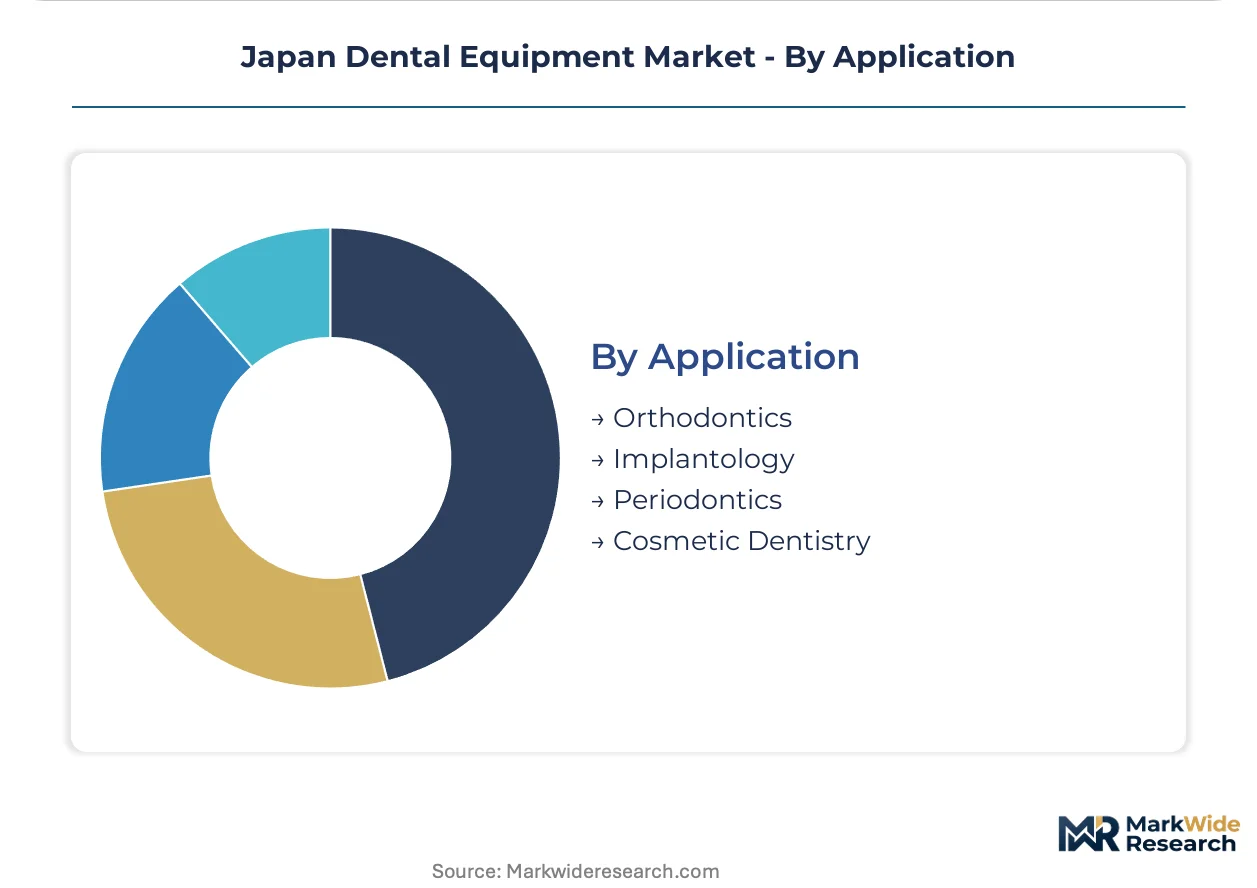
Application:
Procedure reimbursement rates and clinical outcome expectations shape equipment specification requirements.
- Implantology:Surgical and prosthetic workflows requiring cone beam CT planning and guided surgery systems. Expanded fee schedules from the Central Social Insurance Medical Council accelerate diagnostic imaging adoption in high-volume metropolitan practices.
- Cosmetic Dentistry:Aesthetic restorative procedures driving CAD/CAM chairside milling for ceramic crown fabrication. Patient out-of-pocket payment concentration in Tokyo and Osaka sustains premium equipment configurations.
- Orthodontics:Clear aligner and fixed appliance treatments with digital workflow integration for treatment planning.
- Periodontics:Soft-tissue management and regenerative procedures with laser therapeutic platform adoption.
Reimbursement leverage favors Implantology. Direct patient payment concentration defines Cosmetic Dentistry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's dental equipment production concentrates in Osaka and Aichi prefectures, while consumption gravity pulls toward metropolitan clinic clusters in Tokyo, Osaka, and Nagoya where patient density and reimbursement rates justify premium equipment deployment.
Kanto/Tokyo
Tokyo's dental clinics drive replacement cycles for cone beam CT and CAD/CAM systems at 5-7 year intervals. METI digital manufacturing subsidies reduce capital barriers for chairside milling adoption in the capital's dense practitioner networks. The Tokyo metropolitan zone concentrates patient purchasing power for cosmetic dentistry procedures that sustain premium equipment configurations.
Kansai/Osaka
Osaka anchors Japan's precision handpiece manufacturing cluster with component suppliers concentrated in adjacent Aichi prefecture. PMDA device registration timelines of 12-18 months compress product launch windows for manufacturers based in this industrial corridor. The Osaka-Kobe corridor sustains demand for integrated restorative material and equipment ecosystems.
Chubu/Nagoya
Nagoya's small-group practice networks pioneer unbundled procurement models separating hardware ownership from maintenance obligations. Ministry of Health, Labour and Welfare reimbursement revisions for advanced restorative procedures accelerate diagnostic imaging investment in this manufacturing-heavy region. Clinic consortia of 3-8 practitioners aggregate purchasing volume to bypass traditional distributor markups.
Kyushu
Kyushu's clinic networks remain underpenetrated relative to Kanto-Kansai corridors, presenting whitespace for mid-tier equipment configurations. JIS electromagnetic compatibility certification requirements extend testing cycles for foreign suppliers seeking entry into this regional market. Fukuoka's urban center concentrates the island's limited high-volume implantology practices.
Tohoku
Tohoku's dental sector lags in CAD/CAM technician training pipeline development, forcing clinics to absorb operator certification costs or retain laboratory outsourcing. The region's dispersed rural practitioner base limits capital deployment for premium imaging platforms outside Sendai's metropolitan core. Autoclave sterilization compatibility mandates at 121°C constrain equipment specification options available to regional distributors.
Japan Dental Equipment Market Competitive Landscape
The competitive structure tilts toward domestic ergonomic specialists with longstanding manufacturing footprints. Three tiers define the landscape: premium ergonomic chair manufacturers with integrated design-to-delivery capabilities, precision handpiece engineers serving high-speed turbine demand, and restorative material-equipment ecosystem builders extending clinician loyalty beyond hardware replacement cycles. Dominant competitive moves center on modular product architectures enabling phased clinic upgrades, and procurement consortia partnerships that aggregate small-group practice purchasing volume.
Within the domestic specialist tier, Takara Belmont and J. Morita Mfg. Corp. occupy positions anchored by regional manufacturing concentration in Osaka and Aichi prefectures. GC Corporation exemplifies the integrated ecosystem archetype, bundling consumable supply with equipment platforms to sustain recurring revenue relationships. These three Japanese entities represent competitive positioning built on JIS certification familiarity, METI subsidy program alignment, and PMDA regulatory pathway navigation rather than scale-driven cost structures.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Takara Belmont |
| J. Morita Mfg. Corp. |
| Mani Inc. |
| GC Corporation |
| Dentech Corporation |
| Nakanishi Inc. |
| KaVo Dental |
| The Yoshida Dental Mfg. Co., Ltd. |
| Others |
Supply & Pricing Matrix
Small-group dental clinic consortia in Nagoya and Osaka concentrate purchasing volume and negotiate contract-based long-term equipment procurement, anchoring Japan's tiered pricing structure across premium, standard, and economy equipment levels.
Pricing Analysis
Margin tightening in mid-tier handpiece configurations reflects precision bearing supply concentration in Aichi prefecture. Three-tier pricing structure across premium, standard, and economy levels separates Takara Belmont ergonomic chairs from componentized setups and refurbished legacy units. Price differentiation hinges on JIS electromagnetic compatibility certification grade and after-sales service bundling. Cost-down pressure on standard-tier imaging accelerates because METI subsidy eligibility narrows for non-domestic data residency platforms.
Supply Chain Analysis
Refurbished cone beam CT units flow through authorized dealer networks for secondary deployment in Tohoku and Kyushu clinic markets. Component manufacturing concentrates in Japan, Germany, and the United States. Raw material dependencies include precision ceramic bearings, rare-earth magnet alloys for handpiece motors, and photopolymer resins for 3D printing applications. Single-source vulnerability in Osaka-based turbine bearing supply creates disruption risk. Distribution runs through manufacturer-direct channels for premium chairs and distributor-mediated flows for consumables and mid-tier equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's dental equipment market operates as a supply-constrained environment where certified CAD/CAM technician scarcity props pricing power for training-integrated equipment vendors.
For Market Incumbents: Acquire specialized handpiece bearing manufacturers in Aichi prefecture to secure precision component supply against emerging Chinese turbine entrants. Backward integration into ceramic bearing production reduces single-source exposure from Osaka suppliers. Prioritize PMDA regulatory affairs capacity to compress 12-18 month approval timelines for Class III laser platforms. For New Entrants and Emerging Players: METI's digital manufacturing subsidies in Japan open a window for mid-tier CAD/CAM configurations targeting Kyushu and Tohoku clinic networks. Underpenetrated regional markets outside Kanto-Kansai corridors present viable whitespace for compact chairside milling systems. Partner with existing dental laboratory networks for technician training co-investment to bypass certification pipeline bottlenecks. For Investors and Strategic Acquirers: The window for entry favors integrated restorative material-equipment ecosystem builders with recurring revenue models. Long-term viability centers on consumable-anchored relationships that extend beyond hardware replacement cycles. Monitor Central Social Insurance Medical Council reimbursement rate revisions for advanced restorative procedures as inflection indicators for diagnostic imaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regulatory Pathway Optimization | Compressed approval timelines for Class III dental lasers accelerate product launch windows against domestic competitors. |
| Technician Training Partnership | Co-investment with dental laboratory networks addresses certified CAD/CAM operator scarcity constraining chairside adoption. |
| Regional Distribution Expansion | Direct manufacturer relationships in Kyushu bypass traditional distributor markups and capture underpenetrated clinic demand. |
| Modular Product Architecture Development | Componentized chairside configurations align with small-group practice procurement preferences for phased capital deployment. |
| Domestic Data Residency Compliance | Cloud-connected imaging platforms with embedded local data storage satisfy PMDA amendments and METI digital health mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across dental equipment manufacturers, clinic procurement managers, biomedical engineers at academic medical centers, and GPO contracts specialists. METI subsidy program disclosures, PMDA device registration databases, Japan Dental Association membership records, and Ministry of Health, Labour and Welfare reimbursement schedules provided validation layers. Bottom-up equipment unit estimates and top-down market value reconstructions were triangulated for consistency.
Data-stream reconciliation across shipment records, import manifests, and clinic capital expenditure surveys informed the analytical framework. Segmentation dimensions modeled include product type, technology integration intensity, end-user institutional scale, and application procedure category. CAGRs were derived from equipment replacement cycle analysis and reimbursement-driven demand elasticity. Forecast inputs incorporated PMDA approval pipeline velocity and METI industrial policy incentive trajectories across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for chairside CAD/CAM technician training pipeline development would alter the outlook. Forecasts reflect assumptions about reimbursement rate stability and precision component supply continuity. Practitioners should monitor Central Social Insurance Medical Council fee schedule revisions and Osaka bearing manufacturer capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
France Dental Equipment Market