
 Dental Imaging Equipment Market | 2026-2036
Dental Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Imaging Equipment Market Analysis
Buyer concentration in the dental imaging equipment market is pivoting as dental service organizations consolidate independent practices into multi-clinic networks. Envista Holdings Corporation leverages its broad equipment and consumables portfolio to serve these expanding networks with integrated workflow solutions. DENTSPLY SIRONA sustains technology leadership through sustained investment in digital dentistry platforms that connect imaging with chairside manufacturing. Planmeca Oy anchors its competitive position with a vertically integrated manufacturing footprint that spans hardware, software, and imaging analytics.
Dental imaging equipment encompasses intraoral and extraoral systems that capture radiographic, tomographic, or optical data for diagnostic and treatment planning purposes, with cone beam computed tomography systems typically operating at 5-150 µm voxel resolution and sub-millisecond exposure controls to minimize patient radiation dose while maximizing anatomical fidelity. These systems serve commercial purposes by enabling precise implant placement, orthodontic assessment, and periodontal evaluation across outpatient dental settings. Intraoral scanners now lead product type demand as chairside digital impression systems displace traditional polyvinyl siloxane workflows, while cone beam computed tomography commands premium positioning in implantology applications where three-dimensional bone assessment determines treatment feasibility. Digital radiography dominates technology adoption due to lower per-exposure costs and immediate image availability, though optical imaging is gaining traction in orthodontic monitoring where surface topography changes must be tracked across extended treatment intervals.
The FDA regulates dental radiological devices under 21 CFR 1020.32 performance standards for diagnostic x-ray systems, while ISO 13485 quality management requirements govern manufacturing processes for equipment sold across multiple jurisdictions. The Medical Device Regulation in Europe imposes stricter clinical evidence requirements through notified body conformity assessments, lengthening market access timelines for novel imaging modalities. Stakeholders must monitor how evolving AI-enabled diagnostic features trigger additional regulatory scrutiny under software-as-a-medical-device frameworks in major markets.
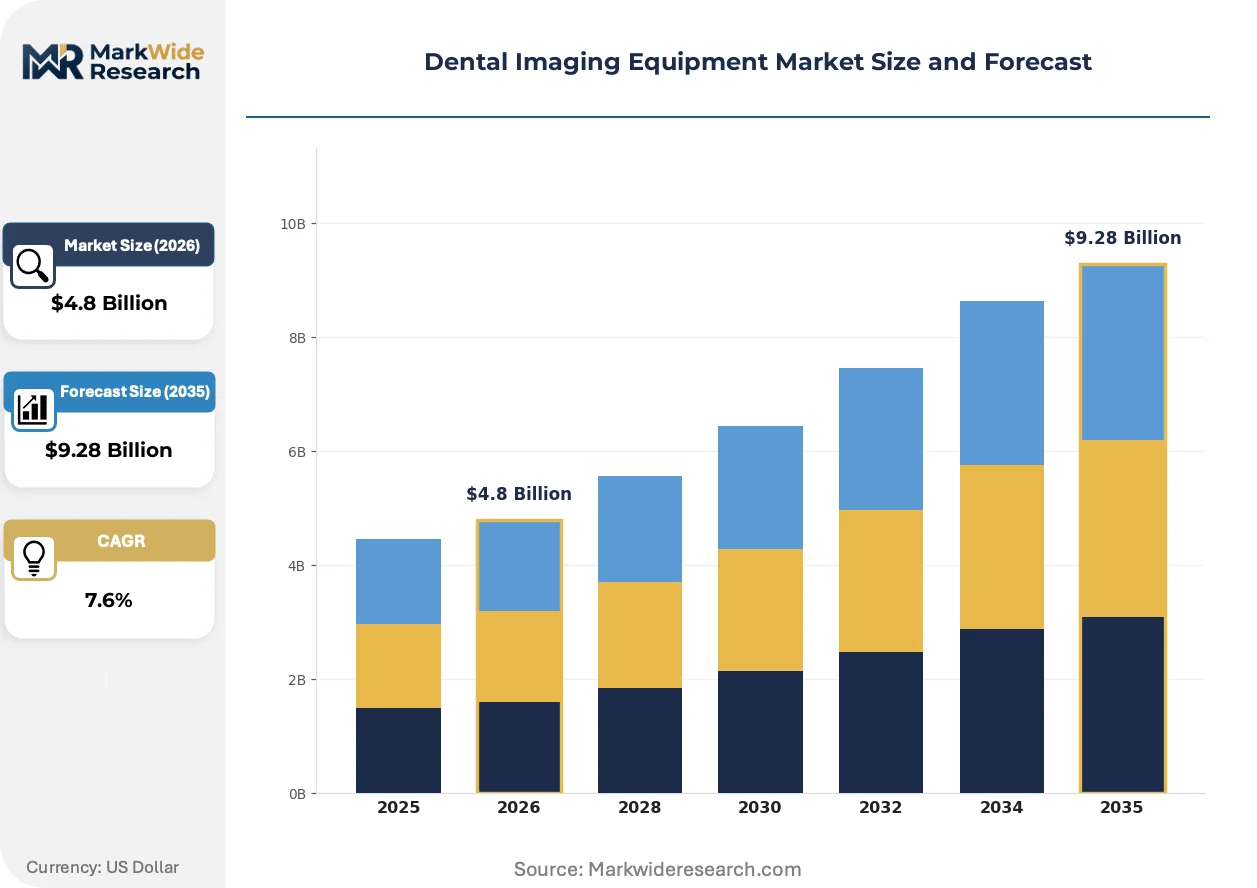
Market Dynamics
Buyer consolidation among dental service organizations is compressing procurement cycles and forcing equipment vendors to restructure sales organizations around enterprise account management rather than individual practice relationships.
Growth Catalysts
- FDA 510(k) pathway refinement:Streamlined premarket notification processes for radiological devices are accelerating product innovation cycles and reducing time-to-revenue for novel imaging modalities.
- Digital impression workflows:Chairside intraoral scanning is displacing polyvinyl siloxane-based physical impressions across orthodontic and restorative practices, driving hardware refresh demand.
- Implantology volume expansion:Three-dimensional bone assessment requirements for dental implant placement are elevating cone beam computed tomography from specialty to standard-of-care equipment.
Market Restraints
- Xenon tube supply concentration:Sourcing vulnerability for high-frequency generators in extraoral systems concentrates among Japanese and German component suppliers, exposing OEMs to input bottlenecks.
- MDR clinical evidence requirements:Europe's Medical Device Regulation imposes extended notified body conformity assessments for novel imaging modalities, lengthening market access timelines by 12-18 months.
- Optical surface scanning substitution:Structured light and confocal microscopy techniques for orthodontic monitoring are capturing share from low-dose radiographic tracking in adolescent patient populations.
Strategic Opportunities
- AI-enabled diagnostic software:Machine learning algorithms for caries detection and periodontal assessment are triggering software-as-a-medical-device regulatory frameworks, creating first-mover advantage for compliant vendors.
- India dental infrastructure buildout:Government health scheme expansion into tier-2 and tier-3 cities is generating demand for portable digital radiography systems at price points below Western equivalents.
- Subscription-based equipment access:Managed service models bundling hardware, maintenance, and consumables are penetrating multi-site dental networks seeking to convert capital expenditure to operational expenditure.
Industry Challenges
- Workflow integration complexity:Connecting new imaging systems to legacy practice management software requires custom HL7/FHIR interface development, extending deployment timelines and inflating implementation costs.
- Radiation physicist certification scarcity:Qualified personnel for equipment calibration and shielding plan validation are concentrated in urban academic medical centers, creating service coverage gaps in rural markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Imaging Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Cone Beam Computed Tomography, Digital X-ray, 3D Imaging Systems Technology: Computed Tomography, Digital Radiography, Optical Imaging, Ultrasound End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Application: Orthodontics, Implantology, Periodontics, Diagnosis |
| Companies Covered | Envista Holdings Corporation, DENTSPLY SIRONA, Planmeca Oy, ACTEON Group, Carestream Dental LLC, VATECH Co. Ltd., DÜRR DENTAL SE, Owandy Radiology, Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Imaging Equipment Market Emerging Trajectories
Artificial intelligence integration is transforming diagnostic workflows from image capture to treatment planning, compressing the traditional radiologist-in-the-loop model toward real-time chairside decision support.
Photorealistic rendering engines embedded in cone beam computed tomography workstations are electrifying surgical planning accuracy. Oral surgeons in high-volume implantology practices are adopting these visualization tools within 18-month replacement cycles. The technology is electrifying competitive differentiation among equipment vendors, forcing rapid software roadmap acceleration to match perceived clinical value.
The EU AI Act's risk classification framework for medical decision-support software is recalibrating development priorities for imaging OEMs. High-risk algorithmic diagnostic features now require conformity assessment by notified bodies before CE marking. Intraoral scanner manufacturers with embedded caries detection modules are restructuring quality management systems to accommodate post-market performance monitoring obligations.
Consolidated procurement by dental service organizations is fragmenting the traditional dealer-distributor channel. Large networks are establishing direct purchasing relationships with manufacturers, disintermediating regional equipment distributors who previously provided financing and installation services. This channel compression is most visible in the United States, where DSOs control equipment standardization across 15,000-plus practice locations and negotiate enterprise pricing unavailable to independent practitioners.
Dental Imaging Equipment Market Segmentation
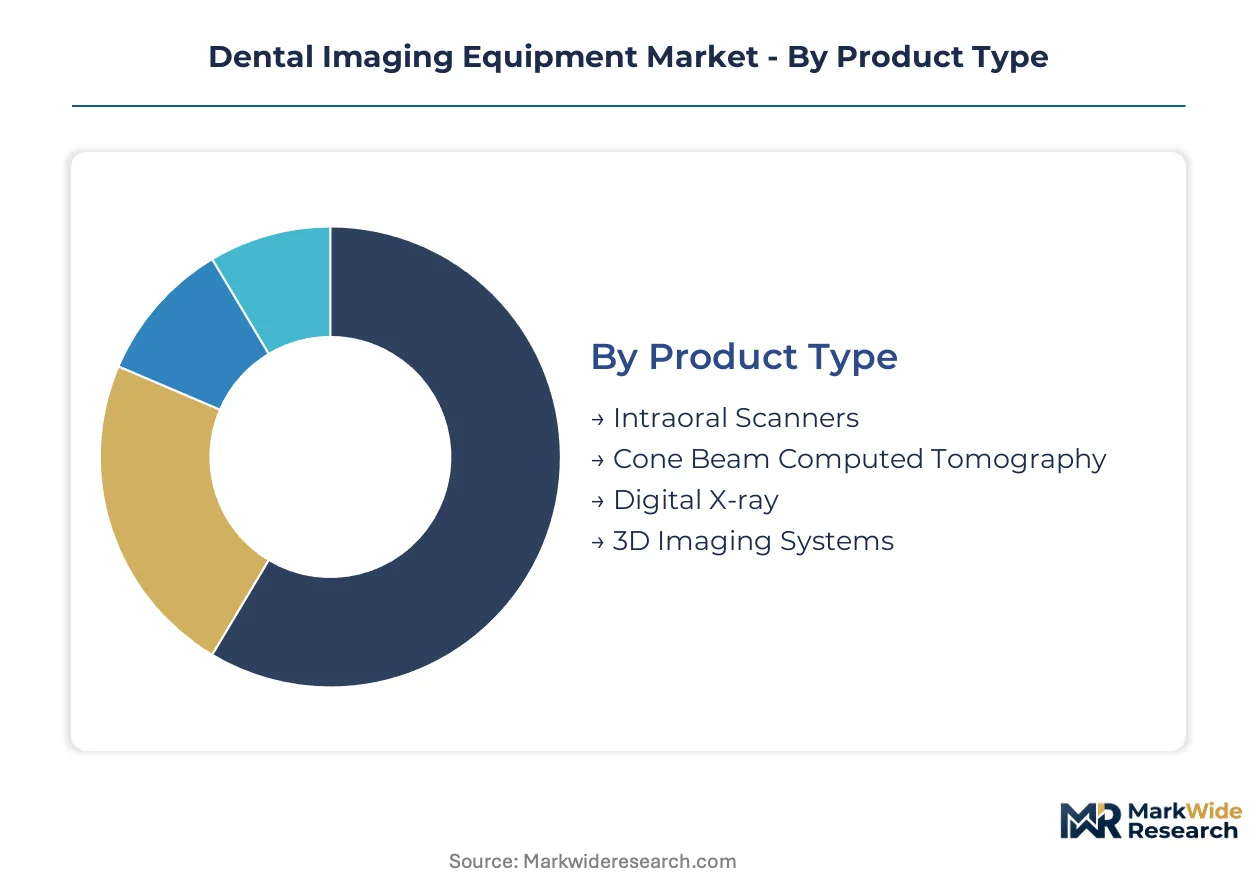
Dental imaging equipment segmentation reveals distinct procurement patterns across product categories. Buyers prioritize workflow integration capabilities when selecting systems, with technology maturity and end-use environment shaping final purchasing decisions.
Product Type:
Purchase decisions in this category pivot on chairside throughput requirements versus diagnostic depth needs.
- Intraoral Scanners:These devices capture three-dimensional surface topography using confocal microscopy or structured light projection at 10-50 µm accuracy. Demand concentrates in orthodontic practices across the United States where digital impression workflows displace polyvinyl siloxane molds. Chairside manufacturing integration accelerates replacement cycles.
- Cone Beam Computed Tomography:Systems generate volumetric datasets at 5-150 µm voxel resolution with sub-millisecond exposure controls. Implantology specialists in Germany and Japan drive premium positioning as three-dimensional bone assessment becomes standard-of-care for treatment planning. Radiation dose minimization features command price premiums.
- Digital X-ray:Solid-state sensors with CMOS or CCD architectures deliver immediate image availability at lower per-exposure cost than film-based systems.
- 3D Imaging Systems:Photorealistic rendering engines embedded in workstations support surgical planning accuracy for complex oral and maxillofacial procedures.
Intraoral scanners lead on scale; cone beam computed tomography leads on momentum.
Technology:
Adoption velocity in this category tracks regulatory clearance timelines and interoperability standards maturity.
- Computed Tomography:Cone beam variants optimized for maxillofacial anatomy operate at reduced radiation dose compared to medical CT. European implantology clinics drive demand following MDR conformity assessment requirements for diagnostic equipment. Voxel resolution specifications differentiate premium from standard configurations.
- Digital Radiography:Direct and indirect conversion sensors dominate intraoral applications with immediate image processing. Dental service organizations in the United States standardize procurement across multi-site networks, compressing price points through volume aggregation. Lower total cost of ownership sustains market penetration.
- Optical Imaging:Structured light and confocal techniques enable surface topography tracking without ionizing radiation exposure.
- Ultrasound:Emerging modality for soft tissue assessment in periodontal applications where radiographic density mapping provides insufficient contrast.
Digital radiography leads on scale; computed tomography leads on momentum.
End User:
Facility type determines capital allocation cycles and service coverage requirements for equipment vendors.
- Dental Clinics:Outpatient settings encompassing solo practices through multi-site dental service organizations drive volume demand. Large networks in the United States negotiate enterprise pricing and direct manufacturer relationships, disintermediating traditional dealer channels. Workflow integration with practice management software determines vendor selection.
- Hospitals:Academic medical centers and integrated delivery networks concentrate advanced imaging for complex oral and maxillofacial surgery. Radiation physicist certification requirements create service coverage gaps in rural markets, favoring vendors with comprehensive field service organizations.
- Research Institutions:Universities and dental schools prioritize imaging systems with open architecture for algorithm development and clinical validation studies.
- Laboratories:Commercial dental laboratories utilize optical scanning for prosthesis design and manufacturing quality control.
Dental clinics lead on scale; hospitals lead on momentum.
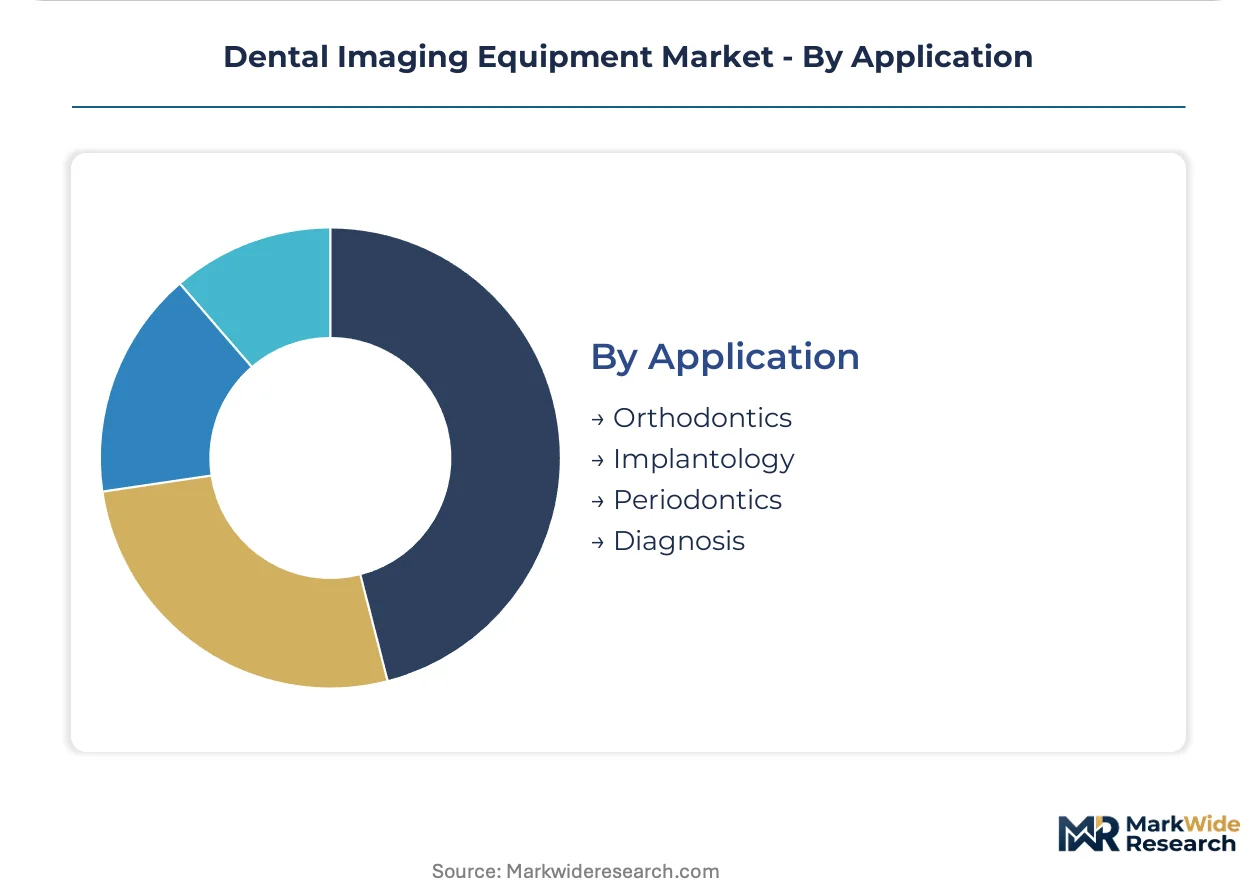
Application:
Clinical indication shapes equipment specification requirements and reimbursement dynamics.
- Orthodontics:Intraoral scanning and optical tracking enable digital treatment planning and appliance fabrication. Adolescent patient populations in the United States drive demand for radiation-free monitoring alternatives to serial radiographic assessment. Clear aligner therapy expansion accelerates hardware refresh cycles.
- Implantology:Three-dimensional bone assessment requirements elevate cone beam computed tomography from specialty to standard-of-care equipment. Surgeons in Germany, Japan, and the United States adopt photorealistic rendering workstations within 18-month replacement cycles for surgical planning accuracy.
- Periodontics:Soft tissue assessment and bone level monitoring applications favor optical coherence tomography and ultrasound modalities.
- Diagnosis:General restorative and preventive applications sustain baseline demand for digital radiography across all practice settings.
Diagnosis leads on scale; implantology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's implantology specialists drive premium cone beam computed tomography adoption, while India's government health schemes accelerate portable digital radiography penetration into tier-2 and tier-3 cities.
United States
Dental service organizations control equipment standardization across 15,000-plus practice locations, compressing procurement cycles through enterprise pricing negotiations. The FDA's 510(k) pathway refinement for radiological devices accelerates product innovation cycles and reduces time-to-revenue for novel imaging modalities. Large multi-site networks in Texas and Florida establish direct manufacturer relationships, disintermediating traditional regional equipment distributors.
Germany
Implantology clinics drive premium positioning for cone beam computed tomography systems as three-dimensional bone assessment becomes standard-of-care for treatment planning. The Medical Device Regulation imposes extended notified body conformity assessments for novel imaging modalities, lengthening market access timelines by 12-18 months. Munich and Stuttgart concentrate advanced imaging manufacturing capabilities, with regional vendors supplying hardware-software integrated workstations to European specialists.
Japan
Xenon tube supply concentration for high-frequency generators in extraoral systems creates sourcing vulnerability concentrated among domestic component suppliers. METI standards govern diagnostic x-ray system performance requirements alongside international ISO 13485 quality management protocols. Tokyo and Osaka dental clinics adopt photorealistic rendering workstations within compressed replacement cycles for surgical planning accuracy.
India
Government health scheme expansion into tier-2 and tier-3 cities generates demand for portable digital radiography systems at price points below Western equivalents. CDSCO regulates medical device imports and manufacturing licensing through risk-based classification frameworks. Maharashtra and Gujarat dental infrastructure buildout concentrates procurement activity, with regional distributors serving emerging clinic networks in Pune and Ahmedabad metropolitan corridors.
China
Domestic manufacturing scale advantages support cost-competitive digital radiography sensor production for intraoral applications. NMPA medical device registration requirements govern market access for imported imaging equipment through clinical trial and quality system documentation. Shanghai and Shenzhen industrial clusters concentrate optical imaging component fabrication, supplying structured light modules for orthodontic monitoring devices.
Dental Imaging Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans integrated dental equipment portfolios, imaging technology specialists, and regional manufacturing operations. Three archetypes dominate: full-platform providers bundling hardware-software-consumables, imaging-focused specialists with vertical manufacturing control, and value-tier suppliers serving emerging markets. Competitive dynamics center on enterprise account management restructuring and subscription-based equipment access models.
Within the diversified-platform tier, Envista Holdings Corporation and DENTSPLY SIRONA occupy positions serving multi-site dental networks with integrated workflow solutions. Planmeca Oy anchors the vertically-integrated specialist segment through captive manufacturing spanning hardware, software, and imaging analytics. These three entities exemplify contrasting strategic postures: portfolio breadth against manufacturing depth against technology convergence.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| DENTSPLY SIRONA |
| Planmeca Oy |
| ACTEON Group |
| Carestream Dental LLC |
| VATECH Co. Ltd. |
| DÜRR DENTAL SE |
| Owandy Radiology |
| Midmark Corporation |
| Others |
Supply Flow & Price Mechanics
Xenon tube sourcing from Japanese and German specialty component producers flows through high-frequency generator assemblies into tiered equipment pricing. CMOS sensor fabrication in South Korea and Taiwan anchors cost structures for digital radiography systems, while final assembly location determines landed price differentials across North American and European dental networks.
Pricing Analysis
Capacity additions in Chinese CMOS sensor foundries are reshaping price floors for intraoral digital radiography systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared cone beam systems from CE-marked equivalents and non-certified regional alternatives. Pricing pressure stems from dental service organization volume aggregation in the United States, where enterprise procurement compresses margins on standard-tier equipment. Independent solo practices exhibit highest price sensitivity, while hospital-affiliated oral surgery centers absorb premium-tier positioning for photorealistic rendering workstations.
Supply Chain Analysis
Photoresist supply for CMOS sensor fabrication rests on Japanese specialty chemical producers concentrated in the Kanto industrial corridor. High-purity xenon gas extraction draws from Ukrainian and Russian feedstock processors, with purification finishing in Germany and Japan. Single-source vulnerability concentrates in high-frequency generator tube manufacturing, where two domestic Japanese suppliers control 80 percent of global output for extraoral imaging systems. Distribution runs through regional equipment dealers in mature markets, while direct manufacturer relationships serve consolidated dental service organization networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental imaging equipment offers margin expansion through AI-enabled diagnostic software tiering, where algorithmic feature sets command subscription premiums atop hardware base pricing. Cost compression in CMOS sensor supply from Chinese foundry expansion creates headroom for mid-tier equipment vendors to capture share without sacrificing gross margins.
For Market Incumbents: Deploy enterprise account management restructuring to defend installed base relationships against direct manufacturer encroachment by dental service organizations. Capture AI diagnostic module certification investment to lock in software-as-a-medical-device compliance ahead of EU AI Act enforcement. Counter optical surface scanning substitution in orthodontic monitoring through bundled radiographic-optical hybrid system positioning. For New Entrants and Emerging Players: Enter via portable digital radiography systems targeting India's tier-2 and tier-3 city clinic buildout under government health scheme expansion. White-space concentration sits in subscription-based equipment access models for mid-sized dental networks seeking operational expenditure conversion. Pursue CDSCO registration pathway for cost-engineered sensor platforms priced 40 percent below Western equivalents. For Investors and Strategic Acquirers: Consolidation pressure builds where AI-enabled diagnostic software capabilities outpace legacy hardware vendors' development roadmaps. Five-to-ten year viability favors acquisition targets with vertical manufacturing control spanning sensor fabrication through workstation assembly. Watch FDA 510(k) clearance velocity for novel imaging modalities as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Software Development | Machine learning algorithms for caries detection trigger SaMD regulatory frameworks requiring notified body conformity assessment. |
| Subscription Equipment Access Model | Managed service bundling converts capital expenditure to operational expenditure for multi-site dental networks. |
| Enterprise Account Management Restructuring | Direct manufacturer relationships disintermediate regional distributors serving consolidated dental service organizations. |
| CMOS Sensor Backward Integration | In-house sensor fabrication captures margin from South Korean and Taiwanese foundry suppliers. |
| India Regulatory Registration Pathway | CDSCO medical device licensing unlocks government health scheme procurement in tier-2 and tier-3 cities. |
Methodological Framework
Multiple input streams — primary interviews with dental equipment procurement directors, biomedical engineers at academic medical centers, and GPO contracts managers, alongside secondary validation through FDA 510(k) filings, ISO 13485 certification databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations captured equipment replacement cycle timing, workflow integration requirements, and pricing negotiation dynamics across independent practices and dental service organization networks.
Data-stream reconciliation across product type segmentation, technology adoption curves, end-user facility categories, and application-specific equipment specifications generated volume and value outputs over the projection horizon. CAGRs were derived from installed base growth, replacement cycle compression, and penetration rate modeling across intraoral scanners, cone beam computed tomography, and digital radiography systems. Forecast inputs incorporated dental implantology volume expansion, clear aligner therapy adoption, and regulatory clearance timeline assumptions.
Inputs from FDA premarket notification databases and European notified body conformity assessment records were available through the study window; gaps in private dental service organization procurement transaction data introduce uncertainty bands around enterprise pricing estimates. Forecasts reflect documented assumptions regarding AI diagnostic software regulatory classification evolution and xenon tube supply chain stability. A small set of named triggers — MDR clinical evidence requirement enforcement, EU AI Act high-risk algorithm classification, and India PLI scheme medical device manufacturing incentives — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market