
 Global Professional Teeth Whitening and Power Toothbrushes Market | 2026-2036
Global Professional Teeth Whitening and Power Toothbrushes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Professional Teeth Whitening and Power Toothbrushes Market Foresight
The capital-intensity divergence between capital-light whitening gel marketers and vertically integrated power toothbrush manufacturers is unwinding as clinic-grade equipment absorbs larger shares of professional budgets. Procter & Gamble leverages its oral care distribution infrastructure to secure shelf space across dental supply chains. Colgate-Palmolive competes through bundled whitening protocols that anchor recurring consumable purchases. Koninklijke Philips dominates rechargeable power toothbrush engineering, sustaining premium positioning through proprietary sonic motor platforms.
Professional teeth whitening and power toothbrushes encompass electromechanical devices and chemically activated systems designed to remove extrinsic stains and modify tooth shade, typically operating at sonic frequencies between 20,000 and 62,000 brush strokes per minute or employing hydrogen peroxide concentrations calibrated for supervised application. Power toothbrushes with ultrasonic technology capture the highest margin pools due to motor miniaturization costs and patent-protected drive systems. Whitening gels represent the largest volume category within professional kits, though LED activation devices register the fastest structural growth as chairside protocols shorten treatment duration. Home use applications remain mature, while dental clinics absorb disproportionate investment in connected brushing analytics and shade-monitoring peripherals.
The US FDA Center for Devices and Radiological Health classifies power toothbrushes as Class I medical devices, while professional whitening gels exceeding certain peroxide thresholds trigger drug-cosmetic hybrid oversight that constrains formulation portability across jurisdictions. Japan's PMDA and Germany's BfArM impose additional electromagnetic compatibility and biocompatibility testing that extend market access timelines for novel LED-UV convergence products. Stakeholders must monitor evolving peroxide concentration ceilings and connected device cybersecurity mandates as regulatory fragmentation between North American and European approval pathways deepens.
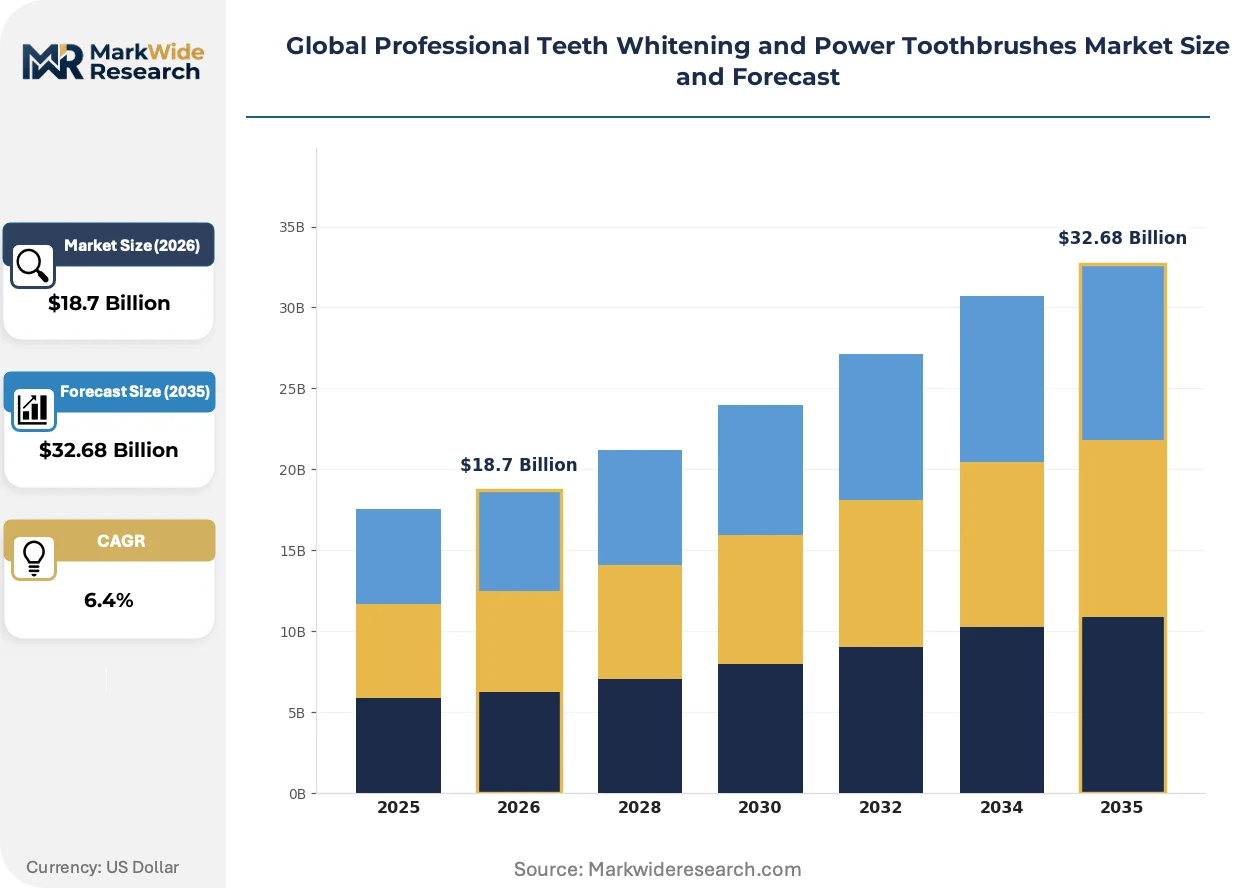
Market Dynamics
Professional chairside protocols are compressing treatment duration from weeks to single sessions, reallocating capital from retail whitening strips toward LED-UV activation systems and connected brushing peripherals in dental clinics.
Growth Catalysts
- FDA Class I Medical Device Pathway:The streamlined clearance for power toothbrushes accelerates product iteration cycles, enabling faster sonic motor platform upgrades.
- Hydrogen Peroxide Concentration Thresholds:Calibrated peroxide ceilings in professional settings create supervised-application moats that retail alternatives cannot cross.
- Dental Clinic Density in Japan:Metropolitan Tokyo and Osaka clusters sustain per-capita professional whitening expenditure above global medians.
Market Restraints
- Neodymium Magnet Supply Concentration:Rare earth processing bottlenecks in upstream sonic motor manufacturing elevate component lead times.
- EU Medical Device Regulation Transition:MDR conformity assessment extensions delay LED-UV convergence product launches by 12-18 months.
- Retail Whitening Strip Substitution:Over-the-counter carbamide peroxide alternatives capture price-sensitive home-use segments.
Strategic Opportunities
- Teledentistry Integration in Germany:Remote shade-monitoring peripherals unlock rural clinic access without physical specialist presence.
- AI-Powered Brushing Analytics:Pressure-sensor data convergence with smartphone apps creates recurring subscription revenue streams.
- India's PLI Scheme for Electronics:Manufacturing incentives for electromechanical devices reduce landed costs for power toothbrush assembly.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity validation queues extend gel formulation launch timelines.
- Electromagnetic Compatibility Certification:PMDA and BfArM testing divergence forces duplicate protocol runs for Japan and Germany market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Professional Teeth Whitening and Power Toothbrushes Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional Teeth Whitening Kits, Power Toothbrushes, Whitening Gels, Replacement Brush Heads, LED Light Devices Technology: Ultrasonic, Sonic, LED Activation, UV Light, Manual, Battery Operated Application: Cosmetic Dentistry, Dental Clinics, Home Use, Spa & Wellness Centers, Orthodontics End User: Dental Professionals, Dental Hygiene Specialists, Beauty Salons, Adult Consumers, Teenagers |
| Companies Covered | Procter & Gamble, Colgate-Palmolive Company, Koninklijke Philips, Ultradent Products, Water Pik, Lion Corporation, Omron Corporation, DenMat Holdings, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Professional Teeth Whitening and Power Toothbrushes Market Shifts & Advancements
Connected oral care ecosystems are fragmenting device-purchasing decisions across dental supply chains, shifting value capture from standalone hardware toward integrated chairside-home monitoring platforms.
Ultrasonic transducer miniaturization is decomposing the cost premium between premium sonic and standard oscillating power toothbrushes. Dental clinics in the United States and Germany are adopting these compact drive systems for portable chairside cleaning units. The technology is decomposing historical price stratification between professional and consumer-grade electromechanical devices.
EU MDR Article 10 post-market surveillance requirements are tightening clinical evidence standards for professional whitening gels exceeding six percent hydrogen peroxide. Manufacturers must now submit periodic safety update reports that track adverse event rates across member states. German notified bodies are processing these submissions with priority queues, while French competitors face extended review cycles.
Subscription-based consumable replenishment is displacing traditional wholesale purchasing in dental supply chains. Clinics in Japan and the United States are locking into multi-year gel cartridge contracts tied to hardware lease agreements. This procurement compression is most visible in metropolitan dental service organizations that standardize protocols across fifty-plus chair networks.
Global Professional Teeth Whitening and Power Toothbrushes Market Segmentation
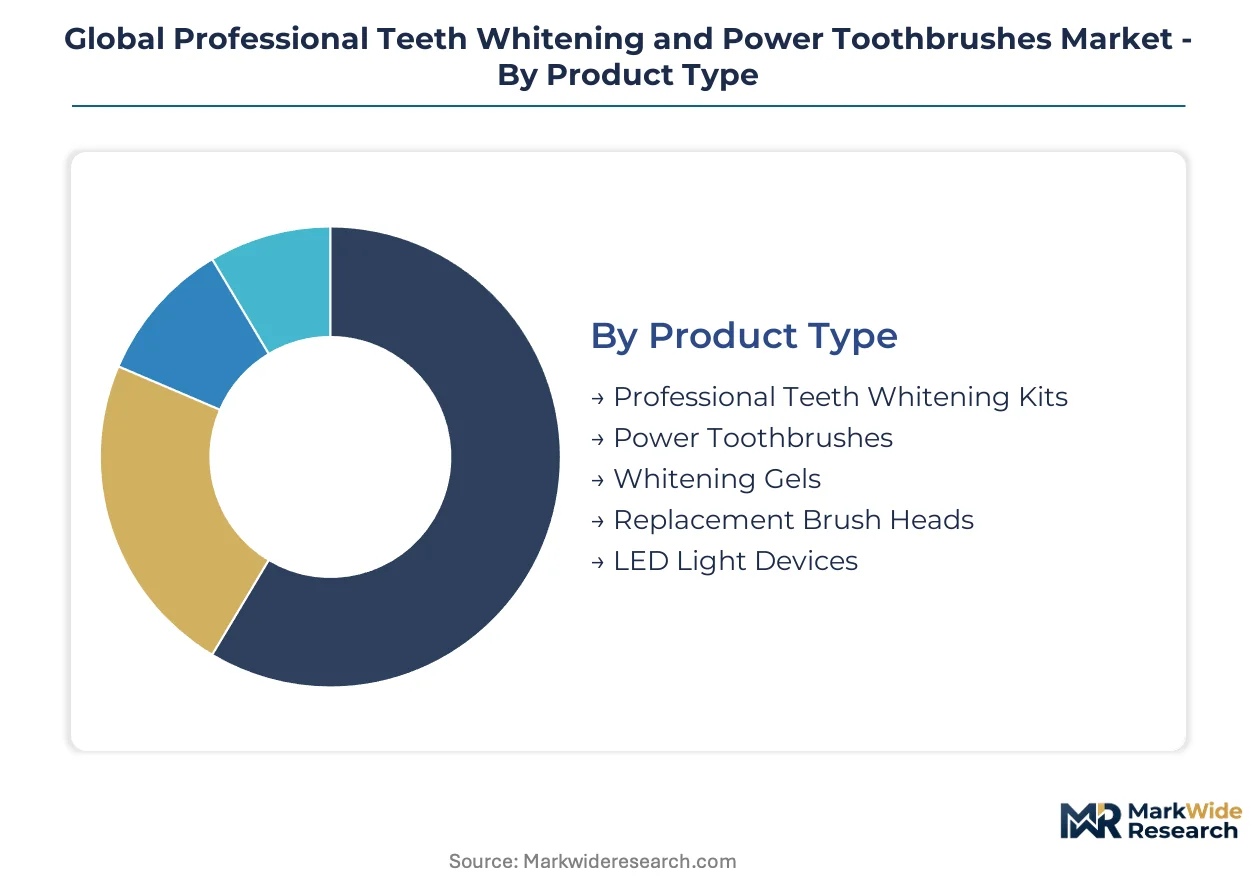
Channel configuration determines how value flows across the professional teeth whitening and power toothbrushes market. Dental supply chains favor bundled equipment-consumable arrangements, while retail channels fragment purchasing decisions across standalone devices and replenishment cycles.
Product Type:
Professional budgets concentrate on chairside systems that lock in recurring consumable purchases, whereas home-use channels absorb volume through lower-ASP disposables and replacement cycles.
- Professional Teeth Whitening Kits:Comprehensive chairside systems combine hydrogen peroxide gels with LED activation hardware calibrated for supervised application. Demand clusters in dental clinics across the United States and Germany, where reimbursement structures favor bundled procedure billing over component separation.
- Power Toothbrushes:Rechargeable electromechanical devices operating at sonic frequencies between 20,000 and 62,000 brush strokes per minute. Metropolitan Tokyo and Osaka dental service organizations standardize procurement across fifty-plus chair networks, compressing vendor selection timelines.
- Whitening Gels:Hydrogen peroxide formulations ranging from six percent for home use to higher concentrations restricted to professional settings.
- Replacement Brush Heads:Proprietary coupling systems that anchor recurring revenue streams through hardware lock-in.
- LED Light Devices:Chairside activation peripherals that shorten single-session treatment duration.
By volume, whitening gels lead. By growth pace, LED light devices are expanding most quickly.
Technology:
Cost tiers separate premium motor engineering from commodity battery alternatives, with patent-protected drive systems commanding manufacturing margin premiums.
- Ultrasonic:Transducer-based systems operating above 20,000 Hz through piezoelectric crystal excitation. Japanese PMDA electromagnetic compatibility testing creates twelve-to-eighteen-month approval timelines that filter out mid-tier competitors lacking regulatory bandwidth.
- Sonic:Mechanically driven brush heads generating fluid dynamic cleaning action through acoustic pressure waves. German BfArM biocompatibility validation prioritizes submissions from notified bodies with established dental device track records.
- LED Activation:Narrow-spectrum light sources accelerating peroxide decomposition rates.
- UV Light:Shorter wavelength systems requiring stricter occupational safety protocols.
- Manual:Non-powered alternatives retaining share in price-sensitive segments.
- Battery Operated:Disposable power sources dominating travel and trial purchase occasions.
Ultrasonic systems capture the steepest margin expansion, while battery-operated units face share erosion from rechargeable platform convergence.
Application:
Customer type stratifies between institutional procurement committees and individual purchase decisions, with dental clinics absorbing disproportionate connected device investment.
- Dental Clinics:Professional settings deploying chairside protocols with shade-monitoring peripherals and integrated brushing analytics. Teledentistry integration in rural Germany unlocks specialist access without physical presence, expanding addressable clinic density.
- Cosmetic Dentistry:Aesthetic-focused practices bundling whitening with orthodontic and veneer procedures. United States metropolitan markets sustain per-capita expenditure above global medians through elective procedure financing structures.
- Home Use:Mature segment facing retail whitening strip substitution pressure.
- Spa & Wellness Centers:Non-clinical channels operating under lighter regulatory oversight.
- Orthodontics:Specialty practices integrating whitening into post-bracket treatment protocols.
Dental clinics anchor professional revenue concentration, though cosmetic dentistry practices are gaining share fastest through elective procedure bundling.
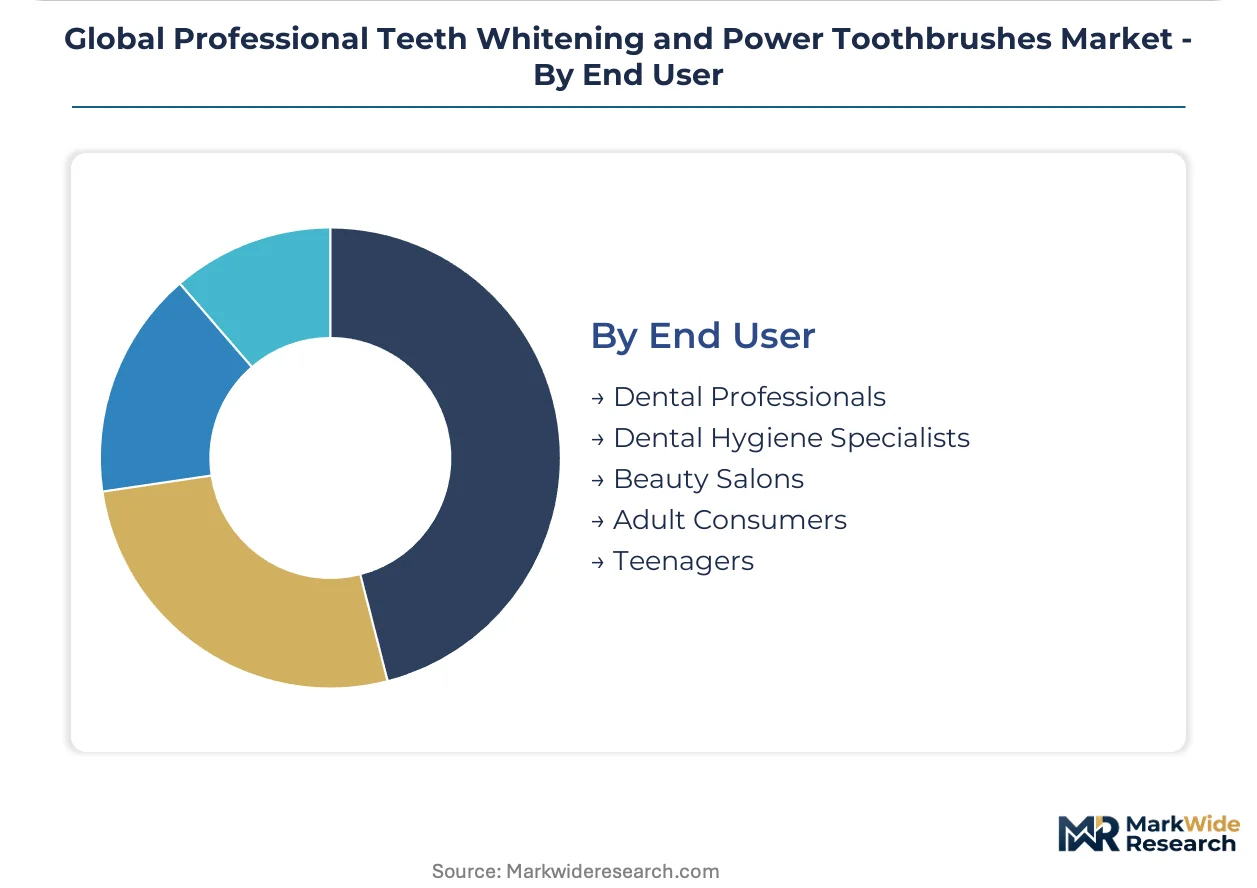
End User:
Volume scale separates institutional purchasers negotiating multi-year supply contracts from individual consumers responding to point-of-sale promotion.
- Dental Professionals:Licensed practitioners with prescribing authority for higher-concentration peroxide formulations. EU MDR Article 10 post-market surveillance requirements now mandate periodic safety update reports tracking adverse events across member states.
- Dental Hygiene Specialists:Chairside support staff executing supervised application protocols under professional supervision. Japanese clinic networks in Tokyo and Osaka standardize training curricula that preference specific equipment manufacturers.
- Beauty Salons:Non-dental channels with restricted formulation access.
- Adult Consumers:Direct purchasers through retail and e-commerce channels.
- Teenagers:Segment with elevated sensitivity to social media-driven aesthetic norms.
Dental professionals dominate value capture, while dental hygiene specialists are climbing the fastest as scope-of-practice expansions broaden chairside execution authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across markets: Japanese dental clinics absorb premium chairside systems with minimal price sensitivity, while Indian consumers gravitate toward battery-operated entry points. German reimbursement structures insulate professional protocols from retail substitution, whereas Brazilian buyers face acute trade-offs between clinic-grade whitening and over-the-counter strips.
United States
Cosmetic dentistry practices in metropolitan Los Angeles and Miami bundle whitening with elective procedures financed through third-party credit. FDA Class I medical device clearance accelerates power toothbrush iteration cycles for domestic manufacturers. Dallas-Fort Worth dental service organizations standardize procurement across fifty-plus chair networks, compressing vendor selection timelines.
Germany
BfArM biocompatibility validation prioritizes submissions from notified bodies with established dental device track records. EU MDR Article 10 post-market surveillance mandates periodic safety update reports for professional whitening gels exceeding six percent hydrogen peroxide. The Munich-Stuttgart corridor concentrates teledentistry integration pilots that extend specialist access to rural Bavarian clinics.
Japan
PMDA electromagnetic compatibility testing creates twelve-to-eighteen-month approval timelines that filter out mid-tier competitors lacking regulatory bandwidth. Metropolitan Tokyo and Osaka dental service organizations sustain per-capita professional whitening expenditure above global medians. Japanese clinic networks standardize training curricula that preference specific equipment manufacturers for chairside execution.
India
PLI scheme incentives for electromechanical devices reduce landed costs for power toothbrush assembly targeting price-sensitive home-use segments. India's central pharmaceutical regulator imposes additional stability testing on hydrogen peroxide formulations that delays professional gel launches by eight to ten months. Maharashtra and Gujarat manufacturing clusters absorb contract assembly volumes for rechargeable sonic motor platforms.
Brazil
ANVISA hybrid drug-cosmetic oversight constrains peroxide concentration portability between professional and retail channels. São Paulo and Rio de Janeiro cosmetic dentistry practices face acute competition from spa and wellness centers operating under lighter regulatory frameworks. Southeast Asian supply chain intermediaries dominate whitening gel import logistics into Brazilian port complexes.
Global Professional Teeth Whitening and Power Toothbrushes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Vertically integrated electromechanical specialists command premium positioning through proprietary motor platforms, while formulation marketers compete on peroxide concentration calibration and chairside protocol bundling. Three archetypes dominate: rechargeable sonic engineering houses, hydrogen peroxide gel specialists, and dental supply chain integrators. Competitive moves concentrate on M&A for regulatory bandwidth acquisition and strategic partnerships for teledentistry platform integration.
Within the premium engineering tier, Koninklijke Philips and Panasonic occupy positions defined by transducer miniaturization capabilities and electromagnetic compatibility certification depth. Procter & Gamble exemplifies the supply chain integrator archetype, leveraging oral care distribution infrastructure to secure shelf space across dental supply chains. These three companies represent contrasting strategic postures: proprietary platform control, component manufacturing scale, and channel integration dominance.
| Leading Market Players |
|---|
| Procter & Gamble |
| Colgate-Palmolive Company |
| Koninklijke Philips |
| Ultradent Products |
| Water Pik |
| Lion Corporation |
| Omron Corporation |
| DenMat Holdings |
| Panasonic |
| Others |
Supply & Pricing Matrix
Neodymium magnet substitution for ferrite alternatives in sonic motor assemblies is simultaneously relocating manufacturing gravity toward China's rare earth processing corridors and compressing margin structures for mid-tier rechargeable toothbrush vendors.
Pricing Analysis
Replacement brush head subscriptions drive lifetime value capture, with proprietary coupling systems locking dental clinics into multi-year consumable contracts. Pricing stratifies across premium sonic platforms, standard oscillating units, and economy battery-operated entry points, with certification grade under EU MDR and FDA Class I pathways commanding measurable premiums. Cost compression in economy tiers is intensifying because India's PLI scheme incentives attract contract assembly volumes. Individual adult consumers exhibit highest price sensitivity, while Japanese dental service organizations absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes into North American and European ports elevate inbound logistics costs for LED-UV activation hardware. Manufacturing concentrates in China, Japan, and Germany, with sonic motor engineering anchored in Japanese precision component clusters and final assembly gravitating toward Chinese electronics manufacturing zones. Upstream dependencies include rare earth magnet feedstock, piezoelectric transducer crystals, and hydrogen peroxide precursor chemicals. Single-source vulnerability in neodymium supply channels poses structural risk. Distribution runs through dental supply chain integrators and direct-to-clinic procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as retail whitening strips capture price-sensitive home-use volume and LED-UV convergence products compress professional treatment duration economics.
For Market Incumbents: Compound proprietary sonic motor platform advantages through backward integration into transducer crystal supply and accelerated FDA Class I iteration cycles. Defend against formulation marketers by bundling chairside hardware with exclusive gel cartridge contracts. Lock dental service organizations into fifty-plus chair standardization protocols that preference integrated brushing analytics.
For New Entrants and Emerging Players: Teledentistry platform integration represents the most penetrable service-layer gap, with rural German and Indian clinics underserved by specialist physical presence. Target cosmetic dentistry practices in Brazil's São Paulo corridor where ANVISA hybrid oversight creates compliance complexity incumbents navigate poorly. Deploy AI-powered shade-monitoring peripherals through smartphone companion apps as the primary go-to-market wedge.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated electromechanical specialists with electromagnetic compatibility certification depth. Long-term viability over the next decade rests on capturing recurring consumable revenue streams rather than standalone hardware margins. Watch PMDA and BfArM testing divergence resolution as the signal indicating whether mid-tier competitors can sustain multi-regional market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Bandwidth Acquisition | MDR notified body relationships in Germany accelerate LED-UV product launches against delayed French competitors. |
| Teledentistry Platform Integration | Remote shade-monitoring peripherals unlock rural clinic access without physical specialist presence in Bavaria. |
| Consumable Subscription Lock-in | Multi-year gel cartridge contracts tied to hardware leases compress procurement cycles across Japanese dental networks. |
| Sonic Motor Miniaturization R&D | Ultrasonic transducer advances decompose price premiums between professional and consumer-grade electromechanical devices. |
| PLI Scheme Manufacturing Localization | Maharashtra and Gujarat assembly clusters reduce landed costs for price-sensitive Indian home-use segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement managers, biomedical engineers at dental service organizations, regulatory affairs specialists navigating FDA and EU MDR pathways, and hydrogen peroxide formulation chemists; and secondary validation through FDA 510(k) filings, EU MDR notified body submission databases, PMDA approval records, customs trade data on oral care device imports, and dental supply chain procurement contract disclosures. Bottom-up unit economics triangulated against top-down market sizing across product type, technology platform, application setting, and end-user archetype dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by professional versus home-use channels, ultrasonic versus sonic versus battery-operated technology tiers, and dental clinic versus cosmetic dentistry versus spa and wellness center application settings. CAGRs were derived from regression analysis against per-capita dental expenditure, clinic density metrics, and regulatory approval velocity. Industry-specific inputs included hydrogen peroxide concentration ceiling movements and connected device cybersecurity mandate adoption curves.
Material uncertainties — rare earth supply disruptions, MDR conformity assessment timeline extensions, and retail whitening strip efficacy improvements — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory fragmentation persistence and professional channel preference stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Orthodontics Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Delivery System Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Fittings Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Global Dental Microscope Market