
 Dental Service Organization Market | 2026-2036
Dental Service Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Service Organization Market Intelligence
Dental support capacity in Texas and Florida is expanding faster than any other US state cluster. Heartland Dental leverages centralized procurement to sustain margin efficiency across its affiliated practices. Smile Brands anchors its growth in branded retail dentistry, while Pacific Dental Services dominates technology-intensive care delivery through proprietary digital workflow platforms. Aspen Dental Management competes on patient acquisition scale, operating over 1,000 locations with standardized fee schedules.
A dental service organization supplies non-clinical business infrastructure to affiliated dental practices, encompassing revenue cycle management, supply chain procurement, marketing, human resources, and IT systems, typically through management service agreements that preserve clinical autonomy. These entities consolidate administrative functions to reduce overhead ratios from roughly 40-50% for solo practices toward 25-30% for affiliated groups, freeing dentist capacity for chairside production. General dentistry generates the largest revenue pool within service type segmentation, though orthodontics captures superior per-procedure margins as clear aligner therapy displaces traditional bracket systems. The management service organization operational model is displacing pure group practice structures, as dentists seek equity retention without operational burden.
The US FDA regulates dental device standards including digital scanners and 3D-printed surgical guides, while OSHA mandates bloodborne pathogen protocols that DSOs standardize across networks at lower per-clinic cost than solo compliance. State dental boards in California, Texas, and New York enforce corporate practice of medicine doctrines that constrain ownership structures, creating regulatory complexity for national expansion strategies. Stakeholders must monitor how state-level scope-of-practice liberalization for dental therapists reshapes workforce economics and patient access metrics.
Market Dynamics
Administrative burden compression is restructuring dental practice economics as solo operators surrender non-clinical functions to centralized management platforms. This operational unbundling accelerates affiliation velocity across Sun Belt metropolitan corridors where dentist supply lags population inflows.
Growth Catalysts
- OSHA bloodborne pathogen standardization:DSOs deploy network-wide compliance protocols at unit costs below solo practice benchmarks, converting regulatory overhead into competitive advantage for affiliated groups.
- Clear aligner therapy substitution:Orthodontic margin expansion from bracket displacement attracts general dentistry practices seeking procedure mix diversification without specialist credentialing investments.
- Texas and Florida demographic pull:Metropolitan population growth exceeding dental graduate output creates patient access gaps that consolidated networks fill faster than de novo solo openings.
Market Restraints
- State corporate practice doctrines:California, Texas, and New York dental boards enforce ownership structure constraints that fragment national platform strategies into jurisdiction-specific legal architectures.
- Digital scanner capital intensity:Chairside intraoral imaging systems require five-figure equipment commitments that strain solo practice cash flows before affiliation.
- Dental therapist scope liberalization variance:Inconsistent state-level workforce expansion rules complicate standardized staffing models across multi-state networks.
Strategic Opportunities
- Management service agreement penetration:Equity-retention structures displace pure group practice models, preserving clinical autonomy while capturing procurement and marketing scale.
- Revenue cycle management outsourcing:Specialized billing and collections infrastructure addresses solo practice accounts-receivable bottlenecks in high-deductible plan environments.
- 3D-printed surgical guide workflow integration:Digital prosthodontics convergence with centralized lab services compresses turnaround times for implant restorations.
Industry Challenges
- HIPAA-compliant IT infrastructure migration:Legacy practice management systems require costly interoperability overhauls to integrate with DSO centralized platforms.
- Dentist retention and production optimization:Affiliate compensation modeling must balance guaranteed base structures with performance incentives that sustain chairside output targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Service Organization Market |
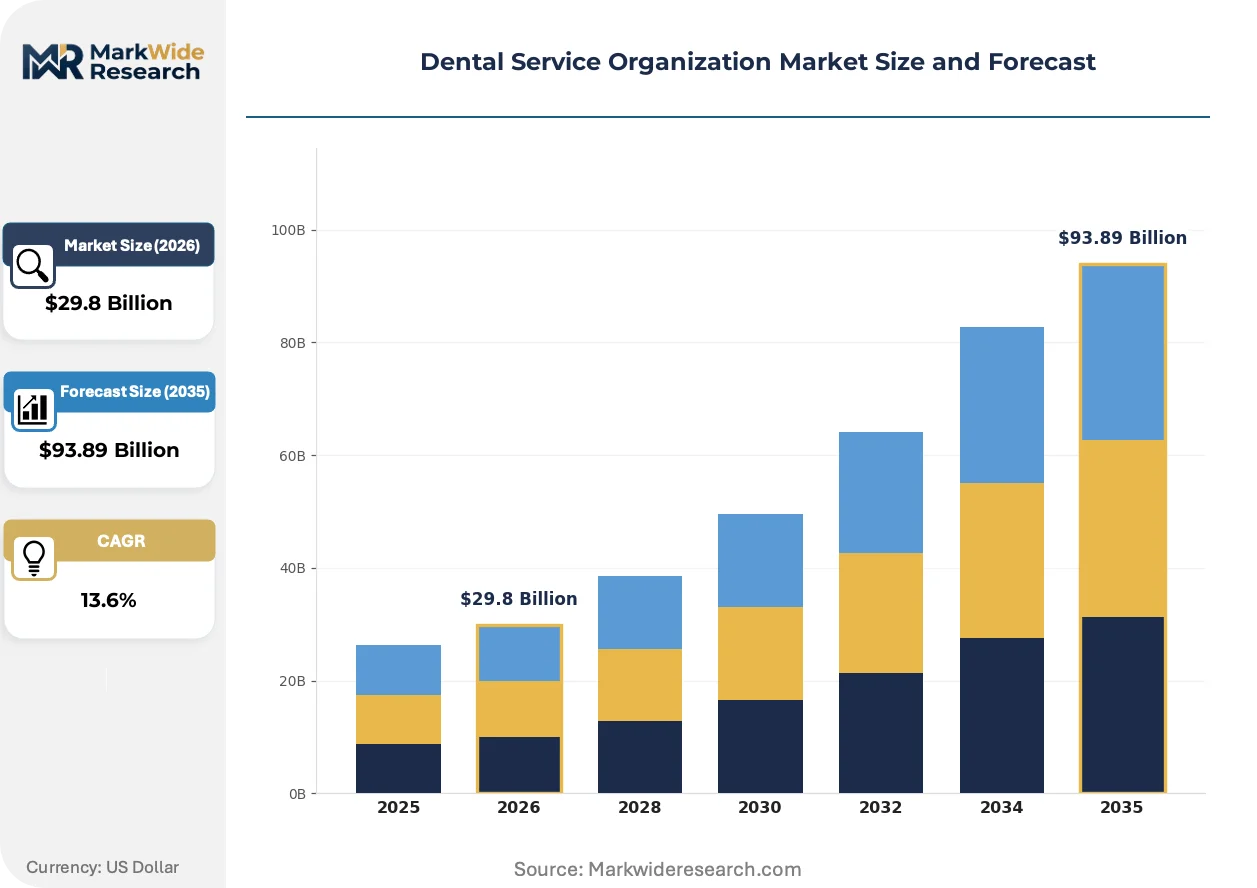
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $93.89 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Dentistry, Orthodontics, Periodontics, Endodontics Operational Model: Group Practice, Solo Practice, Management Service Organization, Franchise Customer Type: Patients, Insurance Providers, Corporations, Government Agencies Care Setting: Community Clinic, Private Practice, Hospital-based, Mobile Unit |
| Companies Covered | PDS Health, Dental Care Alliance, Heartland Dental, InterDent, Inc., Great Expressions Dental Centers, Pacific Dental Services, Smile Brands, Coast Dental Services, LLC, Aspen Dental Management, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Service Organization Market Strategic Shifts & Innovations
Digital workflow platforms are compressing treatment planning cycles and enabling remote specialist consultation across dispersed practice networks. These technological and operational shifts reshape how dental services organize, deliver, and capture value.
Intraoral scanning systems are integrating with cloud-based treatment planning software to eliminate physical impression workflows. Multi-location DSOs deploy these platforms across affiliate bases to standardize diagnostic quality and accelerate restorative throughput. The technology is integrating previously siloed clinical and administrative data streams, enabling predictive scheduling and inventory optimization.
OSHA bloodborne pathogen protocol updates mandate enhanced surface disinfection and instrument sterilization documentation. DSOs absorb these compliance costs through centralized training and supply procurement, while solo operators face disproportionate audit preparation burdens. Smaller practices in high-regulation states respond by accelerating affiliation timelines to transfer liability exposure.
Patients now expect transparent fee schedules and financing options before scheduling appointments, displacing traditional opaque pricing. Retail-oriented dental brands capture this preference shift through standardized service menus and third-party payment platforms. This behavioral pivot concentrates most visibly in suburban markets where younger households prioritize cost predictability over established provider relationships.
Dental Service Organization Market Segmentation
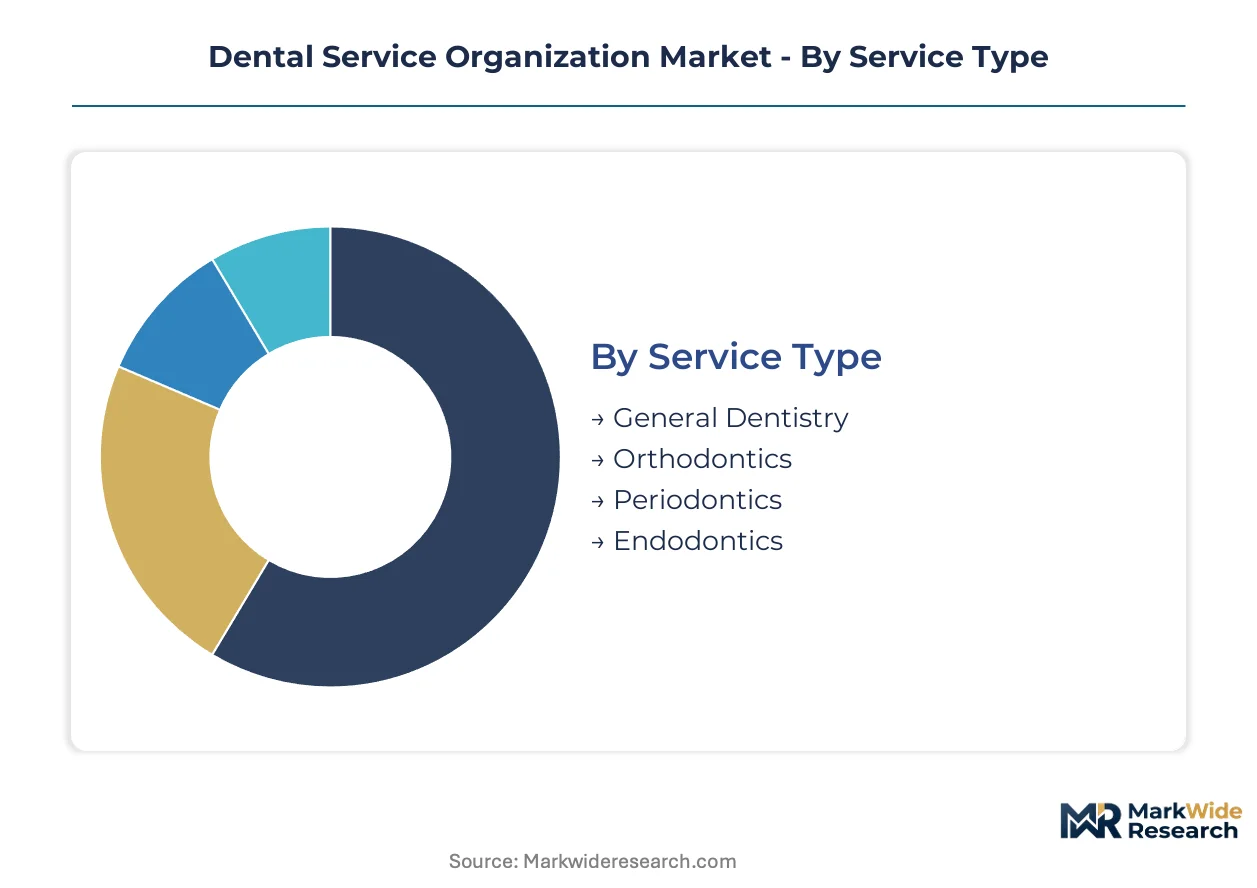
DSO market segmentation reveals how service mix, operational architecture, and care delivery settings determine capital deployment and margin capture. Each category exposes distinct consolidation pressures and technology adoption patterns across affiliated practice networks.
Service Type:
Standardization potential varies sharply across this spectrum, from commoditized preventive protocols to specialized surgical interventions requiring credentialing depth.
- General Dentistry:Comprises diagnostic exams, prophylaxis, restorations, and extractions performed without specialist referral. Demand concentrates in suburban corridors of Texas and Florida where population inflows outpace de novo practice openings. OSHA bloodborne pathogen standardization spreads fastest here due to high procedure volume and repeat patient contact.
- Orthodontics:Encompasses clear aligner therapy and traditional bracket systems for malocclusion correction. Metropolitan Sun Belt markets drive concentration as younger households prioritize aesthetic procedures. Clear aligner substitution for brackets expands per-case margins without requiring specialist partnership structures.
- Periodontics:Surgical and non-surgical management of gingival and alveolar bone disease.
- Endodontics:Root canal therapy and periapical microsurgery requiring microscopic visualization equipment.
Most installed capacity flows through General Dentistry. Expansion is steepest in Orthodontics.
Operational Model:
Cost tier stratification separates capital-light affiliation structures from equity-heavy ownership commitments across the dental practice landscape.
- Management Service Organization:Delivers non-clinical infrastructure through contractual agreements preserving dentist clinical autonomy and equity position. Sun Belt metropolitan networks favor this model for rapid scaling without regulatory ownership constraints. Revenue cycle centralization compresses overhead ratios toward 25-30% versus 40-50% for unaffiliated practices.
- Group Practice:Multiple dentists sharing ownership of a single legal entity with pooled overhead and profit distribution. Texas and Florida urban clusters show concentration where regulatory environments permit corporate practice structures. Digital scanner capital intensity burdens smaller group formations before scale thresholds.
- Solo Practice:Single-dentist ownership bearing full administrative and clinical liability.
- Franchise:Branded operational systems with territorial licensing and standardized fee schedules.
Patient volume concentrates in Management Service Organization structures. Affiliate recruitment velocity runs highest in this category.
Customer Type:
Application urgency separates acute pain-driven demand from scheduled preventive utilization across payer categories.
- Patients:Individual consumers paying through insurance, out-of-pocket, or third-party financing. Suburban Sun Belt markets concentrate demand where transparent fee schedules displace opaque pricing traditions. Financing platform integration accelerates treatment acceptance for high-deductible plan holders.
- Insurance Providers:Commercial payers and dental benefit administrators negotiating network participation rates. Metropolitan Texas corridors show concentration as DSOs leverage scale for preferred provider positioning. Revenue cycle management outsourcing addresses claims complexity for affiliated practices.
- Corporations:Employer-sponsored group dental benefits and on-site clinic contracts.
- Government Agencies:Medicaid, Medicare Advantage, and Veterans Affairs program administration.
Revenue concentration sits with Patients. Payer mix diversification is expanding fastest among Insurance Providers.
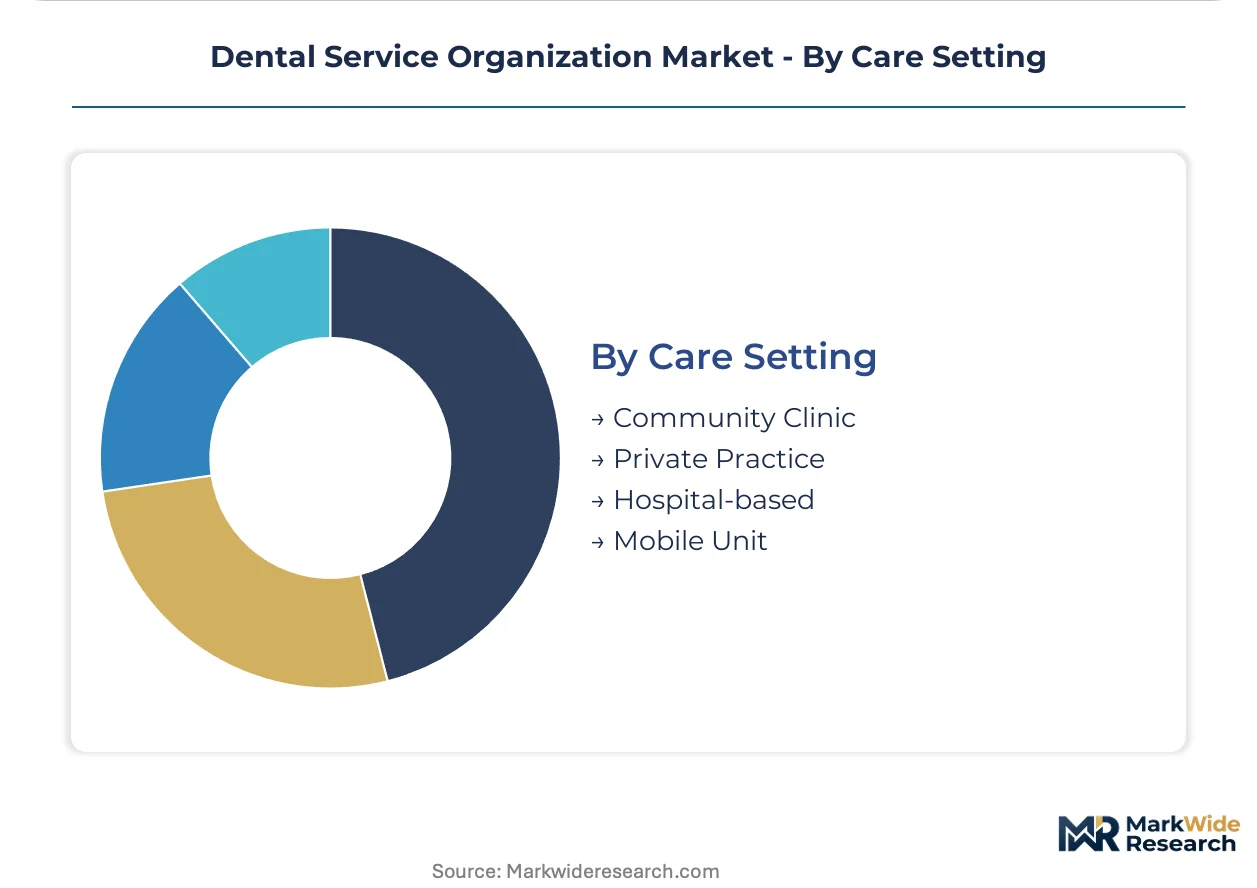
Care Setting:
Geographic accessibility determines patient capture efficiency across fixed and mobile infrastructure configurations.
- Private Practice:Independently operated clinical facilities with dedicated equipment and staff. Florida and Texas suburban corridors concentrate new affiliations where real estate costs remain below coastal metro benchmarks. HIPAA-compliant IT infrastructure migration challenges legacy system operators before DSO platform integration.
- Community Clinic:Non-profit or publicly funded facilities serving underserved populations. Rural Texas counties and Florida Panhandle regions show concentration where dentist supply gaps persist. Dental therapist scope liberalization variance complicates standardized staffing across these settings.
- Hospital-based:Dental departments integrated within acute care or academic medical centers.
- Mobile Unit:Transportable clinical facilities deployed to schools, nursing facilities, or rural sites.
Procedure volume concentrates in Private Practice. Network expansion is accelerating fastest through Community Clinic partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate DSO formation in jurisdictions where compliance cost differentials favor consolidated networks over solo operators. The United States dominates market value as state-level corporate practice doctrines fragment expansion strategies. Metropolitan Sun Belt corridors attract disproportionate affiliation velocity due to dentist supply gaps.
United States
Population growth in Texas and Florida metropolitan areas outpaces dental graduate output, creating patient access voids that DSOs fill faster than de novo solo openings. The FDA regulates dental device standards including digital scanners and 3D-printed surgical guides, while OSHA mandates bloodborne pathogen protocols that networks standardize at lower per-clinic cost. Dallas-Fort Worth and Houston anchor the nation's fastest-expanding DSO footprint.
Germany
Aging demographics and statutory insurance reimbursement pressures drive practice consolidation toward centralized management structures. The country's national pharmaceutical regulator maintains strict medical device classification standards for intraoral imaging systems. Bavaria and North Rhine-Westphalia concentrate affiliated practice networks where procurement scale offsets compressed reimbursement rates.
United Kingdom
NHS dental contract reforms and workforce shortages accelerate private-sector DSO penetration in underserved regions. The Medicines and Healthcare products Regulatory Agency enforces conformity assessment procedures for digital dentistry equipment. London and Southeast England dominate management service organization formations as urban dentists seek operational relief from administrative complexity.
Australia
Private health insurance coverage gaps and geographic dentist maldistribution favor consolidated networks in coastal metropolitan zones. The Therapeutic Goods Administration oversees dental device safety standards including chairside CAD/CAM systems. New South Wales and Victoria concentrate DSO expansion where suburban population growth exceeds practice establishment rates.
Brazil
Rising middle-class dental consumption and fragmented solo practice infrastructure create acquisition opportunities for platform operators. The national health surveillance agency regulates infection control protocols that centralized networks deploy more efficiently than independent operators. São Paulo and Rio de Janeiro metropolitan regions anchor management service agreement penetration in Latin America's largest dental market.
Dental Service Organization Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue technology-intensive differentiation through digital workflow platforms. The market structures around three maturity tiers: national platform operators with thousand-plus location footprints, regional consolidators with state-level density, and specialty-focused affiliates concentrating on orthodontic or pediatric niches. Dominant competitive moves include practice acquisition velocity contests in Sun Belt corridors and proprietary technology stack development to differentiate affiliate value propositions.
Among US-based platform operators, Heartland Dental, Pacific Dental Services, and Aspen Dental Management exemplify contrasting strategic archetypes. Heartland Dental represents the procurement-scale model leveraging centralized supply chain efficiency. Pacific Dental Services occupies the technology-intensive position through proprietary digital workflow platforms. Aspen Dental Management anchors the retail-access tier with standardized fee schedules and patient acquisition scale. These three structures illustrate how operational unbundling creates distinct competitive positions without requiring clinical standardization.
| Leading Market Players |
|---|
| PDS Health |
| Dental Care Alliance |
| Heartland Dental |
| InterDent, Inc. |
| Great Expressions Dental Centers |
| Pacific Dental Services |
| Smile Brands |
| Coast Dental Services, LLC |
| Aspen Dental Management, Inc. |
| Others |
Cost & Logistics Intelligence
Clear aligner therapy substitution simultaneously compresses per-unit production costs and concentrates procurement leverage among affiliated practice networks. This technological shift redirects margin capture from bracket manufacturers toward DSOs with centralized supply agreements, reshaping how dental service organizations negotiate volume discounts across Sun Belt metropolitan corridors.
Pricing Analysis
Retailer markup layers dominate dental service pricing, with DSOs extracting procurement scale advantages through centralized supply contracts that solo operators cannot replicate. Three-tier pricing structure across premium, standard, and economy levels separates technology-intensive clear aligner platforms from traditional bracket systems and basic preventive services. Cost compression in standard preventive tiers is intensifying because reimbursement rate stagnation meets rising OSHA compliance documentation requirements. Unaffiliated solo practices exhibit highest price sensitivity, lacking volume leverage to offset regulatory overhead absorption.
Supply Chain Analysis
Dual-sourcing requirements for intraoral scanners and 3D-printed surgical guide materials mandate multi-supplier qualification across DSO procurement departments. Manufacturing concentration centers on Germany for precision optical components, China for consumable aligner materials, and the United States for FDA-cleared digital workflow software. Raw material dependencies span medical-grade polymers, titanium implant substrates, and sterilization-grade packaging films. Single-source vulnerability persists for proprietary clear aligner thermoforming resins protected by patent estates. Distribution runs through regional dental supply distributors with direct-to-practice logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with OSHA bloodborne pathogen protocol updates driving demand for centralized compliance infrastructure that solo operators cannot sustain independently.
For Market Incumbents: Acquire dental therapist staffing capabilities before scope-of-practice liberalization variance resolves across target states. Consolidate revenue cycle management platforms to defend against fintech-enabled billing disruptors entering the patient financing layer. Capacity addition in Texas and Florida urban corridors captures demographic pull effects before competitor saturation. For New Entrants and Emerging Players: Cloud-native practice management platforms offer the most penetrable wedge for technology-first market entry. White-space targets include rural community clinic partnerships in dentist supply-gap regions and subscription-based compliance-as-a-service for remaining solo operators. Direct-to-dentist SaaS sales bypasses incumbent DSO procurement gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional consolidators with state-level density but sub-scale technology infrastructure. Long-term viability hinges on management service agreement penetration displacing pure group practice structures. Watch dental therapist licensing velocity in Texas and Florida as inflection indicator for workforce economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Management Service Agreement Expansion | Preserves dentist equity retention while capturing procurement scale across Sun Belt networks. |
| Revenue Cycle Management Outsourcing | Addresses accounts-receivable bottlenecks for high-deductible plan holders in metropolitan Texas corridors. |
| 3D-Printed Surgical Guide Integration | Compresses implant restoration turnaround times through centralized lab services and digital workflow convergence. |
| Dental Therapist Scope Expansion | Reshapes workforce economics in jurisdictions where state boards liberalize supervision requirements. |
| HIPAA-Compliant IT Platform Migration | Enables legacy practice management system interoperability with DSO centralized infrastructure. |
Research Approach
Coverage spans the United States, Germany, the United Kingdom, Australia, and Brazil, with primary inputs from each regional cluster. The research combines structured interviews with DSO operations executives, dental practice owners, state dental board administrators, and dental supply procurement managers with secondary validation from FDA device classification databases, OSHA enforcement records, state corporate practice doctrine filings, and dental graduate output statistics. Bottom-up practice-level affiliation velocity triangulates against top-down market size estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across service type, operational model, customer type, and care setting dimensions, with additional granularity for state-level regulatory cluster variations. CAGRs derive from dentist supply-demand gap analysis, affiliation timeline surveys, and technology adoption curve modeling. Forecast inputs include clear aligner therapy substitution rates and dental therapist licensing expansion trajectories.
The model holds under stable state corporate practice doctrine enforcement; deviation in California, Texas, or New York regulatory interpretation would shift affiliation velocity projections materially. Deviation in FDA digital dentistry device approval timelines or OSHA bloodborne pathogen standard updates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Periodontal Dental Service Market
Dental Services
Orthodontic Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Services Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Teledentistry Market
Dental Services
United States Dental Services Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Microdontia Treatment Market
Dental Services
US Dental Chains Market