
 Subperiosteal Dental Implants Market | 2026-2036
Subperiosteal Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Subperiosteal Dental Implants Market Analysis
Europe's MDR reclassification is restructuring the cost-of-entry calculus for subperiosteal implant manufacturers seeking CE marking. Straumann Holding leverages its Swiss manufacturing base and extensive clinical documentation to sustain premium positioning across European dental clinics. Dentsply Sirona competes through integrated digital dentistry workflows that streamline custom framework design. Osstem Implant anchors volume growth in Asia-Pacific markets with cost-optimized titanium architectures.
Subperiosteal dental implants are custom-cast metal frameworks that sit atop the jawbone beneath the periosteum, typically fabricated from surgical-grade titanium or cobalt-chrome alloys through lost-wax casting or CAD/CAM milling, and they serve patients with insufficient alveolar ridge height who cannot support endosseous fixtures. Titanium dominates material selection due to its osseointegration profile and fatigue resistance, while zirconia variants are gaining traction among metal-allergy patients seeking aesthetic anterior solutions. Dental clinics represent the primary delivery channel, though distributor networks in emerging markets are expanding access beyond major metropolitan centers.
The FDA's 510(k) clearance pathway demands biocompatibility testing under ISO 10993 standards, while Europe's MDR requires notified body oversight and post-market surveillance for implantable devices. Japan's PMDA maintains distinct pharmaceutical and medical device classifications that delay market entry without local clinical bridging studies. Stakeholders must monitor evolving reimbursement codes for custom prosthodontic procedures and digital impression technologies that could compress fabrication timelines.
Market Dynamics
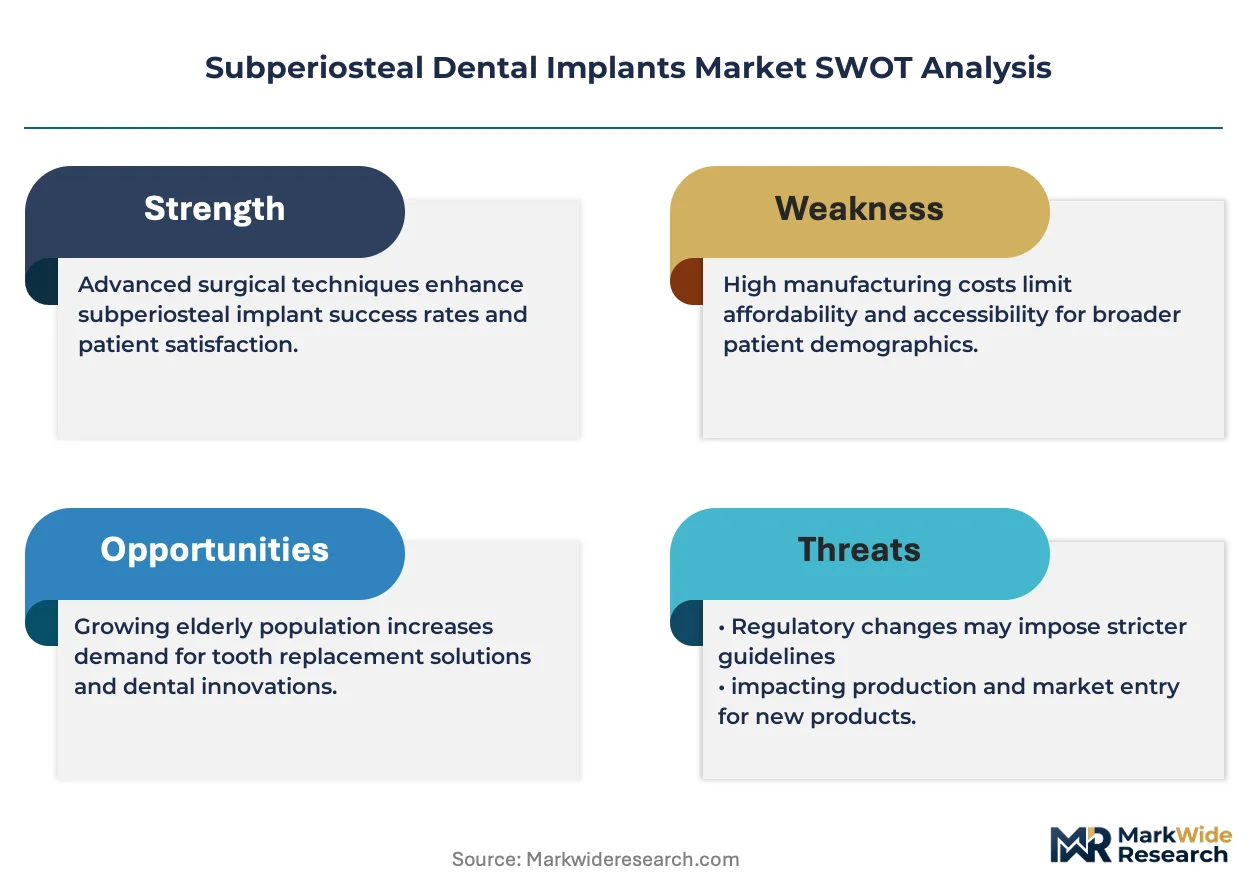
Europe's MDR reclassification is compressing the supplier base for subperiosteal implants by raising clinical documentation thresholds that smaller manufacturers cannot satisfy. This regulatory tightening concentrates production among firms with established notified body relationships and deep quality management systems.
Growth Catalysts
- Aging Demographics in Developed Markets:The United States, Germany, and South Korea face expanding cohorts of edentulous patients with severe alveolar resorption who cannot receive conventional endosseous implants.
- ISO 10993 Biocompatibility Standardization:Harmonized testing protocols streamline FDA 510(k) submissions and CE marking applications, reducing time-to-market for validated titanium and cobalt-chrome frameworks.
- CAD/CAM Digital Workflows:Intraoral scanning and subtractive manufacturing compress custom framework fabrication from weeks to days, enabling same-visit surgical planning in high-volume oral surgery clinics.
Market Restraints
- Titanium Price Volatility:Surgical-grade titanium sponge supply concentrates among a limited set of metallurgical processors, exposing implant fabricators to input cost swings.
- Specialist Workforce Bottlenecks:Maxillofacial prosthodontists and oral surgeons with subperiosteal placement expertise cluster in major metropolitan centers, constraining rural and secondary market penetration.
- Endosseous Implant Substitution:Zygomatic and pterygoid fixtures offer alternative solutions for severe atrophy, diverting patient volume from custom subperiosteal frameworks.
Strategic Opportunities
- India's Underpenetrated Tier-2 Cities:Rising disposable incomes and expanding private dental hospital chains create first-mover potential for subperiosteal specialists beyond Mumbai and Delhi.
- Japan's PMDA Reimbursement Pathway:Recent procedural code expansions for custom implant frameworks reduce out-of-pocket burden for elderly patients with mandibular atrophy.
- Tele-dentistry Integration:Remote consultation platforms connect rural patients with urban surgical centers, enabling pre-operative screening and digital impression capture without travel.
Industry Challenges
- Notified Body Capacity Constraints:Europe's MDR transition has thinned the ranks of designated conformity assessment bodies, extending CE marking timelines for novel implant designs.
- Periosteal Dissection Skill Requirements:Subperiosteal placement demands precise soft-tissue management and flap design that general practitioners rarely master without dedicated fellowship training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subperiosteal Dental Implants Market |
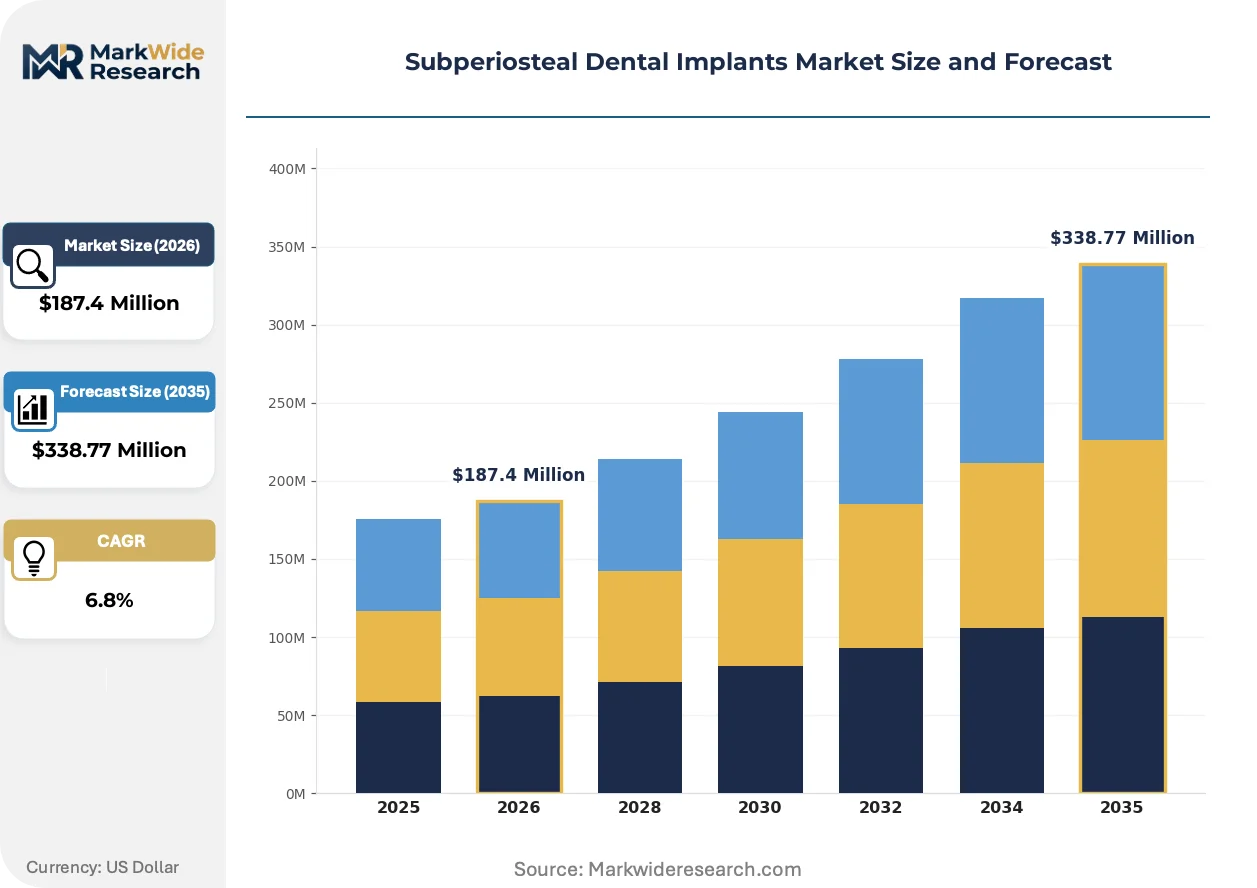
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Implants, Mini Implants, Tapered Implants, Zygomatic Implants Material: Titanium, Zirconia, Polymer, Ceramic End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Delivery Mode: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Straumann Holding, Dentsply Sirona, AVINENT Implant System, Osstem Implant, Nobel Biocare, AB Dental Devices, Zimmer Biomet, BioHorizons, BoneEasy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subperiosteal Dental Implants Market Emerging Trajectories
Digital manufacturing and regulatory harmonization are converging to reshape how custom subperiosteal frameworks reach patients. Three developments are compressing production cycles and redrawing competitive boundaries.
Zirconia-ceramic hybrid architectures are expanding into anterior aesthetic applications where metal allergy concerns and gingival display drive material selection. Seoul-based prosthodontic clinics now specify zirconia frameworks for maxillary cases with thin mucosal biotypes. This material diversification is expanding into patient segments previously excluded from titanium-dominant protocols.
The FDA's 510(k) third-party review pilot is accelerating clearance timelines for established titanium alloy formulations with predicate device histories. Manufacturers with robust quality systems can now secure market authorization through accredited third parties rather than direct FDA submission. Small-to-mid-sized fabricators in the United States are responding by consolidating predicate documentation and streamlining biocompatibility dossiers.
Direct-to-clinic digital portals are displacing traditional dental laboratory intermediaries in custom framework procurement. Oral surgery groups in Germany now upload CBCT datasets and intraoral scans to manufacturer-hosted platforms, receiving milled frameworks without laboratory markup. This channel compression is most visible in high-volume metropolitan practices with in-house CAD/CAM capabilities.
Subperiosteal Dental Implants Market Segmentation
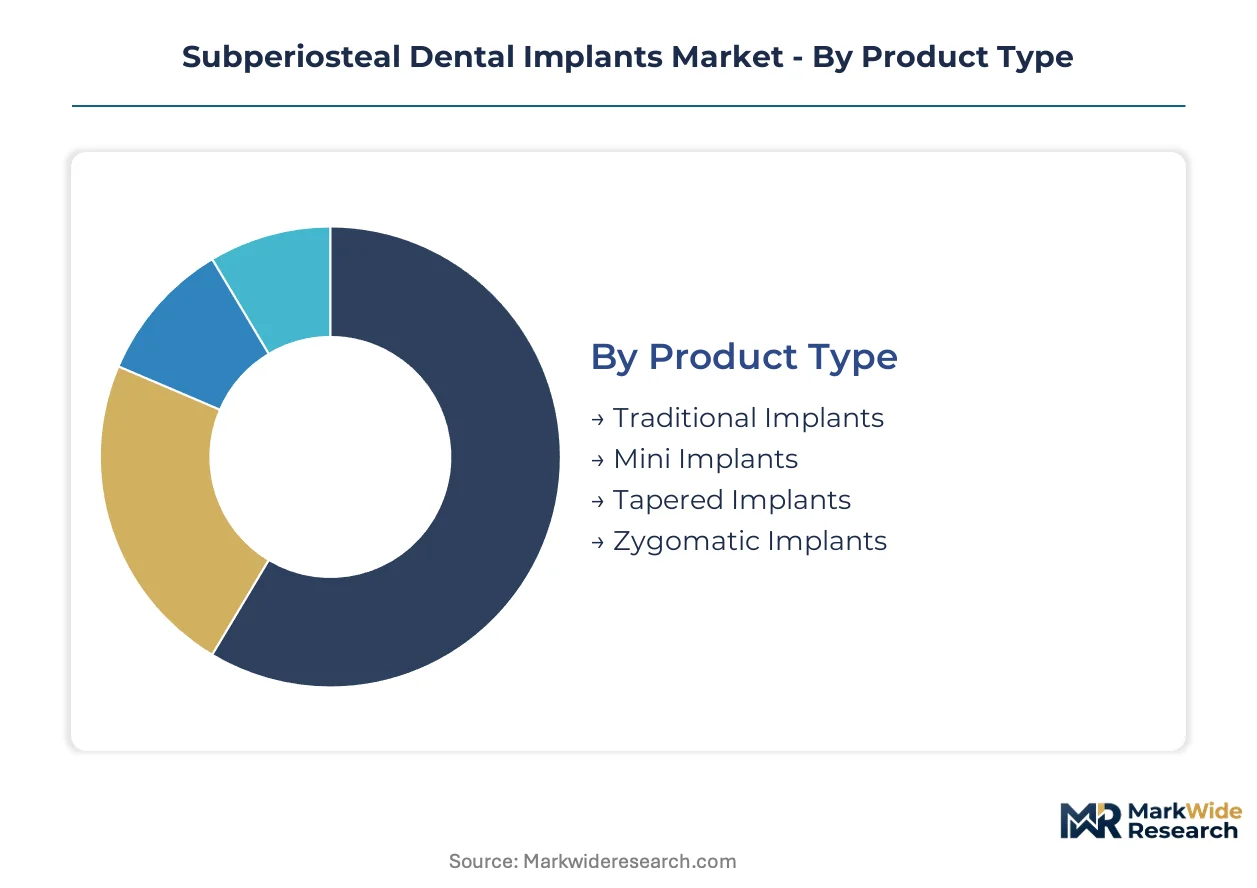
Subperiosteal implant segmentation reflects divergent clinical workflows across developed and emerging markets. Product architecture, material biocompatibility, and procurement channel each determine patient eligibility, reimbursement pathways, and manufacturer margin structure.
Product Type:
Customization intensity varies sharply across this category, from fully patient-specific cast frameworks to semi-standardized mini variants.
- Traditional Implants:Custom-cast cobalt-chrome or titanium frameworks fabricated through lost-wax casting from individual bone impressions. Demand concentrates in United States and German oral surgery centers serving edentulous patients with severe mandibular atrophy who lack sufficient ridge height for endosseous fixtures.
- Mini Implants:Reduced-diameter frameworks for narrow alveolar ridges or interim prosthodontic stabilization. South Korean prosthodontic clinics specify these for elderly patients seeking accelerated treatment timelines without bone grafting protocols.
- Tapered Implants:Anatomically contoured designs for posterior mandibular segments with sloping bone topography.
- Zygomatic Implants:Extended-length fixtures engaging the zygomatic buttress for maxillary atrophy cases.
Leading the category by volume: Traditional Implants. Growing fastest: Mini Implants.
Material:
Cost tiers stratify sharply between commodity titanium feedstock and premium ceramic alternatives.
- Titanium:Surgical-grade Ti-6Al-4V ELI dominates fabrication due to fatigue resistance and established osseointegration data. United States manufacturers leverage ISO 10993 standardized testing to streamline FDA 510(k) submissions for titanium frameworks.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) frameworks for metal-allergic patients and high-aesthetic anterior cases. Seoul and Tokyo prosthodontic clinics specify zirconia for maxillary placements with thin mucosal biotypes.
- Polymer:PEEK and PMMA provisional frameworks for diagnostic wax-ups and surgical stents.
- Ceramic:Alumina-reinforced compositions for specialized biocompatibility requirements.
Titanium commands the greatest volume share. Zirconia is expanding most quickly among aesthetic-focused practices.
End User:
Customer type determines technical support intensity and regulatory documentation burden.
- Dental Clinics:Private oral surgery and prosthodontic practices performing custom impression capture and surgical placement. German metropolitan clinics integrate CAD/CAM workflows to compress fabrication timelines from weeks to days.
- Hospitals:Academic medical centers and private hospital chains managing complex maxillofacial reconstruction cases. South Korean university hospitals anchor demand for zygomatic and traditional framework combinations.
- Research Institutions:Universities and teaching hospitals conducting clinical trials on novel materials.
- Laboratories:Independent dental laboratories serving as intermediaries for framework fabrication.
Dental clinics generate the highest procedure volume. Hospital-based placement is climbing the fastest as complex cases consolidate into tertiary centers.
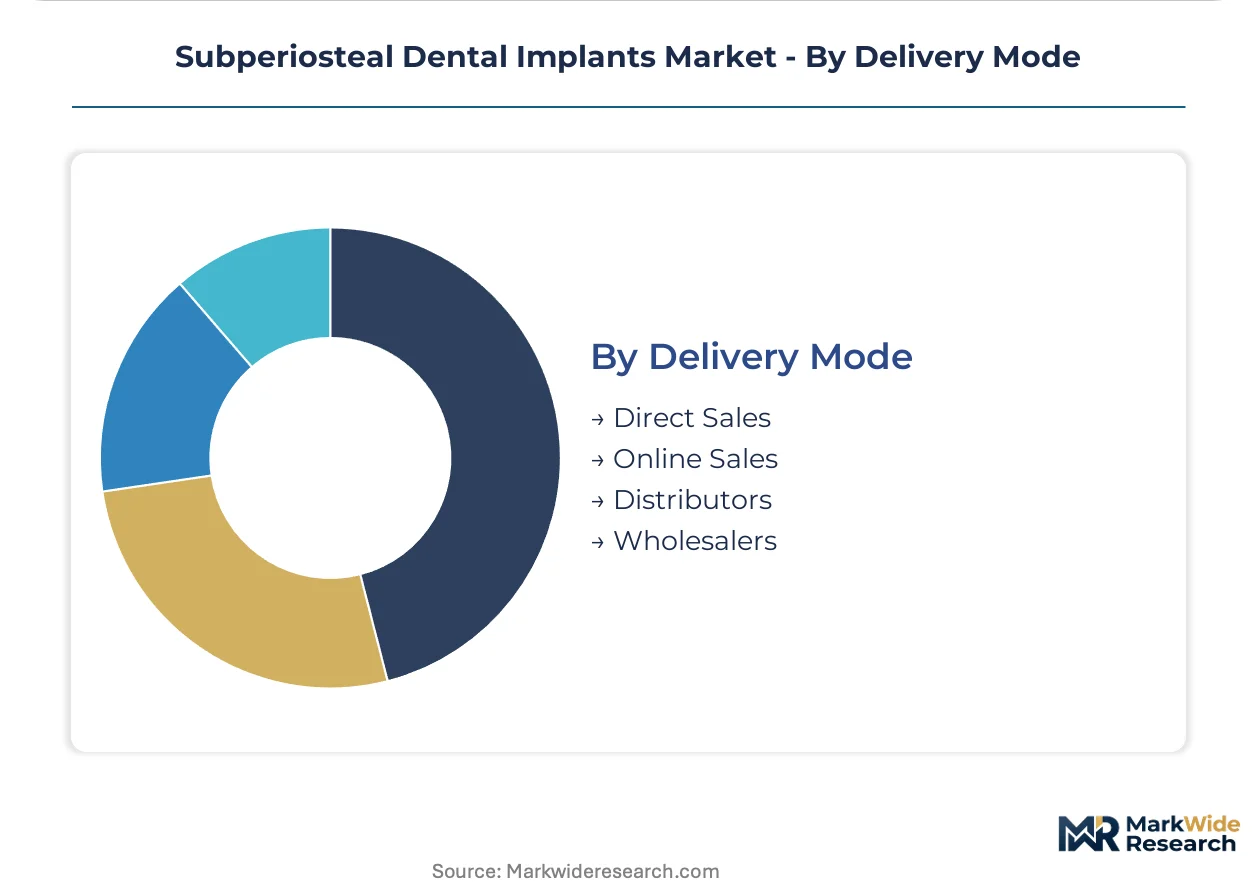
Delivery Mode:
Channel structure is displacing traditional laboratory intermediaries in high-volume markets.
- Direct Sales:Manufacturer-to-clinic relationships enabling digital portal submission of CBCT datasets and intraoral scans. German oral surgery groups leverage direct channels to eliminate laboratory markup on custom frameworks.
- Distributors:Regional medical device distributors with sterilization logistics and local regulatory compliance support. India's tier-2 city expansion relies on distributor networks beyond Mumbai and Delhi.
- Online Sales:E-procurement platforms for standardized components and consumables.
- Wholesalers:Bulk procurement intermediaries serving multi-site clinic chains.
Direct sales dominate revenue concentration. Distributor channels are gaining share fastest in underpenetrated emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in South Korea's Incheon and Busan districts concentrate titanium processing capacity for dental implant fabricators serving the Asia-Pacific corridor.
United States
Oral surgery clinics in metropolitan corridors drive demand for custom-cast frameworks among edentulous patients with severe mandibular atrophy. The FDA's 510(k) clearance pathway under ISO 10993 standards streamlines biocompatibility documentation for titanium alloy submissions. Boston and Los Angeles surgical centers anchor adoption of CAD/CAM-enabled direct-to-clinic procurement models.
Germany
Prosthodontic practices in urban clusters specify subperiosteal frameworks for patients failing bone graft eligibility criteria. Europe's MDR reclassification tightens notified body oversight and post-market surveillance requirements for implantable devices. Munich and Hamburg oral surgery groups integrate digital portals to compress fabrication timelines from laboratory-mediated workflows.
South Korea
Aging demographics in Seoul and Busan expand the addressable pool of patients with insufficient alveolar ridge height for endosseous fixtures. The MFDS maintains distinct pharmaceutical and medical device classifications that shape market entry protocols for custom frameworks. Seoul Capital Area prosthodontic clinics specify mini implant variants for accelerated treatment timelines without grafting protocols.
Japan
University hospitals in Tokyo and Osaka anchor demand for complex maxillofacial reconstruction combining traditional and zygomatic framework approaches. The PMDA's reimbursement pathway expansions for custom implant procedures reduce out-of-pocket burden for elderly patients with mandibular atrophy. Kanto region teaching hospitals conduct clinical bridging studies required for novel material introductions.
India
Private dental hospital chains in tier-2 cities beyond Mumbai and Delhi create first-mover potential for subperiosteal specialists. The CDSCO regulates implantable devices under medical device rules that require local clinical data for Class C and D approvals. Gujarat and Karnataka distributor networks expand access beyond metropolitan surgical centers into secondary markets.
Subperiosteal Dental Implants Market Vendor Landscape
Swiss and German producers anchor the premium-documentation tier; South Korean specialists hold volume-optimized positions in Asia-Pacific markets. The supplier base concentrates among firms with established notified body relationships and deep quality management systems capable of satisfying MDR clinical documentation thresholds. Three archetypes dominate: integrated dental technology conglomerates with digital workflow platforms, pure-play implant manufacturers with metallurgical expertise, and regional specialists with cost-optimized titanium architectures. Competitive moves center on direct-to-clinic channel compression and predicate device consolidation for accelerated regulatory submissions.
Among Switzerland-based holding companies, Straumann Holding exemplifies the premium-tier archetype built on extensive clinical documentation and Swiss manufacturing heritage. Dentsply Sirona occupies a position representing integrated digital dentistry workflows that streamline custom framework design. Osstem Implant anchors the volume-driven segment with cost-optimized architectures for Asia-Pacific market penetration.
| Leading Market Players |
|---|
| Straumann Holding |
| Dentsply Sirona |
| AVINENT Implant System |
| Osstem Implant |
| Nobel Biocare |
| AB Dental Devices |
| Zimmer Biomet |
| BioHorizons |
| BoneEasy |
| Others |
Supply Flow & Price Mechanics
Digital portal procurement preferences among German oral surgery groups are compressing laboratory intermediaries and forcing manufacturers to absorb direct-to-clinic fulfillment costs, which compresses margins on titanium frameworks while rewarding players with in-house CAD/CAM capabilities.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation in subperiosteal implant procurement, with same-week milled frameworks commanding substantial markups over standard four-week cast deliveries. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-manufactured titanium with full MDR documentation from South Korean volume offerings and Indian distributor-channel imports. Pricing pressure stems from titanium sponge cost volatility concentrated among limited metallurgical processors. Hospital-based oral surgery centers exhibit lowest price sensitivity due to bundled reimbursement codes, while independent rural clinics face acute cost compression.
Supply Chain Analysis
Reverse-logistics flows for subperiosteal implants remain minimal given the permanent implantable nature of frameworks, though explant material recovery programs in Switzerland and Germany are emerging for titanium recycling. Supply concentrates in Switzerland, South Korea, and the United States for precision-milled frameworks, while lost-wax casting capacity clusters in Germany and Japan. Raw material dependencies center on surgical-grade titanium sponge from Ukrainian and Russian feedstock processors, cobalt-chrome alloys from German metallurgical specialists, and yttria-stabilized zirconia from Japanese ceramic manufacturers. Single-source vulnerability in titanium sponge supply creates structural risk. Distribution runs through direct manufacturer-to-clinic portals in developed markets and regional medical device distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as Europe's MDR reclassification raises clinical documentation thresholds that eliminate smaller manufacturers lacking notified body relationships.
For Market Incumbents: Deploy predicate device consolidation to accelerate FDA 510(k) submissions and compress regulatory timelines against emerging zygomatic implant substitutes. Deepen backward integration into titanium sponge sourcing to offset metallurgical processor concentration risk. Strengthen direct-to-clinic digital portals to capture laboratory margin compression in German and United States metropolitan markets. For New Entrants and Emerging Players: India's tier-2 private dental hospital chains represent the most penetrable white-space target, with Gujarat and Karnataka distributor networks enabling access beyond saturated Mumbai-Delhi corridors. Cost-optimized mini implant variants for accelerated treatment timelines offer entry wedge against premium-tier incumbents. Tele-dentistry integration with urban surgical centers enables remote pre-operative screening without capital-intensive clinic footprint. For Investors and Strategic Acquirers: The window for entry favors mid-cap manufacturers with established ISO 10993 testing dossiers and notified body relationships capable of satisfying MDR clinical documentation thresholds. Acquisition targets should demonstrate captive titanium alloy formulation expertise or CAD/CAM workflow integration. Monitor notified body capacity expansion announcements as inflection indicator for CE marking timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR reclassification demands expanded clinical documentation for implantable device categories. |
| Hospital System Partnership | South Korean university hospitals anchor demand for complex zygomatic-traditional framework combinations. |
| Software Companion Development | Direct-to-clinic digital portals displace laboratory intermediaries in German metropolitan procurement. |
| Reimbursement Strategy | Japan's PMDA procedural code expansions reduce out-of-pocket burden for elderly mandibular atrophy patients. |
| Backward Integration | In-house titanium sponge sourcing mitigates single-processor concentration risk in metallurgical supply. |
Methodological Framework
FDA 510(k) filings, MFDS medical device registrations, and ISO 10993 biocompatibility testing records formed the secondary backbone for this analysis. Primary interviews with maxillofacial prosthodontists, oral surgeons, dental laboratory technicians, and medical device regulatory consultants complemented secondary validation. Bottom-up procedure volume estimates from United States, German, and South Korean oral surgery clinics were triangulated against top-down manufacturer shipment data across the analysis window.
Historical trendline analysis of subperiosteal implant procedure volumes informed the forecast framework, with segmentation across product type, material composition, end-user channel, and delivery mode. CAGRs were derived from regression analysis of annual procedure growth rates coupled with average selling price trajectories. Industry-specific inputs included titanium sponge price indices, notified body capacity utilization rates, and digital dentistry adoption curves in target markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR notified body capacity constraints, titanium supply disruption events, and endosseous implant technological substitution. Practitioners should monitor regulatory clearance timeline announcements, metallurgical processor consolidation activity, and CAD/CAM workflow penetration rates in tier-2 emerging markets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Delivery System Market
Dental Devices
Dental Braces Market
Dental Devices
Dental Calipers Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Dam Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Root Canal Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Restoration Market
Dental Devices
Orthodontics Market