
 Acrylic Teeth Market | 2026-2036
Acrylic Teeth Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Teeth Market Intelligence
The rise of asset-light models for dental laboratories, facilitated by digital design services and outsourced manufacturing, is reshaping competitive positioning. This shift allows smaller clinics to offer advanced prosthodontics without major capital outlay. In this environment, Dentsply Sirona leverages its extensive global distribution network and brand recognition. Meanwhile, Ivoclar Vivadent differentiates through its dedicated focus on high-impact acrylic materials and integrated digital workflows.
Acrylic teeth are prosthetic components fabricated from polymethyl methacrylate (PMMA) resins, often with cross-linking agents to enhance durability. Their primary purpose is to replace natural teeth in dentures, restoring oral function and aesthetics. While complete dentures represent the largest application, demand for partial dentures is accelerating. High-impact acrylics command a premium over conventional types due to superior fracture resistance, a key differentiator for dental laboratories.
Market access is governed by stringent medical device regulations, including clearance from the US FDA and CE marking under the EU's Medical Device Regulation (MDR). In China, products must comply with standards set by the National Medical Products Administration (NMPA), which impacts material composition protocols. Manufacturers must now decide whether to prioritize investments in advanced polymer science or in digital fabrication compatibility to secure future market share.
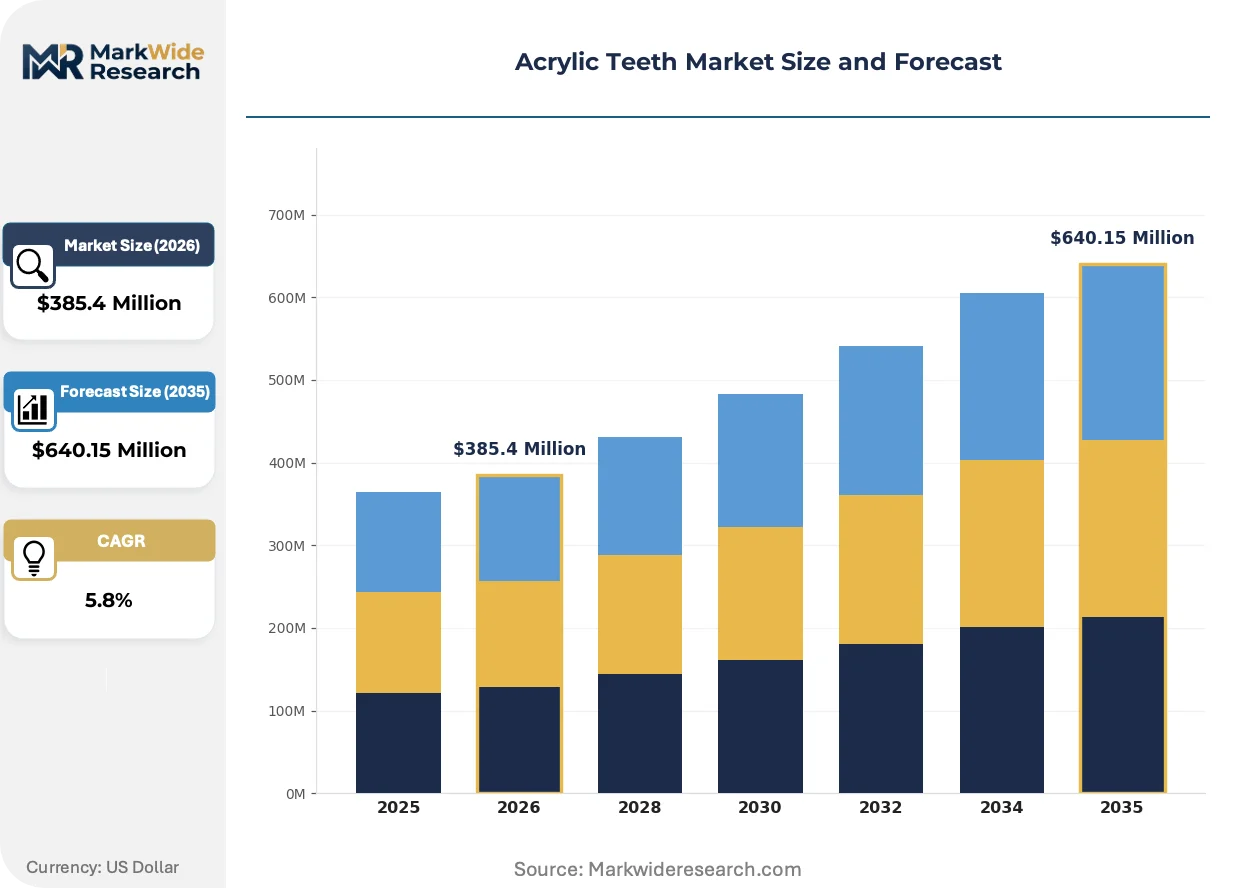
Market Dynamics
The central force shaping the acrylic teeth market is the rapid digitalization of dental laboratory workflows. This shift, driven by the availability of outsourced CAD design services and centralized manufacturing, enables even small clinics to compete without significant capital investment in fabrication equipment.
Growth Catalysts
- High-Impact Material Science:The development of advanced polymethyl methacrylate (PMMA) formulations with cross-linking agents enhances fracture resistance. This technical benefit is a strong pull for dental laboratories seeking to reduce denture failure rates and offer premium products.
- Demographic Shifts in China:A rapidly aging population combined with expanding public and private dental insurance coverage in China creates a concentrated zone of demand. This supports volume growth for both complete and partial dentures.
- Regulatory Up-Classification:The European Union's Medical Device Regulation (MDR) is compelling a move towards higher-purity, well-documented materials. This creates a catalyst for premium acrylics that can meet the stricter evidence requirements for CE marking.
Market Restraints
- Input Cost Volatility:The price of polymethyl methacrylate (PMMA) resins, the primary raw material, is subject to fluctuations in petrochemical feedstock markets. These cost shifts can compress profit margins for manufacturers who are unable to pass increases on to laboratories.
- Threat of Material Substitution:Monolithic zirconia and other advanced ceramic materials present a significant substitution threat, particularly in the high-end, full-arch implant-retained denture segment. These alternatives offer different aesthetic and long-term wear characteristics that appeal to certain patient groups.
- Regulatory Entry Barriers:Gaining market access requires navigating stringent and lengthy approval processes. Compliance with standards from the US FDA, the EU's MDR, and China's NMPA creates significant time and cost barriers for new entrants and new product introductions.
Strategic Opportunities
- Partial Denture Applications:While complete dentures form the market's base, accelerating demand for partial dentures represents a significant growth opportunity. This requires the development of specialized teeth with unique clasps and shades to integrate with remaining natural dentition.
- Digital Fabrication Materials:There is a growing opportunity to develop PMMA resins and pucks specifically optimized for 3D printing and CAD/CAM milling. Materials that offer faster printing speeds, easier milling, and superior post-processing finish can command a premium.
- Direct-to-Laboratory Digital Platforms:Creating online platforms that allow dental labs to directly order custom-designed or standard teeth, bypassing traditional distributors, presents a channel innovation opportunity. This model can improve efficiency and reduce costs for tech-savvy laboratories.
Industry Challenges
- Digital Skills Gap:A primary operational challenge is the shortage of dental technicians proficient in CAD software and digital workflow management. The transition from traditional manual waxing and casting to a fully digital process requires significant training and investment in new skills.
- Continuous Compliance Burden:Adhering to the evolving requirements of regulations like the EU's MDR is a persistent challenge. Manufacturers must continually invest in clinical data collection, post-market surveillance, and documentation to maintain their certifications for existing products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Teeth Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Acrylic, High Impact Acrylic, Modified Acrylic, Injection Molded Acrylic Application: Complete Dentures, Partial Dentures, Dental Implants, Orthodontic Appliances, Prosthodontics End User: Dental Laboratories, Dental Clinics, Hospitals, Educational Institutions Material Grade: Medical Grade, Industrial Grade, Cosmetic Grade, Dental Grade, Food Grade |
| Companies Covered | Heraeus Kulzer, New Stetic, Dentsply Sirona, SHOFU Dental, YAMAHACHI DENTAL, Ivoclar Vivadent, Shandong Huge Dental Material Corporation, Merz-Dental, Vita Zahnfabrik H. Rauter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Teeth Market Strategic Shifts & Innovations
Material science and digital workflows are converging to redefine fabrication standards. This integration moves beyond simple automation, fundamentally altering how material properties are selected and leveraged within prosthetic manufacturing.
Digital scanning and CAD software create precise virtual models for prosthetics. Dental laboratories are rapidly adopting these tools to improve accuracy and reduce turnaround times. This integration with automated milling or 3D printing is collapsing the time and manual labor required for prosthetic fabrication.
The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance mandates. This requires manufacturers to invest more in the traceability and biocompatibility testing of PMMA resins. High-impact acrylics are most affected, as suppliers must provide extensive data to justify their premium classification and maintain CE marking.
A shift towards asset-light business models is evident among dental laboratories. Instead of large capital outlays for in-house milling machines, smaller labs now outsource fabrication to centralized production hubs. This trend is most prominent in North America and Europe, where specialized digital service providers cater to a fragmented network of clinics.
Acrylic Teeth Market Segmentation
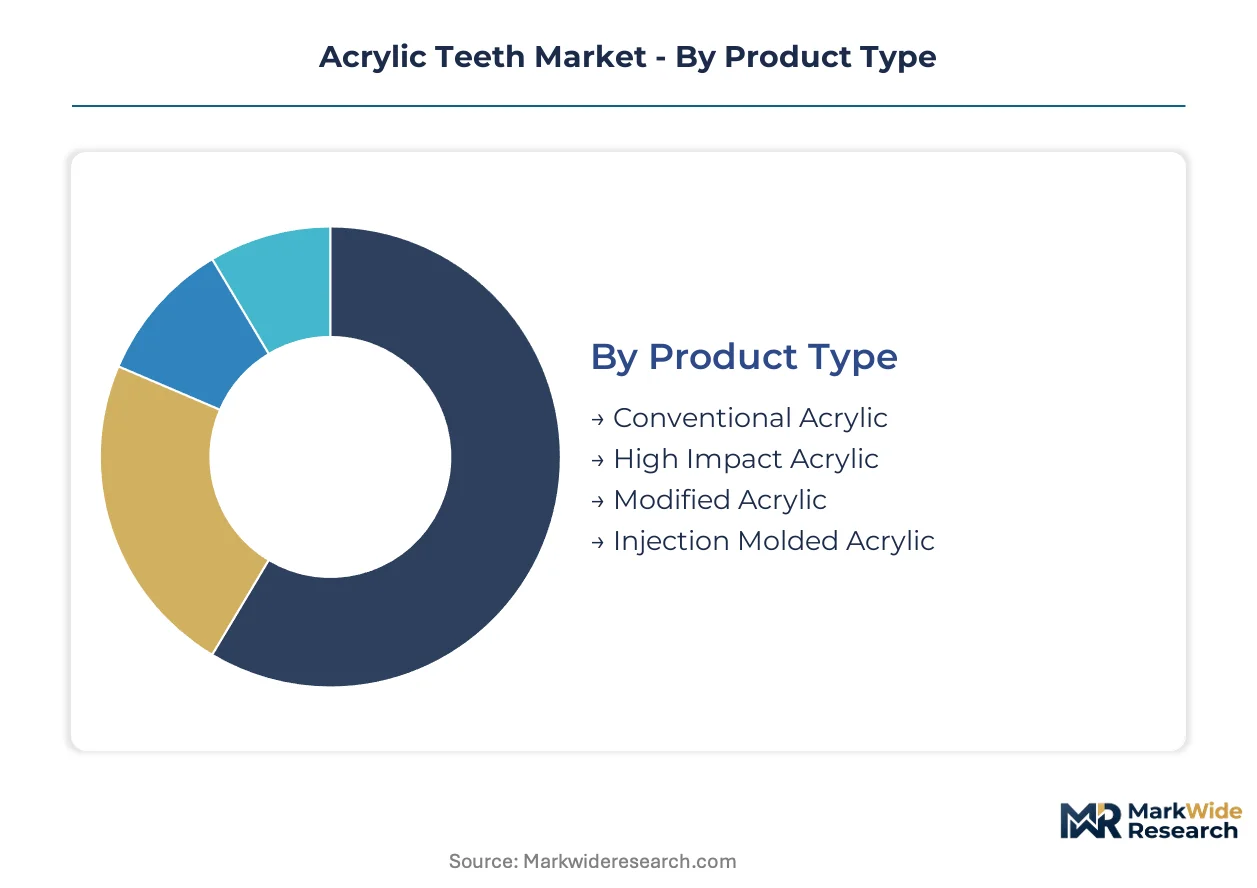
The acrylic teeth market segments based on distinct material properties, end-use applications, and regulatory classifications. Understanding these divisions is crucial for manufacturers to align product development with specific functional requirements and market demands.
Product Type:
The spectrum of product types in the acrylic teeth market reflects diverse functional demands and aesthetic requirements across prosthetic applications.
- High Impact Acrylic:These materials are polymethyl methacrylate (PMMA) resins enhanced with cross-linking agents, delivering superior fracture resistance. Demand concentrates in Europe, where dental laboratories prioritize durability to meet stricter patient expectations and reduce failure rates.
- Conventional Acrylic:Composed primarily of basic PMMA resin, this type offers a cost-effective and widely adopted solution for dental prosthetics. China drives significant demand for conventional acrylics, supporting high-volume production for complete dentures.
- Modified Acrylic:These acrylics incorporate additives to achieve enhanced properties such as improved wear resistance, color stability, or reduced plaque adhesion, addressing specific patient needs.
- Injection Molded Acrylic:Fabricated using injection molding techniques, these products offer exceptional fit accuracy and reduced post-processing, supporting advanced digital fabrication workflows in specialized laboratories.
Established volume favors Conventional Acrylic; emerging adoption favors High Impact Acrylic.
Application:
Application diversity dictates specific material formulations and design considerations for acrylic teeth across various dental procedures.
- Complete Dentures:These prosthetics replace an entire arch of missing teeth, restoring comprehensive mastication and facial aesthetics for edentulous patients. Demand for complete dentures is particularly strong in China, driven by its large aging population and expanding dental access.
- Partial Dentures:Partial dentures replace one or more missing teeth while integrating with remaining natural dentition, often requiring customized clasps and precise shade matching. Accelerating demand in North America and Europe requires specialized teeth designed for seamless integration.
- Dental Implants:Acrylic teeth are utilized as an aesthetic and functional overlay for implant-supported prostheses, providing a fixed or removable restoration anchored by dental implants.
- Orthodontic Appliances:Certain orthodontic devices, such as removable retainers or functional appliances, incorporate acrylic teeth components that require specific flexibility and biocompatibility.
- Prosthodontics:This broad category encompasses various restorative dental treatments, including temporary crowns, bridges, and other custom-fabricated devices utilizing acrylic materials.
Complete dentures remain the primary volume driver, while partial dentures exhibit the steepest expansion trajectory.
End User:
The end-user landscape for acrylic teeth reflects distinct operational scales and procurement patterns across the dental healthcare ecosystem.
- Dental Laboratories:These specialized facilities fabricate custom dental prosthetics from raw materials, often utilizing digital design and manufacturing processes. Demand from dental laboratories in Europe and North America is shaped by the trend towards outsourced digital services.
- Dental Clinics:Dental clinics provide direct patient care, assessing needs and ordering either pre-fabricated or custom-designed acrylic prosthetics from laboratories. Expanding access to dental services in China significantly increases demand from dental clinics.
- Hospitals:Dental departments within larger medical institutions handle complex oral rehabilitation cases, often requiring specialized acrylic teeth for multi-disciplinary treatments.
- Educational Institutions:Dental schools and training centers use acrylic teeth for teaching prosthetic fabrication techniques, material science, and restorative dentistry to students.
Dental laboratories exert significant market influence through fabrication expertise, while dental clinics represent a critical point of patient access.
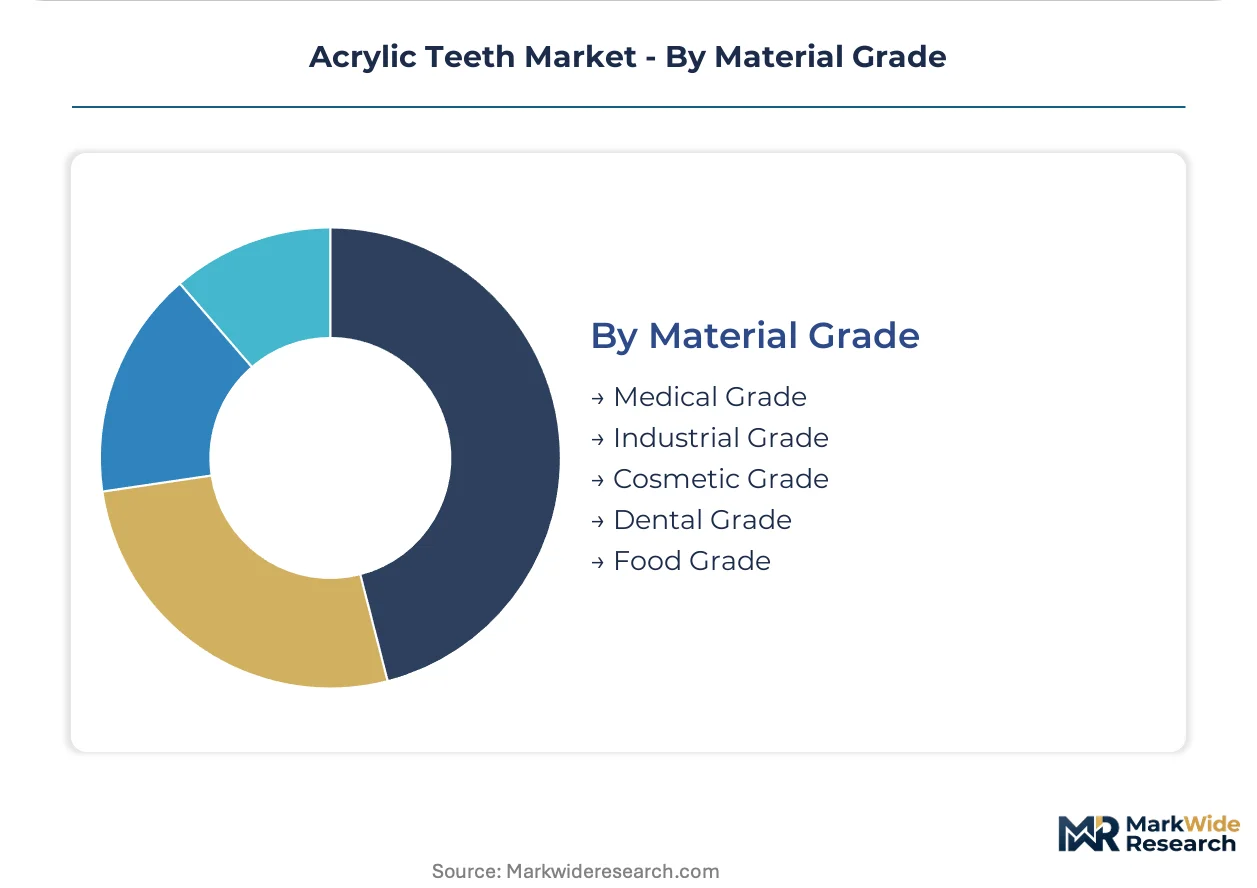
Material Grade:
Material grade classifications are primarily driven by regulatory compliance and performance specifications for patient safety and product longevity.
- Medical Grade:These acrylics are biocompatible and undergo rigorous testing to meet stringent medical device standards for implantable or mucosal-contact applications. Demand for medical grade materials is high in the European Union, compelled by MDR requirements for purity and traceability.
- Dental Grade:Specifically formulated for oral applications, dental grade acrylics balance aesthetic properties with mechanical durability and biocompatibility. The United States market adheres to FDA clearance protocols for these prosthetic materials.
- Industrial Grade:Industrial grade PMMA is used for non-medical applications and adheres to lower purity and biocompatibility standards compared to dental or medical grades.
- Cosmetic Grade:This grade is employed in non-implantable aesthetic dental devices where appearance is the primary concern, such as temporary veneers or custom trays.
- Food Grade:Food grade PMMA is certified for contact with food products and is not directly used in the fabrication of acrylic teeth for oral prosthetics.
Medical Grade materials face the most rigorous regulatory scrutiny, influencing product development across all other grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global acrylic teeth market exhibits varied export-import dynamics, influenced by regional manufacturing capabilities and specific regulatory requirements. Countries with established dental industries often balance domestic production with specialized imports, while emerging markets prioritize volume. This balance dictates material flow and product availability across key geographies.
United States
The United States experiences strong demand for partial dentures and advanced prosthodontics. US FDA clearance protocols stringently shape material specifications and market access for all acrylic teeth. Dental laboratories in California and New York increasingly adopt digital design services for custom prosthetic fabrication. This shift supports specialized product offerings and efficient workflow management.
Germany
Germany prioritizes high-impact acrylics, seeking enhanced durability and superior patient satisfaction. The EU's Medical Device Regulation (MDR) compels manufacturers towards higher-purity, well-documented materials for CE marking. Dental manufacturing hubs around Stuttgart and Munich focus on integrated digital workflows for advanced prosthetics. This concentration drives material science innovation within the European market.
China
China's aging population and expanding dental insurance coverage drive substantial demand for complete and partial dentures. NMPA standards significantly impact material composition protocols and domestic market entry for all acrylic teeth products. Manufacturing centers in the Yangtze River Delta support high-volume production of conventional acrylics for broad distribution. This region is a central force in global acrylic teeth supply.
Japan
Japan's aging demographic seeks advanced aesthetic and functional solutions in dental prosthetics. PMDA regulations ensure product quality and safety for all dental materials, including acrylic teeth. Research institutions in Tokyo and Osaka focus on developing specialized PMMA formulations with enhanced properties. This drives innovation in wear resistance and color stability.
Brazil
Brazil's expanding middle class and public health initiatives increase access to essential dental services. ANVISA governs the registration and commercialization of dental devices, ensuring local compliance. Dental laboratories in São Paulo and Rio de Janeiro increasingly adapt digital fabrication technologies for efficient production. This supports a growing domestic market for acrylic teeth.
Acrylic Teeth Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large multinational corporations and specialized regional manufacturers. This mix creates both consolidated segments for core materials and fragmented niches for advanced solutions. Strategic archetypes include integrated solution providers offering complete digital workflows and material science specialists focused on high-impact acrylics. Dominant competitive moves involve strategic partnerships for market access and continuous investment in advanced polymer science.
Within the integrated solution provider archetype, Dentsply Sirona represents a global entity leveraging extensive distribution networks for comprehensive dental offerings. Ivoclar Vivadent, a prominent European-based manufacturer, occupies a position as a specialist in high-impact acrylic materials and integrated digital workflows. Shandong Huge Dental Material Corporation, based in China, anchors the volume-driven segment, supplying conventional acrylics to a rapidly expanding domestic market. These companies exemplify the diverse approaches to market penetration and product differentiation. Their distinct operational models address varying demands across different geographic and application segments.
| Leading Market Players |
|---|
| Heraeus Kulzer |
| New Stetic |
| Dentsply Sirona |
| SHOFU Dental |
| YAMAHACHI DENTAL |
| Ivoclar Vivadent |
| Shandong Huge Dental Material Corporation |
| Merz-Dental |
| Vita Zahnfabrik H. Rauter |
| Others |
Cost & Logistics Intelligence
Polymethyl methacrylate (PMMA) resin price volatility from petrochemical feedstock markets directly impacts profit margins for acrylic teeth manufacturers. China's high-volume conventional acrylic production also influences global pricing structures, particularly for basic materials.
Pricing Analysis
Dental laboratories anchor a tiered pricing structure for acrylic teeth. Pricing stratifies across premium, standard, and economy levels, driven by material quality grade and regulatory certification. Pricing pressure stems from input cost volatility for PMMA resins, impacting manufacturer profitability. Dental clinics procuring high-volume conventional acrylics exhibit high price sensitivity, while European laboratories prioritize premium high-impact materials for patient satisfaction.
Supply Chain Analysis
Centralized production hubs, offering outsourced manufacturing, hold significant capacity for acrylic teeth fabrication. Supply concentration for raw PMMA resins primarily rests in China and petrochemical-producing regions. The supply chain draws from specialized chemical manufacturers for cross-linking agents and other additives. Single-source vulnerability for advanced PMMA formulations represents a structural risk. Distribution runs through both traditional dental distributors and emerging direct-to-laboratory digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic teeth market exhibits early-cycle expansion, driven by the rapid digitalization of dental laboratory workflows. This shift facilitates wider adoption of advanced prosthodontics across smaller clinics.
For Market Incumbents:Entrench existing market positions by investing heavily in advanced polymer science for high-impact acrylics. Manufacturers must also expand integrated digital workflow solutions to counter the threat of material substitution from monolithic zirconia. Certification investment for EU MDR and US FDA clearance maintains market access. Leveraging global distribution networks ensures broad reach for premium products.
For New Entrants and Emerging Players:Partial denture applications represent a penetrable entry point for specialized acrylic teeth with unique clasps and shades. Developing PMMA resins optimized for 3D printing and CAD/CAM milling offers a distinct advantage in digital fabrication. A direct-to-laboratory digital platform can serve as an efficient go-to-market angle. This approach bypasses traditional distribution channels and reduces costs.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized material science firms and digital dental workflow providers. The market offers long-term viability, driven by aging global populations and expanding dental service access. Acquisition targets include companies with proprietary high-impact acrylic formulations or robust digital platform capabilities. The accelerating adoption rates of digital fabrication technologies in dental laboratories serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D Investment | Dentsply Sirona strengthens high-impact acrylics, enhancing fracture resistance for premium prosthetics. |
| Digital Workflow Integration | Ivoclar Vivadent streamlines laboratory processes, improving accuracy and reducing turnaround times for custom dentures. |
| China Market Expansion | Shandong Huge Dental Material Corporation capitalizes on China's aging population for conventional acrylic volume growth. |
| Regulatory Compliance Upgrade | European manufacturers meet MDR requirements, ensuring product traceability and biocompatibility for CE marking. |
| Direct-to-Laboratory Platform Launch | New entrants reduce distribution costs, improving efficiency for tech-savvy dental laboratories. |
Research Approach
Desk research of regulatory filings, academic journals, and industry reports preceded structured interviews with dental laboratory owners, prosthodontists, and material scientists. This approach combined primary insights with secondary validation, ensuring comprehensive data collection. Bottom-up and top-down triangulation methods reconciled disparate data points. Regulatory affairs specialists also provided critical input.
Assumptions regarding global macroeconomic stability and evolving regulatory environments were held constant across the analysis window. An analytical framework modeled segmentation dimensions including product type, application, end-user, and material grade. Compound annual growth rates were derived from historical trends and projected through quantitative modeling. Key forecast inputs included population demographics and dental insurance coverage expansion.
Practitioners should monitor geopolitical shifts and material science breakthroughs for early signals impacting market dynamics. Forecasts reflect current assumptions, but supply chain disruptions represent a risk factor. Monthly review of regulatory updates and competitive landscape changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Crown Removal Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Sealants Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
US Orthodontics Market
Dental Devices
Nano Dentistry Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Root Canal Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Global Dental Laboratory Welders Market