
 Sleep Apnea Oral Appliances Market | 2026-2036
Sleep Apnea Oral Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Apnea Oral Appliances Market Outlook
Home care settings is hardening as the fastest-expanding end-use channel for sleep apnea oral appliances, shifting volume away from traditional sleep center dependencies. SomnoMed leverages its direct-to-patient platform to capture home-based demand across multiple continents. ProSomnus Sleep Technologies anchors its competitive stance through precision-manufactured CAD/CAM devices with tight tolerances. ResMed competes by extending its respiratory ecosystem into oral appliance adjacencies.
Sleep apnea oral appliances are intraoral devices fabricated from medical-grade polymers that reposition the mandible or tongue to maintain patent upper airways during sleep, typically requiring millimeter-level adjustment precision for therapeutic efficacy. Mandibular advancement devices dominate clinical prescriptions due to established efficacy data and broad dental practitioner familiarity, while custom-fabricated appliances command premium positioning through individualized fit optimization. 3D printing is displacing conventional polypropylene molding in high-throughput laboratories, enabling same-day turnaround that reshapes patient acquisition economics.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU MDR framework imposes enhanced clinical evidence standards for CE-marked appliances entering European markets. Germany's KBA-aligned reimbursement pathways and Japan's PMDA device classifications further fragment regulatory navigation for multinational manufacturers. Stakeholders must monitor evolving dental board scope-of-practice rulings that determine whether general dentists or sleep specialists control patient funnel access.
Market Dynamics
Home care migration is compressing traditional sleep center channels as patients seek direct-to-patient delivery models and dental sleep medicine practitioners bypass hospital-based sleep study dependencies. This structural shift is redistributing volume toward laboratories with rapid-turnaround manufacturing capabilities.
Growth Catalysts
- Reimbursement code expansion:Evolving dental billing codes in the United States are unlocking payer coverage for oral appliance therapy, reducing out-of-pocket patient barriers.
- 3D printing adoption:Same-day CAD/CAM fabrication is collapsing turnaround times from weeks to hours, enabling chairside delivery models in dental practices.
- Germany:KBA-aligned reimbursement pathways and mature dental sleep medicine infrastructure are concentrating prescriber expertise and patient volume in this market.
Market Restraints
- Medical-grade polymer cost volatility:Specialized biocompatible resins face supply concentration among European chemical suppliers, creating input price instability.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance and clinical data mandates are extending CE-marking timelines and compliance expenditures.
- CPAP substitution pressure:Continuous positive airway pressure devices retain first-line insurance coverage in severe obstructive sleep apnea cases, limiting oral appliance addressable share.
Strategic Opportunities
- Japan:PMDA device classification pathways for oral appliances remain underdeveloped relative to Western markets, creating first-mover positioning for compliant entrants.
- Tele-dental integration:Remote mandibular advancement titration and digital impression capture are opening rural and underserved patient populations.
- ISO 13485 convergence:Harmonized quality management standards across regulatory zones are enabling single-audit compliance for multi-market launches.
Industry Challenges
- Dental sleep medicine certification gaps:Limited accredited training programs restrict prescriber pool expansion and create geographic access inequities.
- FDA 510(k) predicate device dependencies:Substantial equivalence pathways require careful predicate selection, with clearance delays when novel mechanisms lack established comparators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Apnea Oral Appliances Market |
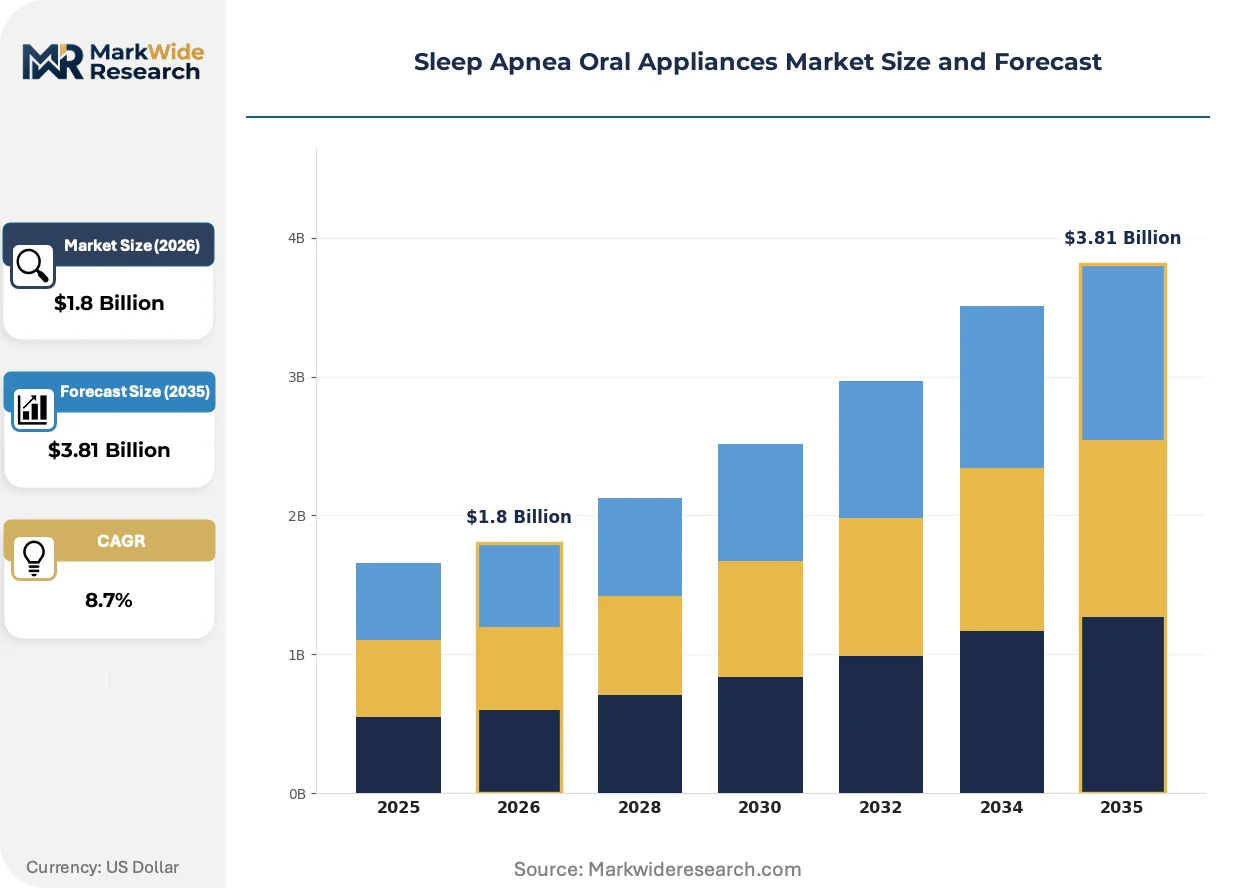
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Advancement Device, Tongue Stabilizing Device, Custom-Fabricated Appliance, Adjustable Appliance End User: Hospitals, Dental Clinics, Home Care, Sleep Centers Technology: 3D Printing, CAD/CAM, Polypropylene Molding, Silicone Distribution Channel: Direct Sales, Online Retail, Wholesale, Dental Distributors |
| Companies Covered | DynaFlex, Airway Management, SomnoMed, Whole You, Panthera Dental, ResMed, Vivos Therapeutics, Apnea Sciences, ProSomnus Sleep Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Apnea Oral Appliances Market Strategic Shifts
Digital workflow integration is collapsing traditional laboratory-to-clinic handoffs as intraoral scanning and cloud-based design platforms enable real-time appliance customization. This technological convergence is compressing patient acquisition cycles and reshaping competitive differentiation.
Multi-material 3D printing is rewriting fabrication economics for mandibular advancement devices. Dental laboratories across the United States and Germany are deploying photopolymer jetting systems capable of producing dual-durometer appliances with integrated soft liners in single builds. This capability is enabling mass customization at unit costs approaching conventional polypropylene molding.
The EU MDR framework is tightening clinical evidence requirements for CE-marked sleep apnea oral appliances entering European markets. Manufacturers must now maintain post-market surveillance systems and periodic safety update reports that exceed previous Medical Device Directive obligations. German notified bodies are experiencing backlog concentration, delaying market entry for devices dependent on new clinical investigations.
Patient acquisition is gravitating toward direct-to-consumer channels and dental practice bypass models. Sleep study referrals from primary care physicians are flattening as patients self-refer to dental sleep medicine specialists following online symptom research. This channel rotation is most pronounced in United States metropolitan markets where dental sleep medicine advertising density is highest.
Sleep Apnea Oral Appliances Market Segmentation
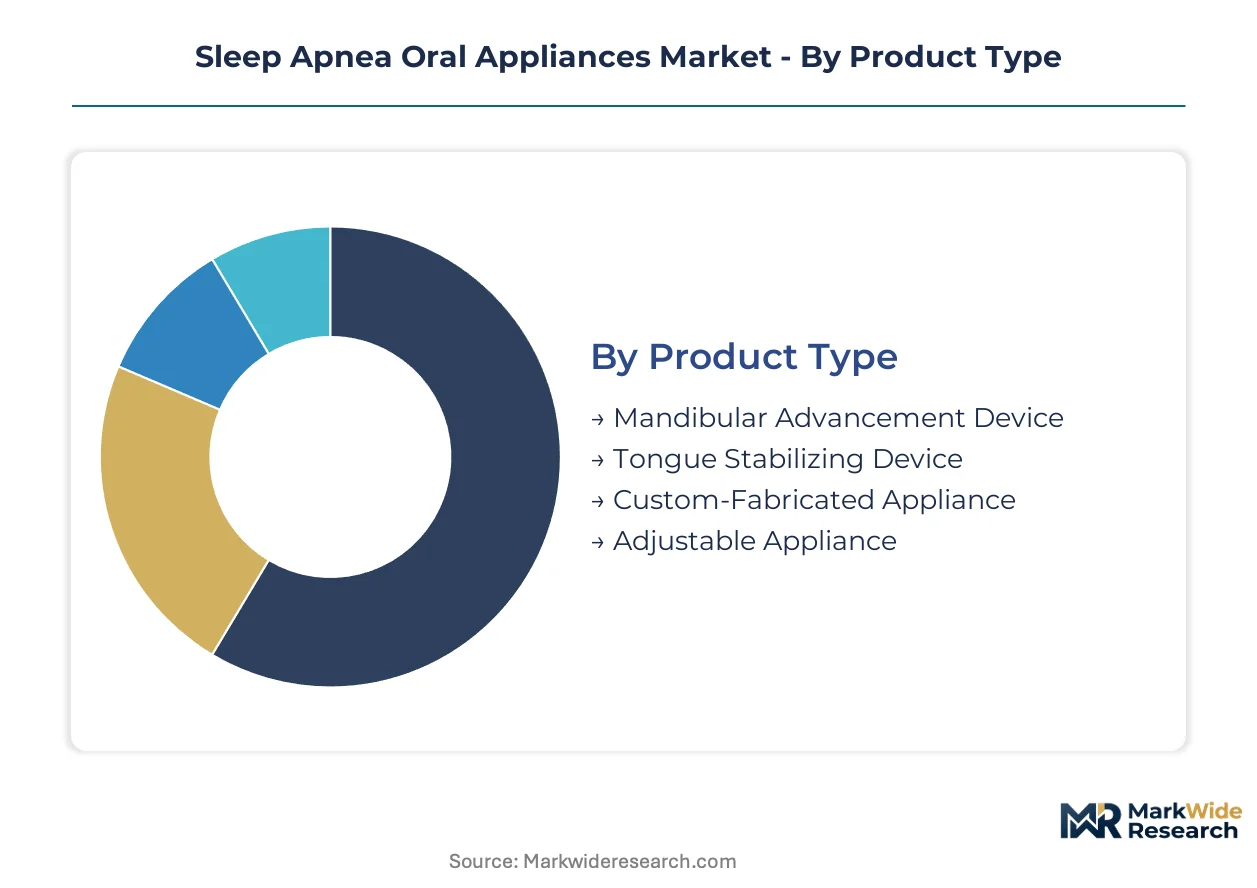
Sleep apnea oral appliances fragment across fabrication technology, therapeutic mechanism, and care delivery setting. Each segmentation axis carries distinct margin profiles and regulatory pathways that shape manufacturer positioning.
Product Type:
Prescriber training depth and reimbursement tier separate buyers across this category.
- Mandibular Advancement Device:Repositions the lower jaw forward via bilateral acrylic or nylon connectors to maintain airway patency. Volume concentrates in United States dental sleep medicine practices where FDA 510(k) predicate familiarity accelerates prescribing confidence; reimbursement code density supports premium positioning.
- Custom-Fabricated Appliance:Patient-specific devices produced from digital impressions with individualized titration ranges. Demand clusters in Germany where KBA-aligned reimbursement rewards precision-manufactured Class II medical devices; laboratory density enables rapid turnaround that drives patient compliance.
- Tongue Stabilizing Device:Suction-based anterior tongue retainers for mandibular edentulism or TMJ contraindications.
- Adjustable Appliance:Mechanisms permitting patient- or clinician-controlled mandibular advancement increments.
Volume sits with Mandibular Advancement Device; growth tilts toward Custom-Fabricated Appliance.
End User:
Care setting determines regulatory burden and patient acquisition economics for manufacturers.
- Home Care:Direct-to-patient delivery models bypass traditional sleep center referrals through tele-dental platforms and mail-order impression kits. United States metropolitan markets show steepest channel expansion as patients self-refer following online symptom research; dental sleep medicine advertising density correlates with home care penetration.
- Dental Clinics:Chairside delivery with intraoral scanning and same-day fitting capabilities. Germany concentrates prescriber expertise through mature dental sleep medicine infrastructure; CAD/CAM integration enables premium service bundling that supports higher device margins.
- Hospitals:Integrated sleep medicine departments with polysomnography-linked prescribing workflows.
- Sleep Centers:Dedicated diagnostic facilities with physician-driven appliance selection protocols.
Volume concentrates in Dental Clinics; Home Care captures the steepest expansion trajectory.
Technology:
Manufacturing throughput and material biocompatibility standards differentiate production platforms.
- 3D Printing:Photopolymer jetting and selective laser sintering systems producing dual-durometer appliances with integrated soft liners. United States and German laboratories deploy these systems for same-day turnaround that collapses patient acquisition cycles; unit economics approach conventional molding at scale.
- CAD/CAM:Digital design-to-manufacture workflows with precision-milled or printed components. Japan shows emerging adoption as PMDA device classification pathways mature; ISO 13485-convergent quality systems enable multi-market deployment from single production facilities.
- Polypropylene Molding:Conventional thermoforming of medical-grade polymers for standardized appliance geometries.
- Silicone:Soft elastomer components for interface comfort and pressure distribution.
Volume sits with Polypropylene Molding; 3D Printing gains share fastest through laboratory automation.
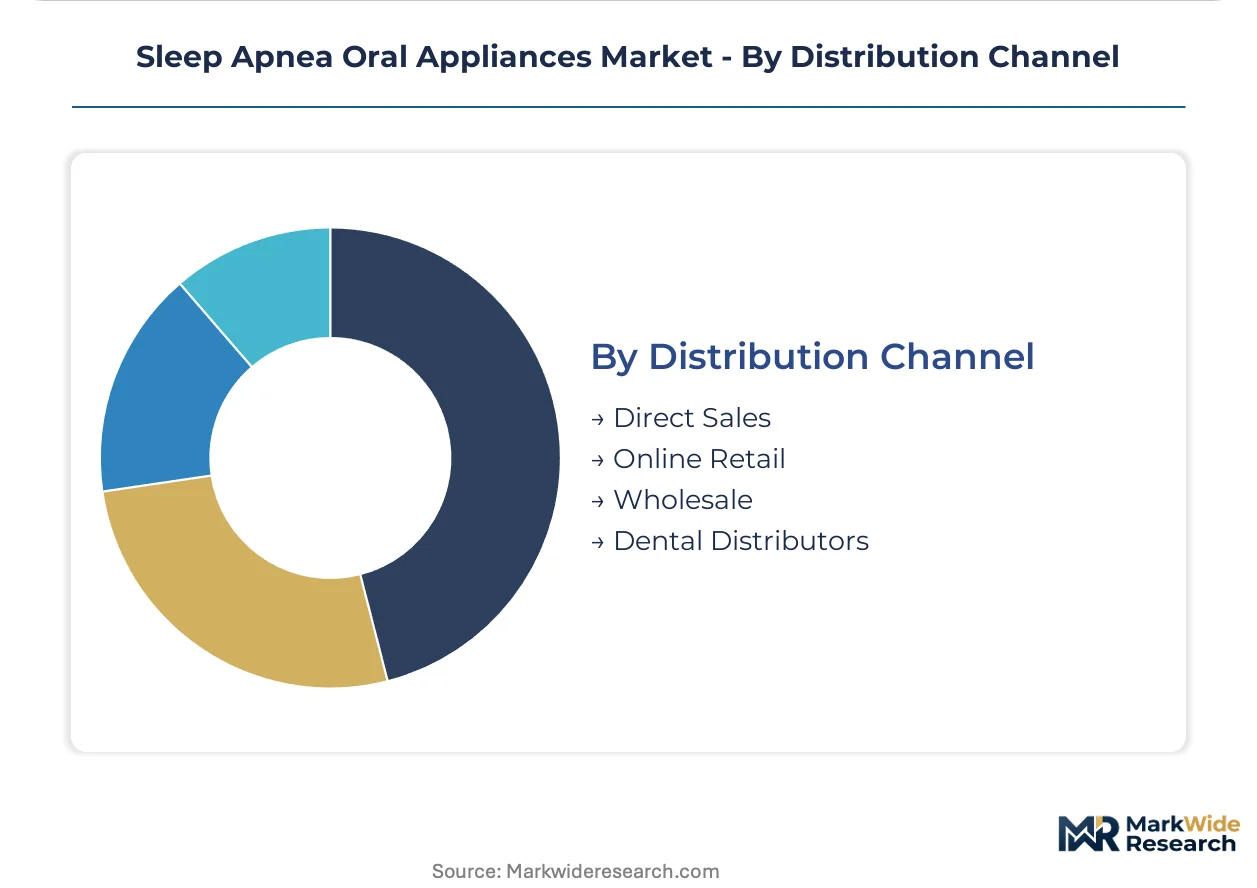
Distribution Channel:
Customer relationship depth and inventory carrying cost structure separate channel strategies.
- Dental Distributors:Specialized medical device wholesalers with field sales forces calling on dental sleep medicine practices. United States market shows channel concentration through Patterson Dental and Henry Schein networks; credit terms and technical training support drive prescriber loyalty.
- Direct Sales:Manufacturer-controlled patient or clinician relationships bypassing intermediaries. SomnoMed's direct-to-patient platform exemplifies this model across multiple continents; margin retention funds regulatory compliance investments for multi-market entry.
- Online Retail:E-commerce platforms with patient self-selection and remote fitting support.
- Wholesale:Bulk procurement arrangements with hospital systems and sleep center networks.
Volume concentrates in Dental Distributors; Direct Sales climbs the fastest as platform economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Dubai and Shenzhen are drawing dental device manufacturing toward concentrated logistics hubs with streamlined customs processing and tax-advantaged export channels.
United States
FDA 510(k) clearance density and expanding dental billing code coverage are accelerating prescriber adoption of mandibular advancement devices. The KBA-aligned reimbursement models in Germany are influencing US payer negotiations for precision-manufactured appliances. Dallas-Fort Worth concentrates laboratory automation investments where 3D printing throughput is reshaping same-day delivery economics.
Germany
KBA reimbursement pathways reward Class II medical device certification for custom-fabricated appliances, concentrating prescriber expertise in dental sleep medicine. EU MDR post-market surveillance requirements are extending CE-marking timelines for new market entrants. Munich-Stuttgart corridor laboratories deploy photopolymer jetting systems for dual-durometer production at unit costs approaching conventional molding.
Japan
PMDA device classification pathways for oral appliances remain underdeveloped relative to Western regulatory frameworks, creating positioning opportunities for compliant first-movers. METI industrial policy is incentivizing domestic CAD/CAM adoption in dental manufacturing clusters. Osaka-Kobe manufacturing belt shows emerging laboratory automation as ISO 13485-convergent quality systems enable multi-market deployment.
Australia
TGA medical device registration requirements align with EU MDR evidence standards, streamlining parallel market entry for CE-marked appliances. Private health insurance rebate structures for sleep apnea therapy are expanding out-of-pocket coverage gaps. Sydney-Melbourne corridor concentrates dental sleep medicine practitioner training programs that address prescriber certification bottlenecks.
Canada
Health Canada device licensing pathways for oral appliances mirror FDA substantial equivalence frameworks, enabling synchronized North American commercialization timelines. Provincial reimbursement variation creates patchwork coverage landscapes that favor direct-to-patient channel development. Toronto-Waterloo region concentrates digital dentistry startups integrating intraoral scanning with cloud-based design platforms.
Sleep Apnea Oral Appliances Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with direct-to-patient platforms capturing margin retention while laboratory service providers dominate volume throughput. Market structure tilts toward fragmented specialization rather than consolidated control, with regional laboratories competing on turnaround velocity against multinational device portfolios. Three archetypes define positioning: precision-manufacturing specialists with CAD/CAM differentiation, respiratory ecosystem extenders leveraging existing clinical relationships, and direct-to-patient platform operators collapsing traditional distribution layers. Dominant competitive moves include strategic partnerships with dental sleep medicine training programs and technology licensing for multi-material 3D printing capabilities.
Among North American fabricators, SomnoMed exemplifies the direct-to-patient platform archetype with continental reach, while ResMed anchors the respiratory ecosystem extension strategy through adjacent device portfolios. ProSomnus Sleep Technologies occupies a position within the precision-manufacturing tier, representing CAD/CAM specialization with tight-tolerance fabrication capabilities. These three entities illustrate divergent paths to market access: platform economics, clinical ecosystem integration, and manufacturing precision respectively.
| Leading Market Players |
|---|
| DynaFlex |
| Airway Management |
| SomnoMed |
| Whole You |
| Panthera Dental |
| ResMed |
| Vivos Therapeutics |
| Apnea Sciences |
| ProSomnus Sleep Technologies |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dental laboratories in the United States and Germany have consolidated manufacturing capacity around photopolymer jetting systems, creating pricing discipline through volume commitments to European resin suppliers while squeezing independent fabricators on turnaround premiums.
Pricing Analysis
Lead-time-driven pricing tiers separate chairside same-day delivery from traditional two-week laboratory turnaround, with CAD/CAM-integrated dental practices commanding premium positioning for immediate fitting while mail-order impression kits compete on accessibility. Three-tier pricing structure across premium custom-fabricated, standard adjustable, and economy boil-and-bite levels tracks certification grade and customization depth. Price erosion runs through polypropylene-molded appliances as 3D printing unit economics approach conventional molding at scale. Hospital sleep centers show least price sensitivity due to bundled reimbursement, while direct-to-consumer channels face acute sensitivity to out-of-pocket exposure.
Supply Chain Analysis
ISO 13485 and FDA 510(k) qualification requirements gate supplier selection, concentrating medical-grade photopolymer sourcing among German and Dutch chemical specialists with biocompatibility master files. Manufacturing gravity centers on United States, Germany, and Japan where dental sleep medicine infrastructure supports laboratory density. Raw material dependencies include methacrylate oligomers, photoinitiators, and nickel-titanium advancement mechanisms. Single-source vulnerability in European resin supply creates tariff exposure risk. Distribution runs through specialized dental distributors with field sales forces in developed markets, while direct-to-patient platforms bypass intermediaries in home care expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers seek captive control over CAD/CAM design software and chairside delivery workflows to defend margin compression from rapid-turnaround laboratories.
For Market Incumbents: Deepen backward integration into photopolymer resin formulation to secure supply continuity against European chemical supplier concentration. Lock in exclusive partnerships with dental sleep medicine training programs to control prescriber funnel access against emerging platform competitors. Prioritize ISO 13485-convergent quality systems that enable single-audit multi-market deployment. For New Entrants and Emerging Players: Capture Japan's underdeveloped PMDA device classification pathway before Western incumbents establish predicate device familiarity. Target tele-dental integration for rural and underserved patient populations bypassing traditional sleep center referrals. Pursue direct-to-patient platform economics with mail-order impression kits and remote mandibular titration support. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-manufacturing specialists with CAD/CAM capabilities in Germany facing EU MDR compliance cost pressures. Long-term viability over the projection horizon hinges on reimbursement code expansion sustainability. Watch FDA 510(k) clearance velocity for novel mechanism devices as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material 3D Printing Licensing | Enables dual-durometer appliance production with integrated soft liners in single builds. |
| Dental Sleep Medicine Training Partnerships | Secures prescriber funnel access through accredited certification program sponsorships. |
| Tele-Dental Platform Integration | Expands patient acquisition into rural populations via remote mandibular advancement titration. |
| EU MDR Post-Market Surveillance Buildout | Accelerates CE-marking timelines through preemptive clinical evidence infrastructure investment. |
| Direct-to-Patient Channel Development | Bypasses dental distributor intermediaries to retain margin for regulatory compliance funding. |
Study Parameters
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR notified body registers formed the secondary backbone, cross-referenced with primary interviews involving dental sleep medicine practitioners, laboratory operations directors, GPO contracts managers, and biomedical engineers specializing in intraoral device fabrication. Bottom-up triangulation across fabrication technology cost structures and top-down validation against reimbursement code expansion trajectories anchored volume estimates.
Historical trendline analysis across mandibular advancement device prescriptions, custom-fabricated appliance laboratory throughput, and home care channel penetration established baseline growth patterns. The modeling framework segmented by product type, end user setting, fabrication technology, and distribution channel, with CAGRs derived from regression against dental billing code density and 3D printing adoption curves. Forecast inputs included KBA-aligned reimbursement pathway stability and PMDA device classification maturation timelines.
The model holds under stable FDA 510(k) predicate availability and continued resin supply concentration; deviation in EU MDR notified body backlog severity or medical-grade polymer cost volatility would shift trajectory. A model refresh is warranted upon material change in dental board scope-of-practice rulings affecting prescriber pool access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
China Dental Devices Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Impression System Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Inlays and Onlays Market