
 South Africa Dental Devices Market | 2026-2036
South Africa Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Dental Devices Market Analytics
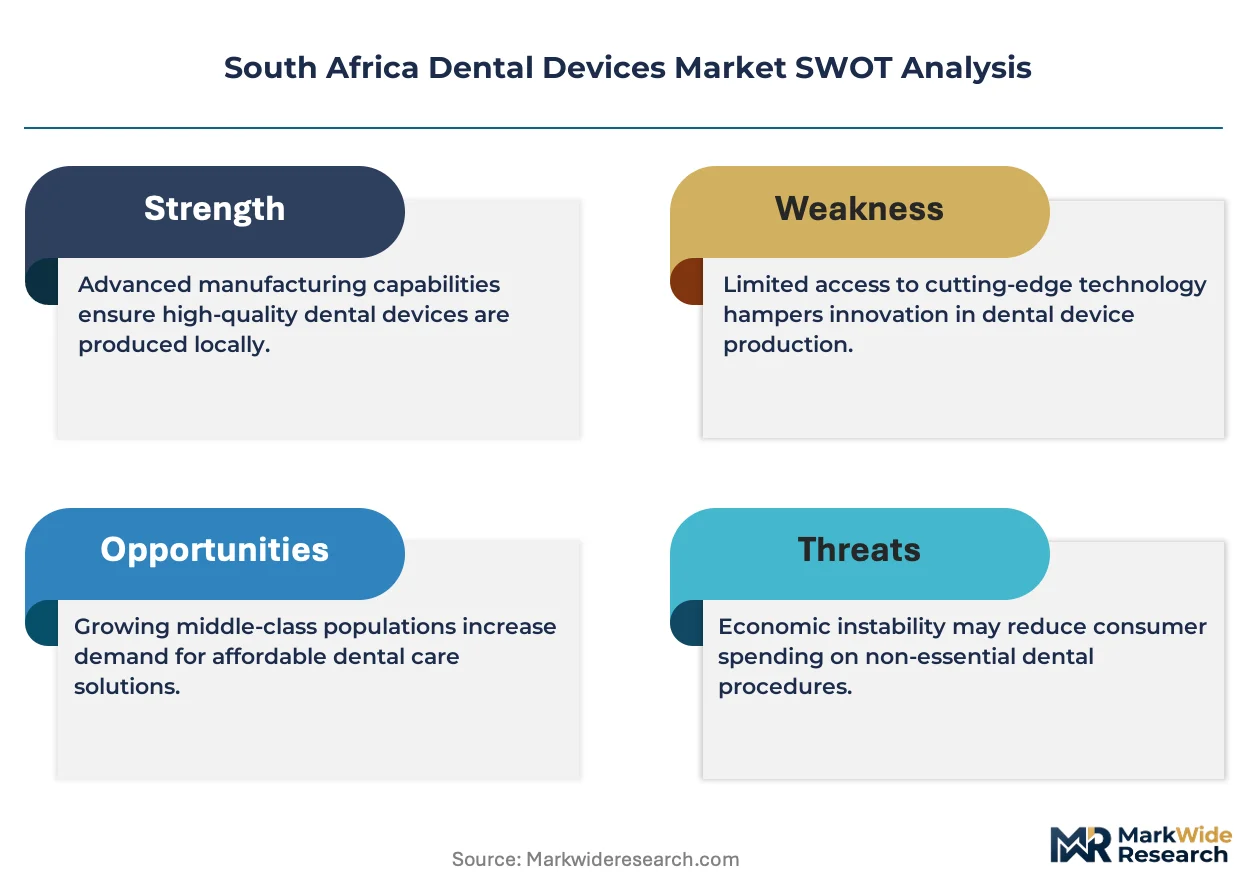
Buyer concentration among private dental clinic chains is shifting toward larger group practices that centralize procurement decisions. Dentsply Sirona leverages its integrated digital workflow platforms to capture recurring consumable revenue from these consolidated buyers. Straumann Group anchors its position through premium implantology portfolios and specialist education programs. Zimmer Biomet competes across the full reconstructive spectrum, sustaining relevance through broad surgical instrument coverage.
Dental devices encompass instruments, equipment, and materials engineered for oral diagnosis, treatment, and prosthetic rehabilitation, typically manufactured from surgical-grade stainless steel, titanium alloys, or zirconia-based bioceramics with precision tolerances measured in micrometers. Their primary purpose is to enable restorative, orthodontic, endodontic, and implantological interventions with predictable clinical outcomes. Implantology commands the deepest margin pools given the specialist training barrier and premium component pricing. Digital Dentistry, spanning intraoral scanning and chairside CAD/CAM milling, represents the fastest-expanding technology segment as South African practices upgrade from conventional impression workflows. Orthodontics remains structurally mature, with demand tilting toward clear aligner systems that require digital infrastructure investment.
South Africa's Health Products Regulatory Authority governs medical device registration, while the South African Dental Association issues clinical practice guidelines that indirectly shape equipment specifications. BIS standards for imported instrumentation and local quality certification requirements create compliance thresholds that filter lower-tier suppliers from the formal channel. Stakeholders must monitor regulatory harmonization pressures between national standards and EU MDR-aligned frameworks, as alignment would accelerate market access for European manufacturers while raising compliance costs for incumbents.
Market Dynamics
Private dental clinic chains in Gauteng are consolidating procurement decisions into centralized purchasing functions, compressing vendor negotiation cycles and favoring suppliers with integrated digital workflow platforms over standalone equipment vendors.
Growth Catalysts
- SAHPRA Registration Harmonization:Alignment with EU MDR frameworks would streamline market access for European manufacturers already certified under CE marking, expanding the supplier base for South African distributors.
- Clear Aligner Digital Infrastructure:Orthodontic practices are investing in intraoral scanning and 3D printing capabilities to capture patient demand for aesthetic alternatives to fixed appliances.
- Gauteng Specialist Density:Johannesburg and Pretoria host the densest concentration of implantology and prosthodontic specialists in South Africa, creating localized demand concentration for premium chairside equipment.
Market Restraints
- Import Duty Structure:BIS standards compliance and customs clearance timelines for surgical-grade stainless steel instrumentation inflate landed costs for equipment not manufactured within the Southern African Customs Union.
- Specialist Training Bottleneck:The limited pipeline of formally trained implantologists restricts addressable market expansion for premium implantology portfolios regardless of equipment availability.
- Currency Volatility:Rand-denominated practice revenues against dollar- or euro-denominated equipment contracts create margin compression during depreciation cycles.
Strategic Opportunities
- Western Cape Expansion:Cape Town's private dental market remains less penetrated by chain consolidation, offering independent practices receptive to technology partnerships.
- Chairside CAD/CAM Convergence:Integration of intraoral scanning with same-day milling systems enables single-visit crown delivery, differentiating practices competing on convenience.
- SADA Continuing Education Partnerships:Equipment vendors can anchor market position through accredited training programs that lock in consumable purchasing from graduating specialists.
Industry Challenges
- Digital Workflow Integration:Practices with legacy analog impression systems face capital intensity and staff retraining requirements when transitioning to fully digital restorative workflows.
- SAHPRA Registration Timelines:Medical device approval cycles can extend 18-24 months for novel chairside technologies, delaying revenue recognition for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Dental Devices Market |
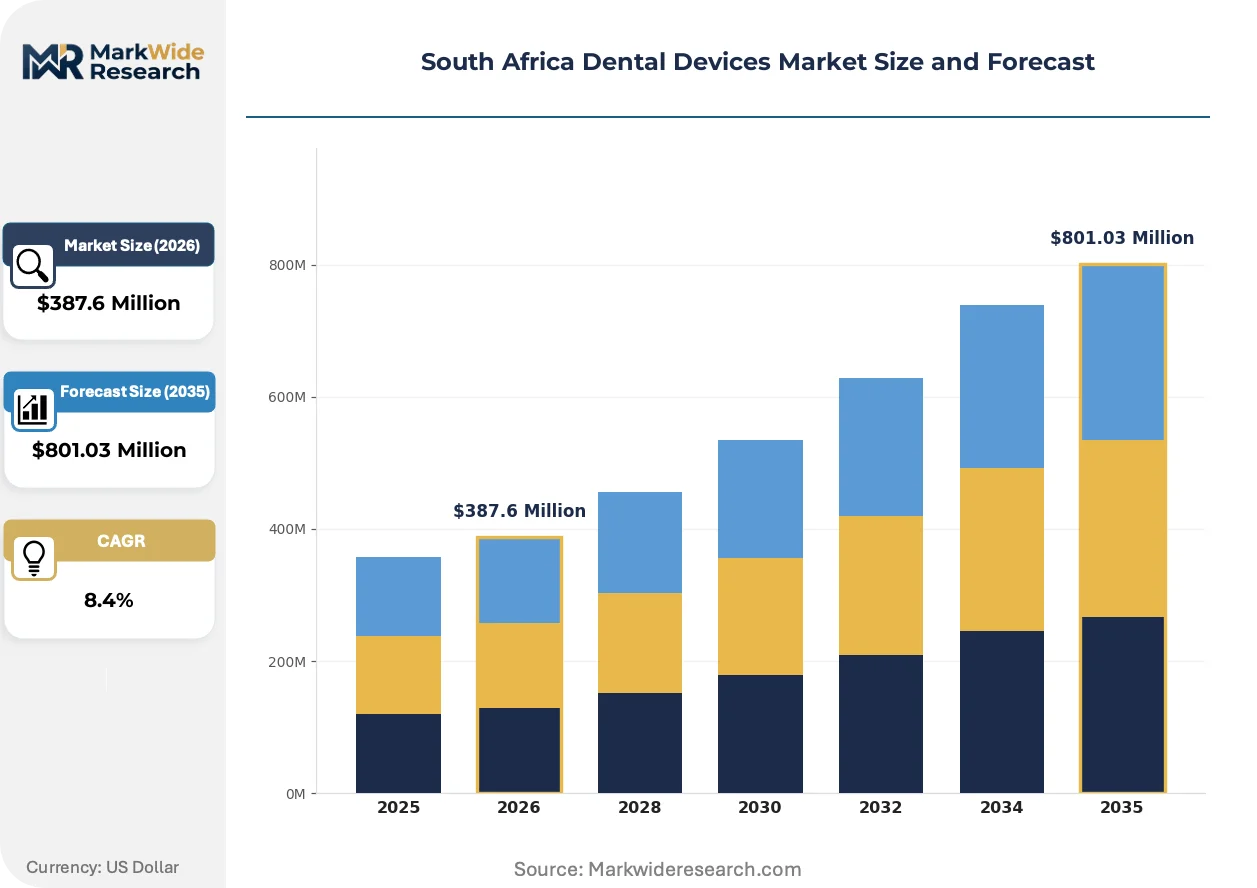
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Endodontics, Restoratives, Implantology Technology: Digital Dentistry, Laser Dentistry, CAD/CAM, Bioceramics End User: Dental Clinics, Hospitals, Academic Institutions, Research Labs Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Nobel Biocare, Zimmer Biomet, Dentsply Sirona, BioHorizons Implant Systems, Carestream Health, 3M, Henry Schein, Planmeca, Straumann Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Dental Devices Market Evolving Landscape
Digital dentistry infrastructure is migrating from large laboratory hubs into individual practice settings, compressing turnaround times and reshaping the economics of restorative and prosthodontic services across South African metropolitan markets.
Intraoral scanning technology is decentralizing diagnostic and impression capture workflows that previously required physical laboratory intermediaries. Private group practices in Johannesburg and Pretoria are deploying chairside scanners at scale, enabling same-day treatment planning and reducing patient visit requirements. This shift is compressing the traditional dental laboratory intermediary layer and reallocating margin capture toward practices with in-house digital production capabilities.
South Africa's Health Products Regulatory Authority maintains stringent medical device registration standards that filter lower-tier suppliers from the formal distribution channel. BIS standards for imported instrumentation create compliance thresholds that favor established manufacturers with dedicated regulatory affairs functions. The implantology segment faces the highest scrutiny given the invasive nature of titanium alloy and zirconia-based bioceramic components, driving consolidation among vendors with proven SAHPRA track records.
Buyer concentration among private dental clinic chains is restructuring vendor relationships toward enterprise-level service agreements. Group practices with centralized procurement functions are unbundling equipment purchases from consumable supply contracts, negotiating separate terms for titanium implant components, zirconia blanks, and orthodontic aligner materials. This bifurcation is most visible in Gauteng province, where the largest chain operators have established dedicated supply chain management roles distinct from clinical operations.
South Africa Dental Devices Market Segmentation
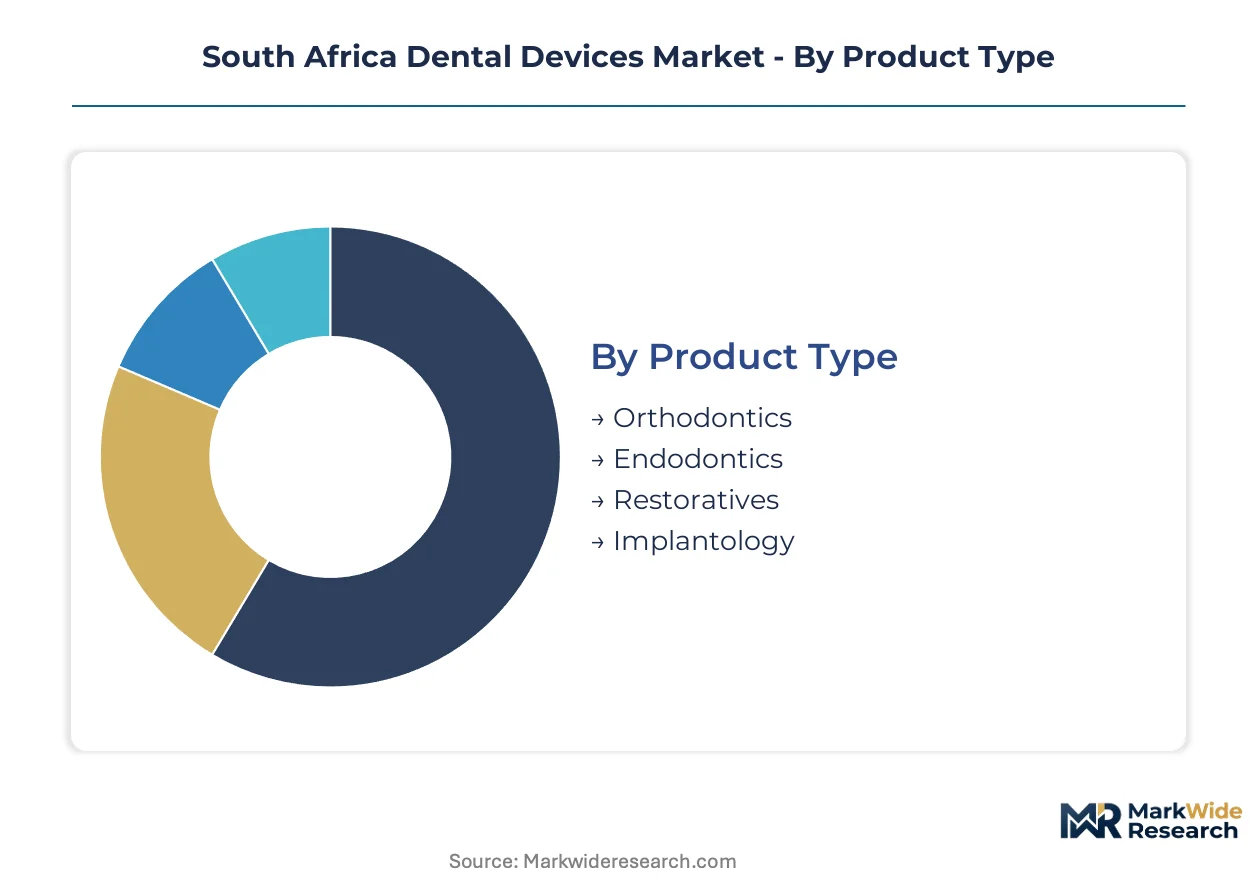
Segmentation in South Africa's dental devices market reveals how procurement patterns diverge across clinical settings and technological sophistication. Gauteng's specialist concentration drives premium segment demand, while Western Cape independents favor flexible technology partnerships over capital-intensive systems.
Product Type:
Customization intensity varies sharply across this category, from standardized consumables to patient-matched surgical components requiring specialist intervention.
- Implantology:Titanium alloy and zirconia-based bioceramic components demand micrometer-precision manufacturing. Johannesburg and Pretoria specialists drive concentrated demand for premium portfolios, constrained by SAHPRA's stringent registration timelines for invasive devices.
- Digital Dentistry:Intraoral scanning and chairside CAD/CAM systems enable same-day restorative workflows. Gauteng chain practices are consolidating procurement of these platforms, displacing conventional laboratory intermediaries.
- Orthodontics:Clear aligner systems require substantial digital infrastructure investment from practices.
- Endodontics:Nickel-titanium rotary instruments and obturation materials serve root canal specialists.
- Restoratives:Composite resins and bonding agents represent high-volume, lower-margin consumable demand.
Leading the category by volume: Restoratives. Growing fastest: Implantology.
Technology:
Cost tier stratification separates capital-intensive platform investments from consumable-dependent modalities.
- CAD/CAM:Chairside milling systems integrate with intraoral scanners to compress crown delivery from two weeks to single visits. Cape Town independents represent untapped expansion opportunity for vendors targeting practices outside Gauteng consolidation.
- Digital Dentistry:Workflow platforms encompass diagnostic imaging, treatment planning software, and practice management integration. Group practices in Johannesburg centralize these decisions through dedicated supply chain roles.
- Laser Dentistry:Soft-tissue and hard-tissue applications require substantial training investment.
- Bioceramics:Zirconia and alumina-based materials serve aesthetic restorative and implant superstructure applications.
Dominant by installed base: Digital Dentistry. Steepest expansion trajectory: CAD/CAM.
End User:
Customer type determines purchasing authority structure and contract complexity.
- Dental Clinics:Private chain practices in Gauteng concentrate procurement through centralized functions, unbundling equipment from consumable contracts. Western Cape independents retain decentralized decision-making receptive to technology partnerships.
- Hospitals:Academic medical centers and private hospital groups require enterprise service agreements with comprehensive maintenance coverage.
- Academic Institutions:Training programs anchor vendor market position through consumable lock-in from graduating specialists.
- Research Labs:Bioceramic and implant surface research drives specialized instrument demand.
Highest procurement volume: Dental Clinics. Fastest contract complexity growth: Hospitals.
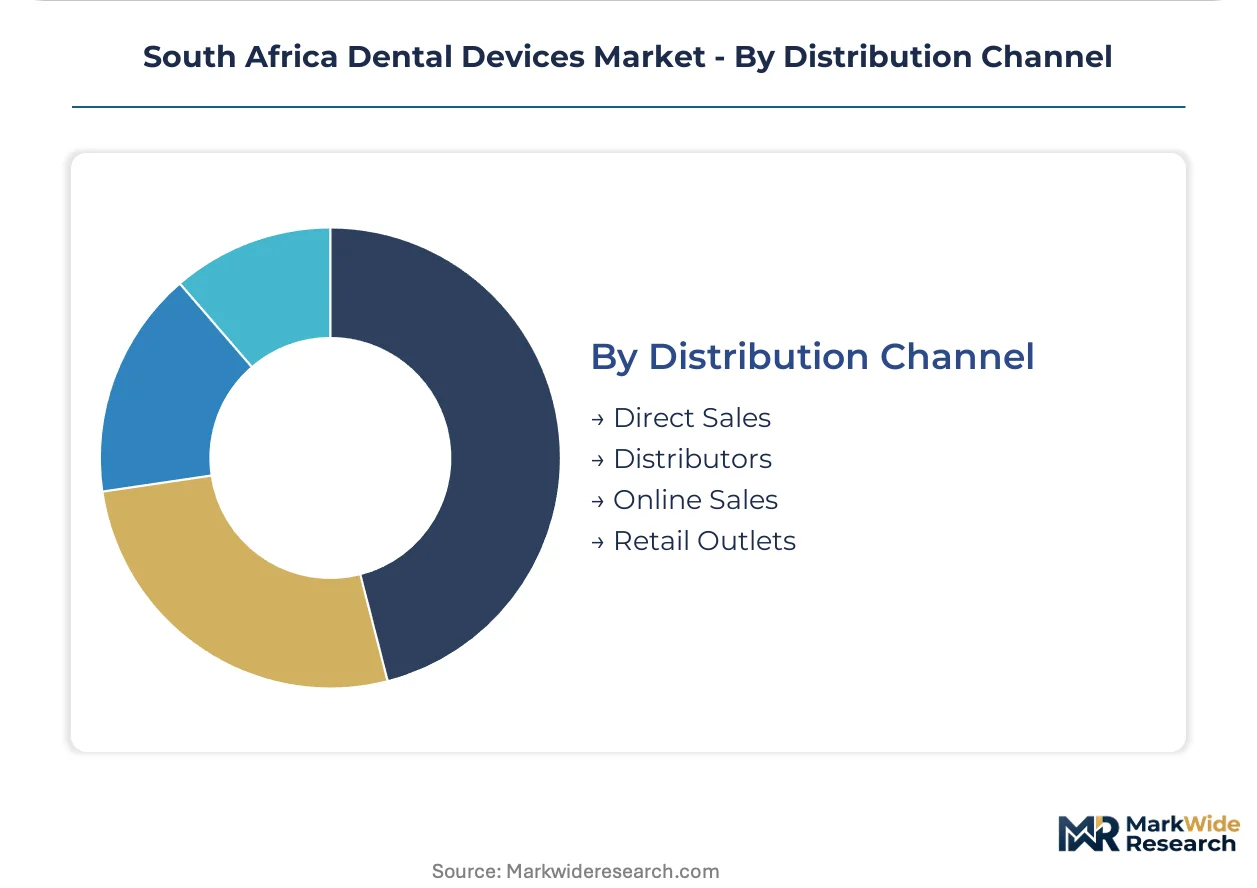
Distribution Channel:
Supply concentration favors established distributors with SAHPRA compliance capabilities over direct manufacturer engagement.
- Distributors:Specialized dental supply houses manage BIS standards compliance and customs clearance for imported stainless steel instrumentation. Rand volatility against dollar-denominated contracts creates margin management challenges throughout the channel.
- Direct Sales:Premium implantology vendors maintain specialist sales forces for Gauteng's concentrated specialist practices.
- Online Sales:Consumables and small equipment bypass traditional distribution for price-transparent procurement.
- Retail Outlets:Limited to over-the-counter oral care products rather than professional devices.
Channel leader by value: Distributors. Fastest channel shift: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dental devices in South Africa concentrates heavily in metropolitan provinces where specialist practices cluster and private healthcare spending flows. Gauteng province anchors procurement volumes through Johannesburg and Pretoria's dense concentration of implantology and prosthodontic specialists. Western Cape presents a contrasting market structure with independent practices receptive to technology partnerships rather than chain consolidation.
Gauteng Province
Johannesburg and Pretoria host South Africa's densest concentration of specialist dental practices, driving concentrated demand for premium chairside equipment and implantology portfolios. SAHPRA's stringent medical device registration standards filter lower-tier suppliers from accessing this high-value market. Private dental clinic chains in the province have established centralized procurement functions, compressing vendor negotiation cycles and favoring suppliers with integrated digital workflow platforms.
Western Cape Province
Cape Town's private dental market remains less penetrated by chain consolidation, preserving decentralized decision-making among independent practices. The South African Dental Association's clinical practice guidelines shape equipment specifications for practitioners seeking accredited continuing education partnerships. This market structure offers technology vendors opportunities for direct practice relationships outside Gauteng's consolidated procurement environment.
KwaZulu-Natal Province
Durban and surrounding metropolitan areas support growing specialist density, though implantology training bottlenecks constrain addressable market expansion regardless of equipment availability. Import duty structures and BIS standards compliance for surgical-grade stainless steel instrumentation inflate landed costs for practices sourcing equipment outside the Southern African Customs Union. Currency volatility between rand-denominated revenues and dollar-denominated contracts creates margin compression during depreciation cycles.
Eastern Cape Province
Port Elizabeth and East London host emerging private dental markets with developing specialist infrastructure, creating longer sales cycles for premium equipment vendors. Academic institutions in the province anchor vendor market position through consumable lock-in from graduating specialists entering regional practice. Distribution channels favor established dental supply houses managing SAHPRA compliance and customs clearance over direct manufacturer engagement.
South Africa Dental Devices Market Competitive Landscape
European producers anchor the premium-tier implantology and digital dentistry segments; North American manufacturers hold positions across the full reconstructive spectrum. The vendor structure stratifies between integrated platform providers capturing recurring consumable revenue and standalone equipment specialists competing on capital cost. Three archetypes dominate: multinational conglomerates with full dental portfolios, premium implantology pure-plays leveraging specialist education lock-in, and regional distributors managing SAHPRA compliance for imported instrumentation. Competitive moves concentrate on enterprise service agreements with group practices and accredited training program sponsorships that secure consumable purchasing from graduating specialists.
Among the premium implantology tier, Straumann Group and Nobel Biocare exemplify the specialist education-driven archetype, anchoring market position through training program relationships that shape long-term purchasing patterns. Dentsply Sirona occupies a position representing integrated digital workflow convergence, with platform strategies designed to capture recurring revenue from practices transitioning to chairside CAD/CAM systems. Zimmer Biomet sits within the full-spectrum reconstructive category, sustaining relevance through broad surgical instrument coverage rather than premium component specialization.
| Leading Market Players |
|---|
| Nobel Biocare |
| Zimmer Biomet |
| Dentsply Sirona |
| BioHorizons Implant Systems |
| Carestream Health |
| 3M |
| Henry Schein |
| Planmeca |
| Straumann Group |
| Others |
Value Network & Pricing Analysis
Centralized procurement functions at Gauteng's private dental clinic chains are compressing vendor margins and forcing suppliers to unbundle equipment from consumable contracts, reshaping how manufacturers structure pricing across premium implantology and digital dentistry tiers.
Pricing Analysis
High-volume restorative consumables trade on thin margins while implantology components capture premium pricing through specialist certification barriers. Three-tier pricing structure across premium, standard, and economy levels reflects SAHPRA registration tiers, brand equity, and after-sales training bundling. Cost compression in economy-grade instrumentation is intensifying because rand depreciation against dollar-denominated supply contracts inflates landed costs. Independent practices in Western Cape exhibit highest price sensitivity; Gauteng chain buyers with centralized procurement show lowest sensitivity due to volume leverage.
Supply Chain Analysis
Freight costs from European manufacturing hubs and East Asian precision component centers constitute a material share of landed equipment prices in South Africa. Supply concentrates in Germany, Switzerland, and South Korea for titanium alloy implants, intraoral scanners, and nickel-titanium rotary instruments. The channel draws from surgical-grade stainless steel mills in India and China, plus zirconia bioceramic feedstock from Japanese suppliers. Single-source vulnerability around EU MDR-certified component suppliers creates bottleneck risk. Distribution runs through specialized dental supply houses managing SAHPRA compliance and BIS standards clearance rather than direct manufacturer engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAHPRA's stringent medical device registration timelines function as a cost-of-compliance moat that filters lower-tier suppliers and rewards established players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Anticipate margin compression from chain procurement centralization by deepening specialist education lock-in through SADA-accredited training programs. Anchor position via backward integration into consumable production for titanium implant components and zirconia blanks. Counter emerging pure-play digital dentistry entrants by bundling chairside CAD/CAM platforms with enterprise service agreements that span maintenance and software updates. For New Entrants and Emerging Players: Chairside 3D printing systems for clear aligner production offer a technology-first wedge into Cape Town's independent practice market outside Gauteng consolidation. Target Western Cape orthodontists seeking aesthetic workflow alternatives without chain procurement barriers. Partner with academic institutions for consumable lock-in from graduating specialists rather than competing on equipment capital cost alone. For Investors and Strategic Acquirers: The window for entry favors distributors with proven SAHPRA track records and established customs clearance capabilities for BIS-compliant instrumentation. Long-term viability hinges on positioning for regulatory harmonization with EU MDR frameworks that would accelerate European manufacturer market access. Watch SAHPRA registration timeline compression as the inflection signal for supply base expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Acceleration | Shortens approval cycles for novel chairside technologies from European manufacturers with existing CE marking. |
| SADA Education Partnership | Locks in consumable purchasing from implantology and prosthodontic specialists graduating from accredited programs. |
| Western Cape Direct Sales Buildout | Captures independent practice demand outside Gauteng chain consolidation through technology partnership models. |
| Chairside CAD/CAM Integration | Enables same-day crown delivery that differentiates practices competing on convenience in metropolitan markets. |
| Consumable Supply Agreement Unbundling | Separates titanium implant and zirconia blank contracts from equipment purchases to optimize procurement leverage. |
Research Methodology
Multi-period observation of implantology specialist density, digital dentistry adoption rates, and chain procurement consolidation anchored the trend analysis, supplemented by interviews with private dental clinic procurement directors, SAHPRA regulatory affairs specialists, SADA continuing education coordinators, and biomedical engineers at academic medical centers. Secondary validation drew from SAHPRA medical device registration databases, South African Dental Association clinical guideline publications, BIS standards documentation, and customs clearance records for surgical-grade instrumentation. Bottom-up practice-level equipment surveys triangulated against top-down distributor shipment data.
Input-output matrices mapped demand from segmentation dimensions including product type, technology tier, end-user category, and distribution channel across the projection horizon. CAGRs were derived from fitted growth curves calibrated to observed adoption S-curves for intraoral scanning and chairside milling systems. Industry-specific forecast inputs incorporated rand-dollar exchange rate volatility assumptions and SAHPRA registration pipeline visibility for novel device categories.
Several conditions sit outside the modeled scope, including abrupt regulatory alignment with EU MDR frameworks, major currency devaluation events beyond historical volatility bands, and specialist training pipeline expansion that could accelerate addressable market growth. Forecasts reflect documented assumptions about procurement centralization velocity and technology substitution rates. Stakeholders should weight assumptions against their own operating context and SAHPRA engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Impression Tray Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Global Dentures Market
Dental Devices
Dental Units Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Carpule Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Calipers Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Orthodontics Market
Dental Devices
3D-Printed Dental Restoration Market