
 North America Dental Aligners Market | 2026-2036
North America Dental Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dental Aligners Market Analytics
The EPA's updated medical plastics waste guidelines is repositioning manufacturer priorities toward recyclable tray materials and reduced single-use packaging. Align Technology, Inc. leverages its Invisalign brand infrastructure to dominate direct-to-provider channels across the United States. Dentsply Sirona anchors its position through integrated digital workflow platforms connecting intraoral scanners to aligner fabrication. 3M competes via proprietary SmartTrack material science that differentiates force delivery profiles.
North America dental aligners are removable orthodontic appliances fabricated from multilayer thermoplastic polymers, typically polyethylene terephthalate glycol-modified copolymers, engineered to apply controlled mechanical force sequences for tooth repositioning with 0.25 to 0.33 millimeter incremental movement per tray stage. Clear aligners lead product type revenue contribution due to adult patient preference for aesthetic treatment modalities, while home user end user segments represent the fastest-growing channel driven by remote monitoring platforms and direct-to-consumer impression kits. Dental offices maintain the dominant distribution channel for high-complexity cases requiring clinical oversight, though online retail captures margin pools in mild malocclusion segments.
FDA 510(k) clearance pathways and Health Canada Medical Device Licensing establish baseline safety and efficacy requirements that shape product development timelines and market access conditions for new entrants. The American Dental Association's voluntary accreditation standards and state-level dental board telehealth regulations further constrain direct-to-consumer model expansion. Stakeholders must monitor evolving scope-of-practice rulings across provincial dental colleges and state licensing boards to anticipate channel restrictions.
Market Dynamics
Suburban orthodontic clinic expansion is compressing patient access times while FDA 510(k) clearance pathways compress product development cycles for new thermoplastic formulations.
Growth Catalysts
- Adult aesthetic preference:Clear aligner demand concentrates among patients aged 25-45 seeking discreet orthodontic correction, driving tray volume through dental offices.
- Health Canada Medical Device Licensing:Streamlined approval timelines for Class II devices reduce market entry barriers for Canadian manufacturers.
- Remote monitoring platforms:Telehealth-enabled impression kits and digital progress tracking expand home user channel penetration.
Market Restraints
- Petrochemical input volatility:Polyethylene terephthalate glycol-modified copolymer resin prices fluctuate with crude oil benchmarks, squeezing gross margins on tray fabrication.
- Single-supplier scanner concentration:Intraoral scanning hardware depends on concentrated OEM sources, creating procurement risk for independent practices.
- State telehealth restrictions:Dental board scope-of-practice rulings in Texas and Florida limit direct-to-consumer model expansion.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia dental colleges show regulatory openness to teledentistry, creating white space for remote-first aligner brands.
- Recyclable tray materials:EPA medical plastics waste guidelines incentivize bio-based thermoplastic development with preferential procurement positioning.
- AI-powered treatment planning:Machine learning algorithms for predictive tooth movement are converging with cloud-based practice management platforms.
Industry Challenges
- Orthodontist training bottlenecks:Clear aligner case complexity requires specialized continuing education, constraining provider pool expansion.
- Interoperability friction:Digital workflow integration between competing scanner formats and proprietary fabrication software creates technical debt for multi-brand practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dental Aligners Market |
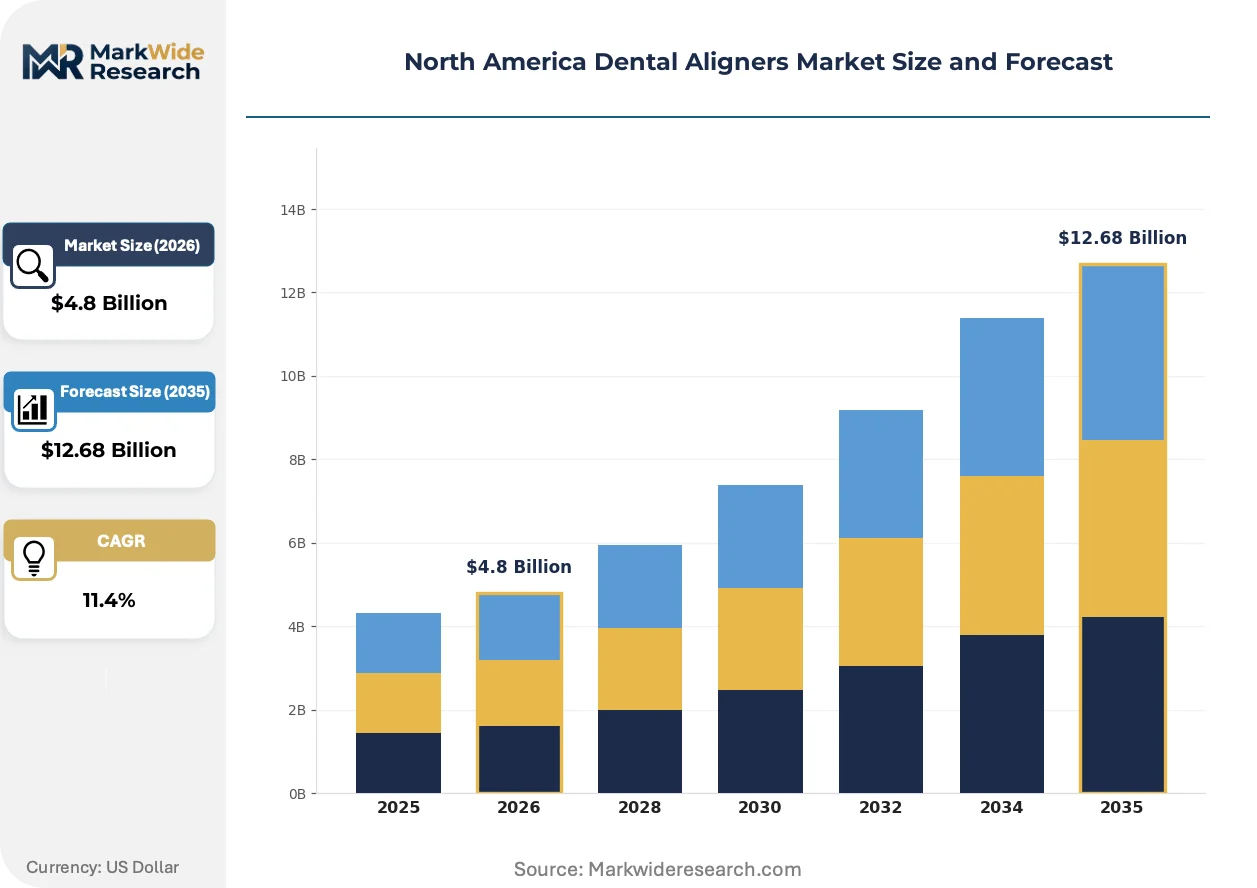
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Traditional Braces, Retainers, Other Devices End User: Orthodontists, Dentists, Dental Clinics, Home Users Material: Plastic, Metal, Composite, Ceramic Distribution Channel: Online Retail, Dental Offices, Pharmacies, Direct Sales |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, 3M, Institut Straumann AG, Henry Schein, Inc., Ormco Corporation, Argen Corporation, TP Orthodontics, Inc., Candid Care Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dental Aligners Market Evolving Landscape
Multilayer thermoplastic engineering and regulatory digitization are compressing treatment timelines while reshaping how orthodontic services reach patients across the United States and Canada.
SmartTrack material science is converging with biomechanical simulation software to enable predictive force delivery profiles. Suburban orthodontic clinics in California and Texas are adopting these integrated platforms at accelerated rates. The technology is converging with chairside 3D printing to compress in-office aligner fabrication from weeks to hours.
FDA 510(k) clearance pathways now incorporate real-world performance data submissions, compressing review timelines for iterative tray designs. Device manufacturers must demonstrate clinical equivalence against predicate aligners while documenting thermoplastic biocompatibility. Canadian manufacturers seeking cross-border market access are prioritizing simultaneous Health Canada Medical Device Licensing submissions to synchronize launch schedules.
Patient acquisition is migrating from referral-dependent dental office channels to direct digital engagement. Remote impression kits and asynchronous orthodontist review are displacing initial in-person consultations for mild malocclusion cases. This behavioral shift concentrates in Sun Belt metropolitan areas where housing sprawl extends physical access to specialty practices.
North America Dental Aligners Market Segmentation
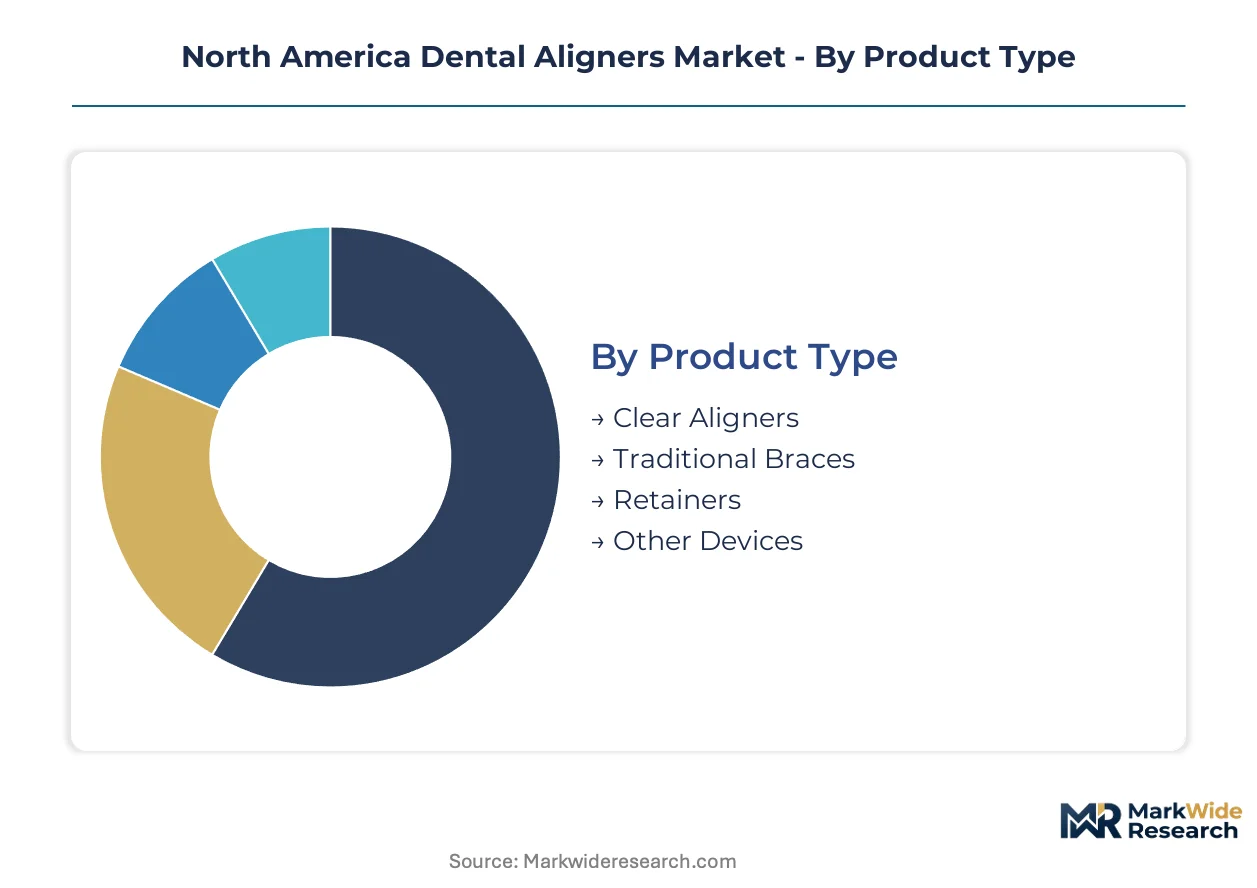
Segmentation in dental aligners reveals distinct capital requirements, patient acquisition economics, and regulatory exposure across product formats and delivery channels. Each dimension shapes manufacturer investment priorities and go-to-market architecture differently.
Product Type:
Capital intensity varies sharply across orthodontic appliance categories, with thermoplastic fabrication demanding specialized multilayer extrusion equipment while metal-based alternatives require precision casting infrastructure.
- Clear Aligners:Multilayer polyethylene terephthalate glycol-modified copolymers engineered for 0.25 to 0.33 millimeter incremental tooth movement per tray stage. Demand concentrates among adult patients aged 25-45 in Texas, California, and Florida metro areas seeking aesthetic correction without fixed appliances. FDA 510(k) clearance pathways and Health Canada Medical Device Licensing frameworks compress development timelines for new thermoplastic formulations.
- Traditional Braces:Stainless steel or nickel-titanium archwire systems bonded to tooth surfaces for complex malocclusion cases. Pediatric and adolescent cases in suburban orthodontic clinics sustain volume, though adult preference for removable alternatives constrains expansion in aesthetic-conscious segments.
- Retainers:Post-treatment stabilization appliances including Hawley and vacuum-formed varieties. Orthodontic practices bundle these with comprehensive treatment packages, generating recurring revenue streams with minimal incremental capital outlay.
- Other Devices:Palatal expanders, space maintainers, and auxiliary orthodontic components serving specialized clinical indications. Lower production volumes limit dedicated manufacturing investment, with most fabrication occurring within integrated dental laboratory networks.
Clear Aligners absorb the bulk of installed capacity; Home Users are expanding most quickly through remote monitoring platforms.
End User:
Customer-type segmentation determines pricing power, with specialized orthodontic practices commanding premium positioning versus general dental offices competing on accessibility.
- Orthodontists:Board-certified specialists managing complex malocclusion cases requiring comprehensive treatment planning. Continuing education requirements and case complexity sustain fee premiums in suburban markets across the United States.
- Dentists:General practitioners capturing mild-to-moderate alignment cases through continuing education programs. Volume growth concentrates in solo and small-group practices seeking ancillary revenue streams without specialist referral overhead.
- Dental Clinics:Multi-provider group practices and dental service organizations standardizing clear aligner protocols across locations. Capital investment in intraoral scanning hardware and digital workflow platforms creates procurement concentration risk.
- Home Users:Direct-to-consumer patients utilizing remote impression kits and asynchronous orthodontist review. Telehealth regulations in Texas and Florida limit model expansion, while Ontario and British Columbia dental colleges show regulatory openness.
Dental Clinics capture the dominant share of tray volume; Home Users are climbing the fastest as remote monitoring platforms mature.
Material:
Input cost volatility and sustainability positioning differentiate material categories, with petrochemical-linked resins exposing margins to crude oil benchmark fluctuations.
- Plastic:Thermoplastic polymers including polyethylene terephthalate glycol-modified copolymers and proprietary multilayer formulations. EPA medical plastics waste guidelines are repositioning manufacturer priorities toward recyclable tray materials and reduced single-use packaging.
- Metal:Stainless steel, nickel-titanium, and cobalt-chromium alloys for fixed appliances and archwire systems. Traditional braces fabrication depends on precision metallurgy with established supply chains.
- Composite:Tooth-colored resin materials for aesthetic bracket systems and temporary restorative applications. Niche positioning in adult cases seeking reduced visual impact from fixed appliances.
- Ceramic:Polycrystalline alumina and zirconia bracket systems offering premium aesthetic performance. Higher material costs and brittleness constrain adoption to premium patient segments.
Plastic dominates production volume; bio-based thermoplastic development is gaining share fastest under EPA waste guideline pressure.
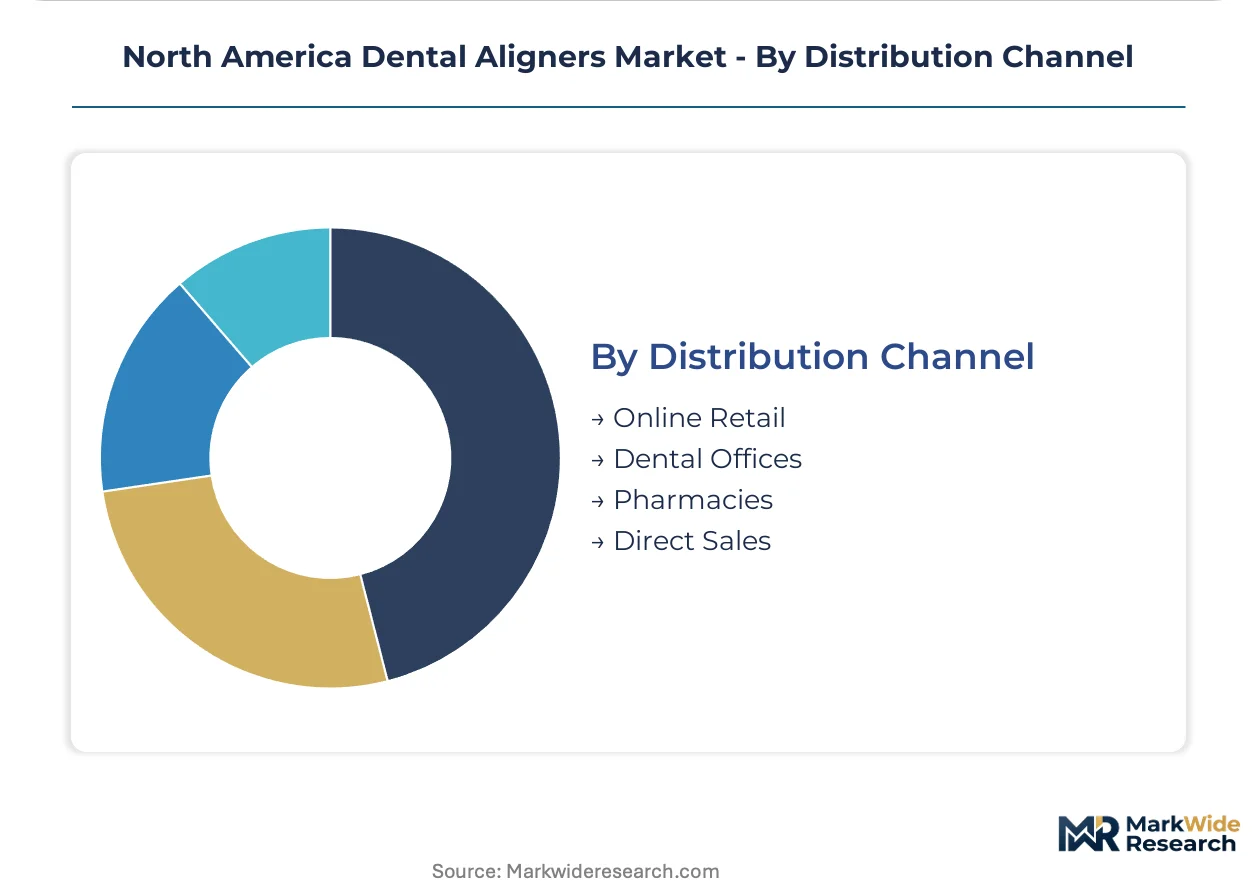
Distribution Channel:
Channel economics reflect patient acquisition cost structures and clinical oversight requirements, with high-complexity cases requiring in-person consultation while mild malocclusion segments migrate online.
- Online Retail:Direct-to-consumer platforms offering remote impression kits and digital treatment monitoring. Asynchronous orthodontist review and telehealth-enabled progress tracking expand penetration in mild malocclusion segments.
- Dental Offices:Traditional chairside consultation and in-practice scanning for comprehensive case management. Dominant channel for high-complexity cases requiring clinical oversight and iterative adjustment.
- Pharmacies:Limited retail presence for over-the-counter retainer products and dental accessories. Marginal positioning constrained by scope-of-practice regulations preventing orthodontic diagnosis in non-clinical settings.
- Direct Sales:Manufacturer field forces and inside sales teams targeting dental service organizations and multi-location practices. Volume discounts and integrated digital workflow platforms anchor enterprise account relationships.
Dental Offices retain the majority of high-value case flow; Online Retail is expanding most quickly in Sun Belt metropolitan areas with extended physical access challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston, Dallas-Fort Worth, and Austin metro corridors anchor North American clear aligner demand through dense suburban orthodontic clinic networks and direct-to-consumer brand penetration.
United States
Texas, California, and Florida metropolitan areas drive patient volume growth through adult aesthetic preference and dental service organization expansion. FDA 510(k) clearance pathways compress product development timelines for new thermoplastic formulations. Houston and Dallas-Fort Worth suburban corridors concentrate orthodontic clinic openings serving clear aligner demand.
Canada
Ontario and British Columbia dental colleges demonstrate regulatory openness to teledentistry models, creating white space for remote-first aligner brands. Health Canada Medical Device Licensing streamlines approval timelines for Class II devices, reducing market entry barriers. Toronto and Vancouver metropolitan areas anchor patient acquisition through integrated digital workflow platforms.
Mexico
Northern border states and Mexico City metropolitan area concentrate cross-border dental tourism and domestic middle-class demand for aesthetic orthodontic solutions. COFEPRIS medical device registration requirements shape product localization strategies for multinational manufacturers. Monterrey and Guadalajara industrial corridors support thermoplastic fabrication subcontracting for North American brands.
North America Dental Aligners Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material science differentiation and digital workflow integration depth. The vendor base stratifies into three tiers: integrated platform owners controlling scanner-to-aligner ecosystems, specialized thermoplastic fabricators serving white-label demand, and direct-to-consumer brands competing on patient acquisition efficiency. Dominant competitive moves include vertical integration into intraoral scanning hardware and strategic partnerships with dental service organizations for volume commitment.
Among integrated platform specialists, Align Technology, Inc. and Dentsply Sirona occupy positions exemplifying end-to-end digital workflow control, while 3M represents material science differentiation through proprietary thermoplastic engineering. These three anchors demonstrate how competitive positioning converges on patient data capture, treatment planning software, and fabrication capacity coordination.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| 3M |
| Institut Straumann AG |
| Henry Schein, Inc. |
| Ormco Corporation |
| Argen Corporation |
| TP Orthodontics, Inc. |
| Candid Care Co. |
| Others |
Value Network & Pricing Analysis
Chairside 3D printing adoption is compressing in-office fabrication timelines from weeks to hours while simultaneously reducing per-unit production costs and redistributing supply leverage toward dental practices with captive manufacturing capacity. This production-method transition concentrates margin capture among integrated platform owners while squeezing white-label thermoplastic fabricators competing on commodity tray economics.
Pricing Analysis
Value-based pricing anchored to treatment outcome certainty and case complexity stratification dominates the market. Three-tier pricing structure across premium, standard, and economy levels separates Invisalign-level brand premiums from dental service organization volume contracts and direct-to-consumer economy tiers. Price differentiation hinges on proprietary material science certification and integrated digital workflow depth. Cost compression in the economy tier is intensifying because remote monitoring platforms reduce orthodontist chair time allocation. Home users exhibit highest price sensitivity, while orthodontic specialists managing complex malocclusions demonstrate lowest sensitivity due to outcome-risk premiums.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Ontario anchor hub-and-spoke patterns serving suburban orthodontic clinic networks. Thermoplastic polymer supply concentrates in the United States, Germany, and Japan, with polyethylene terephthalate glycol-modified copolymer resin sourcing tethered to petrochemical feedstock markets. Raw material dependencies include multilayer extrusion equipment, precision intraoral scanning hardware, and cloud-based treatment planning software licenses. Single-supplier scanner concentration creates procurement vulnerability for independent practices. Distribution runs through direct sales forces targeting dental service organizations alongside dental office channel partnerships for high-complexity case flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance pathways function as a cost-of-compliance moat, elevating capital requirements for market entry and advantaging incumbents with established predicate device portfolios and regulatory affairs infrastructure.
For Market Incumbents: Anticipate direct-to-consumer brand encroachment by hardening digital workflow integration between intraoral scanners and proprietary fabrication software. Prioritize backward integration into recyclable thermoplastic material development to capture EPA guideline-driven procurement preference. Defensive consolidation through dental service organization exclusive partnerships locks in volume commitment against emerging remote-first competitors. For New Entrants and Emerging Players: Begin with Canadian provincial expansion targeting Ontario and British Columbia dental colleges where teledentistry regulatory openness exceeds United States state-level restrictions. Capture white space in suburban orthodontic clinic subcontracting for mild malocclusion cases requiring rapid turnaround. Anchor go-to-market positioning through asynchronous orthodontist review platforms that compress patient acquisition costs below traditional referral-dependent channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated dental technology conglomerates seeking scanner-to-aligner ecosystem completion. Long-term viability favors platform owners with captive patient data infrastructure and recurring software revenue streams. Acquisition target archetype: specialized thermoplastic fabricators with Health Canada Medical Device Licensing and FDA 510(k) predicate clearance. Monitor Health Canada and FDA submission velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Medical Device Licensing | Streamlined Class II approval timelines reduce cross-border market entry barriers for Canadian manufacturers. |
| AI-Powered Treatment Planning Integration | Machine learning algorithms for predictive tooth movement converge with cloud-based practice management platforms. |
| Recyclable Thermoplastic Development | EPA medical plastics waste guidelines incentivize bio-based material science with preferential procurement positioning. |
| Dental Service Organization Partnership | Volume commitment agreements anchor enterprise account relationships and compress patient acquisition costs. |
| Remote Monitoring Platform Deployment | Telehealth-enabled impression kits expand home user channel penetration in regulatory-permissive provinces. |
Research Methodology
Regulatory filing databases, dental industry trade publications, and medical device clearance records formed the secondary backbone, cross-referenced against primary interviews with orthodontic practice owners, dental service organization procurement leads, intraoral scanner manufacturers, and thermoplastic polymer suppliers. Bottom-up and top-down triangulation validated segment-level demand estimates against aggregate market sizing derived from dental laboratory network capacity and aligner tray production volume indicators.
Bottom-up modeling anchored forecasts to individual orthodontic clinic case volume and patient acquisition economics, while top-down verification cross-checked against dental service organization expansion rates and direct-to-consumer brand marketing spend patterns across the projection horizon. Segmentation dimensions included product type, end user archetype, material category, and distribution channel. CAGRs were derived from iterative tray volume growth trajectories and average selling price evolution in premium versus economy tiers. Forecast inputs incorporated suburban clinic opening rates and telehealth regulatory permissiveness indices.
Underlying measurement precision varies by segment; clear aligner product type and dental clinic end user categories carry tighter precision than emerging home user channel estimates. Forecasts reflect documented assumptions regarding FDA and Health Canada approval timeline stability, petrochemical input cost trajectories, and state-level scope-of-practice enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Regeneration Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Dental Laboratories Market
Dental Devices
Global Dental Lasers Market
Dental Devices
North America Dental Lab Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Dental Impression System Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Dental Splints Market