
 Dental Bonding Agent Market | 2026-2036
Dental Bonding Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Bonding Agent Market Intelligence
The EU Medical Device Regulation is consolidating demand around biocompatible, certified dental bonding formulations that minimize patient sensitivity and ensure long-term restoration integrity. DMG leverages its German manufacturing base to sustain premium positioning in light-cured adhesive systems across European dental clinics. 3M competes through extensive R&D investment in universal bonding agents that reduce procedural steps for dentists. KaVo Kerr anchors North American distribution through integrated dental equipment and consumables portfolios.
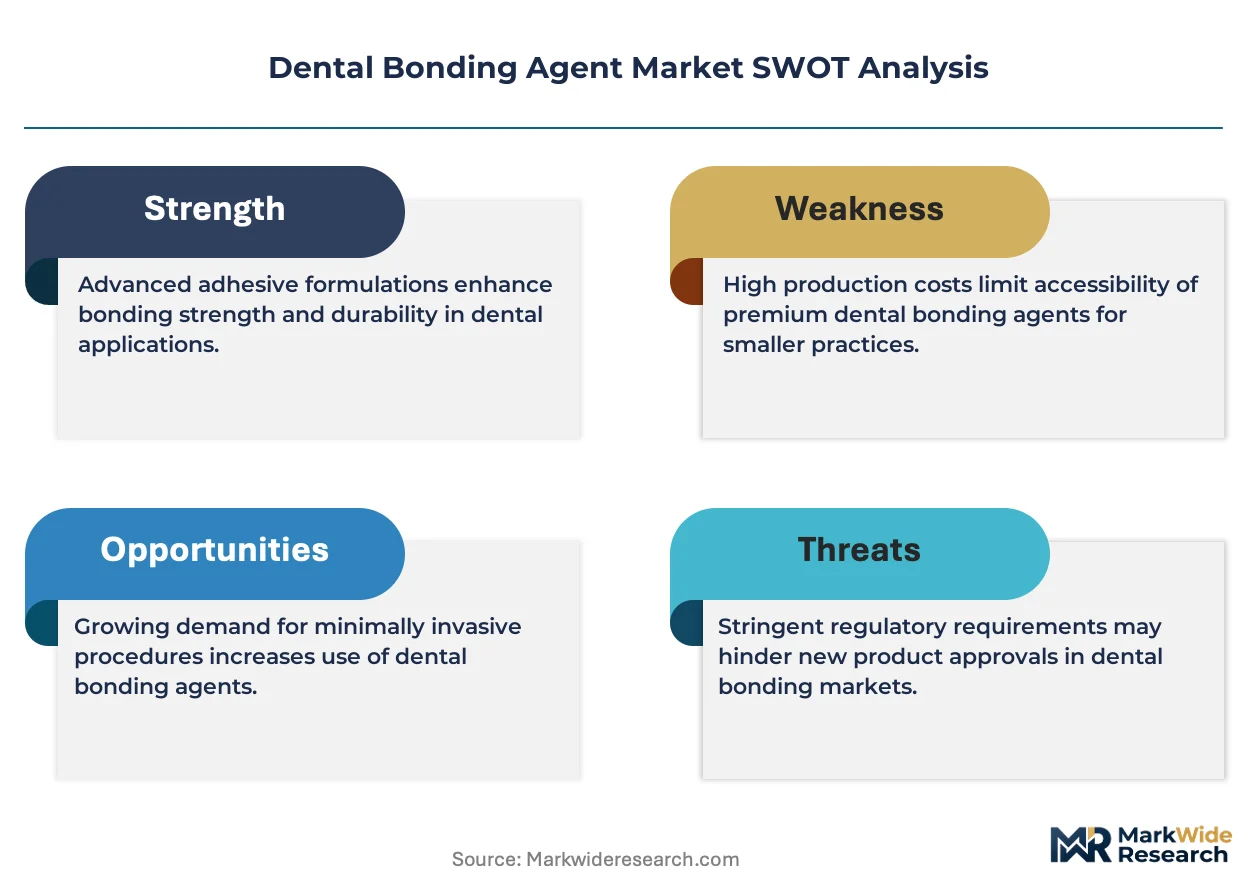
Dental bonding agents are adhesive formulations, typically resin-based or glass ionomer compositions, that chemically and micromechanically unite restorative materials to natural tooth structure through acid-etching or self-etching mechanisms; they function primarily to seal margins, prevent microleakage, and provide durable retention for fillings, veneers, and crowns. Light-cured systems dominate clinical workflows due to controlled setting times and predictable polymerization depth under LED curing lights. Self-adhesive formulations represent the fastest-growing product category as practitioners prioritize reduced technique sensitivity and shorter chairside protocols. Resin-based formulations command the deepest margin pools owing to superior bond strength to enamel and dentin substrates.
FDA clearance pathways and ISO 10993 biocompatibility standards govern market access for dental bonding agents in the United States, while the EU MDR and REACH chemical safety frameworks shape formulation composition across European markets. Japan's PMDA maintains stringent efficacy documentation requirements that filter out lower-tier suppliers from its domestic dental sector. Stakeholders must monitor evolving regulatory convergence between biocompatibility testing and environmental chemical restrictions, as these dual pressures will determine which formulation platforms achieve sustainable commercial scale.
Market Dynamics
The EU Medical Device Regulation is compressing competitive timelines by mandating biocompatibility recertification for all dental bonding agents sold in European clinics, forcing manufacturers to consolidate formulation portfolios around ISO 10993-compliant chemistries.
Growth Catalysts
- Self-etching adhesive chemistry:German orthodontic practices are expanding chairside adoption of single-bottle self-etch systems that eliminate separate phosphoric acid etching steps. This reduces procedure time and technique sensitivity for composite restorations.
- REACH chemical safety frameworks:European manufacturers are accelerating reformulation of resin monomers to eliminate bisphenol-A derivatives ahead of 2026 authorization sunset deadlines. Compliance investments are locking in supplier relationships with certified raw material vendors.
- LED curing light penetration:Brazilian dental clinics are upgrading to high-intensity LED polymerization units that demand matched photoinitiator chemistries in bonding agents. Equipment-biomaterial compatibility is driving brand loyalty in Latin American markets.
Market Restraints
- Acrylic resin price volatility:Fluctuating methacrylate monomer costs tied to petrochemical feedstock markets compress gross margins for light-cured adhesive manufacturers. Formulators lack pricing power to pass through input spikes to contract dental distributors.
- Silane coupling agent supply concentration:Japanese and German chemical suppliers dominate organosilane production for ceramic primer formulations. Any disruption to Asian port logistics immediately constrains universal bonding agent output.
- Bond durability limitations on sclerotic dentin:Aging patient populations present compromised substrate conditions where conventional etch-and-rinse protocols achieve suboptimal micromechanical retention. This technical ceiling restricts indication expansion for certain adhesive classes.
Strategic Opportunities
- Indian dental tourism corridors:Mumbai and Delhi NCR are emerging as hub destinations for aesthetic dentistry attracting Middle Eastern and African patients. Clinics serving this inbound flow prioritize premium bonding systems that support warranty-backed veneer work.
- Bioactive glass ionomer hybrids:Convergence of resin adhesive chemistry with remineralizing glass ionomer technology is opening therapeutic indications for caries-active patients. Formulations releasing fluoride and calcium phosphate ions command price premiums in pediatric segments.
- Direct-to-clinic digital procurement:Specialized e-commerce platforms are disintermediating traditional dental supply distributors in South Korean and Australian markets. Manufacturers building proprietary online portals capture margin previously allocated to wholesale intermediaries.
Industry Challenges
- ISO 10993-5 cytotoxicity testing bottlenecks:Contract laboratories face 14-18 month backlogs for biocompatibility certification required under EU MDR. Product launch timelines stretch unpredictably as manufacturers queue for accredited testing slots.
- Legacy practice management system integration:Chairside inventory tracking software in established US dental groups lacks API connectivity with modern adhesive dispensing systems. Procurement friction from incompatible digital workflows slows new product uptake in consolidated practice networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Bonding Agent Market |
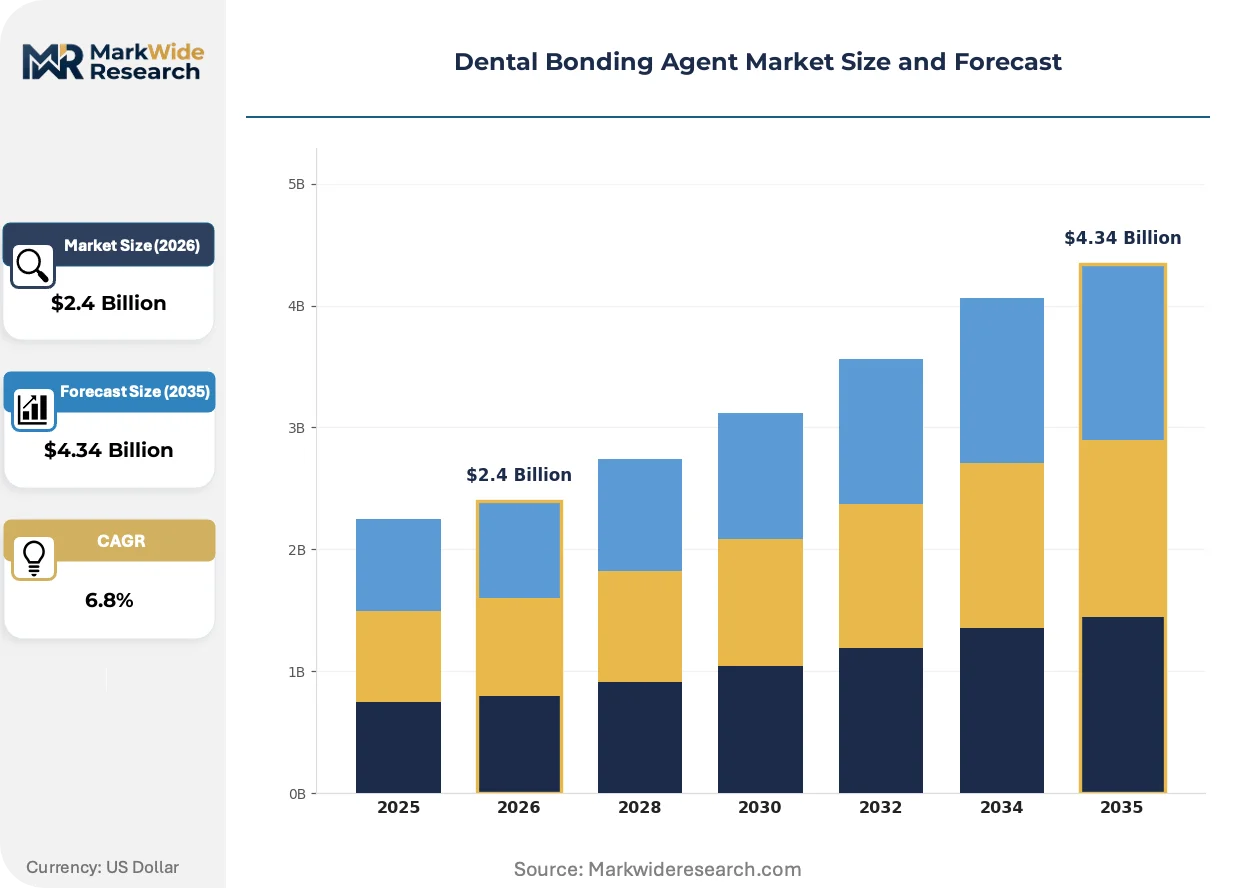
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Cured, Dual-Cured, Self-Adhesive, Total-Etch End User: Dentists, Dental Clinics, Hospitals, Orthodontists Application: Veneers, Fillings, Bonding for Anterior Teeth, Bonding for Posterior Teeth Formulation: Acrylic, Composite, Glass Ionomer, Resin-Based |
| Companies Covered | DMG, Kuraray Noritake Dental, 3M, BISCO Inc, KaVo Kerr, Dentsply Sirona, GC America, VOCO GmbH, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Bonding Agent Market Strategic Shifts & Innovations
Digital chairside workflows are compressing the traditional adhesive selection process from multi-step clinical judgment to algorithm-driven material matching based on intraoral scan data and automated substrate classification.
Universal adhesive systems incorporating multifunctional monomers are automating the decision architecture for dentists selecting between etch-and-rinse, self-etch, and selective-etch protocols. Large dental service organizations in the United States are standardizing procurement around these simplified platforms to reduce training variance across associate dentists. The technology is automating compatibility testing between bonding agents and diverse restorative substrates that previously required manual specification.
Japan's PMDA has tightened documentation requirements for dental adhesive efficacy claims, mandating bond strength data from standardized substrate preparations rather than manufacturer-optimized protocols. This regulatory shift is elevating submission costs for foreign manufacturers seeking market access. European exporters are responding by establishing Tokyo-based clinical testing partnerships to generate compliant performance datasets.
Buying committees at US dental service organizations are consolidating supplier relationships from fragmented multi-brand purchasing to single-source adhesive contracts with volume rebate structures. Traditional independent dental dealers are losing shelf space as these organizations negotiate direct manufacturer agreements. The concentration is most visible in Texas and Florida where private equity-backed practice rollups have achieved sufficient scale to bypass distributor markups entirely.
Dental Bonding Agent Market Segmentation
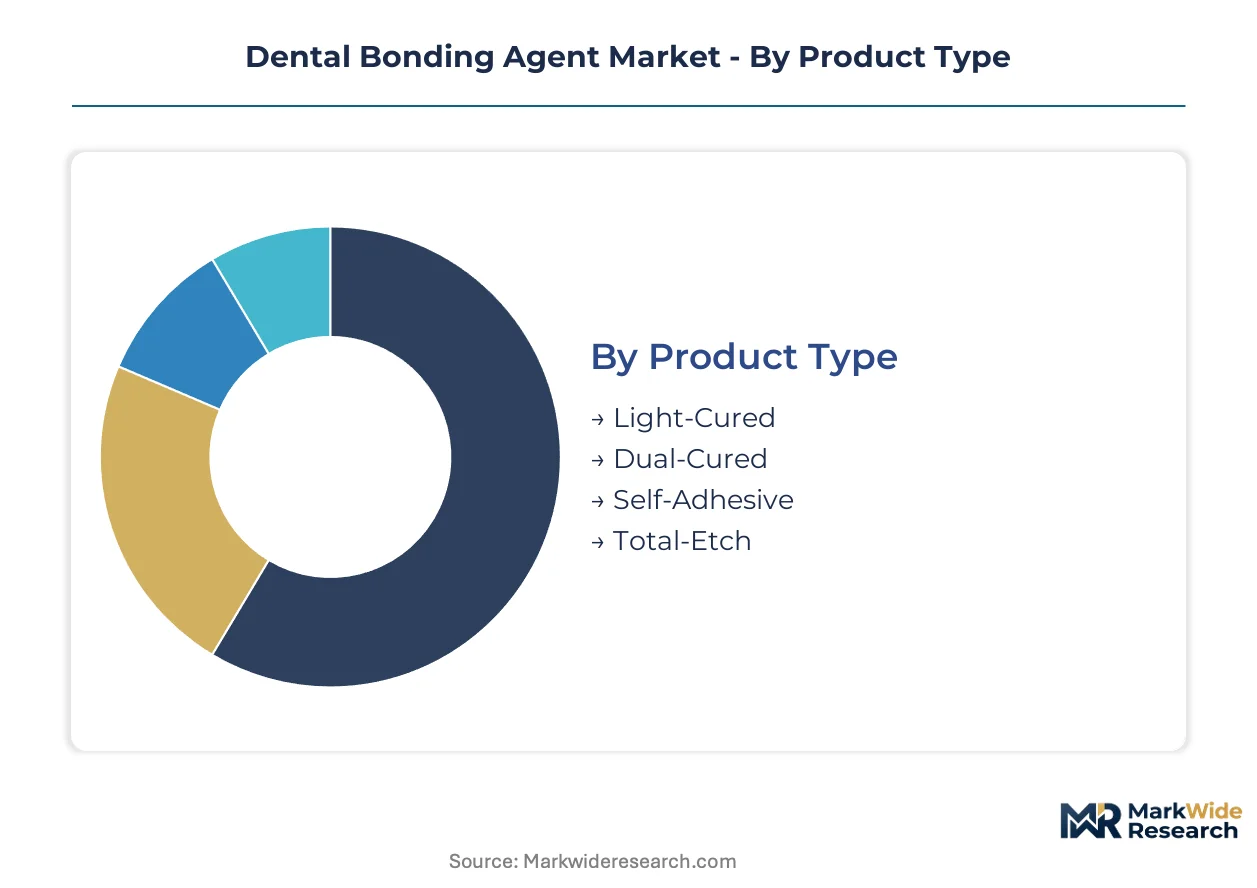
Dental bonding agent procurement patterns diverge sharply across clinical settings, with orthodontic practices driving self-adhesive adoption while hospital systems prioritize bulk universal formulations. Segmentation reveals how substrate complexity, curing infrastructure, and regulatory compliance reshape vendor selection criteria across patient care environments.
Product Type:
Equipment upgrade cycles and LED curing light penetration are redrawing competitive boundaries between adhesive chemistries, as practices modernize polymerization hardware.
- Light-Cured:Photoinitiator-activated resin systems polymerize under LED or halogen curing lights with controlled setting times. Demand concentrates in German and US dental clinics where high-intensity LED units have achieved near-universal adoption, locking in photoinitiator-matched formulations.
- Self-Adhesive:Methacrylate monomer blends incorporating acidic functional groups eliminate separate etching steps. Brazilian and South Korean orthodontic practices are expanding chairside use of these systems to compress procedure times and reduce technique sensitivity for composite restorations.
- Dual-Cured:Hybrid photoinitiator-chemical initiator systems cure through light exposure or self-catalysis in deep preparations. Endodontic post cementation and opaque ceramic substrates drive niche demand.
- Total-Etch:Conventional phosphoric acid etching followed by separate primer and adhesive application. Legacy protocols persist in academic training institutions and cost-sensitive markets.
Volume placements concentrate in Light-Cured systems; the faster expansion belongs to Self-Adhesive formulations.
End User:
Procurement authority and reimbursement structures fragment demand across institutional settings, with consolidated practice networks wielding divergent specification power versus independent operators.
- Dentists:Independent general practitioners represent the deepest volume pool, purchasing through dental supply distributors or direct manufacturer agreements. Texas and Florida dental service organizations are consolidating multi-clinic procurement around single-source adhesive contracts with volume rebate structures.
- Dental Clinics:Multi-chair facilities serving aesthetic dentistry patients prioritize premium bonding systems supporting warranty-backed veneer work. Mumbai and Delhi NCR clinics serving Middle Eastern dental tourism flows specify high-margin universal adhesives.
- Hospitals:Institutional procurement departments negotiate formulary contracts based on biocompatibility certification and bulk pricing. EU MDR compliance requirements filter supplier pools to ISO 10993-certified manufacturers.
- Orthodontists:Specialty practices emphasizing indirect bonding protocols for bracket placement drive demand for precise viscosity-controlled formulations. German orthodontic corridors are expanding self-adhesive resin use for fixed appliance bonding.
Procurement volume aggregates with Dental Clinics; Orthodontists are gaining share fastest through indirect bonding protocol expansion.
Application:
Substrate preparation complexity and aesthetic visibility requirements stratify adhesive performance specifications across anterior versus posterior indications.
- Veneers:Ultra-thin ceramic or composite laminates demand high-translucency adhesives with color stability and marginal seal integrity. Indian aesthetic dentistry hubs specify premium systems for warranty-backed cosmetic work on international patients.
- Fillings:Direct composite restorations in load-bearing cavities require durable enamel-dentin bonding with minimal postoperative sensitivity. US dental service organizations standardize universal adhesive platforms across associate dentists to reduce training variance.
- Bonding for Anterior Teeth:High-visibility substrates mandate polished surface compatibility and shade-matching precision. Japanese PMDA efficacy documentation requirements elevate submission costs for foreign manufacturers seeking anterior indication claims.
- Bonding for Posterior Teeth:Occlusal load-bearing restorations prioritize compressive strength and wear resistance over optical properties. Sclerotic dentin conditions in aging patient populations constrain bond durability for certain adhesive classes.
Fillings dominate placement volume; Veneers command the steepest expansion trajectory through dental tourism growth.
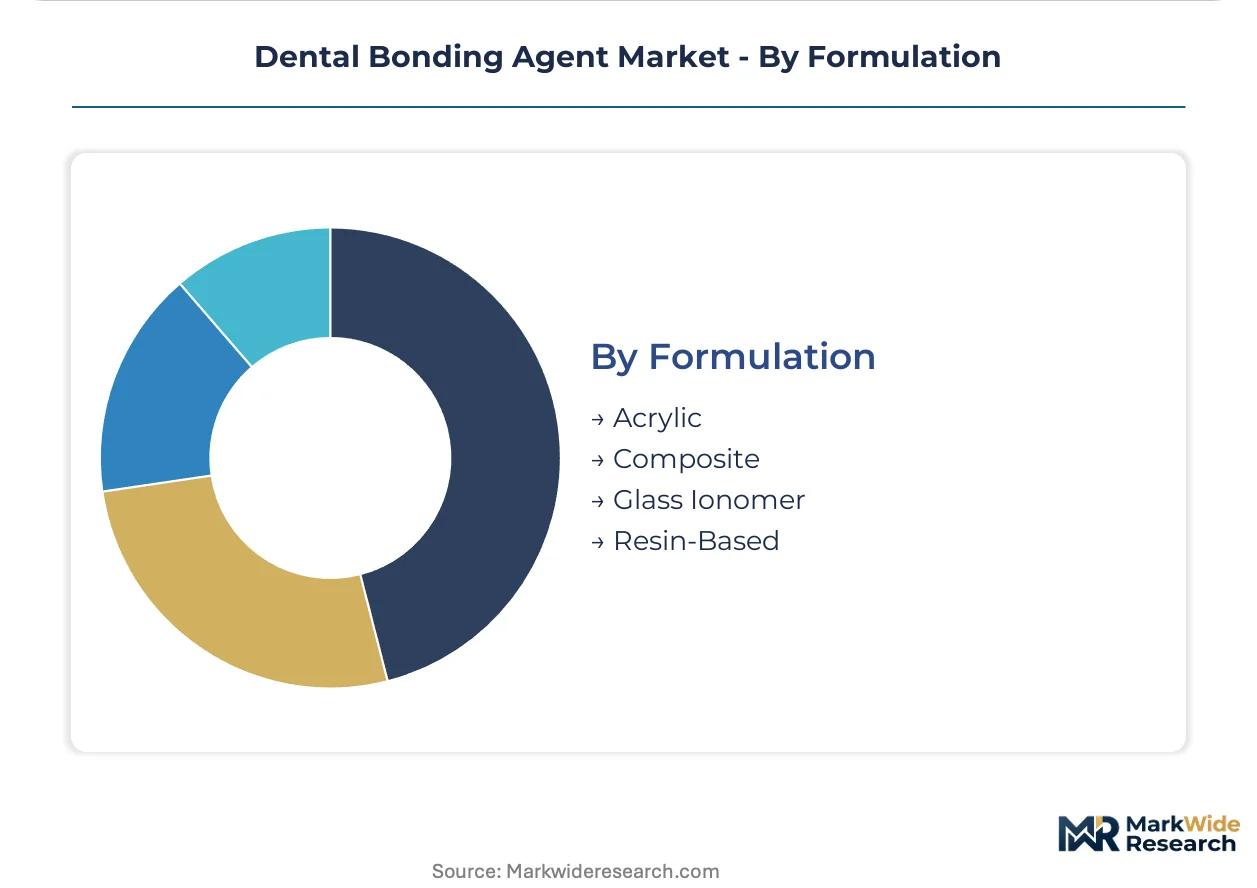
Formulation:
Raw material chemistry and biocompatibility certification costs stratify margin structures across polymer systems, with resin monomer reformulation pressures intensifying under REACH chemical safety frameworks.
- Resin-Based:Methacrylate and dimethacrylate monomer systems provide superior bond strength to enamel and dentin through micromechanical retention and hybrid layer formation. European manufacturers are accelerating bisphenol-A derivative elimination ahead of authorization deadlines.
- Glass Ionomer:Polyalkenoate cement systems releasing fluoride ions target caries-active pediatric patients. Bioactive hybrid formulations incorporating calcium phosphate release command price premiums in therapeutic indications.
- Composite:Filled resin systems balancing mechanical properties with handling characteristics. Silane coupling agent supply concentration in Japanese and German chemical suppliers constrains universal bonding agent output.
- Acrylic:Polymethyl methacrylate-based systems for provisional restorations and specific cementation protocols. Methacrylate monomer price volatility tied to petrochemical feedstock markets compresses gross margins.
Resin-Based formulations anchor volume placement; Glass Ionomer hybrids are climbing fastest through pediatric therapeutic indication expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision dental manufacturing corridor concentrates the highest-value bonding agent production, with Stuttgart and Munich anchoring formulation R&D clusters serving clinics across the EU.
United States
Texas and Florida dental service organizations are consolidating multi-clinic procurement around single-source adhesive contracts with volume rebate structures. FDA clearance pathways govern market access under ISO 10993 biocompatibility standards. The Greater Boston corridor hosts specialized testing laboratories supporting regulatory submissions.
Germany
DMG leverages its German manufacturing base to sustain premium positioning in light-cured adhesive systems across European dental clinics. The EU Medical Device Regulation mandates biocompatibility recertification for all dental bonding agents sold in European clinics. The Stuttgart precision manufacturing zone concentrates formulation expertise for orthodontic self-adhesive systems.
Japan
Japanese and German chemical suppliers dominate organosilane production for ceramic primer formulations serving universal bonding agent output. The PMDA maintains stringent efficacy documentation requirements that filter out lower-tier suppliers from its domestic dental sector. The Kanto region around Tokyo hosts clinical testing partnerships generating compliant performance datasets.
Brazil
Brazilian dental clinics are upgrading to high-intensity LED polymerization units that demand matched photoinitiator chemistries in bonding agents. Equipment-biomaterial compatibility drives brand loyalty in Latin American markets. São Paulo anchors distribution networks reaching aesthetic dentistry practices across the Mercosur region.
India
Mumbai and Delhi NCR are emerging as hub destinations for aesthetic dentistry attracting Middle Eastern and African patients. Clinics serving this inbound flow prioritize premium bonding systems that support warranty-backed veneer work. The country's national pharmaceutical regulator oversees import licensing for dental biomaterials.
Dental Bonding Agent Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and biocompatibility certification depth. The vendor base stratifies into three tiers: multinational dental conglomerates with integrated equipment-consumables portfolios, specialized adhesive formulators with regional manufacturing footprints, and private-label distributors sourcing from contract manufacturers. Two dominant competitive moves are reshaping positioning: direct-to-clinic digital procurement platforms disintermediating traditional supply distributors, and REACH-driven reformulation investments locking in certified raw material supplier relationships.
Within the multinational conglomerate tier, 3M and Dentsply Sirona represent archetypal competitors with diversified dental portfolios spanning equipment and consumables. KaVo Kerr anchors North American distribution through integrated dental equipment and consumables portfolios. Among specialized European formulators, DMG exemplifies premium positioning through German manufacturing proximity to precision dental clinics.
| Leading Market Players |
|---|
| DMG |
| Kuraray Noritake Dental |
| 3M |
| BISCO Inc |
| KaVo Kerr |
| Dentsply Sirona |
| GC America |
| VOCO GmbH |
| Ivoclar Vivadent |
| Others |
Cost & Logistics Intelligence
LED curing light standardization across Brazilian and German dental clinics is compressing formulation costs while concentrating photoinitiator supply among certified chemical suppliers. This equipment-biomaterial coupling simultaneously reduces per-unit adhesive margins and locks manufacturers into single-source photoinitiator dependencies.
Pricing Analysis
Chairside throughput value anchors pricing tiers, with self-adhesive formulations commanding premiums based on procedure-time savings for orthodontists. Three-tier pricing structure across premium universal systems, standard etch-and-rinse kits, and economy glass ionomer bases reflects ISO 10993 certification grade and LED compatibility guarantees. Pricing pressure stems from methacrylate monomer volatility tied to petrochemical feedstock markets. Independent general practitioners in the United States exhibit highest price sensitivity, while Indian aesthetic dentistry clinics serving Middle Eastern dental tourism flows accept steep premiums for warranty-backed veneer systems.
Supply Chain Analysis
ISO 10993-5 cytotoxicity certification gating creates 14-18 month testing backlogs that filter supplier pools to accredited contract laboratories. Raw material concentration centers on German and Japanese organosilane production for ceramic primers, Brazilian photoinitiator blending operations, and Chinese methacrylate monomer synthesis. Silane coupling agent supply concentration in Asian port logistics presents single-source vulnerability. Distribution runs through dental supply distributors in North American and European markets, with direct-to-clinic digital procurement platforms disintermediating traditional wholesale channels in South Korea and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Universal adhesive systems are displacing multi-step etch-and-rinse protocols as the dominant clinical workflow, compressing competitive differentiation to photoinitiator efficiency and biocompatibility certification speed.
For Market Incumbents: Cement supplier relationships with ISO 10993-accredited testing laboratories to secure priority cytotoxicity certification slots ahead of EU MDR recertification deadlines. Lock in long-term organosilane supply agreements with German and Japanese chemical producers to insulate against Asian logistics disruptions. Prioritize backward integration into photoinitiator synthesis to capture margin from LED curing light penetration in Latin American markets. For New Entrants and Emerging Players: The price-point gap between premium universal adhesives and economy glass ionomer systems creates white-space opportunity for mid-tier self-adhesive formulations targeting Indian dental tourism corridors. Target Mumbai and Delhi NCR aesthetic dentistry clinics with warranty-backed veneer adhesive bundles. Pursue direct-to-clinic digital procurement partnerships to bypass entrenched distributor relationships in Australian and South Korean markets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dental conglomerates seeking ISO 10993-certified formulation platforms. Five-to-ten year viability hinges on REACH-compliant bisphenol-A-free resin chemistry investments. Watch for EU MDR enforcement acceleration as the inflection signal triggering consolidation premiums for pre-certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | Eliminates bisphenol-A derivatives ahead of authorization deadlines, locking certified raw material supplier relationships. |
| Direct-to-Clinic Digital Procurement | Disintermediates traditional dental supply distributors, capturing margin previously allocated to wholesale intermediaries. |
| ISO 10993 Certification Investment | Secures EU MDR market access as biocompatibility recertification compresses competitive timelines. |
| LED Photoinitiator Matching | Equipment-biomaterial compatibility drives brand loyalty in Brazilian and German high-intensity curing light markets. |
| Bioactive Glass Ionomer Hybrid Development | Convergence with remineralizing technology opens pediatric therapeutic indications commanding price premiums. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA submission databases, and REACH authorization records, complemented by interviews with dental adhesive formulators, orthodontic practice owners, hospital procurement managers, GPO contracts administrators, and dental supply distributors. Secondary sources included ISO 10993 biocompatibility test reports, LED curing light manufacturer specification sheets, and methacrylate monomer trade flow data. Bottom-up volume estimates from clinic-level procurement patterns were cross-referenced against top-down manufacturer shipment disclosures.
Historical volume trajectories were cross-referenced against clinician panel input regarding protocol adoption rates. The analytical framework segmented demand across product type, end user, application, and formulation chemistry throughout the projection horizon. CAGRs were derived from weighted average of clinician intention-to-adopt surveys and equipment replacement cycle analysis. Forecast inputs incorporated LED curing light penetration curves, EU MDR enforcement intensity assumptions, and dental service organization consolidation rates.
Underlying measurement precision varies by segment; self-adhesive and light-cured system volumes carry tighter precision than dual-cured niche applications due to more visible procurement patterns. Forecasts reflect documented assumptions regarding regulatory enforcement timing and raw material supply continuity. A model refresh is warranted upon material change in EU MDR biocompatibility recertification deadlines or REACH authorization sunset schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Toothpaste Market
Dental Materials
Dental Gypsum Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Putty Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Amalgam Market
Dental Materials
Crack Tooth Syndrome Market