
 Zirconia Based Dental Ceramics Market | 2026-2036
Zirconia Based Dental Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Zirconia Based Dental Ceramics Market Analytics
Dental laboratory supply chains is fragmenting as digital workflow adoption disrupts traditional distributor relationships between milling centers and chairside providers. Straumann leverages its integrated implant-to-restoration platform to control upstream zirconia blank sourcing. Dentsply Sirona anchors North American distribution through its CAD/CAM hardware-software ecosystem. Ivoclar Vivadent differentiates via specialized shading systems that match natural dentition across its zirconia portfolio.
Zirconia based dental ceramics are yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) materials, typically containing three to five mole percent yttrium oxide to achieve flexural strength exceeding 900 MPa for load-bearing dental restorations. These ceramics serve prosthodontic and restorative applications where metal-free biocompatibility and aesthetic translucency prove clinically essential. Blocks dominate product type volume as milling centers standardize on pre-sintered blanks for efficient CNC production. CAD/CAM technology leads fabrication method adoption while 3D printing emerges fastest among additive manufacturing approaches for complex bridge frameworks. Aesthetic dentistry applications command premium positioning within the application mix as patient-driven cosmetic procedures expand.
FDA 510(k) premarket notification requirements govern zirconia dental device commercialization in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards on permanent implantable restorations. ISO 6872 standards for ceramic dental materials provide the international baseline for flexural strength and fracture toughness testing that manufacturers must satisfy for multi-jurisdiction market access. Stakeholders must monitor evolving regulatory divergence between FDA and MDR pathways when allocating clinical trial and registration investments across manufacturing footprints.
Market Dynamics
CAD/CAM workflow standardization is compressing traditional dental laboratory networks as chairside milling and centralized production models displace conventional crown-and-bridge fabrication. This technological inflection is redistributing value capture from distributors toward equipment-integrated material suppliers.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated clearance pathways for ceramic dental devices reduce premarket notification timelines, accelerating product launches for Y-TZP blanks and milled restorations.
- Metal-Free Prosthetic Preference:Patient demand for biocompatible, aesthetic alternatives to PFM crowns is pulling dental clinics toward zirconia-based solutions in anterior and posterior applications.
- German Laboratory Cluster Density:Concentrated precision milling capacity in Stuttgart, Munich, and Cologne anchors European supply, enabling rapid turnaround for CAD/CAM-fabricated restorations.
Market Restraints
- Yttrium Oxide Supply Concentration:Rare earth processing dependence on Chinese refining infrastructure creates input cost volatility for Y-TZP manufacturers.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's stricter requirements for permanent implantable restorations extend registration timelines and inflate compliance costs.
- Hybrid Ceramic Substitution:Resin-matrix ceramics and lithium disilicate alternatives capture price-sensitive aesthetic cases with simpler milling protocols.
Strategic Opportunities
- 3D Printing Bridge Frameworks:Additive manufacturing of complex multi-unit restorations offers geometric freedom beyond subtractive CNC limits, with early adoption visible in German and Swiss dental laboratories.
- China NMPA Biocompatibility Upgrades:Strengthened national standards for dental materials create compliance-driven replacement cycles among domestic manufacturers seeking export certification.
- Direct-to-Clinic Blank Distribution:Bypassing traditional dental distributors through e-procurement platforms and manufacturer-direct contracts captures margin and captures usage data.
Industry Challenges
- CAD/CAM Technician Training Gap:Shortage of operators proficient in digital design software and five-axis milling programming constrains laboratory throughput expansion.
- ISO 6872 Certification Complexity:Multi-jurisdiction flexural strength and fracture toughness testing requirements delay market entry for novel zirconia formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zirconia Based Dental Ceramics Market |
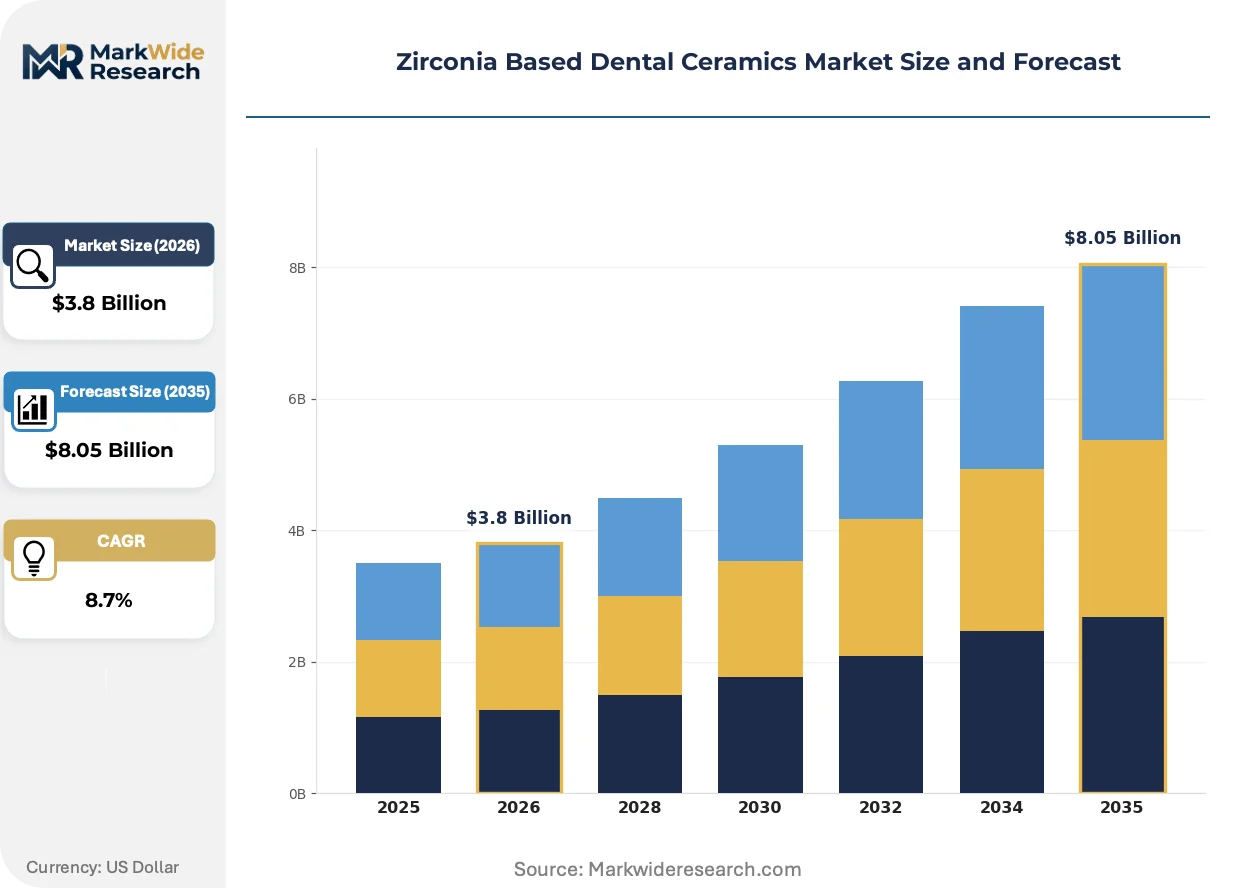
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blocks, Crowns, Bridges, Inlays Application: Prosthodontics, Orthodontics, Restorative Dentistry, Aesthetic Dentistry Technology: CNC Milling, 3D Printing, CAD/CAM, Pressing End User: Dental Clinics, Dental Laboratories, Hospitals, Research Institutions |
| Companies Covered | Straumann, GC Corporation, Dentsply Sirona, Zirkonzahn, Sagemax Bioceramics, Ivoclar Vivadent, VITA Zahnfabrik, Micerium, Nobel Biocare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zirconia Based Dental Ceramics Market Evolving Landscape
Digital dentistry workflows are collapsing traditional production timelines while regulatory divergence between FDA and EU pathways is forcing parallel compliance investments. These forces are compressing margins for non-integrated suppliers while rewarding captive technology ecosystems.
Multi-layer gradient zirconia with discrete translucency zones is rendering obsolete monolithic blocks requiring manual staining and characterization. High-volume milling centers in Germany and the United States are adopting these pre-shaded blanks to eliminate post-milling labor. The technology is compressing restoration turnaround from days to hours while standardizing aesthetic outcomes across technician skill levels.
The EU Medical Device Regulation's clinical evidence requirements for permanent implantable restorations are elevating barrier-to-entry for non-European manufacturers. Companies must now generate prospective clinical data or leverage equivalent device predicates with documented follow-up periods. German and Swiss manufacturers with existing MDR Technical Documentation are capturing share from competitors still navigating notified body backlogs.
Chairside milling adoption by group dental practices is disintermediating regional dental laboratories that historically served single-practitioner clinics. DSOs and multi-location groups in the United States are consolidating procurement through centralized CAD/CAM equipment leases with captive material supply agreements. This concentration is most visible in Florida, Texas, and California where dental practice aggregation has advanced furthest.
Zirconia Based Dental Ceramics Market Segmentation
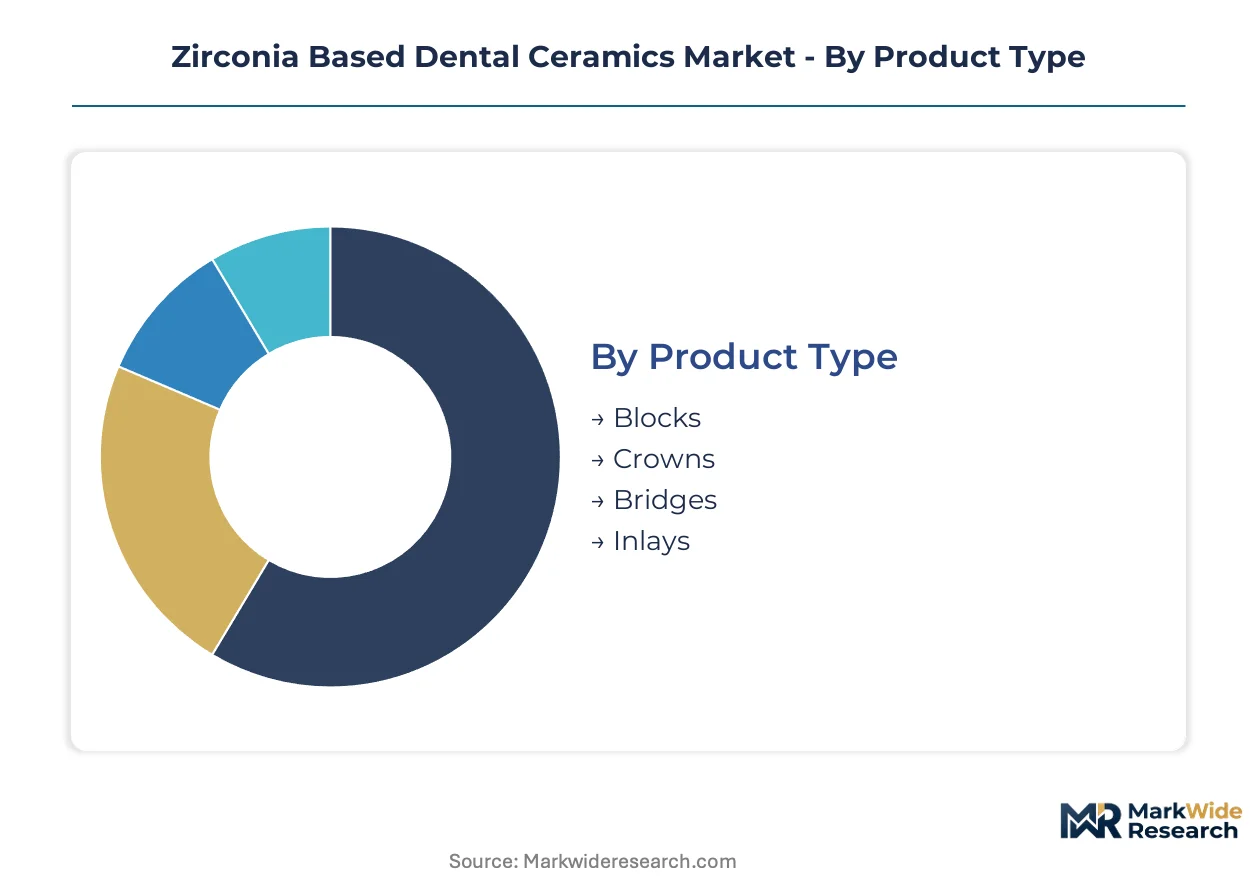
Zirconia dental ceramics fragment across four critical dimensions that determine procurement patterns, margin structures, and technical service requirements. Each segmentation axis reveals distinct competitive dynamics between equipment-integrated suppliers and independent material vendors.
Product Type:
After-sales service intensity varies dramatically across product formats, with pre-sintered blanks demanding minimal technical support while finished restorations require chairside adjustment protocols and warranty management.
- Blocks:Pre-sintered Y-TZP blanks in standardized disc and puck geometries dominate milling center procurement. German precision machining clusters in Stuttgart and Munich anchor European volume, where five-axis CNC workflows consume high-purity zirconia with sub-50-micron grain structures for load-bearing posterior crowns.
- Crowns:Fully contoured monolithic and layered zirconia crowns command premium positioning in aesthetic dentistry. Dental clinics across Florida and Texas DSO networks are consolidating procurement through chairside milling agreements that bundle material supply with equipment maintenance contracts.
- Bridges:Multi-unit frameworks require specialized sintering protocols and connector design optimization for flexural strength distribution.
- Inlays:Conservative restoration formats suit price-sensitive anterior applications with simpler milling parameters.
Blocks hold the largest share; momentum sits with crowns as chairside adoption accelerates.
Application:
Cost tier stratification separates high-value aesthetic procedures from functional rehabilitation cases, with reimbursement differentials driving material selection across patient segments.
- Aesthetic Dentistry:Patient-funded cosmetic procedures demand multi-layer gradient zirconia with discrete translucency zones matching natural dentition. California and Florida dental groups report strongest volume as elective spending concentrates in high-income metropolitan corridors.
- Prosthodontics:Full-arch reconstructions and implant-supported restorations require Y-TZP with flexural strength exceeding 900 MPa. Swiss and German manufacturers with MDR Technical Documentation capture share from competitors navigating notified body backlogs for permanent implantable classifications.
- Restorative Dentistry:Single-tooth replacements and conventional crown-and-bridge work constitute the volume baseline.
- Orthodontics:Temporary anchorage devices and bracket systems utilize zirconia for metal-free biocompatibility in adolescent patients.
Prosthodontics generates the highest absolute revenue; aesthetic dentistry is climbing the fastest as patient-driven cosmetic demand expands.
Technology:
Customer type fragmentation separates high-volume milling centers from chairside clinics, with technology selection determining capital intensity and technician skill requirements.
- CAD/CAM:Integrated design-to-manufacture workflows compress restoration turnaround from days to hours. Dentsply Sirona's hardware-software ecosystem anchors North American adoption through bundled material supply agreements that lock in zirconia blank sourcing.
- 3D Printing:Additive manufacturing of complex bridge frameworks offers geometric freedom beyond subtractive CNC limits. German and Swiss dental laboratories lead early adoption for multi-unit restorations with undercut geometries impossible to mill.
- CNC Milling:Subtractive machining remains the production standard for pre-sintered blank processing.
- Pressing:Heat-pressing of zirconia-reinforced lithium silicate suits smaller laboratories without CAD/CAM capital investment.
CAD/CAM commands current volume leadership; 3D printing shows the steepest expansion trajectory as geometric complexity requirements intensify.
End User:
Supply concentration patterns favor integrated equipment-material platforms as procurement consolidates through DSO networks and centralized laboratory contracts.
- Dental Laboratories:Centralized production facilities in Germany, Switzerland, and the United States process high-volume restoration orders for distributed clinic networks. Straumann's integrated implant-to-restoration platform captures upstream zirconia blank sourcing through exclusive supply agreements.
- Dental Clinics:Chairside milling adoption by group practices disintermediates regional laboratories. Texas and California DSOs consolidate procurement through centralized equipment leases with captive material supply contracts.
- Hospitals:Academic medical centers and oral surgery departments handle complex trauma and oncology reconstructions.
- Research Institutions:Universities and dental schools drive novel formulation development and clinical validation studies.
Dental laboratories retain the largest share; dental clinics are gaining share fastest as chairside workflow adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German milling clusters while cost-sensitive procurement dominates North American DSO networks. This asymmetry fragments margin capture across the value chain.
United States
DSO consolidation in Florida, Texas, and California drives chairside milling adoption through centralized equipment leases. FDA 510(k) streamlining accelerates product launches for Y-TZP blanks. Precision milling centers in Minneapolis and Dallas anchor domestic production capacity for high-volume restoration orders.
Germany
Dense laboratory clusters in Stuttgart, Munich, and Cologne process European restoration demand with sub-50-micron grain structure expertise. EU MDR clinical evidence requirements elevate barriers for non-European competitors. Baden-Württemberg's five-axis CNC infrastructure enables rapid turnaround for CAD/CAM-fabricated prosthetics.
China
Domestic manufacturers upgrade biocompatibility standards to secure NMPA export certification. Yangtze River Delta dental material producers face rare earth processing cost volatility from yttrium oxide supply concentration. Shenzhen milling centers adopt multi-layer gradient zirconia for aesthetic dentistry applications.
Switzerland
Swissmedic-regulated manufacturers capture premium positioning through existing MDR Technical Documentation. Geneva and Basel laboratories pioneer 3D-printed bridge frameworks with geometric freedom beyond subtractive limits. Alpine precision machining heritage supports implant-to-restoration platform integration.
Japan
PMDA standards enforcement drives quality differentiation among ceramic dental material suppliers. Osaka-Kobe manufacturing corridor specializes in high-translucency zirconia for anterior aesthetic cases. METI industrial policy supports dental technology R&D consortia advancing additive manufacturing protocols.
Zirconia Based Dental Ceramics Market Competitive Landscape
Equipment-integrated platforms and independent material suppliers split the market into divergent value-capture models. Straumann's implant-to-restoration ecosystem and Dentsply Sirona's hardware-software bundles concentrate procurement leverage. Three archetypes dominate: captive technology platforms, specialized shading system developers, and precision milling equipment manufacturers. M&A activity targets CAD/CAM workflow integration while direct-to-clinic distribution contracts displace traditional dental distributors.
Among Swiss and German platform operators, Straumann and Ivoclar Vivadent exemplify equipment-integrated archetypes with upstream blank sourcing control. Zirkonzahn anchors the precision milling equipment tier from its Italian base. These three occupy positions where technology bundling determines procurement decisions rather than standalone material pricing.
| Leading Market Players |
|---|
| Straumann |
| GC Corporation |
| Dentsply Sirona |
| Zirkonzahn |
| Sagemax Bioceramics |
| Ivoclar Vivadent |
| VITA Zahnfabrik |
| Micerium |
| Nobel Biocare |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine freight corridors connecting German milling clusters to Swiss precision machining centers impose logistics cost premiums that compound with yttrium oxide refining concentration in China, stratifying final restoration pricing across customization tiers while compressing margins for non-integrated blank distributors.
Pricing Analysis
The customization-premium spread between configured-to-order multi-layer gradient blanks and standard monolithic blocks spans three-tier pricing structure across premium, standard, and economy levels, with ISO 6872 certification grade and five-axis milling complexity as primary differentiation drivers. Price erosion runs through economy-tier pre-sintered discs as Chinese domestic manufacturers upgrade NMPA biocompatibility standards for export qualification. Dental service organizations exhibit highest price sensitivity through centralized equipment lease negotiations, while Swiss prosthodontic laboratories demonstrate lowest sensitivity due to MDR-mandated quality assurance requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with German five-axis CNC specialists in Stuttgart and Munich, Swiss precision machining houses near Basel, and Yangtze River Delta milling centers serving Asian demand. Raw material dependencies draw from Chinese yttrium oxide refining infrastructure, Japanese high-purity zirconia sand processing, and German binding agent formulation expertise. Single-source vulnerability in rare earth supply creates input cost volatility that propagates through blank pricing. Distribution runs through equipment-integrated platforms rather than independent dental distributors as chairside adoption accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from patient-driven aesthetic demand splitting procurement between high-volume milling centers and chairside clinic networks, creating distinct service tiers that reward specialized positioning over scale.
For Market Incumbents: Harden MDR Technical Documentation advantages by accelerating notified body engagement for permanent implantable classifications before competitor backlog clearance. Deepen upstream control over yttrium oxide sourcing through long-term offtake agreements with Chinese refiners, insulating against rare earth price volatility that threatens margin stability in standard-grade blank production.
For New Entrants and Emerging Players: Build out direct-to-clinic e-procurement capabilities targeting Texas and Florida DSO networks consolidating procurement through centralized equipment leases. Capture share in 3D-printed bridge frameworks where geometric complexity requirements exceed subtractive CNC limits, leveraging additive manufacturing partnerships with German and Swiss laboratories pioneering multi-unit restoration protocols.
For Investors and Strategic Acquirers: Specialized shading system developers with Ivoclar Vivadent-type aesthetic matching technology represent priority acquisition targets given patient-funded cosmetic procedure expansion. Long-term viability hinges on CAD/CAM workflow integration depth rather than standalone material pricing power. Monitor FDA 510(k) clearance velocity and EU MDR notified body capacity as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates market access ahead of competitors navigating notified body backlogs for permanent implantable classifications. |
| Yttrium Oxide Supply Agreement | Secures rare earth input pricing stability against Chinese refining infrastructure concentration volatility. |
| Direct-to-Clinic Platform Launch | Bypasses traditional dental distributors to capture margin and usage data from DSO procurement consolidation. |
| 3D Printing Bridge Framework Development | Unlocks geometric freedom for complex multi-unit restorations beyond subtractive CNC machining limits. |
| Multi-Layer Gradient Zirconia Introduction | Eliminates post-milling labor through pre-shaded blanks, compressing restoration turnaround from days to hours. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR Technical Documentation filings, ISO 6872 certification registries, and dental laboratory procurement records. Interviews with CAD/CAM equipment specialists, dental laboratory operations directors, GPO contracts managers, and prosthodontic clinicians combined with bottom-up restoration volume modeling and top-down ceramic materials market sizing.
Forecast inputs include adoption curves for chairside milling versus centralized laboratory production, yttrium oxide price elasticity effects on blank manufacturing costs, and regulatory divergence between FDA streamlined pathways and EU MDR clinical evidence requirements. Segmentation dimensions span product type, application, fabrication technology, and end-user channel structure. CAGRs derive from fitted growth curves against historical restoration procedure volumes and equipment installation base expansion.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by equipment-integrated platforms or accelerated NMPA biocompatibility upgrades by Chinese manufacturers would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance timelines, EU notified body capacity utilization, and DSO equipment lease contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Alginate Market
Dental Materials
Dental Plaster Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Amalgam Market
Dental Materials
Dental Impression Material Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Global Dental Zirconia Block Market