
 Face Primer Market | 2026-2036
Face Primer Market Size, Share, and Industry Trends Forecast 2026-2036
Face Primer Market Analysis
Professional studio and bridal makeup artistry is consolidating as the fastest-rising end-use vertical for face primers. L'Oréal Group leverages its dermatological R&D pipeline to anchor clinical-grade primer credibility across prestige channels. Estée Lauder Companies sustains premium positioning through heritage brand equity and controlled specialty retail distribution. Shiseido Company differentiates with JIS-compliant formulation science targeting Asian skin microbiome research.
Face primer constitutes a cosmetic base layer engineered from silicones, film-forming polymers, and emollients to extend makeup wear time, control sebum, and smooth skin topography for uniform pigment application. Manufacturing employs high-shear emulsification to achieve particle sizes below 50 microns, ensuring optical blurring without visible residue. Hydrating primers lead volume within product type segmentation as consumers prioritize barrier-supporting hybrids over traditional mattifying bases. Liquid formulation dominates manufacturing scale due to pump-dispensing compatibility and lower per-unit fill costs versus stick formats. Pore-filling variants command the strongest margin pools through specialized elastomer content and professional-channel pricing power.
FDA cosmetic registration requirements under the Modernization of Cosmetics Regulation Act reshape U.S. product safety documentation and ingredient disclosure obligations. REACH compliance in Europe restricts certain cyclic silicones, redirecting formulation investment toward plant-derived alternatives and biosynthetic polymers. China's NMPA and GB standards mandate animal-testing exemptions for imported cosmetics, altering global pre-market certification workflows. Stakeholders must monitor regulatory divergence between major markets to avoid reformulation costs and access delays.
Market Dynamics
Clean-label formulation mandates under REACH and FDA Modernization of Cosmetics Regulation Act are forcing manufacturers to abandon cyclic silicones and rebuild supply chains around plant-derived film formers and biosynthetic polymers.
Growth Catalysts
- Professional makeup artistry expansion:Bridal and studio segments in South Korea and the United States are normalizing primer as a non-negotiable base layer, creating pull-through demand for prestige and clinical-grade variants.
- REACH silicone restrictions:The European framework's prohibition on D4/D5/D6 cyclic silicones is redirecting R&D investment toward dimethicone crosspolymers and squalane-based alternatives with comparable optical performance.
- K-beauty routine proliferation:China's tier-one cities and Seoul's consumer base have institutionalized multi-step skincare layering, embedding primer between sunscreen and foundation as a standard step.
Market Restraints
- Specialty elastomer supply concentration:Pore-filling primer variants depend on captive production of spherical silicone elastomers concentrated among Japanese and German chemical suppliers, creating input bottlenecks.
- Reformulation cost compression:Clean-label transitions require complete redevelopment of emulsification protocols and stability testing, extending time-to-market by 18-24 months for established portfolios.
- Color-correcting serum substitution:Tinted skincare hybrids with immediate tone-evening properties are capturing trial budgets from traditional neutral primers among younger demographics.
Strategic Opportunities
- India's emerging prestige channel:The country's expanding specialty retail footprint and dermatologist-dispensed cosmetic protocols remain underpenetrated by clinical primer positioning.
- Men's grooming protocol expansion:Male-identifying consumers in Brazil and Mexico are adopting concealer and foundation routines that require primer for wear extension, opening gender-neutral formulation development.
- GB standards animal-testing exemption:China's NMPA acceptance of alternative safety data is enabling faster import registration for cruelty-free brands previously excluded from domestic e-commerce.
Industry Challenges
- Microbiome claim substantiation:Formulators face capability gaps in clinical testing infrastructure required to support skin-barrier and microbiome-friendly positioning against JIS and ISO standards.
- Cross-regulatory dossier divergence:Separate safety documentation requirements under FDA, REACH, and NMPA are fragmenting product development workflows and preventing single-formula global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Primer Market |
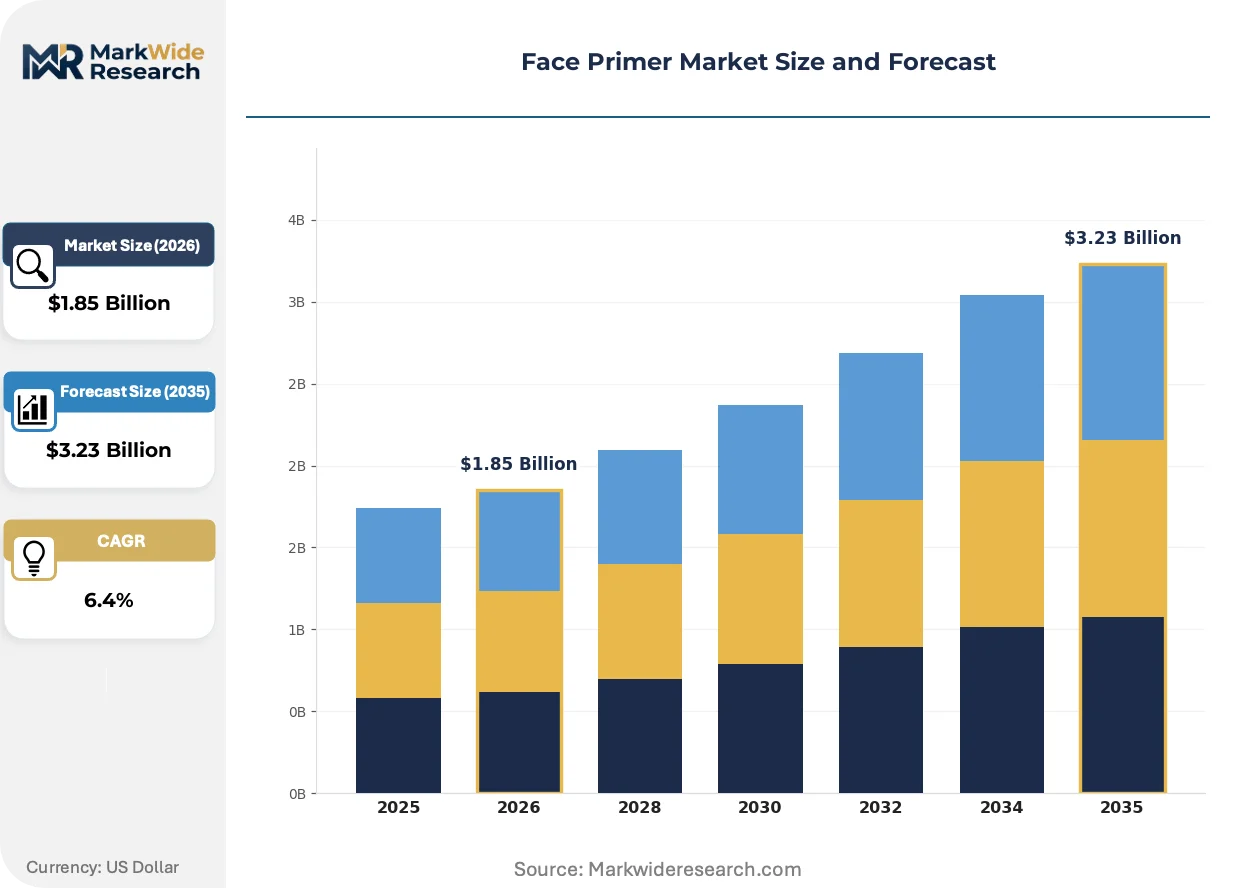
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte, Hydrating, Illuminating, Pore-Filling Formulation: Cream, Gel, Liquid, Stick End User: Professional, Personal, Commercial, Studio Distribution Channel: Online, Supermarket, Specialty Store, Beauty Salons |
| Companies Covered | LVMH Beauty, Kao Corporation, L'Oréal Group, Coty Inc, Revlon Inc, Estée Lauder Companies, Procter & Gamble Beauty, Avon Products Inc, Shiseido Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Primer Market Emerging Trajectories
Biosynthetic polymer chemistry and adaptive texture systems are compressing the performance gap between silicone-dependent legacy primers and next-generation clean-label alternatives. Regulatory pressure and consumer ingredient literacy are converging to reward transparency and clinical substantiation.
Water-dispersible elastomer gels derived from fermentation-based polysaccharides are electrifying texture engineering in hydrating primer segments. Professional makeup artists in Los Angeles and Seoul studios are adopting these formats for their compatibility with water-based foundations and absence of pilling. The shift is compressing demand for traditional dimethicone-heavy bases and forcing incumbent suppliers to license biopolymer production capabilities.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity thresholds in cosmetic-grade silicones. Manufacturers serving European distribution must now certify sub-ppm levels of specified cyclic compounds, adding analytical chemistry overhead to raw material qualification. Asian exporters to the EU are consolidating testing partnerships with ECHA-recognized laboratories to avoid customs detention.
Ingredient transparency apps and searchable INCI databases are shortening consumer consideration cycles and amplifying rejection of undisclosed fragrance components. Clean beauty retailers in New York and London are responding with mandatory full-disclosure policies that disqualify primers with proprietary "parfum" blends. Formulators are pivoting to certified allergen-free fragrance technologies or positioning entirely fragrance-free SKUs to maintain shelf placement.
Face Primer Market Segmentation
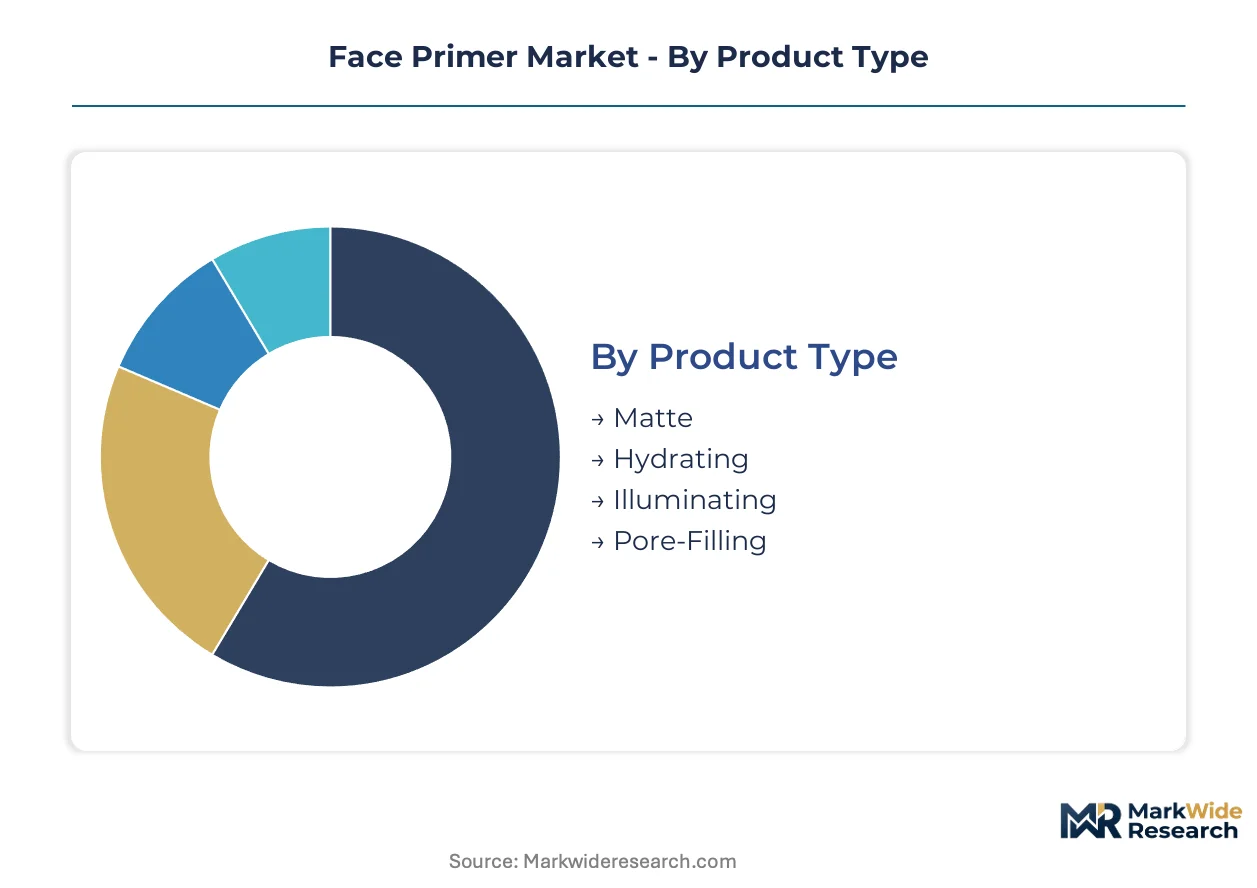
Face primer purchasing patterns fragment across four distinct dimensions, each revealing divergent margin structures and channel access requirements. Manufacturers must align R&D investment with the specific performance thresholds and regulatory sensitivities governing each segment cluster.
Product Type:
Upgrade cycles accelerate as consumers replace legacy silicone-heavy bases with biopolymer alternatives that satisfy REACH and FDA disclosure mandates.
- Hydrating:Hyaluronic acid and glycerin-dominant matrices engineered for barrier-supporting wear under water-based foundations. South Korea's K-beauty cluster drives volume through multi-step routine embedding, with Seoul consumers treating primer as a skincare-makeup hybrid step. Formulators face stability challenges integrating high water-phase content without compromising film-forming integrity.
- Pore-Filling:Spherical elastomer suspensions—silicone-derived or biosynthetic—create optical diffusion across enlarged follicle topography. Professional studio makeup artists in Los Angeles and bridal specialists in Mumbai command premium pricing for immediate skin-smoothing effects. Japanese and German chemical suppliers control captive production of functional elastomers, constraining input availability.
- Matte:Sebum-absorbing silica and clay suspensions targeting humid-climate wear extension.
- Illuminating:Mica and pearl pigment dispersions for light-reflecting base layers in editorial and event makeup.
Volume placements concentrate in Hydrating; the faster expansion belongs to Pore-Filling.
Formulation:
Cost tier stratification separates mass-market pump dispensers from artisanal stick formats commanding 3-4x per-gram pricing.
- Liquid:Pump-compatible emulsions manufactured through high-shear homogenization achieving sub-50-micron particle distribution. China's tier-one city consumers and US prestige channel buyers normalize liquid as the default format, driving manufacturing scale advantages and lowest per-unit fill economics. Compatibility with airless packaging extends shelf stability for clean-label preservative systems.
- Cream:Thicker oil-in-water emulsions packaged in jars or squeeze tubes, concentrated in dermatologist-dispensed and clinical positioning channels. India's emerging specialty retail sector shows particular appetite for cream formats supporting barrier-repair claims. Jar packaging requirements elevate preservative system costs versus liquid alternatives.
- Gel:Water-dispersible biopolymer bases with immediate cooling sensory profiles.
- Stick:Anhydrous wax-and-oil matrices requiring hot-pour manufacturing and higher packaging conversion costs.
Manufacturing throughput peaks with Liquid; margin per unit climbs highest for Stick.
End User:
Application context determines performance specification rigor and repurchase frequency patterns.
- Professional:Makeup artists in bridal, editorial, and film production environments demand batch-to-batch consistency and flash photography compatibility. South Korean studio professionals and US bridal specialists normalize primer as non-negotiable base protocol, creating pull-through demand for prestige-tier supply. Formulators must certify against JIS and ISO color-stability standards for this channel.
- Personal:Individual consumers purchasing through retail and e-commerce channels, with trial behavior concentrated in China's tier-one cities and Brazil's expanding prestige retail footprint. Subscription box sampling and influencer seeding drive initial conversion, with repurchase contingent on texture compatibility with existing foundation wardrobes.
- Commercial:Salon and spa back-bar provisioning for service-incorporated application.
- Studio:Dedicated production facility contracts for film, television, and commercial photography.
Revenue concentration sits with Professional; Personal delivers the steepest expansion trajectory.
Distribution Channel:
Channel selection constrains formulation disclosure requirements and shelf-life specifications.
- Specialty Store:Sephora, Ulta, and equivalent prestige retailers in New York, London, and Seoul mandate full INCI transparency and prohibit proprietary fragrance masking. Clean beauty positioning requires third-party certification (Leaping Bunny, EWG Verified) for shelf placement. Staff education investments convert higher basket attachment rates versus self-service environments.
- Online:Direct-to-consumer and marketplace platforms enabling searchable ingredient databases and review-driven consideration. China's Tmall and Douyin commerce ecosystems concentrate volume for imported cruelty-free brands leveraging NMPA animal-testing exemptions. Return logistics costs escalate for liquid formats versus solid alternatives.
- Supermarket:Mass-market placement requiring price-point compression and broad demographic formulation tolerance.
- Beauty Salons:Professional-only distribution with service-integrated trial and repurchase capture.
Transaction value concentrates in Specialty Store; Online captures the fastest volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in South Korea's Incheon and China's Shanghai Pudong concentrate primer manufacturing capacity for Asia-Pacific export. These bonded logistics parks attract multinational cosmetics firms through tariff exemptions and accelerated customs clearance for raw material imports.
United States
Bridal makeup artistry in Los Angeles and New York City normalizes primer as mandatory base protocol, creating pull-through demand for prestige-tier supply. The FDA Modernization of Cosmetics Regulation Act mandates enhanced ingredient disclosure and safety documentation, extending product development timelines. South Florida's humidity-driven wear-extension needs sustain matte-format demand among personal consumers.
South Korea
Seoul's K-beauty cluster institutionalizes multi-step skincare layering, embedding primer between sunscreen and foundation as standard protocol. The MFDS enforces strict cosmetic safety standards while supporting innovation through the K-Beauty Globalization Initiative. Gangnam district flagship stores and Hongdae influencer studios drive global trend diffusion for water-dispersible biopolymer formats.
China
Tier-one city consumers in Shanghai, Beijing, and Shenzhen treat primer as skincare-makeup hybrid within elaborate daily routines. The NMPA's acceptance of animal-testing alternatives under GB standards enables faster import registration for cruelty-free brands. Hangzhou's live-streaming commerce ecosystem concentrates volume for cross-border e-commerce distribution.
Japan
Tokyo's professional makeup artists demand JIS-certified batch consistency for editorial and commercial production environments. METI's support for biosynthetic polymer R&D redirects formulation investment toward plant-derived film formers. Osaka's chemical suppliers control captive production of spherical elastomers for pore-filling variants.
India
Mumbai's bridal specialists and Bengaluru's expanding specialty retail sector show appetite for clinical-grade primer positioning. The BIS cosmetics standards framework is tightening quality requirements for imported formulations. Delhi-NCR's dermatologist-dispensed cosmetic protocols remain underpenetrated by prestige primer brands.
Face Primer Market Vendor Landscape
Top-tier vendors anchor prestige and clinical-grade positioning, while mid-tier players compete on accessible price points through mass-market distribution. The vendor base stratifies across dermatological R&D capabilities, heritage brand equity, and controlled specialty retail access. Three archetypes dominate: multinational beauty conglomerates with integrated R&D pipelines, regional specialists leveraging local microbiome research, and clean-beauty challengers exploiting regulatory exemptions. Competitive moves concentrate on portfolio diversification into silicone-free alternatives and strategic partnerships with biopolymer suppliers.
Among the multinational conglomerates, L'Oréal Group, Estée Lauder Companies, and Shiseido Company exemplify divergent strategic positioning. L'Oréal Group represents the dermatological-credibility archetype through clinical-grade formulation pipelines. Estée Lauder Companies occupies a position defined by heritage brand equity and controlled specialty retail distribution. Shiseido Company anchors the Asian-skin-science specialization, with JIS-compliant research targeting microbiome-friendly positioning. These three entities collectively illustrate how scale, science, and regional expertise create defensible market positions.
| Leading Market Players |
|---|
| LVMH Beauty |
| Kao Corporation |
| L'Oréal Group |
| Coty Inc |
| Revlon Inc |
| Estée Lauder Companies |
| Procter & Gamble Beauty |
| Avon Products Inc |
| Shiseido Company |
| Others |
Supply Flow & Price Mechanics
Spherical silicone elastomer and biosynthetic polysaccharide raw material costs cascade through three distinct pricing tiers, with Japanese and German chemical suppliers commanding premium positioning for pore-filling primer inputs while mass-market liquid formats compete on per-unit fill economics.
Pricing Analysis
Short lead-time premiums for professional-channel pore-filling primers run 40-60 percent above standard replenishment cycles, while spot inventory of hydrating biopolymer bases trades at modest discounts. Three-tier pricing structure across prestige, specialty, and mass-market levels separates clinical-grade JIS-certified formulations from clean-label alternatives and economy pump-dispense SKUs. Pricing pressure stems from REACH-compliant reformulation overhead extending development timelines 18-24 months. Personal consumers in China's tier-one cities show highest price sensitivity, whereas bridal studio professionals in Los Angeles and Mumbai absorb premium positioning without volume elasticity.
Supply Chain Analysis
Returns of liquid primer formats through China's Tmall and Douyin commerce ecosystems generate reverse-logistics costs 3-4x above stick alternatives, compressing net margins on hydrating and pore-filling variants. Manufacturing concentrates in South Korea's Incheon free-trade zone, China's Shanghai Pudong bonded logistics parks, and Osaka's chemical corridor. Raw material flows draw from Japanese spherical elastomer producers, German biosynthetic polymer specialists, and Indian squalane refiners. Single-source vulnerability sits with captive elastomer production among two Japanese chemical suppliers. Distribution runs through Sephora and Ulta specialty retail in the United States, cross-border e-commerce into China, and dermatologist-dispensed channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The face primer market sits in a technology-transition phase as biosynthetic polysaccharide film formers displace cyclic silicone-dependent legacy formulations under REACH and FDA disclosure mandates.
For Market Incumbents: Acquire biopolymer fermentation capabilities or license production partnerships with Japanese and German chemical suppliers to secure elastomer input continuity. Defensive consolidation requires accelerating JIS-certified microbiome claim substantiation ahead of clean-beauty challengers exploiting China's NMPA animal-testing exemptions. Channel control through Sephora and Ulta staff education investments protects basket attachment rates against direct-to-consumer entrants. For New Entrants and Emerging Players: Live-streaming commerce on China's Douyin and Tmall platforms offers the lowest customer acquisition cost for cruelty-free brands leveraging GB standards compliance. White-space targets concentrate on India's underpenetrated dermatologist-dispensed channel and Brazil's emerging male grooming primer adoption. Go-to-market positioning should anchor on fragrance-free SKUs with searchable INCI transparency to satisfy specialty retail gatekeeping requirements. For Investors and Strategic Acquirers: Shiseido's JIS-compliant microbiome research program filing patents in Tokyo is the leading indicator that Asian-skin-science specialization will consolidate competitive advantage over the next decade. Acquisition targets should screen for captive biopolymer supply agreements or backward integration into fermentation-based raw material production. Monitor ECHA's REACH Annex XVII enforcement actions for cyclic silicone impurity thresholds as the signal for accelerated incumbent portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer R&D Partnership | Fermentation-based polysaccharide development with Osaka chemical suppliers closes silicone-free performance gap. |
| JIS Certification Investment | Tokyo editorial studio demand for batch consistency creates professional-channel pricing power. |
| Cross-Border E-Commerce Launch | Hangzhou live-streaming commerce enables cruelty-free brands to bypass NMPA animal-testing delays. |
| Dermatologist Channel Expansion | Delhi-NCR clinical positioning captures India's underpenetrated prestige primer segment. |
| Fragrance-Free SKU Development | Clean beauty retailer mandates in New York and London disqualify undisclosed parfum blends. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with formulation chemists at multinational beauty conglomerates, regulatory affairs leads navigating FDA and REACH compliance, professional makeup artists in Los Angeles and Seoul studios, and specialty retail category buyers at Sephora and Ulta. Bottom-up triangulation across product-type segmentation and top-down validation against regional import-export flows ensured cross-verification of volume and value estimates.
Granularity-level modeling addressed four dimensions: hydrating versus pore-filling versus matte versus illuminating product types; liquid versus cream versus gel versus stick formulation formats; professional versus personal versus commercial end-user contexts; and specialty store versus online versus supermarket versus beauty salon distribution channels. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in timelines and raw material substitution elasticities. Forecast inputs incorporated K-beauty routine penetration rates in China's tier-one cities and bridal makeup artistry expansion in the United States and India.
The model holds under stable REACH enforcement and NMPA animal-testing exemption continuity; deviation in ECHA cyclic silicone threshold tightening or GB standards reversion would shift reformulation cost assumptions. Practitioners should monitor biopolymer supplier capacity announcements and professional-channel inventory build patterns for early signals of input constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market