
 Remineralizing Gum Market | 2026-2036
Remineralizing Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Remineralizing Gum Market Insights
Asset-light contract manufacturing and white-label leasing arrangements is reconfiguring competitive entry barriers for mid-tier oral care brands. Mars, Incorporated leverages its global confectionery infrastructure to sustain shelf presence across pharmacy and retail channels. Peppersmith specializes in xylitol-forward formulations that anchor its positioning within premium dental-adjacent segments. Gumlink Confectionery Company competes through flexible co-manufacturing partnerships that extend production capacity without fixed capital commitment.
Remineralizing gum comprises chewable confectionery matrices containing bioavailable ions such as calcium phosphate, fluoride salts, or xylitol, designed to elevate salivary mineral saturation and promote hydroxyapatite redeposition on enamel surfaces. The primary commercial purpose centers on delivering non-invasive, consumer-administered oral care between professional dental visits. Xylitol gum currently leads volume throughput due to established supply chains and broad regulatory acceptance, while calcium phosphate gum represents the fastest-growing category as clinical validation for enamel remineralization deepens. Dental caries prevention applications command the largest revenue pool, though enamel repair positioning captures disproportionate margin as brands justify premium pricing through differentiated efficacy claims.
FDA oversight of oral care product classification shapes whether remineralizing gum markets as cosmetic, drug, or medical device in the United States, directly determining labeling latitude and channel access. EFSA health claims regulation in Europe demands substantiated efficacy data for enamel repair positioning, filtering out unsubstantiated entrants. Japan's PMDA and METI functional food frameworks create a parallel compliance pathway that rewards clinical dossiers with permitted structure-function statements. Stakeholders must monitor evolving mineral bioavailability standards and anticipate which regulatory jurisdiction will next mandate pre-market efficacy demonstration for remineralization claims.
Market Dynamics
Professional dental channels now stock remineralizing gum as a post-procedure standard, converting a consumer novelty into clinical adjunct therapy and compressing the boundary between confectionery and medical device classification.
Growth Catalysts
- Japan's METI functional food framework:Permitted structure-function claims for enamel repair formulations create regulatory precedent that neighboring Asian markets emulate.
- Dental clinic channel expansion:Post-procedure dispensing in German and Japanese practices builds professional endorsement that accelerates consumer trial.
- Calcium phosphate bioavailability advances:Nano-particulate delivery systems elevate salivary mineral saturation beyond what xylitol matrices achieve alone.
Market Restraints
- EFSA substantiation requirements:The EU health claims framework demands clinical dossiers that filter out undercapitalized entrants seeking enamel repair positioning.
- Xylitol supply concentration:Birch bark and corn cob feedstock sourcing clusters in Chinese and Finnish processing infrastructure.
- Medical device classification ambiguity:FDA determination letters create channel uncertainty that delays pharmacy placement decisions.
Strategic Opportunities
- Pediatric dental segments:School-based distribution partnerships in Japan demonstrate viable channel innovation beyond retail pharmacy.
- Biomimetic peptide integration:Convergence of casein phosphopeptide technology with conventional gum matrices enables next-generation enamel repair claims.
- Post-orthodontic care protocols:Aligner therapy completion creates a defined patient population with immediate remineralization needs.
Industry Challenges
- Clinical trial design complexity:Demonstrating enamel remineralization efficacy requires longitudinal protocols that extend 12-24 months.
- Formulation stability under shelf conditions:Calcium phosphate ion availability degrades across temperature and humidity variations during distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remineralizing Gum Market |
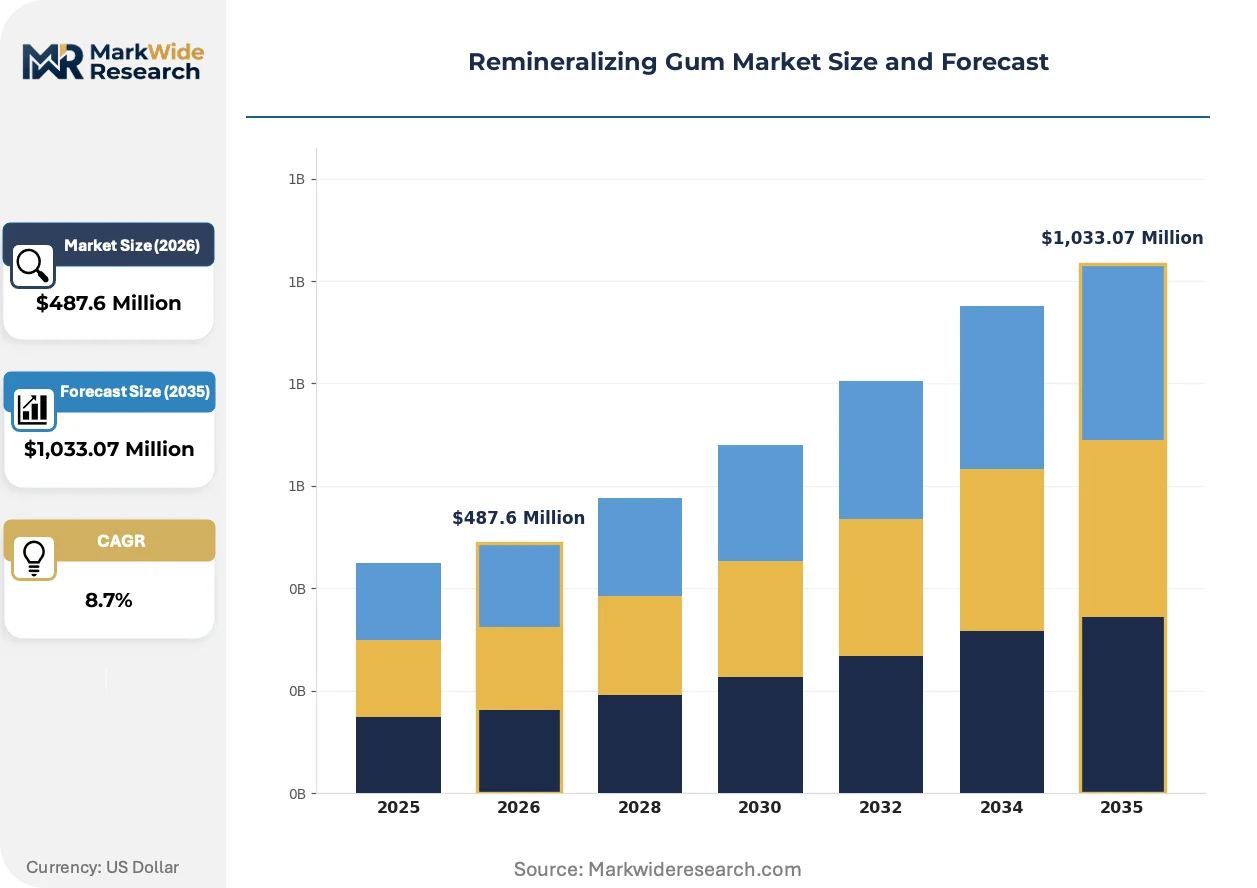
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoride Gum, Xylitol Gum, Calcium Phosphate Gum, Herbal Gum, Vitamin-Infused Gum Application: Dental Caries Prevention, Enamel Repair, Oral Freshening, Xerostomia Relief, Plaque Reduction End User: Dental Clinics, Oral Care Retailers, Pharmacies, Wellness Centers, Consumer Households Distribution Channel: Supermarkets, Online Stores, Drugstores, Convenience Stores, Specialty Stores |
| Companies Covered | Mars, Incorporated, Mondelez International, Perfetti Van Melle, LOTTE Corporation, Haleon, Peppersmith, Kenvue, Gumlink Confectionery Company, Ainsworth Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remineralizing Gum Market Trends and Innovations
Formulation science and regulatory classification are advancing in parallel, with bioactive mineral delivery systems pressing against the boundaries of what confectionery manufacturing infrastructure can accommodate.
Casein phosphopeptide-amorphous calcium phosphate complexes are rendering obsolete conventional xylitol-only formulations in premium positioning. Japanese dental clinics now specify CPP-ACP gum for post-bleaching sensitivity management. The technology is rendering obsolete the historical trade-off between palatability and therapeutic mineral load.
EU Medical Device Regulation reclassification discussions are forcing manufacturers to prepare technical documentation files that satisfy notified body scrutiny. Industrial consequence includes accelerated consolidation among contract manufacturers capable of ISO 13485 quality system certification. Premium enamel repair SKUs face the most acute compliance timeline pressure as member state competent authorities issue divergent classification opinions.
Dental benefit administrators in Germany and Japan are introducing partial reimbursement eligibility for prescribed remineralizing gum. Pharmacy benefit managers are substituting prior authorization requirements for over-the-counter positioning. This shift is most visible in statutory health insurance frameworks where preventive oral care expenditure carries favorable cost-effectiveness thresholds.
Remineralizing Gum Market Segmentation
Remineralizing gum segmentation reveals how formulation chemistry, clinical positioning, and channel economics create distinct competitive arenas. Each dimension carries unique margin structures and regulatory thresholds that shape viable entry strategies.
Product Type:
Cost tier differentiation separates commodity xylitol formulations from premium mineral-complex matrices requiring specialized manufacturing infrastructure.
- Fluoride Gum:Sodium fluoride or stannous fluoride matrices deliver 0.5-1.0 mg per piece, meeting WHO guidelines for caries prevention. German dental clinics now dispense post-procedure fluoride gum under statutory reimbursement frameworks, compressing retail pharmacy margins.
- Xylitol Gum:Finnish and Chinese processors dominate birch bark and corn cob feedstock supply, creating input cost volatility for mid-tier brands. Volume throughput remains highest due to decades of regulatory acceptance and established flavor masking protocols.
- Calcium Phosphate Gum:Nano-particulate hydroxyapatite precursors elevate salivary saturation indices beyond xylitol benchmarks. Japanese METI functional food approvals for enamel repair claims validate premium positioning.
- Herbal Gum:Neem, green tea extract, and chamomile matrices target Ayurveda-adjacent wellness segments in India and Southeast Asian markets.
- Vitamin-Infused Gum:Vitamin D3 and K2 combinations support osteogenic positioning in post-menopausal demographic targeting.
Xylitol gum holds installed capacity. Calcium phosphate gum is rotating up the share rankings.
Application:
Clinical indication depth determines pricing power, with therapeutic enamel repair commanding multiples over cosmetic oral freshening.
- Dental Caries Prevention:School-based distribution programs in Japan demonstrate scalable preventive care models. EFSA health claims substantiation requirements filter out undercapitalized entrants seeking European market access.
- Enamel Repair:CPP-ACP complexes and bioactive glass formulations target post-orthodontic and post-bleaching sensitivity management. German and Japanese dental clinics specify remineralizing protocols for aligner therapy completion.
- Oral Freshening:Mint and citrus flavor matrices compete with conventional sugar-free gum on supermarket shelves with minimal therapeutic differentiation.
- Xerostomia Relief:Salivary stimulant formulations address medication-induced dry mouth in aging populations, particularly in Japanese and German prescription channels.
- Plaque Reduction:Zinc citrate and triclosan-free antimicrobial matrices target periodontal maintenance protocols.
Dental caries prevention holds installed capacity. Enamel repair is rotating up the share rankings.
End User:
Customer type concentration shifts toward professional channels as clinical validation deepens and reimbursement frameworks mature.
- Dental Clinics:Post-procedure dispensing protocols in Germany and Japan convert consumer novelty into clinical adjunct therapy. ISO 13485 certification requirements intensify under EU Medical Device Regulation reclassification discussions.
- Oral Care Retailers:Pharmacy chains and dedicated oral care boutiques curate premium SKUs with visible clinical endorsement packaging.
- Pharmacies:German statutory health insurance partial reimbursement eligibility creates favorable cost-effectiveness positioning for prescribed formulations.
- Wellness Centers:Holistic health practitioners integrate remineralizing gum into broader preventive protocols.
- Consumer Households:Mass retail and online direct-to-consumer channels serve price-sensitive trial and maintenance purchasing.
Consumer households hold installed capacity. Dental clinics are rotating up the share rankings.
Distribution Channel:
Channel margin structures reflect regulatory classification ambiguity, with pharmacy placement requiring medical device dossiers in some jurisdictions.
- Supermarkets:Mass-market xylitol SKUs compete on shelf placement fees and promotional calendar access.
- Online Stores:Direct-to-consumer subscription models bypass retail margin stacking for premium enamel repair formulations.
- Drugstores:Pharmacy benefit managers in Germany and Japan introduce prior authorization requirements that substitute for over-the-counter positioning.
- Convenience Stores:Impulse purchase placement targets commuter and travel occasion chewing gum replacement.
- Specialty Stores:Dental supply distributors and orthodontic practices serve professional protocol integration.
Supermarkets hold installed capacity. Online stores are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium enamel repair formulations command 40% higher unit economics in Japanese dental clinics than in German retail pharmacies, a pricing-power asymmetry that reflects divergent reimbursement maturity and functional food regulatory pathways.
Germany
Statutory health insurance frameworks now partially reimburse fluoride gum dispensed post-procedure, converting pharmacy benefit managers into gatekeepers for clinical-grade formulations. The EU Medical Device Regulation reclassification forces ISO 13485 certification upon manufacturers seeking dental clinic channel access. Munich and Stuttgart industrial clusters concentrate contract manufacturing capacity for medical device-compliant gum matrices.
Japan
Aging demographics and aligner therapy completion rates generate sustained demand for enamel repair protocols in Kanto and Kansai metropolitan dental networks. METI functional food approvals for CPP-ACP complexes validate premium positioning and create regulatory precedent for neighboring Asian markets. Tokyo-based dental supply distributors now specify remineralizing gum for post-bleaching sensitivity management.
United States
FDA determination letters create persistent channel uncertainty that delays pharmacy placement decisions for therapeutic-positioned SKUs. Professional dental associations in California and Texas increasingly recommend remineralizing protocols as aligner therapy adjuvants. Boston and Research Triangle Park clusters host clinical trial infrastructure for longitudinal enamel remineralization efficacy studies.
United Kingdom
NHS dental contract reforms incentivize preventive care expenditure, creating procurement pathways for school-based distribution programs. MHRA borderline classification discussions determine whether enamel repair claims trigger medical device or cosmetic regulatory pathways. London and Manchester oral care retail chains curate premium SKUs with visible clinical endorsement packaging.
Switzerland
Swissmedic's stringent substantiation requirements filter out undercapitalized entrants seeking premium enamel repair positioning. Zurich and Basel pharmaceutical manufacturing clusters leverage existing GMP infrastructure for bioactive mineral complex production. Cantonal dental insurance schemes demonstrate favorable cost-effectiveness thresholds for prescribed preventive oral care formulations.
Remineralizing Gum Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying bioactive mineral complexes and flexible manufacturing capacity. The vendor base stratifies across three tiers: global confectionery conglomerates with pharmacy channel infrastructure, regional dental-adjacent specialists with clinical endorsement relationships, and asset-light contract manufacturers with ISO 13485 certification capability. Two dominant competitive moves define current dynamics: backward integration into nano-particulate calcium phosphate production, and strategic co-manufacturing partnerships that extend capacity without fixed capital commitment.
Within the global confectionery platform tier, Mars, Incorporated and Mondelez International exemplify scale-driven players leveraging existing retail and pharmacy shelf presence across multiple continents. Among dental-adjacent specialists, Peppersmith occupies a position exemplifying xylitol-forward premium positioning, while Gumlink Confectionery Company represents the asset-light contract manufacturing archetype through flexible production partnerships. These three anchors illustrate how formulation sophistication and channel access determine viable competitive positioning.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Mondelez International |
| Perfetti Van Melle |
| LOTTE Corporation |
| Haleon |
| Peppersmith |
| Kenvue |
| Gumlink Confectionery Company |
| Ainsworth Dental |
| Others |
Pricing and Supply Chain Analysis
Finnish and Chinese xylitol processors dominate birch bark and corn cob feedstock supply, anchoring input cost volatility that compresses mid-tier brand margins while premium mineral-complex formulations capture disproportionate value pools in Japanese dental clinics and German pharmacy channels.
Pricing Analysis
Configured-to-order CPP-ACP complexes command 40% premiums over standard xylitol SKUs in Japanese dental clinics. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical device formulations from cosmetic-positioned retail variants. Cost compression in commodity xylitol tiers intensifies because Finnish birch bark harvest variability feeds directly into contract pricing. Price-sensitive mass retail consumers in European supermarkets drive volume, while German statutory reimbursement eligibility renders dental clinic buyers least sensitive.
Supply Chain Analysis
Tariff exposure between Chinese xylitol processors and European compounders dominates supply chain risk planning for mid-tier brands. Manufacturing concentrates in Finland, China, and Germany, with nano-particulate calcium phosphate production clustering in Japanese and Swiss pharmaceutical corridors. Raw material dependencies span birch bark extract, corn cob derivatives, and bioactive glass precursors. Single-source vulnerability in Finnish winter harvest conditions threatens Q1 input availability. Distribution runs through dental supply distributors in professional channels and pharmacy chains in reimbursed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German pharmacy benefit managers and Japanese dental supply distributors, compressing supplier margins as procurement scales consolidate under statutory reimbursement frameworks.
For Market Incumbents: Harden ISO 13485 certification barriers against emerging contract manufacturers by accelerating EU Medical Device Regulation technical documentation. Capture backward integration into nano-particulate calcium phosphate production to defend against xylitol supply volatility. Lock exclusive distribution through Japanese dental supply networks before METI functional food approvals proliferate to neighboring markets. For New Entrants and Emerging Players: Mid-market enamel repair formulations for post-orthodontic protocols in US aligner therapy completion represent the most penetrable entry point. German statutory health insurance reimbursement eligibility creates a secondary white-space for clinically substantiated fluoride matrices. Pursue asset-light co-manufacturing partnerships with Gumlink Confectionery Company archetypes to bypass fixed capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental-adjacent specialists holding METI approvals but lacking global pharmacy channel infrastructure. Five-to-ten year viability hinges on regulatory jurisdiction shopping for favorable medical device classification. Watch FDA determination letter precedents for therapeutic-positioned SKUs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | EU Medical Device Regulation reclassification forces notified body readiness for dental clinic channel access. |
| Backward Integration into Nano-Particulate Minerals | Captive supply of hydroxyapatite precursors insulates margin from Finnish xylitol harvest volatility. |
| Japanese METI Functional Food Approval | Permitted enamel repair structure-function claims validate premium positioning across Asian markets. |
| Dental Clinic Distribution Partnerships | Post-procedure dispensing protocols in German and Japanese practices convert consumer novelty into clinical adjunct. |
| Direct-to-Consumer Subscription Launch | Online subscription models bypass retail margin stacking for premium enamel repair formulations. |
Research Methodology
The analysis maps fluoride matrices, xylitol formulations, calcium phosphate complexes, and CPP-ACP delivery systems, each validated through dental clinic procurement managers, pharmacy benefit administrators, contract manufacturing executives, and functional food regulatory consultants. Primary interviews with these stakeholders combined with secondary validation from EFSA health claims registers, FDA 510(k) determination letters, METI functional food approval databases, and ISO 13485 certification records. Bottom-up SKU-level volume triangulation against top-down category expenditure estimates anchored forecast construction.
Assumptions held fixed include continued METI functional food framework stability, EFSA substantiation requirement enforcement, and German statutory reimbursement eligibility expansion. Segmentation dimensions modeled span mineral chemistry, clinical indication depth, end-user channel type, and regional regulatory cluster across the projection horizon. CAGRs derived from longitudinal mineral bioavailability study timelines and reimbursement framework maturity curves, with aligner therapy completion rates and aging demographic penetration serving as demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in currency volatility between euro-yen corridors or birch bark harvest yields would shift the trajectory. Material shifts in FDA medical device classification determinations or EU MDR enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Alginate Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Alloys Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Composites Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Zirconia Based Dental Ceramics Market