
 Biomaterial Wound Dressing Market | 2026-2036
Biomaterial Wound Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Biomaterial Wound Dressing Market Outlook
Asset-light contract manufacturing and royalty-based licensing is rewriting competitive entry barriers for mid-scale biomaterial suppliers. 3M Company leverages its polymer science heritage to dominate high-performance polyurethane foam platforms. Smith & Nephew PLC anchors its position through specialized collagen matrices for chronic wound biologics. Molnlycke Health Care AB differentiates via channel control across European hospital group purchasing organizations.
Biomaterial wound dressings comprise engineered substrates—collagen matrices, chitosan polysaccharide films, or silk fibroin scaffolds—designed to maintain moist healing environments while enabling cellular infiltration and controlled biodegradation. These materials typically achieve absorption capacities of fifteen to twenty times their dry weight and serve primarily to accelerate closure in exuding wounds where passive gauze fails. Hydrogel and alginate segments lead current revenue pools due to their versatility across burn and surgical applications, while collagen-based platforms represent the fastest-growing material category as clinicians seek bioactive substrates that modulate matrix metalloproteinase activity. Home care end users now command expanding share as reimbursement shifts favor outpatient chronic wound management over institutional stays.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and material validation requirements for manufacturers targeting transatlantic distribution. The EPA and OECD test guidelines further govern cytotoxicity and sensitization protocols that determine which chitosan sourcing and crosslinking chemistries achieve commercial scale. Stakeholders must monitor evolving FDA guidance on antimicrobial claims in wound dressings, as substantiation requirements for silver-ion or PHMB-loaded biomaterials will likely separate premium-positioned suppliers from commodity competitors.
Market Dynamics
Hospital procurement teams now prioritize advanced collagen and chitosan dressings for chronic wound management, compressing purchasing cycles and elevating biocompatibility documentation requirements across supplier bases. This demand concentration is restructuring competitive entry barriers for mid-scale biomaterial suppliers.
Growth Catalysts
- EMA Medical Device Regulation conformity assessments:These assessments are accelerating validation investments by manufacturers targeting transatlantic distribution, filtering out undercapitalized competitors.
- Chitosan polysaccharide films:These bioactive substrates modulate matrix metalloproteinase activity in diabetic foot ulcers, attracting clinician preference in Japan and Germany.
- Home care end users:Reimbursement shifts favoring outpatient chronic wound management over institutional stays are expanding addressable patient populations beyond hospital settings.
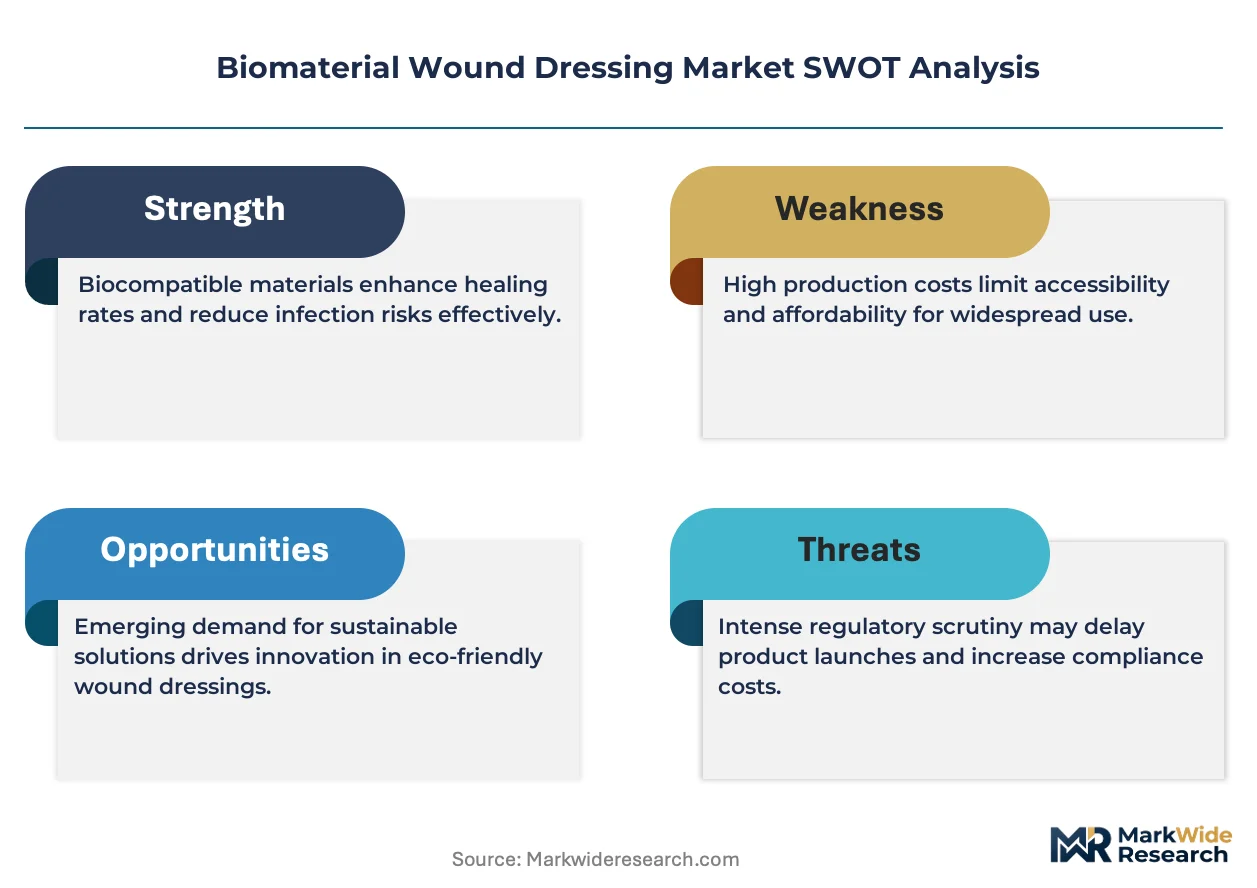
Market Restraints
- Chitosan sourcing concentration:Shellfish supply chains cluster in Southeast Asian coastal regions, exposing manufacturers to climate volatility and trade friction.
- FDA antimicrobial claim substantiation:Evolving guidance on silver-ion or PHMB-loaded biomaterials creates regulatory friction that extends product development timelines by 12-18 months.
- Passive gauze substitution ceiling:Cost-sensitive acute care settings in emerging markets continue defaulting to cotton-based dressings for low-exudate wounds.
Strategic Opportunities
- Silk fibroin scaffolds:Convergence with 3D bioprinting platforms enables patient-specific wound geometry matching in reconstructive surgical applications.
- United States outpatient clinics:Underpenetrated ambulatory surgical centers represent expansion channels as site-of-care migration accelerates.
- EPA and OECD test guideline harmonization:Standardized cytotoxicity protocols reduce redundant validation costs for suppliers pursuing multi-jurisdiction approval.
Industry Challenges
- Crosslinking chemistry expertise:Scarce polymer scientists capable of optimizing chitosan degradation profiles command premium compensation, constraining R&D scaling.
- FDA 510(k) clearance documentation:Predicate device identification and substantial equivalence demonstrations consume 8-14 months of dedicated regulatory affairs capacity.
- Legacy hospital inventory systems:Integration complexity with ERP platforms delays real-time consumption tracking and automated replenishment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomaterial Wound Dressing Market |
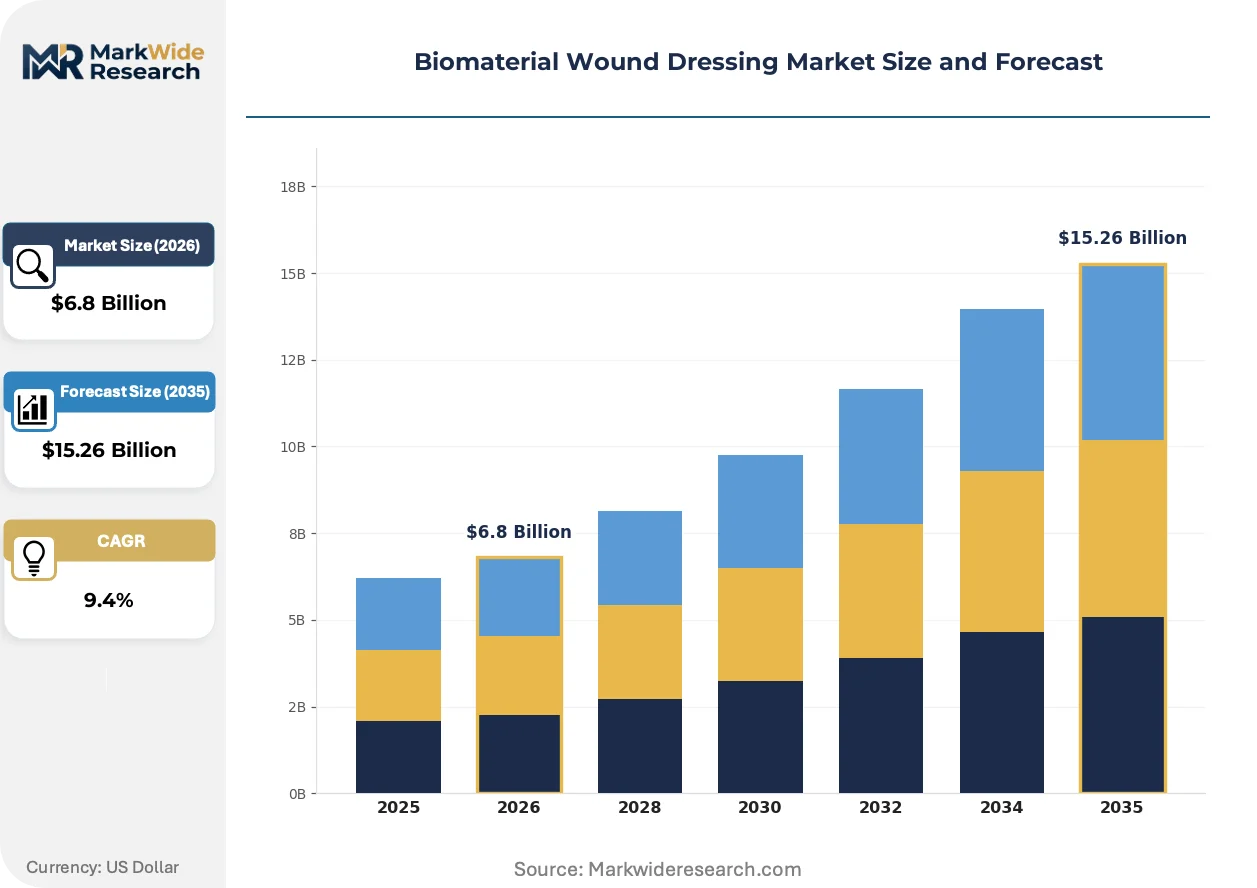
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Foam Dressings, Film Dressings, Alginate Dressings Material: Collagen, Chitosan, Polyurethane, Silk Fibroin End User: Hospitals, Home Care, Ambulatory Surgical Centers, Long-term Care Facilities Application: Burns, Surgical Wounds, Chronic Wounds, Traumatic Injuries |
| Companies Covered | 3M Company, ConvaTec Group PLC, Smith & Nephew PLC, Molnlycke Health Care AB, B. Braun SE, Integra LifeSciences Corporation, Hollister Incorporated, Coloplast A/S, Solventum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomaterial Wound Dressing Market Strategic Shifts
Active healing substrates are displacing passive moisture management as the dominant design paradigm, with clinicians demanding dressings that directly modulate cellular activity rather than merely maintaining environmental conditions.
Electrospun nanofiber collagen matrices achieve absorption capacities of fifteen to twenty times their dry weight while enabling controlled biodegradation synchronized to wound closure rates. Burn centers in the United States and Germany are adopting these platforms for partial-thickness injuries, rendering obsolete conventional hydrogel sheets that require more frequent changes and disrupt granulation tissue formation.
REACH substance restrictions and EU MDR biocompatibility requirements are tightening material traceability mandates for chitosan crosslinking agents and residual protein content. Manufacturers must now document supply chain provenance back to shellfish harvest locations, with collagen-based platforms facing the most intensive audit burden due to bovine spongiform encephalopathy transmission concerns.
Group purchasing organizations now bundle advanced wound care with total cost-of-care contracts, unbundling legacy fee-for-service dressing procurement. Hospital systems in Germany and Japan are piloting episode-based reimbursement models where dressing selection directly impacts margin realization, shifting purchasing authority from individual clinicians to centralized value analysis committees.
Biomaterial Wound Dressing Market Segmentation
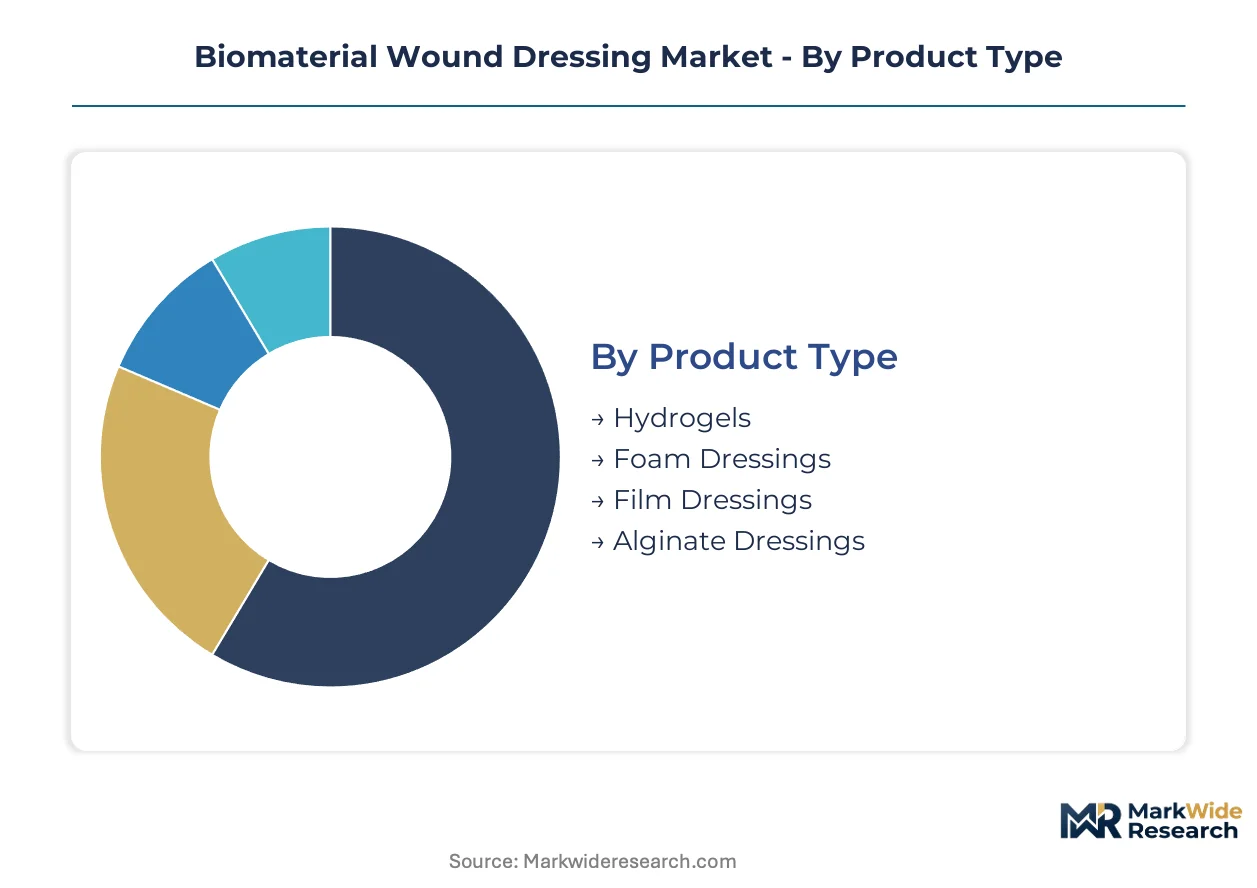
Segmentation in biomaterial wound dressings reveals divergent technology requirements across clinical settings. Material selection and product architecture determine reimbursement eligibility, regulatory pathway complexity, and procurement channel access.
Product Type:
Cost tier stratification separates commodity moisture management from premium bioactive platforms commanding specialized reimbursement codes.
- Hydrogels:Crosslinked polymer networks containing 90% water content maintain moist environments for autolytic debridement in partial-thickness burns. Demand concentrates in United States burn centers where Medicare reimbursement favors extended wear time over frequent dressing changes.
- Foam Dressings:Hydrophilic polyurethane matrices achieve absorption capacities exceeding fifteen times dry weight while maintaining vapor transmission balance. German hospital group purchasing organizations prioritize these platforms for moderate-to-heavy exudate management in post-surgical applications.
- Film Dressings:Semi-permeable polyurethane membranes enable oxygen exchange while blocking liquid water and bacterial ingress.
- Alginate Dressings:Calcium-sodium salt fibers derived from brown seaweed form gel matrices upon contact with wound exudate.
Hydrogels hold installed capacity. Foam dressings is rotating up the share rankings.
Material:
Application requirements dictate material selection, with bioactive substrates displacing passive polymers in chronic wound protocols.
- Collagen:Denatured extracellular matrix proteins modulate matrix metalloproteinase activity and attract fibroblasts to non-healing wound beds. Japanese clinicians favor these substrates for diabetic foot ulcers where accelerated granulation tissue formation reduces amputation risk.
- Chitosan:Deacetylated chitin polysaccharides exhibit intrinsic antimicrobial properties and hemostatic functionality through platelet aggregation. Demand clusters in Southeast Asian manufacturing corridors where shellfish processing waste provides feedstock proximity.
- Polyurethane:Segmented block copolymers enable tunable hydrophilicity and mechanical compliance in foam and film architectures.
- Silk Fibroin:Bombyx mori-derived proteins offer slow biodegradation kinetics and minimal inflammatory response in reconstructive applications.
Polyurethane holds installed capacity. Collagen is rotating up the share rankings.
End User:
Customer type determines purchasing authority structure, with institutional procurement teams diverging from individual clinician decision-making in outpatient settings.
- Hospitals:Centralized value analysis committees evaluate total cost-of-care impact across dressing selection, nursing labor, and length-of-stay metrics. United States health systems increasingly bundle wound care into episode-based reimbursement contracts.
- Home Care:Patients and family caregivers manage dressing changes without clinical supervision, driving demand for intuitive application and extended wear intervals. German reimbursement shifts toward outpatient chronic wound management expand addressable populations beyond institutional settings.
- Ambulatory Surgical Centers:Procedure-specific dressing protocols prioritize rapid application and minimal follow-up requirements.
- Long-term Care Facilities:Staff turnover challenges necessitate simplified product training and reduced technique sensitivity.
Hospitals hold installed capacity. Home care is rotating up the share rankings.
Application:
Volume distribution across wound etiologies reflects demographic disease burden and surgical procedure mix in target geographies.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries require sustained bioactive intervention due to pathological healing environments. United States Medicare expenditure on these indications drives manufacturer R&D prioritization toward collagen and antimicrobial-loaded platforms.
- Surgical Wounds:Incisional closure support demands predictable absorption profiles compatible with primary closure techniques. Japanese surgical volume concentration in metropolitan hospital clusters creates procurement scale advantages for standardized product configurations.
- Burns:Partial and full-thickness thermal injuries necessitate conformable coverage with controlled evaporative cooling.
- Traumatic Injings:Acute mechanical tissue disruption requires rapid hemostasis and contamination barrier functionality.
Surgical wounds hold installed capacity. Chronic wounds is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where hospital group purchasing organizations extract volume discounts, while Japanese procurement maintains premium positioning through technology-weighted evaluation criteria.
United States
Medicare expenditure on diabetic foot ulcers and pressure injuries drives hospital procurement of collagen-based platforms. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting institutional distribution. Burn centers in Texas and California adopt electrospun nanofiber matrices for partial-thickness injuries, displacing conventional hydrogel sheets.
Germany
EMA Medical Device Regulation conformity assessments filter undercapitalized competitors from transatlantic distribution channels. Episode-based reimbursement models piloted in Bavaria and North Rhine-Westphalia shift purchasing authority to centralized value analysis committees. Hospital group purchasing organizations in the Eindhoven-Randstadt corridor prioritize polyurethane foam platforms for post-surgical applications.
Japan
Aging demographics and metropolitan hospital concentration in Tokyo and Osaka create procurement scale advantages for standardized product configurations. PMDA biocompatibility standards govern collagen sourcing validation requirements. Clinicians in Kansai favor bioactive substrates for diabetic foot ulcer management where accelerated granulation reduces amputation risk.
United Kingdom
NHS England procurement frameworks favor total cost-of-care contracts bundling advanced wound care with nursing labor metrics. MHRA post-Brexit regulatory autonomy creates divergence from EMA validation timelines for chitosan crosslinking chemistries. Research clusters in Cambridge and Oxford drive silk fibroin scaffold development converging with 3D bioprinting platforms.
China
NMPA medical device registration requirements intensify documentation burdens for imported collagen matrices. Shellfish processing corridors in Zhejiang and Fujian provinces provide chitosan feedstock proximity for domestic manufacturers. Yangtze River Delta hospital systems expand outpatient chronic wound management capacity under reimbursement shifts favoring home care.
Biomaterial Wound Dressing Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying engineered substrates to branded finished-goods manufacturers. The vendor base stratifies across three tiers: multinational conglomerates with polymer science heritage, mid-scale biomaterial suppliers leveraging asset-light contract manufacturing, and regional specialists concentrating on single material categories. Two strategic archetypes dominate: diversified healthcare conglomerates defending margin through vertical integration into raw material sourcing, and focused wound care specialists capturing share via regulatory-first entry into chronic wound protocols. Competitive moves concentrate on M&A for crosslinking chemistry capabilities and strategic partnerships with 3D bioprinting platform developers.
Within the diversified healthcare conglomerate tier, 3M Company and Smith & Nephew PLC exemplify platform integrators leveraging polymer science and collagen matrix expertise respectively. Molnlycke Health Care AB occupies a position among European channel controllers specializing in hospital group purchasing organization penetration. These three entities represent contrasting geographic anchoring—American, British, and Swedish—that shapes their regulatory navigation strategies and procurement channel access across FDA, MHRA, and EMA jurisdictions.
| Leading Market Players |
|---|
| 3M Company |
| ConvaTec Group PLC |
| Smith & Nephew PLC |
| Molnlycke Health Care AB |
| B. Braun SE |
| Integra LifeSciences Corporation |
| Hollister Incorporated |
| Coloplast A/S |
| Solventum |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam freight corridors transmit cost volatility from Southeast Asian shellfish processing clusters through to European hospital group purchasing organizations, compressing margins for chitosan-dependent suppliers while amplifying price premiums for collagen matrices with documented bovine sourcing provenance.
Pricing Analysis
The customization-premium spread separates standard polyurethane foam platforms from patient-specific electrospun nanofiber configurations, with the latter commanding reimbursement code advantages in United States burn centers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification grade, and volume scale commitments from German hospital systems. Pricing pressure stems from Medicare episode-based reimbursement pilots that bundle dressing costs with nursing labor metrics. Home care segments exhibit highest price sensitivity due to out-of-pocket exposure, while academic medical centers prioritize bioactive performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza and Catalent holding biopolymer processing capacity for collagen crosslinking, while specialized chitosan extraction clusters dominate Zhejiang and Fujian provinces. Raw material dependencies draw from Indonesian shrimp shell waste streams, German polyurethane precursor chemicals, and Japanese silk fibroin cultivation. Single-source vulnerability concentrates in Southeast Asian shellfish harvests exposed to climate-driven supply interruptions. Distribution runs through hospital group purchasing organizations in the United States and Germany, with direct-to-clinic channels expanding in Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biomaterial wound dressing market constitutes a high-growth disruption propelled by EMA Medical Device Regulation conformity assessments that filter undercapitalized competitors and elevate validation investment thresholds for transatlantic distribution.
For Market Incumbents: Insulate market position through backward integration into collagen sourcing networks with full bovine spongiform encephalopathy traceability documentation, while expanding captive chitosan extraction capacity in coastal Southeast Asian corridors to neutralize climate-driven supply volatility. Prioritize crosslinking chemistry R&D investments that accelerate biodegradation profile optimization ahead of emerging silk fibroin scaffold competitors.
For New Entrants and Emerging Players: Pursue regulatory-first entry into United States outpatient chronic wound management segments where reimbursement shifts favor home care channels over institutional procurement. Target ambulatory surgical centers in underserved Midwestern states with simplified application protocols that reduce technique sensitivity for high-turnover nursing staff. Leverage asset-light contract manufacturing partnerships to bypass capital-intensive biopolymer processing infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core wound care divisions with underutilized polymer science platforms but intact FDA 510(k) predicate device libraries. Long-term viability centers on acquisition of specialized crosslinking chemistry capabilities that command scarce scientific talent premiums. Monitor FDA guidance evolution on antimicrobial claim substantiation as the critical inflection signal separating premium-positioned suppliers from commodity competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access through predicate device equivalence demonstrations for collagen matrices. |
| EMA MDR Conformity Assessment | Filters undercapitalized competitors from transatlantic distribution channels. |
| Hospital GPO Partnership | Secures volume commitments through episode-based reimbursement contract bundling. |
| Crosslinking Chemistry Acquisition | Captures scarce polymer science talent for chitosan degradation optimization. |
| 3D Bioprinting Platform Integration | Enables patient-specific wound geometry matching in reconstructive surgical applications. |
Study Parameters
The analysis maps hydrogel, foam, alginate, and collagen matrix sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at transatlantic manufacturers. Primary interview data triangulates against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare expenditure reports, and hospital procurement contract repositories. Bottom-up segment sizing reconciles with top-down macroeconomic indicators across the analysis window.
Assumptions held fixed include EMA Medical Device Regulation enforcement timelines and Medicare reimbursement code stability for bioactive dressings, while variables incorporated shellfish supply chain volatility and antimicrobial claim substantiation evolution. Segmentation dimensions span material chemistry, wound etiology application, end-user setting, and regional regulatory cluster. CAGRs derive from installed base erosion rates and adoption curve modeling for emerging substrate technologies, with inputs from diabetic foot ulcer incidence projections and surgical procedure volume trajectories.
Sensitivities concentrate around FDA guidance revisions for silver-ion loaded biomaterials and climate-driven interruptions to Southeast Asian chitosan feedstock harvests. Quarterly review of EMA notified body capacity constraints and Medicare episode-based reimbursement pilot expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Scaffold Materials Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Flowable Hemostats Market
Biomaterials
US Heparin Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Atelocollagen Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
North America Chitosan Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market