
 Global Self-Adhesive Vinyl Films Market | 2026-2036
Global Self-Adhesive Vinyl Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Adhesive Vinyl Films Market Foresight
Automotive fleet branding is expanding as a primary demand vertical for self-adhesive vinyl films, displacing traditional paint-based commercial vehicle identification. 3M Company leverages its multi-layer casting technology to sustain premium positioning in vehicle wrap applications across North America. ORAFOL Europe GmbH anchors European supply through its Berlin-area manufacturing complex, while Avery Dennison Corporation competes on channel control via direct-to-fleet distributor networks.
Self-adhesive vinyl films consist of polyvinyl chloride or polyolefin layers coated with pressure-sensitive adhesives, typically ranging from 50 to 200 microns in caliper, engineered for conformability to curved substrates and UV resistance. Cast vinyl dominates premium vehicle wrap and architectural applications due to dimensional stability and absence of memory effects, while calendered vinyl occupies high-volume signage and promotional graphics where cost efficiency outweighs longevity requirements. Printable vinyl segments are capturing margin pools as wide-format inkjet compatibility becomes a baseline specification rather than a specialty feature.
FDA indirect food contact standards constrain adhesive chemistries in labeling applications, while REACH and RoHS frameworks in Europe restrict heavy metal stabilizers and certain plasticizers in vinyl formulations. China's GB standards and the EU's F-Gas Regulation collectively shape material substitution timelines for solvent-based manufacturing processes. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
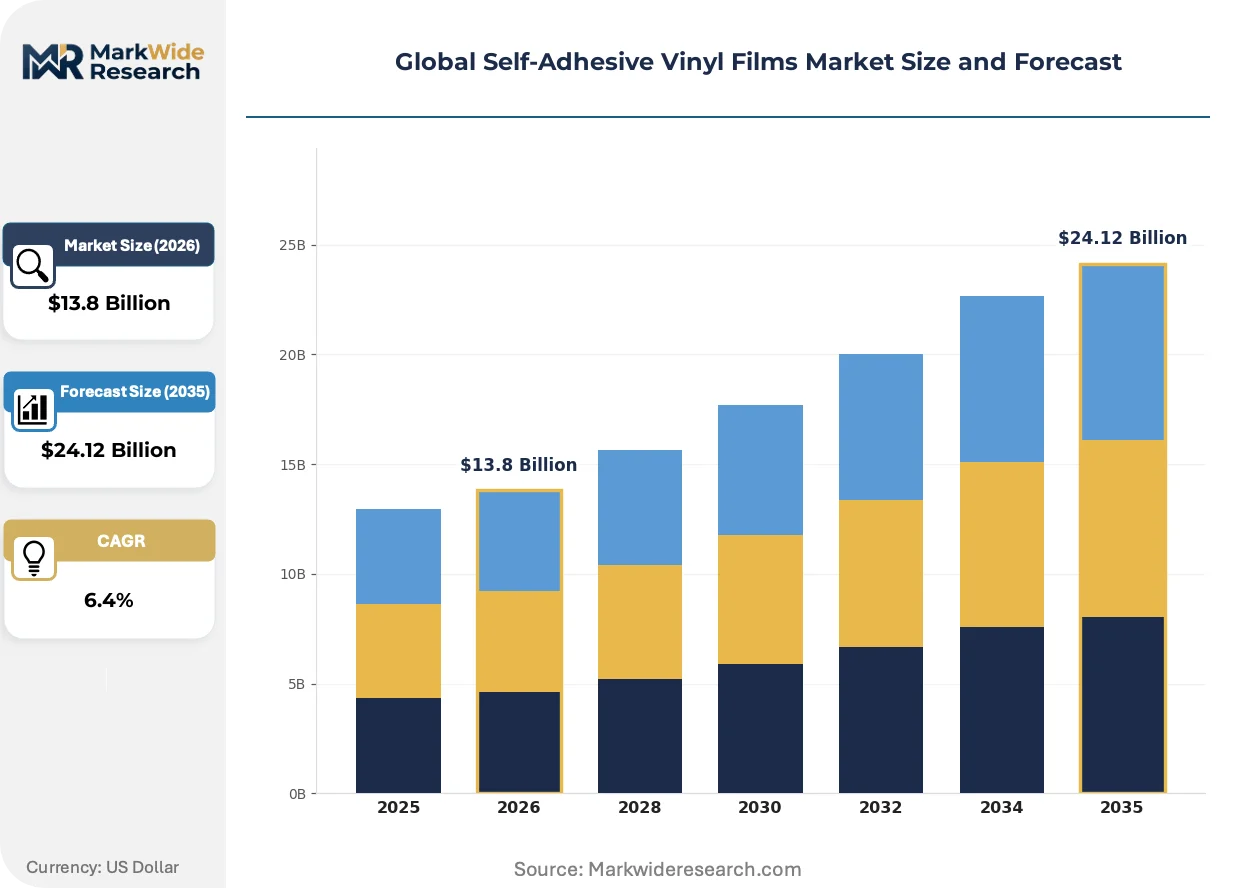
Market Dynamics
Fleet operators in Germany, the United States, and China are phasing out paint-based vehicle identification in favor of removable vinyl wraps, compressing replacement cycles from seven years to eighteen months and rewiring procurement specifications across logistics networks.
Growth Catalysts
- Automotive fleet wraps:Commercial vehicle operators in the United States and Germany are adopting full-body vinyl applications for brand consistency and asset resale flexibility.
- REACH phthalate restrictions:ECHA enforcement is redirecting formulation procurement toward non-plasticizer adhesive systems in European labeling and packaging applications.
- Wide-format inkjet compatibility:Printable vinyl segments are capturing margin pools as on-demand short-run graphics production displaces screen-printed alternatives.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with crude oil indices, compressing margins for calendered film producers serving price-sensitive signage markets.
- East Asian supply concentration:China's export-oriented packaging hubs dominate high-volume calendered output, creating single-source exposure for European distributors.
- Cast vinyl technical barriers:Multi-layer casting equipment requires capital intensity and process expertise that limits new entrant participation in premium vehicle wrap segments.
Strategic Opportunities
- India's logistics modernization:The country's PLI scheme for automotive components is stimulating fleet expansion among e-commerce delivery operators with unmet vinyl branding demand.
- EU F-Gas Regulation:Solvent-based manufacturing phase-outs are creating first-mover advantage for waterborne adhesive developers serving REACH-compliant formulations.
- Architectural surface films:Interior renovation applications in commercial real estate are adopting removable vinyl for tenant improvement cycles without substrate damage.
Industry Challenges
- Skilled installer scarcity:Vehicle wrap application demands certified technicians proficient in heat-gun conformability techniques for complex curves, creating bottlenecked service capacity.
- Cross-border certification lag:FDA indirect food contact approvals for adhesive systems require twelve-to-eighteen-month timelines that stall product launches in North American labeling markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Adhesive Vinyl Films Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calendered Vinyl, Cast Vinyl, Heat Transfer Vinyl, Printable Vinyl, Textile Vinyl Application: Vehicle Wraps, Signage & Graphics, Interior Decoration, Labeling, Protective Coatings End User Industry: Advertising Agencies, Shipping Companies, Event Management, Retail Outlets, Packaging Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | ORAFOL Europe GmbH, Great K2 Industry Co., Ltd., 3M Company, Shanghai DER New Material Co., Ltd., SHENZHEN SUN TONE NEW MATERIAL CO., LTD., Avery Dennison Corporation, Arlon Graphics LLC, Lintec Corporation, HEXIS SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Adhesive Vinyl Films Market Shifts & Advancements
Digital production workflows and regulatory chemistry constraints are converging to compress product development cycles and redirect competitive advantage toward formulation agility rather than scale economies alone.
Air-release adhesive technologies are automating bubble-free application for non-professional installers. Fleet maintenance departments and small-format print shops are adopting these systems to reduce labor dependency. The technology is automating quality consistency previously requiring specialized technician training, expanding addressable demand beyond traditional sign-making channels.
ECHA's SVHC candidate list expansion is accelerating substitution of organotin stabilizers in European vinyl formulations. Manufacturers serving automotive and architectural segments are reformulating around calcium-zinc alternatives to maintain CE marking eligibility. Cast vinyl producers targeting Germany's KBA vehicle certification requirements face accelerated R&D timelines to validate long-term adhesion performance under new thermal aging protocols.
Buyer concentration among logistics operators is compressing sourcing cycles toward annual framework agreements with technical performance guarantees. Small regional distributors are losing share to direct manufacturer relationships as fleet procurement departments centralize specification control. This pattern is most visible in North American over-the-road trucking networks where asset standardization across thousands of vehicles demands batch-to-batch color consistency unavailable through fragmented supply.
Global Self-Adhesive Vinyl Films Market Segmentation
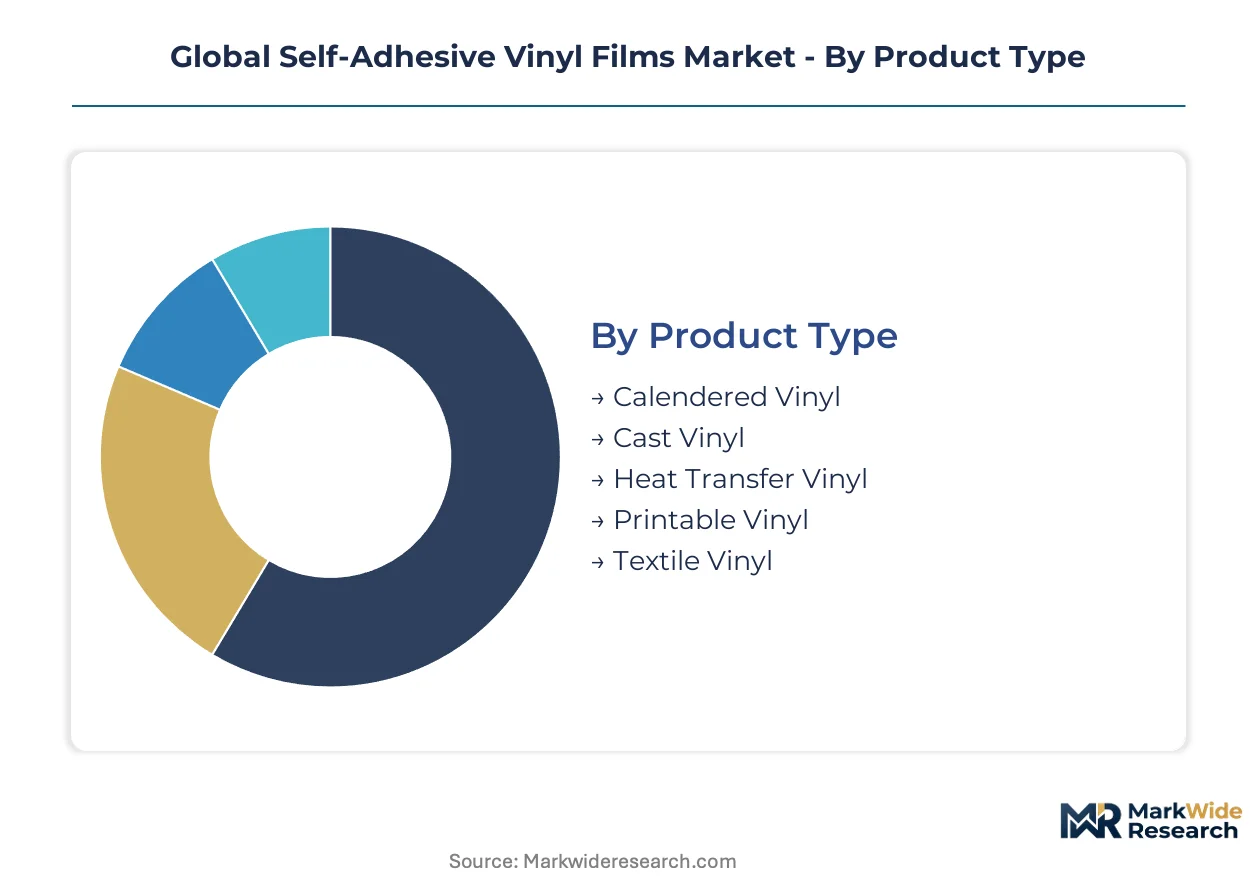
Segmentation in self-adhesive vinyl films determines capital allocation priorities and margin capture potential. Manufacturing complexity varies dramatically across product architectures, while application durability requirements reshape channel economics and customer lifetime value calculations.
Product Type:
Cast vinyl commands the steepest upfront capital requirements due to multi-layer casting lines and solvent recovery systems, while calendered production scales through simpler extrusion equipment.
- Cast Vinyl:Manufactured through solvent casting of liquid resin onto release liners, producing films with zero memory effect and 50-100 micron precision calipers. Germany's KBA-certified vehicle wrap specialists specify cast vinyl for fleet operators demanding seven-year colorfastness warranties and complex conformability around compound curves.
- Calendered Vinyl:Formed through heated roller compression of PVC compound, yielding 80-200 micron films with higher shrinkage rates but substantially lower unit economics. China's export packaging hubs in Zhejiang and Guangdong provinces concentrate calendered capacity for high-volume promotional graphics serving North American and European distributors.
- Heat Transfer Vinyl:Carrier-backed adhesive films designed for textile bonding via heat press activation, typically 100-250 microns with hot-melt or polyurethane adhesive layers.
- Printable Vinyl:Surface-engineered for wide-format inkjet compatibility with enhanced ink adhesion and dot gain control, spanning both cast and calendered substrates.
- Textile Vinyl:Specialized formulations for fabric lamination and garment decoration, incorporating stretch-recovery properties and wash-cycle durability.
Calendered vinyl absorbs the bulk of installed capacity; printable vinyl is expanding most quickly as on-demand digital production displaces screen-printed alternatives.
Application:
Application segments diverge sharply in performance specification intensity, with vehicle wraps demanding the most rigorous adhesive and conformability testing protocols.
- Vehicle Wraps:Full-body or partial graphics applications requiring cast vinyl with air-release adhesives and 3-7 year removable clean-removal properties. United States logistics operators including FedEx Ground contractors and Amazon Delivery Service Partners are standardizing fleet wrap specifications to compress asset remarketing cycles.
- Signage & Graphics:Outdoor and indoor display applications spanning billboards, point-of-purchase displays, and building identification, where calendered films dominate cost-sensitive volume procurement.
- Interior Decoration:Architectural surface films for wall coverings, furniture laminates, and retail fixture refreshes, emphasizing repositionable adhesives and substrate-safe removal.
- Labeling:Pressure-sensitive labels for consumer goods, industrial drums, and logistics tracking, constrained by FDA indirect food contact and REACH phthalate restrictions.
- Protective Coatings:Temporary surface protection films for manufacturing, transit, and installation phases, prioritizing clean-peel adhesion without residue transfer.
Signage and graphics commands the largest volume position; vehicle wraps are climbing the fastest as commercial fleet operators abandon paint-based identification systems.
End User Industry:
Customer concentration patterns vary by procurement sophistication, with shipping companies and advertising agencies representing opposite poles of specification control versus price sensitivity.
- Advertising Agencies:Creative services firms managing brand campaigns with demanding color-matching protocols and rapid turnaround requirements. Large holding companies in London and New York centralize vinyl procurement through preferred supplier agreements with batch-to-batch consistency guarantees.
- Shipping Companies:Asset-heavy logistics operators with standardized fleet identification needs and centralized procurement functions. Germany's DHL and DB Schenker operations specify KBA-compliant cast vinyl through direct manufacturer relationships, bypassing distributor markups.
- Event Management:Temporary installation specialists requiring short-duration graphics with rapid application and removal properties.
- Retail Outlets:Store operators using vinyl for seasonal promotions, window graphics, and fixture branding with mixed internal and outsourced installation.
- Packaging Manufacturers:Converters integrating pressure-sensitive labels into primary and secondary packaging lines, subject to FDA and REACH chemical compliance.
Advertising agencies represent the most fragmented demand base; shipping companies are consolidating procurement fastest through direct manufacturer frameworks.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct sales capturing the most sophisticated fleet operators while distributors serve fragmented regional demand.
- Direct Sales:Manufacturer-to-end-user relationships for large fleet operators and national retail chains with dedicated specification teams. Avery Dennison and 3M maintain direct sales organizations for North American trucking networks requiring color consistency across thousands of vehicle assets.
- Distributors:Regional and national intermediaries holding inventory for same-day availability to sign shops and installation contractors. ORAFOL Europe GmbH anchors European distribution through Berlin-area logistics serving German, Polish, and Czech print service providers.
- Online Retail:E-commerce platforms serving small-format print shops and DIY installers with standardized product configurations and credit card purchasing.
- Wholesale:Volume purchasing cooperatives and buying groups aggregating demand from independent sign-making businesses.
- Specialty Stores:Physical retail locations targeting hobbyists, small businesses, and educational institutions with hands-on product selection.
Distributors retain the broadest geographic coverage; direct sales channels are gaining share fastest among logistics operators with centralized procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's export processing zones in Zhejiang and Guangdong provinces concentrate calendered vinyl capacity for intercontinental supply. Germany's automotive aftermarket clusters anchor premium cast vinyl demand. India's logistics corridors under the PLI scheme are stimulating fleet branding procurement.
United States
FedEx Ground contractors and Amazon Delivery Service Partners are standardizing fleet wrap specifications across over-the-road trucking networks. EPA oversight of solvent emissions shapes adhesive formulation requirements for domestic converters. Michigan and Ohio-based fleet maintenance hubs are centralizing vinyl procurement through direct manufacturer frameworks.
Germany
DHL and DB Schenker operations specify KBA-certified cast vinyl for commercial vehicle identification with seven-year colorfastness warranties. ECHA's SVHC candidate list expansion is accelerating organotin stabilizer substitution in European formulations. The Berlin-Brandenburg manufacturing complex anchors continental supply for German, Polish, and Czech print service providers.
China
Zhejiang and Guangdong province packaging hubs dominate high-volume calendered output for North American and European distributor markets. GB standards and the dual carbon goals collectively shape material substitution timelines for solvent-based manufacturing processes. Shanghai DER New Material and SHENZHEN SUN TONE occupy positions within the export-oriented production cluster.
India
E-commerce delivery fleet expansion under the PLI scheme for automotive components is generating unmet vinyl branding demand among logistics operators. BIS certification requirements for imported adhesive films are extending procurement lead times for international suppliers. Maharashtra and Gujarat logistics corridors are emerging as concentration points for fleet wrap installation capacity.
Japan
Phthalate-free formulation shifts by domestic manufacturers are redirecting procurement specifications toward non-plasticizer adhesive systems. METI guidance on chemical substance management influences vinyl compound selection for labeling applications. Kansai and Chubu industrial zones maintain specialized capacity for precision calendered films serving electronics and automotive segments.
Global Self-Adhesive Vinyl Films Market Competitive Landscape
Top-tier vendors anchor premium cast vinyl segments, while mid-scale calendered producers compete on throughput and regional logistics. The vendor base stratifies across multi-layer casting specialists, high-volume extrusion operators, and regional converters serving fragmented signage demand. Strategic archetypes include technology licensors with proprietary adhesive systems, vertically integrated resin-to-film manufacturers, and distributor-anchored channel controllers. Dominant competitive moves encompass direct-to-fleet procurement relationship building and waterborne adhesive R&D partnerships for REACH-compliant formulation pipelines.
Among Germany-based specialists, ORAFOL Europe GmbH and HEXIS SAS occupy positions within the premium vehicle wrap tier, exemplifying KBA-certified manufacturing and continental distribution density. 3M Company represents the technology-licensor archetype with multi-layer casting expertise and North American fleet direct sales organizations. These three anchors illustrate the geographic and capability stratification shaping competitive positioning across automotive aftermarket and architectural specification channels.
| Leading Market Players |
|---|
| ORAFOL Europe GmbH |
| Great K2 Industry Co., Ltd. |
| 3M Company |
| Shanghai DER New Material Co., Ltd. |
| SHENZHEN SUN TONE NEW MATERIAL CO., LTD. |
| Avery Dennison Corporation |
| Arlon Graphics LLC |
| Lintec Corporation |
| HEXIS SAS |
| Others |
Supply & Pricing Matrix
Cast-calendered bifurcation separates seven-year warranty fleet wraps from commodity signage films, with KBA certification and air-release adhesive systems commanding 3-4x unit economics over Zhejiang-exported calendered stock. This performance ladder reshapes procurement: German automotive aftermarket clusters source through direct manufacturer frameworks while North American distributors absorb spot-market volatility from Guangdong packaging hubs.
Pricing Analysis
Short-lead-time premiums accrue to ORAFOL Europe GmbH and 3M Company for KBA-certified cast vinyl with batch-to-batch color consistency guarantees, while spot inventory from Chinese calendered producers trades at compressed margins. Three-tier pricing structure across premium cast, standard printable, and economy monomeric grades differentiates by durability certification and conformability specification. Cost compression in calendered segments intensifies because PVC resin and plasticizer costs fluctuate with crude oil indices. Small-format print shops and DIY installers exhibit highest price sensitivity; logistics operators with centralized fleet procurement demonstrate lowest sensitivity due to total-cost-of-ownership framing around asset resale values.
Supply Chain Analysis
Skilled technician availability constrains installation capacity in Germany's automotive aftermarket clusters and Michigan-Ohio fleet maintenance corridors, creating service bottlenecks that propagate upstream to film procurement cycles. Manufacturing concentrates in China's Zhejiang and Guangdong provinces for calendered output, Germany's Berlin-Brandenburg complex for premium cast vinyl, and Japan's Kansai-Chubu zones for precision electronics-grade films. Raw material dependencies encompass PVC resin from petrochemical complexes, pressure-sensitive acrylic adhesives, and silicone release liners. Single-source exposure to Chinese calendered capacity creates tariff and logistics chokepoint vulnerability for European distributors. Distribution runs through regional intermediaries for fragmented sign shop demand and direct manufacturer relationships for centralized fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer casting equipment scarcity and certified installer bottlenecks prop pricing power for incumbent premium producers, constraining volume expansion regardless of downstream demand absorption.
For Market Incumbents: Anticipate waterborne adhesive R&D partnerships to secure REACH-compliant formulation pipelines ahead of EU F-Gas Regulation phase-outs. Defensive consolidation around Berlin-Brandenburg and North American direct sales organizations protects against Korean and Japanese phthalate-free formulation entrants. Capacity addition in India's Maharashtra-Gujarat logistics corridors captures PLI-scheme fleet expansion before international suppliers establish BIS-certified import pathways.
For New Entrants and Emerging Players: Air-release adhesive automation technologies offer white-space entry into non-professional installer segments underserved by incumbent technician-dependent service models. India's e-commerce delivery fleet expansion presents the most penetrable geography given unmet vinyl branding demand and extended procurement lead times for international suppliers. Go-to-market execution partners with regional print service providers in Poland and Czech markets bypass ORAFOL's distribution density.
For Investors and Strategic Acquirers: Re-rating potential sits with waterborne adhesive specialists given ECHA enforcement acceleration and solvent-based manufacturing phase-out timelines. Long-term viability across the analysis window favors backward-integrated resin-to-film manufacturers with captive PVC compound supply. Acquisition target archetype: mid-scale calendered producers in China's export hubs with established North American distributor relationships. Signal to watch: BIS certification timeline compression for imported adhesive films as India's logistics modernization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Adhesive R&D Partnership | ECHA REACH compliance secures CE marking eligibility for German automotive aftermarket supply. |
| Direct-to-Fleet Procurement Framework | Avery Dennison and 3M bypass distributor markups in North American trucking networks. |
| India PLI Corridor Capacity Buildout | Maharashtra-Gujarat installation capacity captures e-commerce delivery fleet expansion. |
| Air-Release Technology Product Launch | Automated bubble-free application expands addressable demand beyond certified technician channels. |
| Organotin Stabilizer Substitution Program | Calcium-zinc alternatives maintain KBA vehicle certification under expanded SVHC candidate list. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet procurement managers, wide-format print shop operators, adhesive formulation chemists, and distributor inventory planners. Bottom-up triangulation against top-down macroeconomic drivers validated volume and value estimates. Secondary sources encompassed ECHA SVHC database entries, KBA vehicle certification registries, EPA solvent emission disclosures, and China customs export statistics for calendered film HS codes.
Granularity-level modeling operated at product type-by-application-by-country intersection, with separate forecasts for cast vinyl vehicle wraps, calendered signage films, and printable segments across Germany, United States, China, India, and Japan. CAGRs derived from elasticity-adjusted demand projections incorporating fleet replacement cycle compression and regulatory substitution timelines. Industry-specific inputs included logistics operator fleet standardization protocols, REACH phthalate restriction enforcement patterns, and wide-format inkjet equipment installation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price volatility and trade policy disruption scenarios. Forecasts reflect assumptions around installer capacity expansion rates and BIS certification processing timelines. Material deviation in ECHA enforcement intensity or India's PLI scheme disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market