
 Global Demineralized Bone Matrix Market | 2026-2036
Global Demineralized Bone Matrix Market Size, Share, and Industry Trends Forecast 2026-2036
Global Demineralized Bone Matrix Market Foresight
Hospital purchasing consortia and ambulatory surgical center networks is reconfiguring how demineralized bone matrix products reach surgical sites. Stryker leverages its integrated trauma and spine platforms to secure long-term supply agreements with integrated delivery networks. Zimmer Biomet anchors its position through dedicated extremities and biologics sales forces that call directly on orthopedic clinics. Medtronic Plc competes by bundling DBM with its spinal hardware portfolios, reducing procurement friction for fusion procedures.
Demineralized bone matrix comprises acid-extracted allograft bone in which the inorganic mineral phase has been removed, leaving behind a collagen scaffold rich in osteoinductive bone morphogenetic proteins that stimulate mesenchymal stem cell differentiation into osteoblasts. The material serves primarily as an osteoconductive and osteoinductive void filler in spinal fusion, dental extraction sockets, and long-bone fracture sites where autograft harvest is contraindicated or insufficient. Putty and gel formulations command the largest volume share due to intraoperative handling advantages in minimally invasive approaches, while injectable DBM represents the fastest-expanding format as percutaneous delivery techniques gain surgical adoption. Orthopedic trauma applications generate substantial demand through emergency department and level-one trauma center channels, whereas spinal fusion procedures concentrate margin pools through higher ASPs and bundled payment structures.
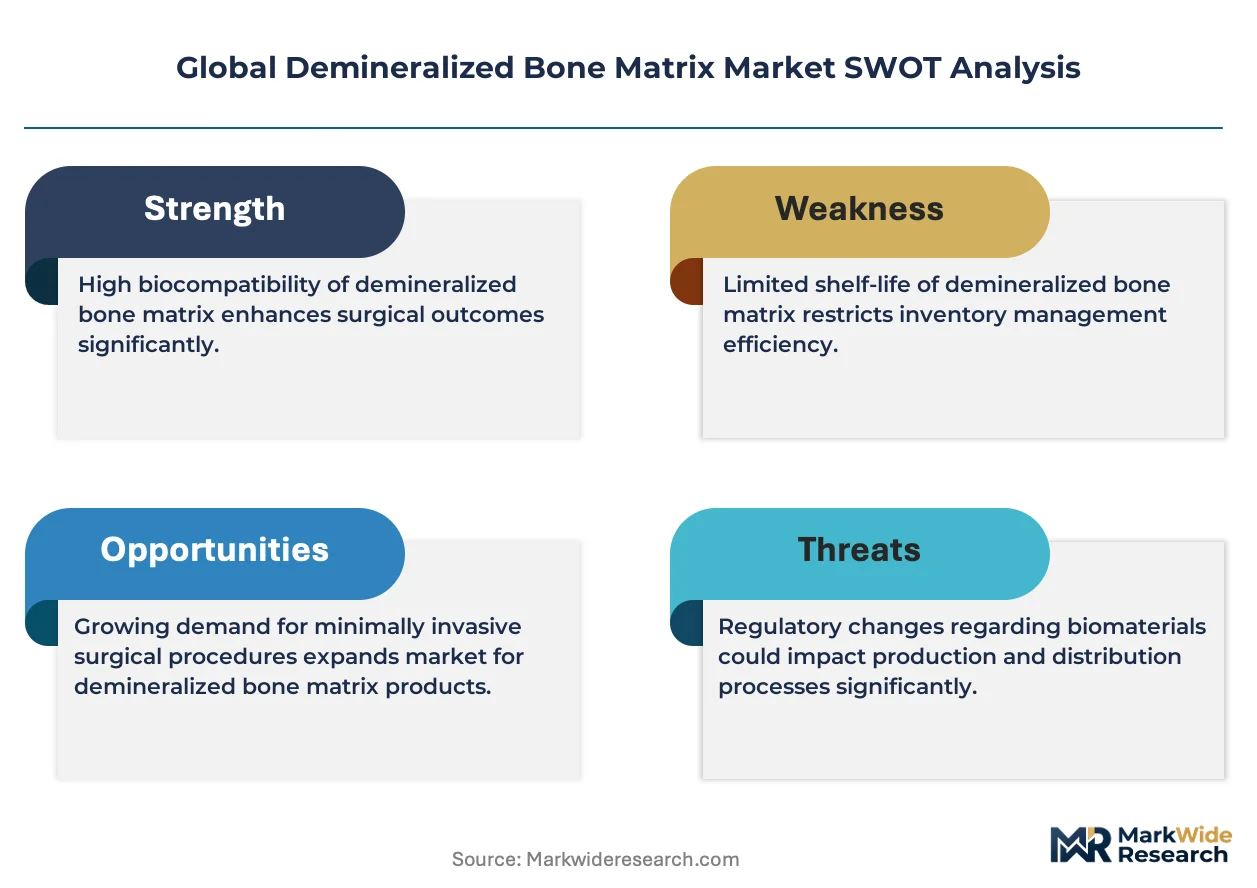
The FDA regulates DBM as a 510(k) medical device requiring demonstration of substantial equivalence, while the agency's Human Cells, Tissues, and Cellular and Tissue-Based Products framework imposes donor screening and processing standards on allograft tissue banks. ISO 13485 quality management certification and AATB accreditation function as baseline market access requirements for suppliers serving US and European hospitals. Stakeholders must monitor evolving CMS reimbursement determinations for bone graft substitutes in outpatient settings, as site-of-service payment differentials increasingly influence surgeon and facility product selection.
Market Dynamics
Orthopedic clinics and ambulatory surgical centers are consolidating purchasing power through group purchasing organizations, forcing DBM suppliers to restructure pricing and service models around bundled contract terms rather than transactional sales.
Growth Catalysts
- CMS site-of-service reimbursement differentials:Higher payment rates for spinal fusion performed in outpatient settings accelerate migration from hospitals to orthopedic clinics, expanding addressable procedure volumes for putty and gel formulations.
- Minimally invasive surgical techniques:Percutaneous delivery methods favor injectable DBM formats that can navigate narrow working channels, creating pull-through demand for specialized delivery systems.
- Aging surgical populations in Germany and Japan:Expanding Medicare-equivalent coverage for bone graft substitutes in these markets extends commercial runway beyond United States saturation.
Market Restraints
- Allograft tissue supply concentration:Dominance of United States tissue banks creates geographic vulnerability to donor screening protocol changes or processing disruptions.
- Synthetic bone graft substitution:Ceramic and polymer alternatives with lower batch-to-batch variability capture price-sensitive trauma cases where osteoinductivity is less critical.
- FDA 510(k) substantial equivalence requirements:Demonstration burden for novel DBM-carrier combinations extends regulatory timelines and elevates pre-market capital requirements.
Strategic Opportunities
- Underpenetrated dental extraction socket market in India:Rising oral surgery volumes and limited domestic allograft processing infrastructure create import-dependent demand for premium DBM putties.
- Combination product regulatory pathway:FDA breakthrough device designation for DBM-ceramic composites offers expedited review and differentiated positioning in spinal fusion.
- Direct-to-clinic distribution platforms:Specialized logistics networks bypassing hospital central supply reduce fulfillment friction for high-volume orthopedic clinic chains.
Industry Challenges
- AATB accreditation complexity:Multi-site tissue processing facilities face audit coordination burdens that strain quality management systems and extend certification maintenance cycles.
- Surgeon training requirements for injectable delivery:Percutaneous technique proficiency gaps limit adoption velocity despite product availability, necessitating proctoring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Demineralized Bone Matrix Market |
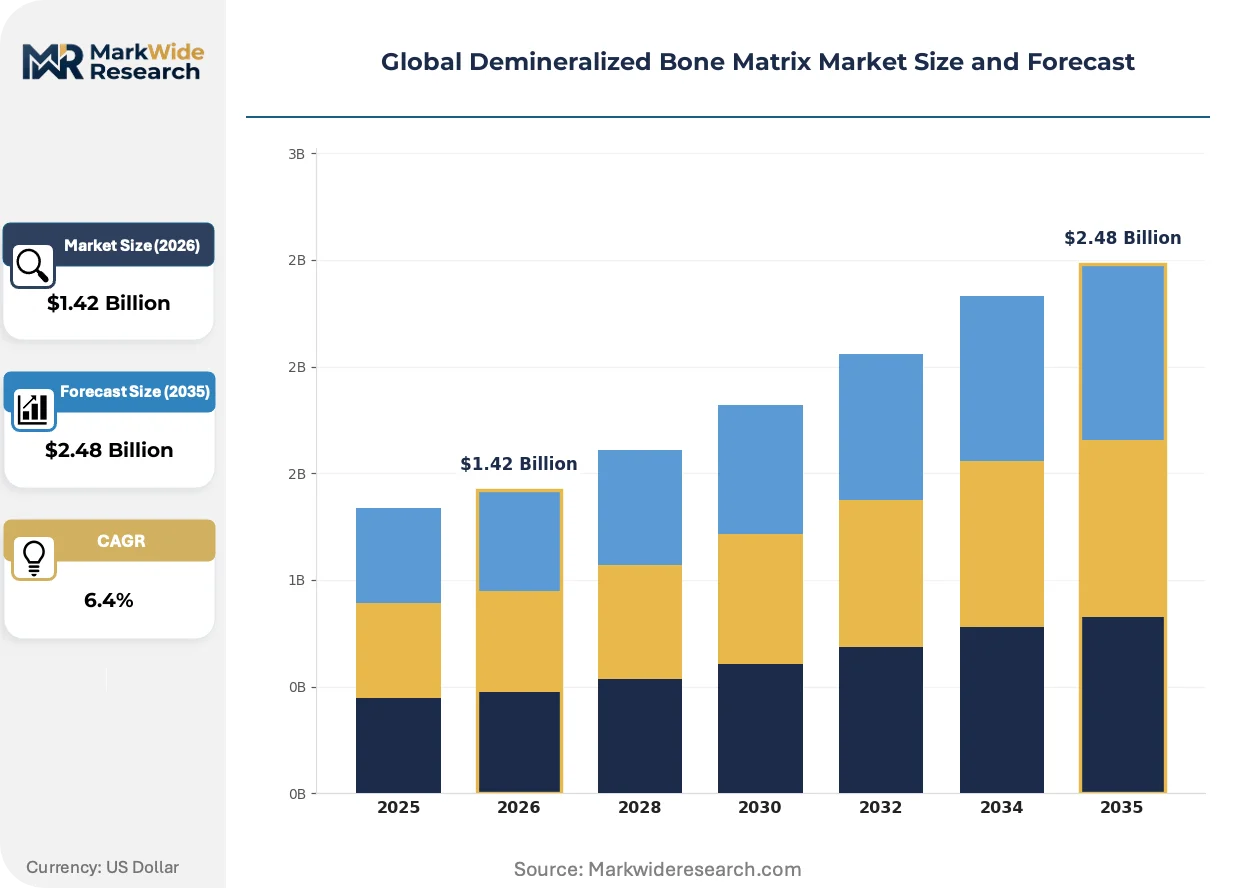
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Putty, Gel, Chip, Sheet, Injectable Application: Spinal Fusion, Dental Surgery, Orthopedic Trauma, Plastic Surgery End User: Ambulatory Surgical Centers, Dental Clinics, Orthopedic Clinics, Plastic Surgery Centers Form: Freeze-Dried, Frozen, Lyophilized, Fresh |
| Companies Covered | Stryker, SeaSpine, Zimmer Biomet, Berkeley Advanced Biomaterials, Globus Medical, Medtronic Plc, Arthrex Inc, XTANT MEDICAL, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Demineralized Bone Matrix Market Shifts & Advancements
Formulation science and delivery mechanism engineering are compressing the functional gap between DBM and synthetic alternatives while regulatory frameworks adapt to combination product complexity.
Lyophilized DBM sponges with pre-mixed saline activation are collapsing the preparation time disadvantage against ready-to-use synthetic grafts. Orthopedic trauma teams in level-one centers are adopting these formats for emergency department availability. The technology is collapsing the historical trade-off between biological performance and operative efficiency that favored ceramics in time-critical cases.
EMA's 2023 updated guidance on tissue-engineered product classification redefines borderline determinations for DBM combined with synthetic carriers. Manufacturers must now navigate notified body consultation requirements that previously applied only to cell-based therapies. Spinal fusion applications in Germany and France face the steepest compliance recalibration as CE marking renewal cycles align with Medical Device Regulation timelines.
Surgeon preference for single-vendor fusion solutions is consolidating procurement decisions around hardware-biologics bundles. Independent orthopedic clinics are surrendering purchasing autonomy to integrated delivery networks that negotiate system-wide contracts. This concentration is most visible in Texas and Florida markets where ambulatory surgery center joint ventures between device manufacturers and physician groups capture outpatient spinal volume.
Global Demineralized Bone Matrix Market Segmentation
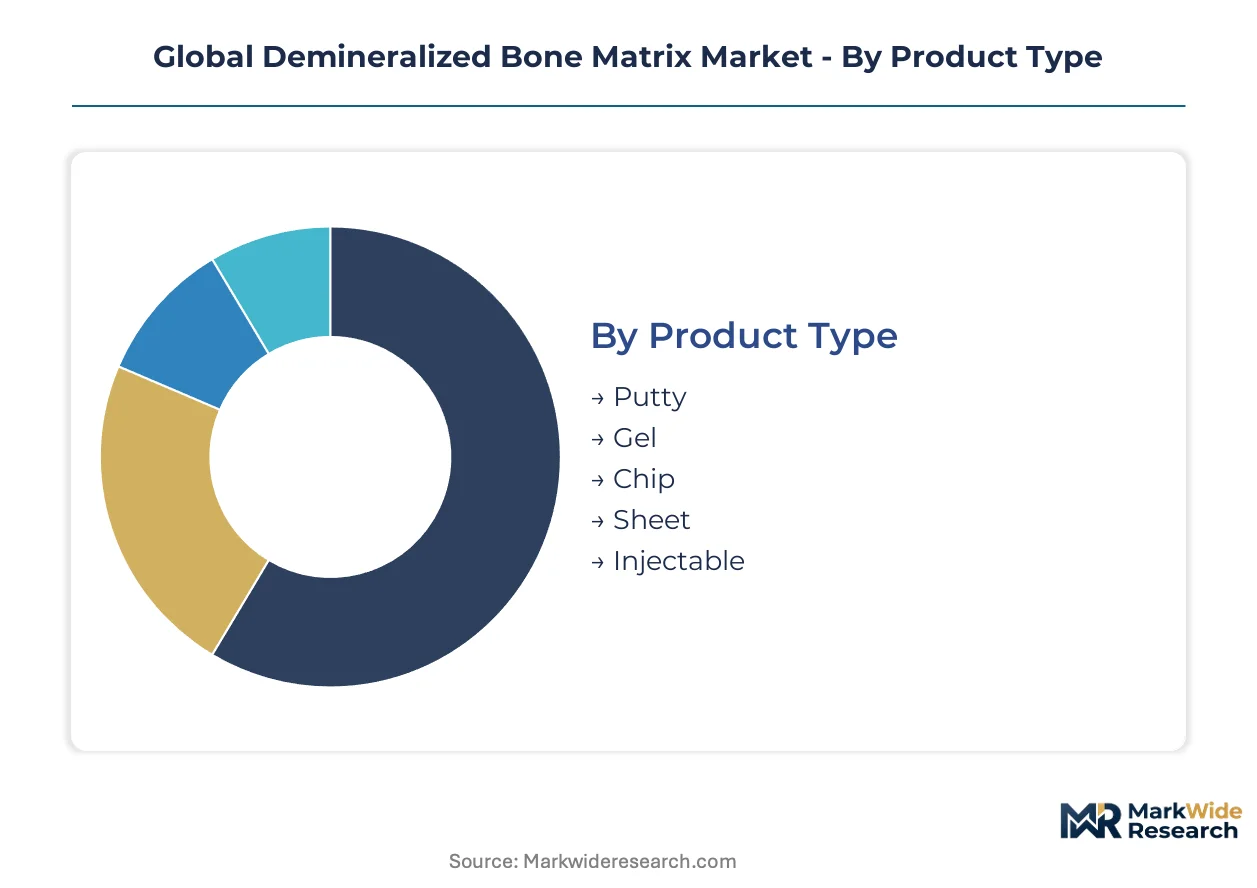
Demineralized bone matrix suppliers must align formulation portfolios with distinct surgical workflows and regulatory pathways across four critical dimensions. Each segmentation axis reveals divergent margin structures, procurement gatekeepers, and technology substitution risks that reshape competitive positioning.
Product Type:
Mature putty and gel formats dominate current revenue pools, while injectable delivery systems emerge as the technology frontier reshaping minimally invasive adoption curves.
- Putty:Moldable DBM-carrier composites enable precise contouring around vertebral bodies and fracture sites. Orthopedic trauma teams in United States level-one centers favor putty for its intraoperative pliability and rapid preparation. Demand concentrates in spinal fusion bundles where handling speed reduces operating room turnover costs.
- Injectable:Flowable formulations navigate percutaneous working channels for kyphoplasty and vertebroplasty augmentation. German spine surgeons are adopting injectable DBM-ceramic hybrids for outpatient fusion procedures under EMA's tissue-engineered product guidance. Percutaneous technique certification requirements currently constrain penetration velocity despite product availability.
- Gel:Viscous suspensions optimize packing density in dental extraction sockets and small-bone voids. Japanese oral surgeons prefer gel consistency for maxillofacial applications under PMDA's biological product standards.
- Chip:Particulate formats provide structural scaffolding for long-bone nonunions. Trauma centers in Brazil source chips for open reduction internal fixation augmentation per ANVISA's allograft import protocols.
- Sheet:Flexible membranes contour to irregular bone surfaces in craniomaxillofacial reconstruction. Plastic surgery centers in South Korea deploy sheets for orbital floor repairs under MFDS biologics registration.
Putty handles the majority of throughput; injectable is the fastest mover on share.
Application:
Volume concentrates in high-procedure spinal and trauma categories, while dental and plastic surgery segments offer premium pricing escape from bundled payment compression.
- Spinal Fusion:Interbody and posterolateral fusion procedures consume DBM volumes at ASPs sustained by hospital bundled payments. United States integrated delivery networks negotiate system-wide contracts covering thoracolumbar and cervical applications. CMS site-of-service differentials accelerate migration to ambulatory settings where putty and injectable formats reduce operative time.
- Dental Surgery:Extraction socket preservation and ridge augmentation generate consistent demand with limited synthetic substitution threat. Indian oral surgery clinics represent underpenetrated import-dependent demand as domestic allograft processing infrastructure remains nascent.
- Orthopedic Trauma:Long-bone fractures and nonunions drive emergency department consumption through level-one trauma center channels. Ceramic alternatives capture price-sensitive cases where osteoinductivity is less critical than structural support.
- Plastic Surgery:Craniofacial reconstruction and hand surgery applications command premium pricing outside orthopedic procurement bundles. French maxillofacial units under ANSM oversight specify lyophilized formats for aesthetic bone grafting.
Spinal fusion captures the dominant revenue pool; dental surgery is climbing the fastest as oral surgery volumes expand in Asia-Pacific markets.
End User:
Procurement authority is migrating from hospital central supply toward clinic-level purchasing through specialized distribution platforms and direct sales forces.
- Orthopedic Clinics:Outpatient spinal fusion volumes rise as surgeon-owners capture site-of-service payment differentials. Texas and Florida ambulatory surgery center joint ventures concentrate purchasing power for putty and injectable formats.
- Ambulatory Surgical Centers:Networked facilities negotiate group purchasing organization contracts that compress pricing transparency. Stryker and Zimmer Biomet deploy dedicated biologics sales forces to secure long-term supply agreements.
- Dental Clinics:Independent oral surgery practices maintain autonomous procurement for socket preservation products. Direct-to-clinic logistics platforms bypass hospital central supply friction for high-volume chains.
- Plastic Surgery Centers:Boutique facilities prioritize single-vendor relationships covering implants and biologics. Swissmedic-registered centers in Geneva and Zurich specify premium lyophilized sheets for aesthetic applications.
Orthopedic clinics absorb the highest procedure volume; ambulatory surgical centers are gaining share fastest through network consolidation.
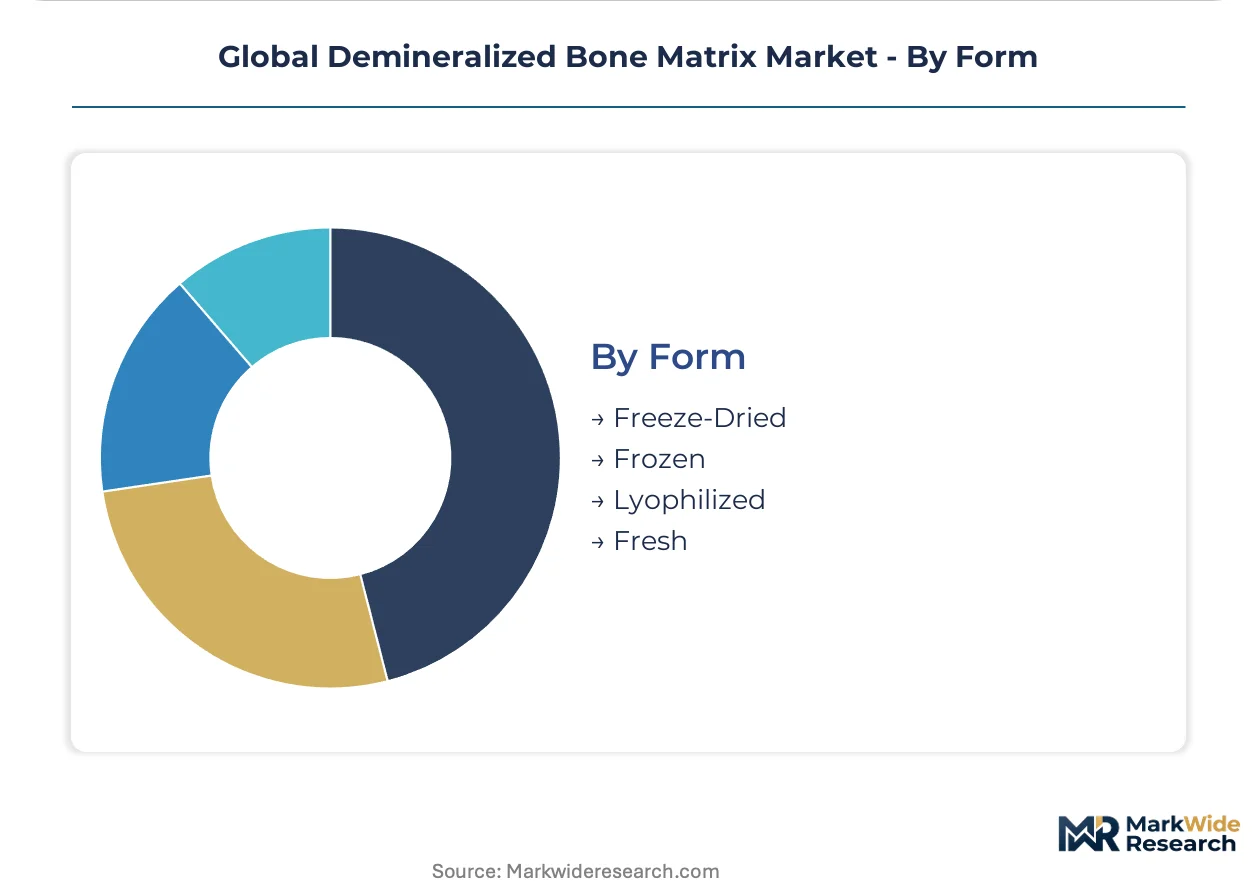
Form:
Processing methodology determines shelf stability, osteoinductive preservation, and regulatory classification complexity across tissue bank supply chains.
- Freeze-Dried:Lyophilization extends shelf life while preserving bone morphogenetic protein activity. United States tissue banks under AATB accreditation dominate freeze-dried output for domestic and export markets.
- Lyophilized:Advanced dehydration protocols enable room-temperature storage with saline activation at point-of-use. Level-one trauma centers in Japan adopt pre-mixed activation formats for emergency department availability.
- Frozen:Cryopreserved allograft maintains higher cell viability for applications where osteogenic potential matters. Health Canada-registered tissue establishments supply frozen DBM for Canadian hospital consortia.
- Fresh:Non-processed allograft serves niche applications requiring maximum biological activity. Regulatory burden and infectious disease screening constraints limit fresh format commercialization outside specialized tissue bank relationships.
Freeze-dried formats manage the bulk of commercial throughput; lyophilized configurations are expanding most quickly as preparation convenience drives surgical preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles handles the largest share of temperature-controlled biologics imports into North America, underwriting the United States' position as the primary consumption hub for demineralized bone matrix products.
United States
Outpatient spinal fusion volumes at orthopedic clinic chains in Texas and Florida are accelerating demand for putty and injectable formats. FDA 510(k) clearance pathways for combination DBM-allograft products compress commercial timelines for domestic manufacturers. The Dallas-Fort Worth metroplex anchors distribution networks serving ambulatory surgery center joint ventures between device manufacturers and physician groups.
Germany
German spine surgeons are adopting injectable DBM-ceramic hybrids for outpatient fusion procedures as Medicare-equivalent coverage expands. EMA's 2023 updated guidance on tissue-engineered product classification redefines borderline determinations for DBM combined with synthetic carriers. The Rhine-Ruhr industrial corridor concentrates notified body consultation expertise for CE marking renewal cycles under Medical Device Regulation timelines.
Japan
Aging surgical populations are extending commercial runway for bone graft substitutes as PMDA biological product standards mature. Level-one trauma centers in Tokyo and Osaka adopt lyophilized formats with pre-mixed saline activation for emergency department availability. The Kanto region dominates domestic tissue processing infrastructure under METI oversight.
India
Rising oral surgery volumes in Mumbai and Delhi are creating import-dependent demand for premium DBM putties as domestic allograft processing infrastructure remains nascent. CDSCO import protocols for biological products shape procurement timelines for socket preservation applications. The Maharashtra-Gujarat pharmaceutical corridor channels distribution through specialized direct-to-clinic logistics platforms.
Brazil
Trauma centers in São Paulo source DBM chips for open reduction internal fixation augmentation under ANVISA allograft import protocols. Public hospital purchasing consortia are consolidating procurement authority for orthopedic biologics. The São Paulo-Minas Gerais axis anchors Latin America's largest concentration of level-one trauma facilities.
Global Demineralized Bone Matrix Market Competitive Landscape
On the supply side, the industry is consolidating around integrated delivery network contracts and hardware-biologics bundling arrangements that favor scale. Three strategic archetypes dominate: diversified orthopedic conglomerates with spine and trauma platforms, dedicated biologics specialists with tissue bank relationships, and emerging injectable-format innovators. M&A activity targets ambulatory surgery center distribution channels, while strategic partnerships with group purchasing organizations secure volume commitments.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet exemplify the hardware-biologics bundling model that reduces procurement friction for fusion procedures. Medtronic Plc occupies a position representing the spinal hardware portfolio anchoring strategy. SeaSpine sits within the dedicated spine biologics specialist archetype focused on outpatient procedural volumes.
| Leading Market Players |
|---|
| Stryker |
| SeaSpine |
| Zimmer Biomet |
| Berkeley Advanced Biomaterials |
| Globus Medical |
| Medtronic Plc |
| Arthrex Inc |
| XTANT MEDICAL |
| DePuy Synthes |
| Others |
Supply & Pricing Matrix
The Port of Los Angeles handles the largest share of temperature-controlled biologics imports into North America, and its freight cost dynamics amplify supply concentration effects while forcing three-tier pricing stratification across premium lyophilized formats, standard freeze-dried putties, and economy-grade chips for price-sensitive trauma centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations, with ISO 13485 certification tier and AATB accreditation status driving price differentiation between tissue bank suppliers. Pricing pressure stems from synthetic ceramic alternatives capturing trauma cases where osteoinductivity matters less than structural support. Ambulatory surgical centers exhibit highest price sensitivity through group purchasing organization leverage, while integrated delivery networks absorb premium pricing for bundled hardware-biologics solutions.
Supply Chain Analysis
Tariff exposure between United States tissue processing facilities and German notified body consultation requirements dominates supply chain risk planning for CE marking renewals under Medical Device Regulation timelines. Geographic supply concentrates in United States AATB-accredited tissue banks, Japanese METI-registered processing facilities, and Swissmedic-certified European establishments. Raw material dependencies center on cadaveric donor tissue availability, acid demineralization reagents, and collagen carrier substrates. Single-source vulnerability to donor screening protocol changes threatens batch consistency. Distribution runs through specialized cold-chain logistics networks serving hospital central supply and direct-to-clinic platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic bone graft substitutes are eroding the trauma segment, forcing DBM incumbents to defend biological performance premiums through formulation innovation and delivery mechanism differentiation.
For Market Incumbents: Build hardware-biologics bundling moats by anchoring DBM supply agreements to spinal hardware contracts with integrated delivery networks in Texas and Florida. Deepen AATB-accredited tissue processing capacity to secure batch-to-batch consistency against synthetic substitution threats. Prioritize injectable format R&D to capture percutaneous technique adoption curves before ceramic hybrids consolidate minimally invasive fusion segments. For New Entrants and Emerging Players: Build out direct-to-clinic distribution platforms targeting underpenetrated Indian oral surgery markets where domestic allograft processing infrastructure remains nascent. Capture dental extraction socket demand through premium putty imports via CDSCO-registered channels. Leverage specialized logistics partnerships to bypass hospital central supply friction for high-volume Mumbai and Delhi clinic chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dedicated spine biologics specialists with ambulatory surgery center channel control over diversified orthopedic conglomerates facing bundling margin compression. Five-to-ten year viability rests on FDA 510(k) clearance velocity for combination DBM-ceramic products. Watch EMA tissue-engineered product guidance enforcement as inflection signal for European market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Combination Product Submission | Expedited clearance for DBM-ceramic hybrids compresses commercial timelines against synthetic alternatives. |
| Ambulatory Surgery Center Joint Venture | Physician-manufacturer partnerships in Florida capture site-of-service payment differentials for outpatient fusion. |
| Direct-to-Clinic Logistics Platform | Bypassing hospital central supply reduces fulfillment friction for high-volume orthopedic clinic chains. |
| EMA Notified Body Pre-Consultation | Early engagement on tissue-engineered product classification mitigates MDR renewal compliance burden. |
| Injectable Format Delivery System Development | Percutaneous technique certification support accelerates surgeon adoption velocity for minimally invasive applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and tissue bank quality directors; and secondary validation against FDA 510(k) clearances, AATB accreditation records, CMS reimbursement determinations, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across the analysis window.
Forecast inputs incorporated product type segmentation by putty, injectable, gel, chip, and sheet formats; application splits across spinal fusion, dental surgery, orthopedic trauma, and plastic surgery; end-user channel dynamics between orthopedic clinics, ambulatory surgical centers, and hospital systems; and form-based processing methodology distinctions. CAGRs derived from logistic adoption curve modeling for minimally invasive techniques and demographic projection inputs for aging surgical populations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by synthetic bone graft manufacturers or breakthrough ceramic-osteoinductive hybrids would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Global Dental Cements Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Teeth Whitening Market
Dental Materials
Toothpaste Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Dental Plaster Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Fluoride Materials Market
Dental Materials
Dental Putty Market
Dental Materials
Dental Alginate Market