
 Solid Toothpaste Market | 2026-2036
Solid Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Toothpaste Market Insights
Buyer concentration is repositioning as specialty zero-waste retailers fragment across direct-to-consumer channels while health store chains consolidate shelf access. Nelson Naturals leverages its Canadian manufacturing base to control raw material sourcing for clay-based formulations. Georganics anchors the UK market through dental professional endorsements and glass jar distribution. Bite Toothpaste Bits differentiates via subscription-model channel control and aluminum refill systems.
Solid toothpaste denotes concentrated oral care formulations—typically calcium carbonate, sodium bicarbonate, or clay bases bound with coconut oil and essential oils—that activate with saliva contact to deliver fluoride or fluoride-free cleaning without water-heavy paste matrices. Manufacturing employs cold-press compaction or tablet punching at moisture levels below five percent to prevent microbial growth and preserve surfactant stability. Minty variants dominate current volume due to familiar taste migration from conventional paste, while activated charcoal formulations command premium positioning through visual differentiation and whitening claims despite limited clinical substantiation. Compostable packs represent the fastest-growing packaging segment as EU Green Deal compliance deadlines force brand owners to abandon laminated tubes.
The EU Green Deal and REACH frameworks restrict microplastic additives and mandate packaging recyclability, directly elevating compostable pack demand across European formulations. The FDA maintains monograph control over fluoride concentration claims in the United States, creating regulatory friction for imported tablet products seeking anticavity positioning. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, where packaging fee structures threaten margin economics for non-compostable formats.
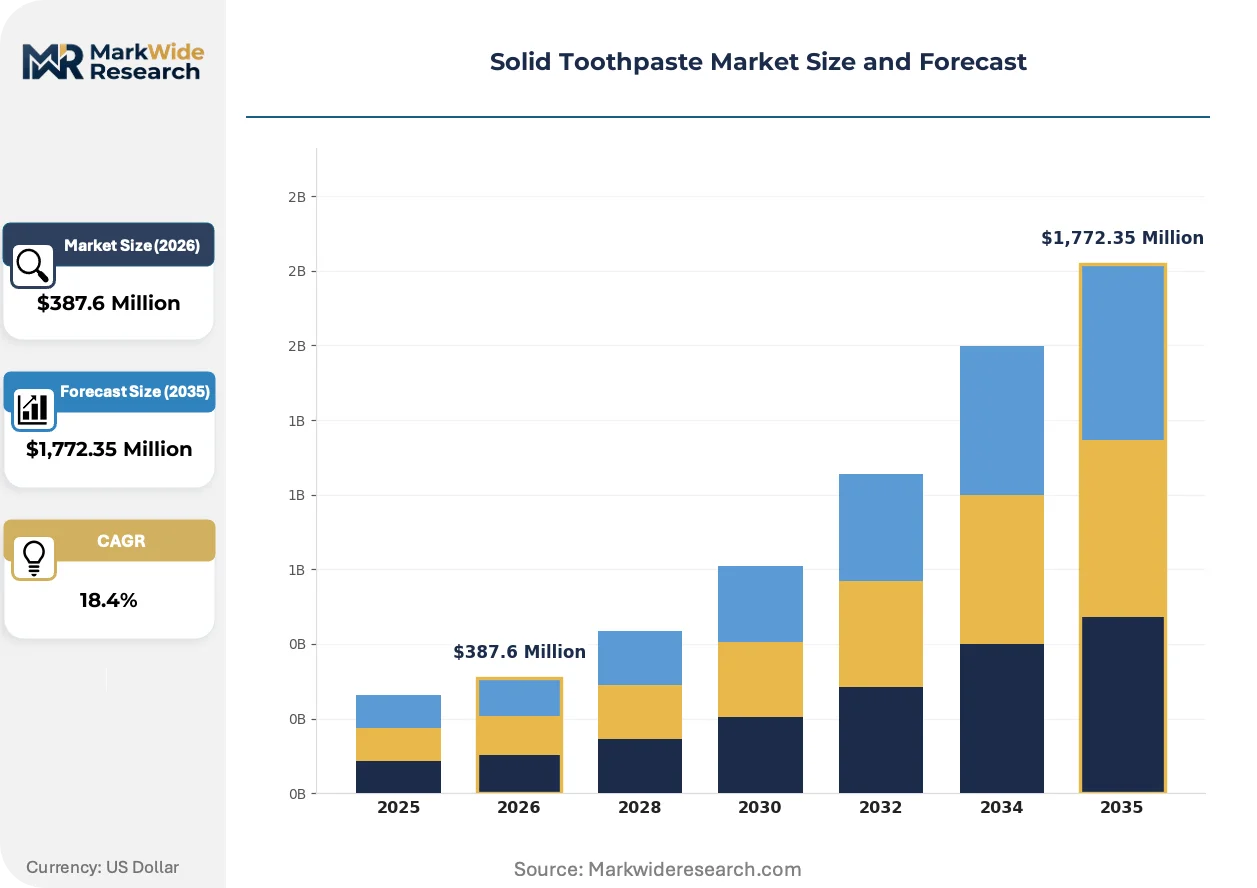
Market Dynamics
The EU Green Deal's single-use plastic restrictions are compressing conventional tube-based supply chains while forcing rapid packaging reconfiguration toward compostable materials and aluminum refill systems.
Growth Catalysts
- REACH microplastic bans:The European Chemicals Agency's additive restrictions eliminate synthetic polymer competitors, creating regulatory space for clay and mineral-based formulations.
- Zero-waste retail networks:Germany's package-free store density concentrates consumer access points and normalizes solid format trial among mainstream buyers.
- Tablet punching automation:Cold-press compaction equipment upgrades reduce unit production costs below five percent moisture thresholds, improving surfactant stability margins.
Market Restraints
- Fluoride regulatory friction:FDA monograph control over anticavity claims creates import barriers for tablet products seeking therapeutic positioning in the United States.
- Coconut oil price volatility:Base oil input costs fluctuate with Southeast Asian weather patterns and biofuel diversion demand, compressing margin predictability.
- Moisture sensitivity:Sub-five-percent humidity requirements throughout cold-press manufacturing limit viable production geographies to temperate climate zones.
Strategic Opportunities
- Extended producer responsibility tailwinds:California and New York state-level packaging fee structures penalize laminated tubes, advantaging compostable pack innovators.
- Dental professional channel:UK and German clinician endorsement protocols remain underexploited for prescription-adjacent fluoride tablet distribution.
- Subscription-model convergence:Direct-to-consumer aluminum refill systems combine with personalized flavor profiling to capture recurring revenue streams.
Industry Challenges
- Surfactant stability expertise:Formulation chemistry talent capable of maintaining sodium cocoyl isethionate activity in low-moisture matrices remains concentrated among legacy oral care R&D centers.
- Compostable certification timelines:Industrial compostability validation under ASTM D6400 and EN 13432 extends new product introduction cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Toothpaste Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minty, Herbal, Activated Charcoal, Whitening Packaging Type: Recyclable Tubes, Compostable Packs, Eco-Friendly Jars, Travel Cases Customer Type: Eco-Conscious Consumers, Families, Dental Professionals, Travel Enthusiasts Distribution Channel: Online Retailers, Health Stores, Supermarkets, Specialty Shops |
| Companies Covered | Hello Products (Colgate Palmolive), Nelson Naturals, The Humble Co., Weldental (Chew Tab), Non Plastic Beach, Bite Toothpaste Bits, Georganics, Chomp Toothpaste, Denttabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Toothpaste Market Trends and Innovations
Packaging material science and regulatory compliance deadlines are jointly restructuring competitive advantage around circular economy credentials rather than formulation differentiation alone.
Waterless manufacturing is expanding into mainstream oral care production. Cold-press compaction and tablet punching systems activate concentrated calcium carbonate and sodium bicarbonate bases through saliva contact alone. Major contract manufacturers in Germany and the Netherlands are retrofitting equipment lines to handle sub-five-percent moisture operations. This capital deployment is expanding into geographies previously dependent on water-heavy paste matrices, compressing conventional tube supply chain economics.
EU Green Deal packaging mandates are forcing laminated tube abandonment across European formulations. The framework's recyclability requirements and single-use plastic restrictions create non-compliance costs that outweigh reformulation investments. Brands serving Germany, France, and Benelux markets are accelerating compostable pack transitions ahead of enforcement deadlines. Glass jar and aluminum refill systems capture shelf space formerly occupied by conventional packaging.
Travel-format purchasing is fragmenting distribution channel control. Tablet and paste-bar formats bypass liquid restrictions in carry-on baggage regulations, capturing airport retail and direct-to-consumer subscription channels. Health store chains consolidate shelf access for impulse purchases while specialty zero-waste retailers build localized fulfillment networks. This channel bifurcation concentrates in Germany and the United Kingdom where zero-waste retail density supports localized replenishment cycles.
Solid Toothpaste Market Segmentation
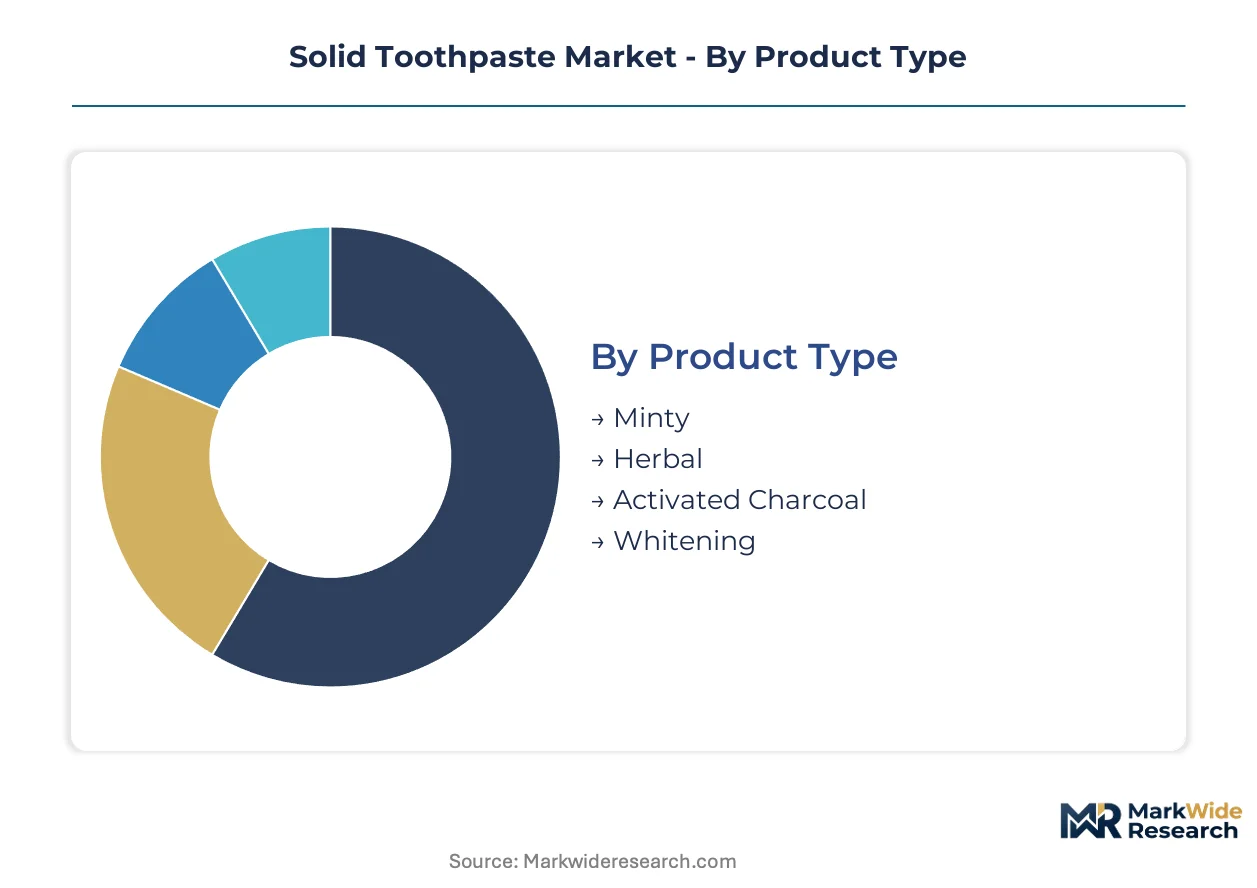
Solid toothpaste manufacturers align formulation chemistry and packaging engineering to distinct buyer workflows. Segmentation reveals where supply-side capabilities match demand-side willingness to pay for zero-waste credentials.
Product Type:
Manufacturing equipment for cold-press compaction clusters around clay and mineral-based chemistries, concentrating supply capacity in specific formulation families.
- Minty:Calcium carbonate and sodium bicarbonate bases bound with coconut oil deliver familiar taste migration from conventional paste. Demand concentrates in Germany where zero-waste retail density normalizes solid format trial among mainstream buyers seeking sensory continuity.
- Herbal:Essential oil blends featuring tea tree, clove, and eucalyptus replace synthetic flavors in fluoride-free positioning. UK health store chains consolidate shelf access for these variants as dental professional endorsements validate natural antimicrobial claims.
- Activated Charcoal:Visual differentiation drives premium positioning despite limited clinical substantiation for whitening efficacy.
- Whitening:Peroxide-free mineral abrasives target aesthetic-conscious segments in direct-to-consumer channels.
Today's leader: Minty. Tomorrow's challenger: Herbal.
Packaging Type:
EU Green Deal compliance deadlines are reconfiguring supplier bases around compostable certification capabilities versus aluminum and glass expertise.
- Compostable Packs:Industrial compostability validation under EN 13432 and ASTM D6400 extends new product introduction cycles by twelve to eighteen months. Germany's package-free store networks and France's extended producer responsibility fee structures accelerate adoption ahead of enforcement deadlines.
- Eco-Friendly Jars:Glass container systems anchor UK distribution through Georganics' dental professional channel strategy, capturing recurring refill purchases.
- Recyclable Tubes:Laminated aluminum-plastic hybrids face margin pressure from state-level packaging fees in California and New York.
- Travel Cases:Aluminum refill systems combine with subscription models to bypass liquid restrictions in carry-on baggage regulations.
Compostable packs are climbing the fastest as regulatory non-compliance costs outweigh reformulation investments.
Customer Type:
Price elasticity varies sharply across buyer groups, with professional endorsement protocols unlocking prescription-adjacent fluoride distribution.
- Eco-Conscious Consumers:Willingness to pay premiums for zero-waste credentials concentrates in millennial demographics with travel-heavy lifestyles.
- Dental Professionals:UK and German clinician endorsement channels remain underexploited for fluoride tablet distribution with therapeutic positioning.
- Families:Multi-user household formats favor larger-count compostable packs with child-friendly flavor profiles.
- Travel Enthusiasts:Tablet formats bypass TSA liquid restrictions, capturing airport retail and direct-to-consumer subscription channels.
Travel enthusiasts currently drive volume. Dental professionals offer the steepest expansion trajectory through prescription-adjacent positioning.
Distribution Channel:
Channel bifurcation between consolidated health store chains and fragmented specialty zero-waste retailers reshapes fulfillment economics.
- Online Retailers:Subscription-model convergence with personalized flavor profiling captures recurring revenue streams through aluminum refill systems.
- Health Stores:Consolidated shelf access for impulse purchases concentrates in Germany and UK retail networks with established zero-waste product adjacencies.
- Specialty Shops:Localized fulfillment networks in package-free stores support replenishment cycles with minimal inventory carrying costs.
- Supermarkets:Mainstream grocery penetration remains limited by surfactant stability expertise concentration among legacy oral care R&D centers.
Online retailers dominate recurring revenue capture. Specialty shops are gaining share fastest through localized zero-waste density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemistry talent clusters in Germany's industrial corridor and the UK's pharmaceutical belt, anchoring European supply capacity for low-moisture compaction processes.
Germany
Zero-waste retail density in Berlin and Hamburg normalizes solid format trial among mainstream buyers. The EU Green Deal's single-use plastic restrictions force laminated tube abandonment ahead of enforcement deadlines. Bavaria's contract manufacturing hubs retrofit equipment lines for sub-five-percent moisture operations.
United Kingdom
Dental professional endorsement protocols in London and Manchester validate natural antimicrobial claims for fluoride-free positioning. REACH microplastic bans eliminate synthetic polymer competitors from formulation options. The Midlands health store chains consolidate shelf access for herbal variants with clinician backing.
United States
Travel enthusiasts in California and New York drive tablet format adoption through TSA-compliant carry-on convenience. FDA monograph control over fluoride concentration claims creates import barriers for therapeutic-positioning products. Pacific Northwest zero-waste retail networks build localized fulfillment infrastructure.
France
Extended producer responsibility fee structures in Paris and Lyon penalize conventional packaging formats. EN 13432 compostability certification requirements extend new product introduction cycles. The Provence-Alpes-Côte d'Azur region concentrates essential oil sourcing for herbal formulation bases.
Canada
Eco-conscious millennials in Toronto and Vancouver sustain premium pricing for zero-waste credentials. Health Canada regulatory frameworks govern fluoride tablet distribution with therapeutic claims. British Columbia's natural products manufacturing base controls raw material sourcing for clay-based formulations.
Solid Toothpaste Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and packaging engineering dimensions. The vendor base separates into three strategic archetypes: legacy oral care multinationals leveraging distribution scale, zero-waste pure-plays controlling compostable certification timelines, and dental professional channel specialists capturing prescription-adjacent fluoride positioning. Competitive moves concentrate on aluminum refill system deployment and cold-press compaction capacity expansion.
Among North American pure-play specialists, Nelson Naturals and Bite Toothpaste Bits exemplify the zero-waste archetype through subscription-model channel control. Georganics anchors UK positioning within the dental professional endorsement tier. These three companies represent distinct competitive vectors: Canadian manufacturing base control, direct-to-consumer aluminum refill systems, and clinician-validated glass jar distribution respectively.
| Leading Market Players |
|---|
| Hello Products (Colgate Palmolive) |
| Nelson Naturals |
| The Humble Co. |
| Weldental (Chew Tab) |
| Non Plastic Beach |
| Bite Toothpaste Bits |
| Georganics |
| Chomp Toothpaste |
| Denttabs |
| Others |
Pricing and Supply Chain Analysis
Formulation chemistry talent clustering in Germany's industrial corridor and the UK's pharmaceutical belt creates labor-cost differentials that spread pricing tiers across premium clinician-validated and economy direct-to-consumer segments.
Pricing Analysis
Bundled subscription services with aluminum refill systems command recurring revenue premiums against unbundled single-purchase compostable packs. Three-tier pricing structure across premium, standard, and economy levels separates dental professional-endorsed fluoride tablets from mass-market minty variants and private-label economy strips. Price differentiation hinges on compostable certification grade and subscription bundling depth. Cost compression in the standard tier is intensifying because REACH compliance investments concentrate among certified European suppliers, while eco-conscious millennials in direct-to-consumer channels show lowest price sensitivity.
Supply Chain Analysis
Ocean freight cost volatility from Southeast Asian coconut oil origins to North American fulfillment centers compresses margin predictability for clay-based formulation producers. Supply concentrates in Germany, the United Kingdom, and Canada, with cold-press compaction equipment retrofitting across Bavaria and the Netherlands. Raw material dependencies center on Sri Lankan and Philippine coconut oil, French essential oil extracts, and British calcium carbonate deposits. Single-source vulnerability runs through Southeast Asian base oil supply chains. Distribution runs through direct-to-consumer subscription platforms and consolidated health store chains in Germany and the UK.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs elevating European price floors and FDA regulatory friction suppressing US therapeutic-positioning margins.
For Market Incumbents: To counter subscription-model disintermediation by pure-play specialists, legacy oral care multinationals should deepen backward integration into compostable packaging certification capabilities and deploy aluminum refill systems through acquired direct-to-consumer platforms. Capacity addition in Germany's contract manufacturing corridor secures surfactant stability expertise concentration. For New Entrants and Emerging Players: EU Green Deal packaging mandates in Germany and France open a window for compostable pack specialists to capture shelf space ahead of enforcement deadlines. The most penetrable white space sits in dental professional endorsement protocols for prescription-adjacent fluoride tablet distribution. A go-to-market angle anchored in clinician validation protocols unlocks premium positioning unavailable to mass-market entrants. For Investors and Strategic Acquirers: Consumer goods conglomerates seeking sustainability portfolio expansion are the most active acquirer in this space. Five-to-ten year viability hinges on compostable certification capability consolidation and subscription-model infrastructure control. Acquisition targets should profile as zero-waste pure-plays with validated EN 13432 credentials and aluminum refill system deployment. The signal to watch is state-level extended producer responsibility fee structure adoption in California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Certification Investment | EN 13432 validation accelerates EU Green Deal compliance ahead of enforcement deadlines. |
| Aluminum Refill System Deployment | Subscription-model infrastructure captures recurring revenue from travel enthusiasts. |
| Dental Professional Channel Development | Clinician endorsement protocols unlock prescription-adjacent fluoride tablet positioning. |
| Cold-Press Capacity Expansion | German equipment retrofitting secures surfactant stability expertise concentration. |
| Backward Integration into Coconut Oil Sourcing | Southeast Asian supply base control mitigates price volatility from weather patterns. |
Research Methodology
Direct dialogue with brand managers at zero-waste pure-plays, category buyers at health store chains, formulation chemists at contract manufacturers, and dental professional endorsement coordinators grounded qualitative insights. Secondary validation drew from EU Green Deal regulatory filings, REACH microplastic restriction documentation, FDA monograph guidance, and customs records of coconut oil imports. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Bottom-up volume builds aggregated segment-level projections across product type, packaging format, customer archetype, and distribution channel dimensions. Top-down cross-checks applied macroeconomic elasticity assumptions to oral care category spending patterns. CAGRs derived from regression analysis of historical adoption curves in adjacent zero-waste personal care categories. Forecast inputs included EU Green Deal compliance timeline acceleration scenarios and FDA regulatory friction persistence assumptions.
Revisions become necessary when REACH enforcement intensity, FDA monograph reinterpretation, or coconut oil supply disruption materialize beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Impression Material Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Plaster Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Fluoride Materials Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Dental Restorative and Regenerative Material Market