
 Crack Tooth Syndrome Market | 2026-2036
Crack Tooth Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Crack Tooth Syndrome Market Analysis
ISO 6876 certification for root canal sealing materials is unwinding competitive access across the Crack Tooth Syndrome landscape, forcing smaller suppliers to recalibrate formulation investments. Dentsply Sirona Inc. leverages its integrated imaging-to-restoration workflow to dominate premium diagnostic placements. Henry Schein, Inc. anchors North American distribution through its direct-to-practice logistics network. Ivoclar Vivadent AG specializes in high-performance crown ceramics that sustain margin pools in restoration-intensive cases.
Crack tooth syndrome denotes an incomplete fracture of a tooth structure that propagates from the crown toward the root, typically triggered by occlusal overload or restorative stress concentration, with fracture depth measured via bitewing radiography or transillumination intensity loss to determine pulp involvement. The condition primarily serves to guide clinical decision-making between conservative restoration and endodontic intervention. Symptomatic presentations command the largest share of intervention volumes due to urgent pain-driven patient presentation, while vertical cracks represent the fastest-growing structural category as clinicians improve at detecting early longitudinal fractures before complete tooth separation. Transillumination and pulp vitality testing together capture expanding diagnostic share as practices invest in chairside adjunct tools that reduce reliance on radiographic interpretation alone.
FDA 510(k) clearance pathways for dental imaging devices shape product commercialization timelines, while ISO 13485 quality management requirements govern manufacturing consistency for diagnostic and treatment equipment sold into regulated markets. The EU Medical Device Regulation (MDR) reclassification of certain dental restoration materials is tightening conformity assessment burdens for European market access. Stakeholders must monitor evolving reimbursement coding for crack-specific diagnoses across national health systems to anticipate shifts in patient out-of-pocket exposure and treatment velocity.
Market Dynamics
Digital radiography and cone-beam computed tomography are compressing diagnostic timelines for incomplete tooth fractures, forcing clinicians to recalibrate referral patterns between general practice and endodontic specialists. This imaging shift is redistributing margin pools across the diagnostic-to-treatment workflow.
Growth Catalysts
- ISO 6876 certification:Harmonized standards for root canal sealing materials are streamlining cross-border material approvals, reducing regulatory duplication for multi-market suppliers.
- Aging demographics in Japan:Elevated occlusal wear rates among patients over 65 are expanding the addressable pool of symptomatic cases requiring intervention.
- Transillumination adjunct protocols:Chairside fiber-optic devices are reducing false-negative rates in early crack detection, improving case capture before pulp involvement.
Market Restraints
- Zirconia input cost volatility:Fluctuations in yttria-stabilized zirconia powder pricing are compressing margin stability for crown-intensive restoration workflows.
- EU MDR reclassification burdens:Tightened conformity assessment requirements for certain dental restoration materials are extending time-to-market for European product launches.
- Diagnostic substitution by CBCT:High-resolution three-dimensional imaging is cannibalizing demand for traditional bitewing interpretation in premium practices.
Strategic Opportunities
- Underpenetrated German ambulatory sector:Independent dental clinics in eastern federal states present whitespace for diagnostic equipment placement against hospital-affiliated competitors.
- AI-assisted fracture pattern recognition:Machine learning algorithms applied to radiographic databases are enabling predictive risk stratification for occlusal overload patients.
- Direct-to-practice logistics channels:Specialized distributors are bypassing traditional dental depot networks to reduce fulfillment friction for consumable restoration materials.
Industry Challenges
- Endodontic microsurgery skill scarcity:Limited fellowship-trained specialists capable of executing cracked-tooth preservation procedures are constraining service capacity expansion.
- FDA 510(k) imaging device timelines:Extended clearance durations for novel diagnostic hardware are deferring revenue recognition for equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crack Tooth Syndrome Market |
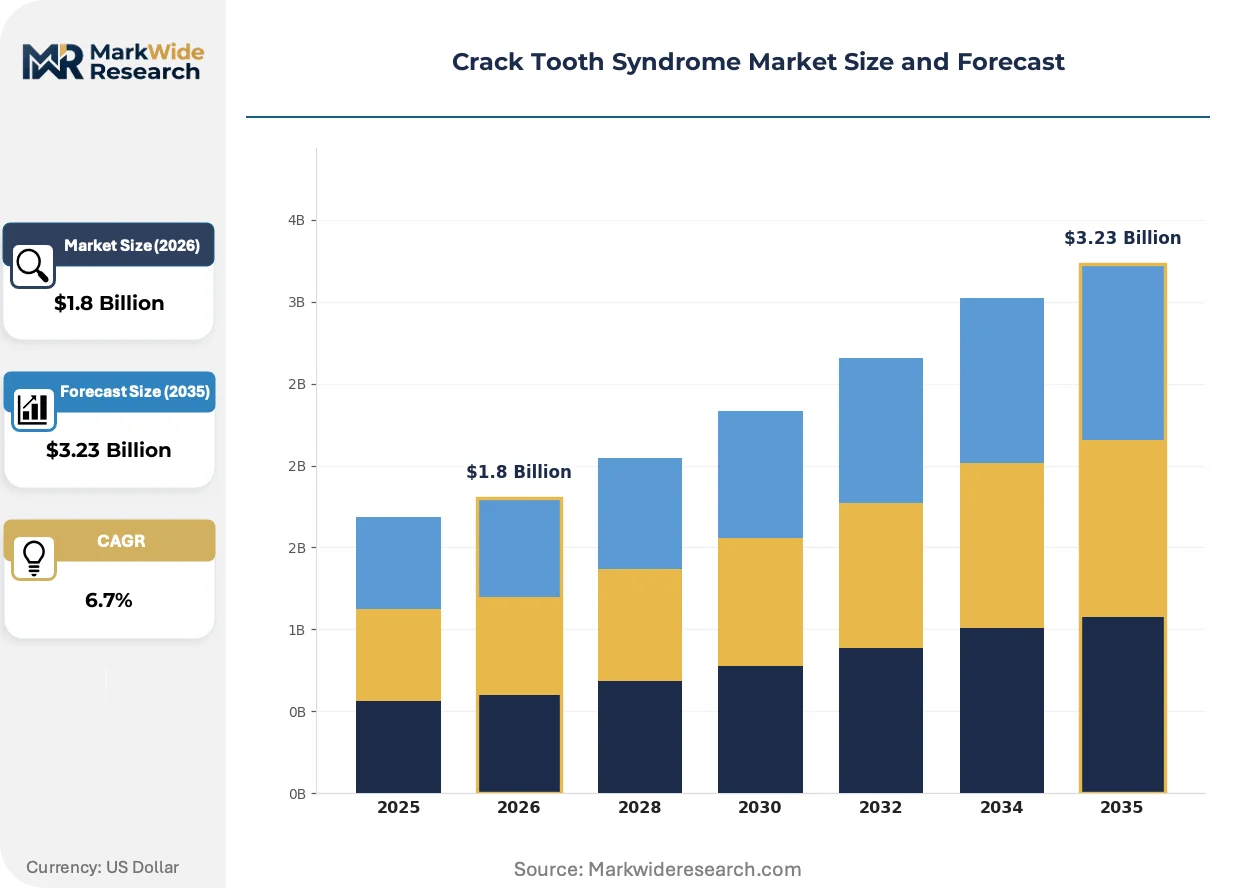
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Symptomatic, Asymptomatic, Vertical Cracks, Horizontal Cracks Treatment Option: Root Canal Therapy, Crown Restoration, Direct Restoration, Extraction Patient Age Group: Children, Adolescents, Adults, Seniors Diagnostic Method: Clinical Examination, Radiographical Analysis, Transillumination, Pulp Vitality Testing |
| Companies Covered | Ivoclar Vivadent AG, 3M, Henry Schein, Inc., Kavo Kerr, Coltene Holding AG, Dentsply Sirona Inc., GC Corporation, Shofu Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crack Tooth Syndrome Market Emerging Trajectories
Diagnostic accuracy imperatives are reshaping capital allocation across dental practices, with investment priority shifting from restoration hardware toward detection and case-planning software. This reorientation is compressing traditional equipment refresh cycles.
Cone-beam computed tomography systems with sub-millimeter voxel resolution are displacing conventional panoramic radiography for complex crack assessment. Endodontic specialists in the United States and Germany are adopting these platforms at accelerated replacement rates. The technology is displacing referral-based diagnostic workflows by enabling same-visit treatment planning in general practice settings.
The EU Medical Device Regulation's reclassification of certain crown ceramics is imposing new clinical evidence requirements on manufacturers seeking CE marking. This regulatory tightening is elevating compliance costs for mid-tier material suppliers. Restoration-intensive cases in France and Italy are experiencing delayed product availability as firms recalibrate technical documentation.
Patients are prioritizing pain-driven urgent presentations over scheduled preventive screenings, compressing the window between symptom onset and intervention. This behavioral shift is straining same-day scheduling capacity in United States metropolitan practices. Urban dental clinics in New York and Los Angeles are responding with expanded triage protocols to manage acute case volume.
Crack Tooth Syndrome Market Segmentation
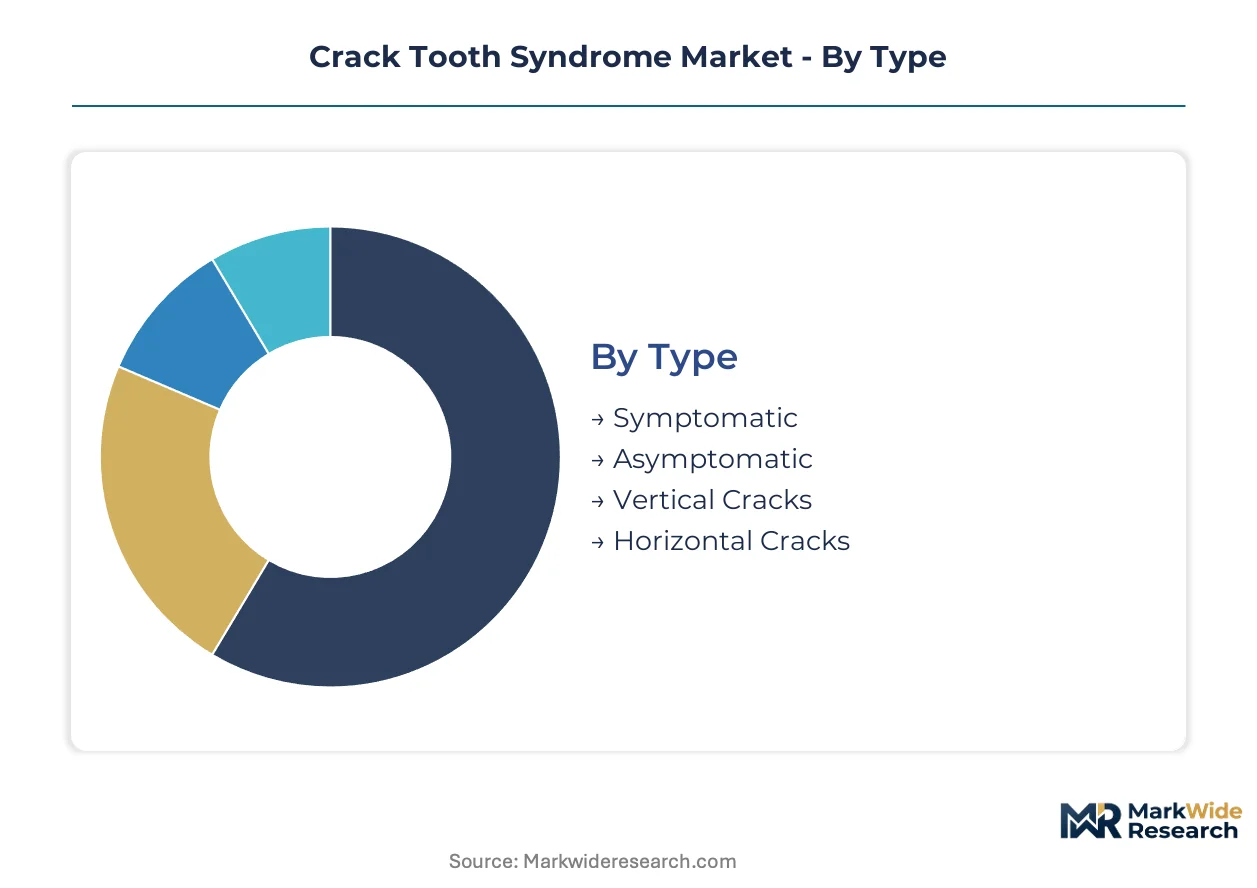
Crack tooth syndrome presents heterogeneous clinical manifestations that demand differentiated diagnostic and therapeutic protocols. Segmentation by fracture type, treatment modality, patient demographics, and detection method enables precise resource allocation across the care continuum.
Type:
FDA diagnostic coding distinctions and EU MDR risk classification frameworks create divergent reimbursement pathways for each fracture category.
- Symptomatic:Pain-driven presentations with pulp involvement or dentin hypersensitivity require urgent intervention protocols. United States metropolitan practices report elevated same-day scheduling pressure from this cohort, with New York and Los Angeles clinics expanding triage capacity to manage acute volume surges.
- Vertical Cracks:Longitudinal fractures propagating from crown to root represent the most technically challenging preservation scenarios. German endodontic specialists are expanding microsurgery fellowship programs to address capability scarcity in cracked-tooth retention procedures.
- Asymptomatic:Incidental radiographic findings during routine screening drive preventive restoration decisions.
- Horizontal Cracks:Circumferential fractures near the cementoenamel junction typically result from traumatic occlusion.
Symptomatic presentations handle the majority of throughput; vertical cracks are climbing the fastest on intervention share.
Treatment Option:
Margin pool distribution across the therapeutic workflow depends on material certification tiers and specialist labor availability.
- Root Canal Therapy:Endodontic intervention with ISO 6876-certified sealing materials preserves tooth structure in deep fracture cases. Japan's aging demographic over 65 is expanding demand for pulpal therapy as occlusal wear rates accelerate.
- Crown Restoration:Full-coverage ceramic or zirconia restorations protect compromised teeth from further fracture propagation. EU MDR reclassification of certain crown ceramics is extending time-to-market for European manufacturers, compressing product availability in France and Italy.
- Direct Restoration:Bonded composite repairs address superficial cracks without full crown preparation.
- Extraction:Terminal cases with complete root separation require prosthetic replacement planning.
Crown restoration captures the largest margin pool; root canal therapy is gaining share fastest as preservation protocols advance.
Patient Age Group:
Physiological tooth structure maturation and cumulative occlusal loading create distinct risk profiles across life stages.
- Seniors:Decades of functional wear, restored tooth structures, and diminished enamel elasticity elevate fracture susceptibility. German ambulatory dental clinics in eastern federal states are targeting this demographic with expanded diagnostic equipment placement.
- Adults:Peak functional demands from masticatory loading and bruxism behaviors concentrate intervention need in the 35-55 cohort.
- Adolescents:Traumatic sports injuries and erupting permanent dentition present unique fracture patterns.
- Children:Primary tooth trauma and developmental anomalies require pediatric-specific management protocols.
Seniors account for the steepest case volume trajectory; adults maintain the largest active treatment base.
Diagnostic Method:
Capital equipment refresh cycles and software integration requirements differentiate detection technology adoption curves.
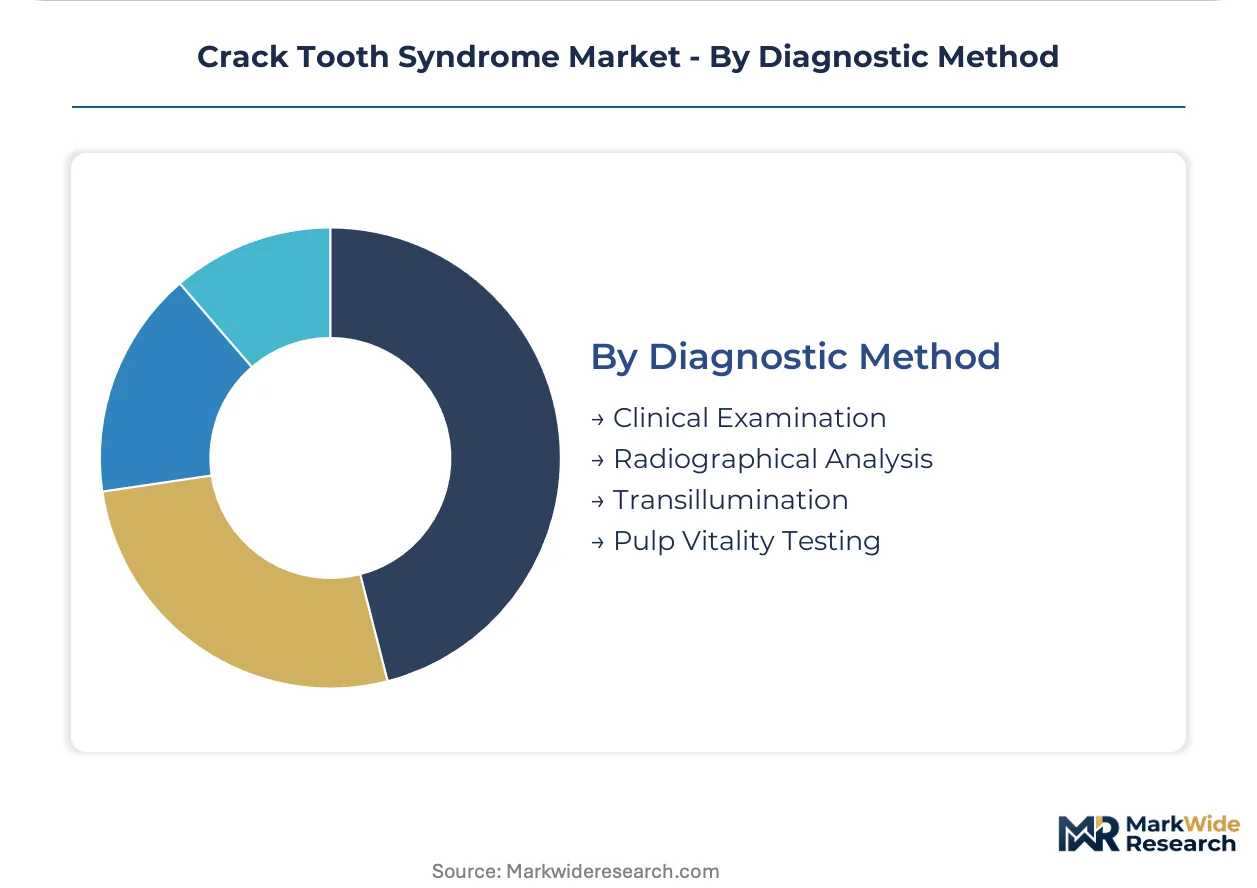
- Radiographical Analysis:Digital bitewing and periapical imaging remain the standard of care for fracture depth assessment. CBCT systems with sub-millimeter voxel resolution are displacing conventional panoramic radiography in United States and German endodontic practices.
- Transillumination:Fiber-optic chairside devices reduce false-negative rates in early crack detection. Henry Schein's direct-to-practice logistics network is accelerating deployment of these adjunct tools across North American general practices.
- Clinical Examination:Visual inspection and tactile probing with dental explorers provide initial screening sensitivity.
- Pulp Vitality Testing:Thermal and electric sensitivity assessments determine endodontic involvement extent.
Radiographical analysis handles the majority of diagnostic throughput; transillumination is expanding most quickly as chairside adjunct investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endodontic specialists and general dental practices in aging economies drive diagnostic equipment procurement. United States metropolitan clinics, German ambulatory networks, and Japanese geriatric dental services concentrate the highest intervention volumes.
United States
New York and Los Angeles dental clinics report acute same-day scheduling pressure from symptomatic patients. FDA 510(k) clearance pathways shape commercialization timelines for novel imaging hardware. CBCT systems with sub-millimeter voxel resolution displace conventional panoramic radiography in endodontic practices across the Northeast Corridor.
Germany
Independent dental clinics in eastern federal states present whitespace for diagnostic equipment placement against hospital-affiliated competitors. EU MDR reclassification of certain crown ceramics extends time-to-market for restoration material launches. Bavarian endodontic specialists expand microsurgery fellowship programs to address capability scarcity in cracked-tooth retention.
Japan
Patients over 65 exhibit elevated occlusal wear rates that expand the addressable pool of symptomatic cases. METI industrial standards govern dental device quality assurance protocols. Kanto region dental chains accelerate transillumination adjunct deployment to reduce false-negative detection rates in early fracture cases.
United Kingdom
London and Southeast England practices concentrate premium diagnostic placements amid private insurance reimbursement expansion. NHS coding evolution for crack-specific diagnoses shifts patient out-of-pocket exposure calculations. Midlands dental service organizations consolidate procurement of chairside fiber-optic detection tools.
France
ANSM regulatory oversight of dental restoration materials tightens conformity assessment burdens for European market access. Île-de-France endodontic centers experience delayed product availability as manufacturers recalibrate technical documentation. Auvergne-Rhône-Alpes dental clinics adopt AI-assisted fracture pattern recognition from radiographic databases.
Crack Tooth Syndrome Market Vendor Landscape
Player mix skews toward integrated imaging-to-restoration workflow providers alongside specialized material suppliers and regional distribution networks. Tiered competitive structure separates premium diagnostic equipment manufacturers from mid-tier consumable suppliers and value-oriented distributors. Strategic archetypes include full-solution integrators, single-category specialists, and logistics-anchored platforms. Dominant competitive moves encompass direct-to-practice channel expansion and diagnostic software portfolio diversification.
Among Swiss-anchored material specialists, Ivoclar Vivadent AG exemplifies the premium ceramic restoration archetype. Dentsply Sirona Inc. occupies a position within the integrated workflow tier, representing imaging-to-treatment convergence. Henry Schein, Inc. anchors the North American distribution vector, exemplifying logistics-anchored market access.
| Leading Market Players |
|---|
| Ivoclar Vivadent AG |
| 3M |
| Henry Schein, Inc. |
| Kavo Kerr |
| Coltene Holding AG |
| Dentsply Sirona Inc. |
| GC Corporation |
| Shofu Inc. |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates at ISO 13485-certified manufacturing facilities in Germany and Japan establish price floors for diagnostic equipment while concentrating supply leverage among premium-tier producers. Scale advantages in cone-beam computed tomography assembly compress per-unit costs for integrated workflow providers, forcing mid-tier competitors toward consumable specialization or distribution partnerships.
Pricing Analysis
Long-term supply agreements with yttria-stabilized zirconia powder suppliers typically incorporate London Metal Exchange indexation clauses that pass through raw material volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared imaging systems from CE-marked alternatives and unbranded consumables. Cost compression in standard-tier crown ceramics intensifies because EU MDR reclassification elevates technical documentation burdens. Price sensitivity concentrates among independent German dental clinics in eastern federal states, while Japanese geriatric dental chains demonstrate reduced elasticity for preservation-focused treatment modalities.
Supply Chain Analysis
United States, Germany, and Japan anchor production of sub-millimeter voxel resolution CBCT systems and ISO 6876-certified endodontic sealing materials. Manufacturing draws from specialized rare earth elements for imaging sensors, medical-grade polymers for fiber-optic transillumination devices, and precision-milled zirconia blanks for crown substrates. Single-source vulnerability concentrates in yttria-stabilized zirconia powder supply from limited specialty chemical producers. Distribution runs through direct-to-practice logistics networks that bypass traditional dental depot intermediaries, with Henry Schein's North American infrastructure exemplifying channel consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-assisted diagnostic platforms that reduce specialist interpretation dependency, requiring defensive repositioning around clinical workflow integration rather than hardware sales alone.
For Market Incumbents: Shield premium positioning by embedding diagnostic software into existing imaging hardware installed bases, creating switching costs against standalone AI entrants. Deepen backward integration into ISO 6876-certified sealing material production to capture margin pools shifting from equipment toward consumable-intensive preservation protocols. Prioritize channel control through exclusive direct-to-practice logistics partnerships that constrain competitor access to high-velocity metropolitan clinics.
For New Entrants and Emerging Players: Lead with AI-assisted fracture pattern recognition algorithms trained on anonymized radiographic databases from underpenetrated French and Italian markets where incumbent diagnostic software penetration remains limited. Target independent dental clinics in Germany's eastern federal states with equipment-as-a-service models that reduce capital expenditure barriers against hospital-affiliated competitors. Deploy transillumination adjunct devices through specialized distributors bypassing traditional depot networks.
For Investors and Strategic Acquirers: Single-category diagnostic software specialists with FDA 510(k) clearance pathways and established hospital system partnerships represent priority acquisition targets. Long-term viability hinges on consolidation of fragmented chairside detection tool markets into integrated imaging-to-treatment platforms. Monitor FDA 510(k) clearance velocity for novel CBCT hardware as inflection indicator for equipment replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Software Portfolio Diversification | AI-assisted fracture pattern recognition from radiographic databases enables predictive risk stratification for occlusal overload patients. |
| Direct-to-Practice Channel Expansion | Specialized distributors bypass traditional dental depot networks to reduce fulfillment friction for consumable restoration materials. |
| ISO 6876 Certification Investment | Harmonized standards for root canal sealing materials streamline cross-border approvals and reduce regulatory duplication burdens. |
| Microsurgery Fellowship Program Development | Bavarian endodontic specialists expand training capacity to address capability scarcity in cracked-tooth retention procedures. |
| CE Marking Pathway Acceleration | EU MDR reclassification of crown ceramics tightens conformity assessment requirements for European market access. |
Methodological Framework
Operator-level perspectives from endodontic specialists, dental clinic procurement managers, biomedical equipment engineers, and GPO contracts administrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, ISO certification registries, hospital procurement databases, and CMS Medicare reimbursement coding evolution. Bottom-up patient volume modeling and top-down equipment shipment triangulation converged on segment-level estimates across fracture type, treatment modality, and diagnostic method dimensions.
Sensitivity analysis tested forecast robustness against alternative scenarios for EU MDR implementation timing and zirconia input cost trajectories. Segmentation modeling incorporated fracture type, patient age cohort, detection technology, and regional regulatory cluster variations across the projection horizon. CAGRs derived from fitted growth curves applied to equipment replacement cycles and consumable utilization rates per procedure, with specific inputs including CBCT adoption velocity in United States metropolitan practices and transillumination adjunct deployment in Japanese geriatric dental chains.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR conformity assessment frameworks; material policy shifts would require re-modeling of commercialization timelines and market access economics. Specific risks that could revise projections include extended FDA imaging device clearance durations, further EU MDR reclassification of restoration materials, and acute zirconia supply disruptions. Recalibration cycles align with material shifts in reimbursement coding evolution and diagnostic technology replacement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Alloys Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Dental Putty Market
Dental Materials
Dental Alginate Market
Dental Materials
Fluoride Materials Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Bonding Agent Market