
 Dental Amalgam Market | 2026-2036
Dental Amalgam Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Amalgam Market Analysis
Public hospital procurement is restructuring demand patterns across the Dental Amalgam Market as government-funded dental programs in price-sensitive regions expand their restorative material budgets. Ivoclar Vivadent leverages its European manufacturing base to sustain premium-grade alloy supply chains for institutional buyers. SDI Limited anchors the Asia-Pacific trade through its Melbourne production facility, while AT&M Biomaterials competes on scale in the Chinese domestic market with standardized capsule formulations.
Dental amalgam constitutes a metallic restorative material typically composed of silver, tin, copper, and mercury alloyed into a pliable compound that hardens into durable fillings with compressive strength exceeding 400 MPa. Manufacturers cold-weld or triturate pre-dosed capsules to activate the mercury-alloy reaction before intraoral placement. Silver amalgam dominates product type revenue due to its established clinical track record and lower per-unit cost against mercury-free alternatives. High-strength amalgam captures margin concentration in pediatric dentistry applications where chewing load resistance proves critical. Direct sales channels control the bulk institutional segment, though distributors occupy growing share in fragmented private clinic networks across Latin America and Africa.
FDA 510(k) clearance requirements govern alloy composition limits and mercury vapor release thresholds for US market entry, while the Minamata Convention binds ratifying nations to phased mercury reduction in dental applications. ECHA REACH restrictions and EU MDR classification pressures are forcing European manufacturers to diversify toward encapsulated delivery systems with reduced mercury exposure risk. Stakeholders must monitor evolving national implementation timelines for mercury phase-down commitments and calibrate product portfolios between conventional alloy preservation and composite substitution investments.
Market Dynamics
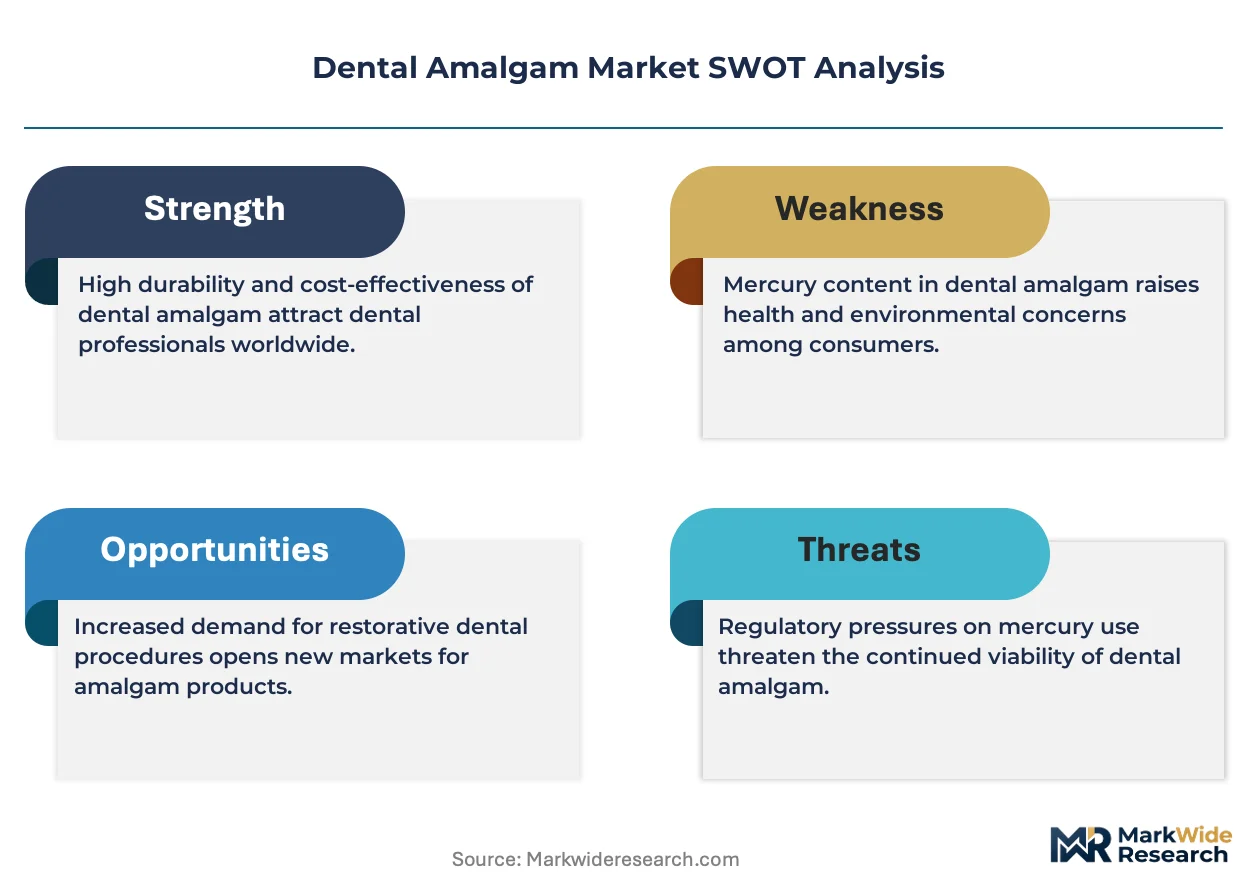
Mercury phase-down commitments under the Minamata Convention are fragmenting procurement patterns across public and private dental channels, forcing manufacturers to recalibrate alloy formulations and geographic prioritization simultaneously.
Growth Catalysts
- Public dental program expansion:Government-funded oral health initiatives in India, Indonesia, and Brazil sustain institutional demand for cost-effective restorative materials despite environmental scrutiny.
- REACH encapsulation standards:European manufacturers pivoting to pre-dosed capsule systems with reduced mercury exposure risk capture premium positioning in regulated markets.
- Pediatric durability requirements:High-copper amalgam alloys with compressive strength exceeding 400 MPa retain preference for posterior restorations in children where chewing loads prove extreme.
Market Restraints
- Mercury input cost volatility:Spot price fluctuations for elemental mercury concentrate margins for alloy producers dependent on bulk chemical procurement.
- Substitution threat from composite resins:Nanofilled and bulk-fill composite technologies with improved wear resistance displace amalgam in aesthetic-conscious private practices across North America and Western Europe.
- Minamata Convention ratification gaps:Uneven national implementation timelines create regulatory arbitrage that complicates manufacturer portfolio planning and inventory allocation.
Strategic Opportunities
- Rural clinic networks in Nigeria and Kenya:Underpenetrated East and West African markets with limited cold-chain infrastructure favor shelf-stable amalgam over temperature-sensitive composite alternatives.
- Encapsulated delivery system innovation:Single-use capsule designs with built-in trituration mechanisms reduce chairside mercury exposure and align with occupational safety mandates.
- India's National Oral Health Program:Central government procurement tenders for district hospital dental units create volume anchors for standardized alloy formulations.
Industry Challenges
- Mercury handling certification gaps:Dental school curricula in emerging markets lag in training proper amalgam waste segregation and spill response protocols.
- Dual inventory complexity:Manufacturers maintaining parallel conventional and reduced-mercury product lines face working capital strain and SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Amalgam Market |
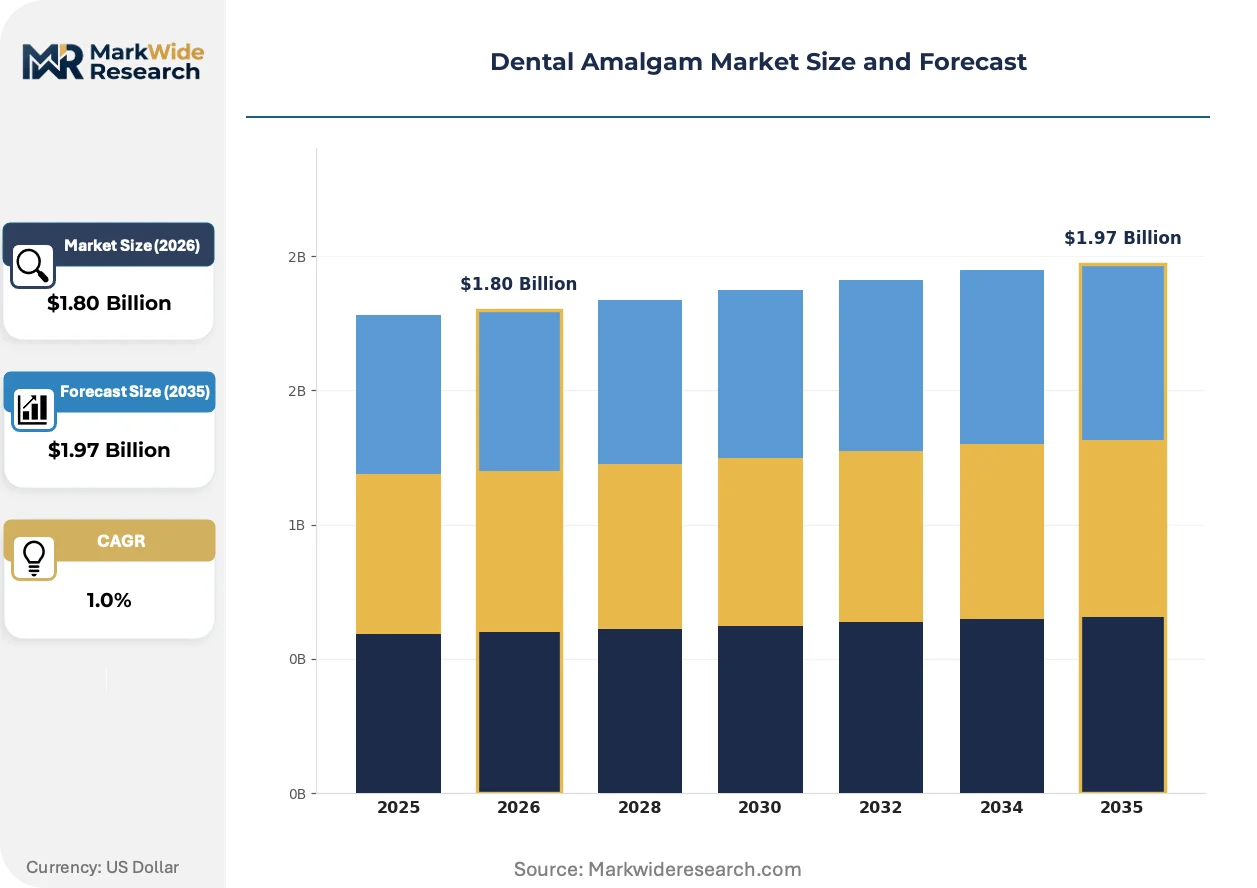
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Amalgam, Mercury-Free Amalgam, High-Strength Amalgam, Low-Strength Amalgam End User: Dentists, Dental Clinics, Hospitals, Research Institutions Application: Restorative Dentistry, Tooth Fillings, Preventive Care, Pediatric Dentistry Distribution Channel: Direct Sales, Online Retail, Distributors, Dental Supply Stores |
| Companies Covered | Ivoclar Vivadent, Cooksondental, Southern Dental Industries (SDI Limited), CY International, AT&M Biomaterials, Silmet Dental, Wykle Research, Foshan SCS Medical Instrument, Nordiska Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Amalgam Market Emerging Trajectories
Encapsulation engineering and mercury-sequestration chemistry are converging to extend amalgam's clinical relevance against polymer-based substitutes, while procurement centralization reshapes how restorative materials reach chairside.
Pre-dosed amalgam capsules with integrated mixing spheres are automating trituration consistency and reducing operator exposure to unbound mercury vapor. Public hospital dental departments across Southeast Asia adopt these systems at accelerating rates to comply with occupational health audits. The technology is automating quality standardization previously dependent on manual technique variation.
ECHA REACH restrictions on mercury compound classifications are compelling European manufacturers to reformulate alloy compositions and relocate production to jurisdictions with transitional grace periods. The regulatory pressure is compressing regional supply autonomy and accelerating technology licensing agreements with Asian partners. German and Swiss producers face the steepest compliance cost escalations under tightened MDR classification timelines.
Bulk institutional tenders from national health ministries are consolidating purchasing power and squeezing distributor margins across Latin America and Africa. Direct manufacturer-to-hospital contracts now displace traditional dental supply house intermediaries in Brazil, Mexico, and South Africa. This channel compression is most visible in state-level procurement for Brazil's Unified Health System dental units.
Dental Amalgam Market Segmentation
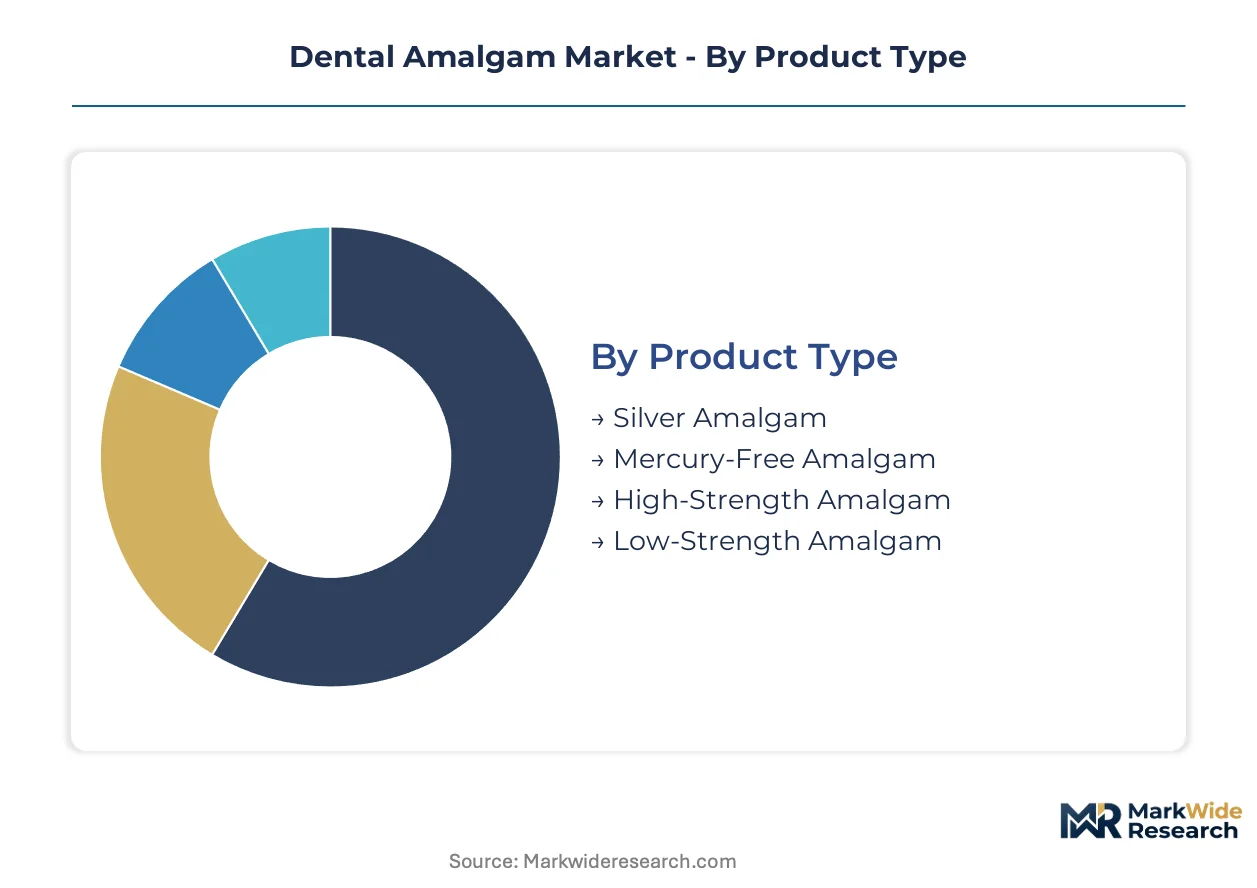
Dental amalgam procurement patterns diverge sharply across clinical settings, with cost constraints governing public hospital choices and aesthetic priorities driving private practice selection. Segmentation reveals how formulation chemistry, patient demographics, and supply chain architecture shape purchasing behavior across institutional and retail channels.
Product Type:
Cost sensitivity and mercury exposure regulations create divergent buyer profiles across alloy formulations.
- Silver Amalgam:Conventional silver-tin-copper-mercury alloy delivers compressive strength exceeding 400 MPa at the lowest per-unit cost. District hospitals in India and Indonesia anchor procurement volumes through government tender programs that prioritize durability over environmental concerns.
- High-Strength Amalgam:High-copper formulations with spherical particle architecture resist marginal fracture under extreme occlusal loads. Pediatric dentistry applications in Brazil's public health system favor this grade for posterior restorations in children with high chewing forces and limited compliance with recall schedules.
- Mercury-Free Amalgam:Gallium-based alternatives eliminate mercury content entirely while sacrificing some mechanical properties. European dental schools in Germany and Switzerland pilot these formulations to align with REACH occupational exposure mandates.
- Low-Strength Amalgam:Traditional lathe-cut particle alloys serve cost-minimal applications in temporary restorations and humanitarian dental missions across sub-Saharan Africa.
Volume sits with Silver Amalgam; growth tilts toward High-Strength Amalgam.
End User:
Procurement scale and regulatory exposure separate institutional buyers from independent practitioners.
- Hospitals:Public dental departments in India's National Oral Health Program generate consolidated tender volumes exceeding private clinic purchases by order of magnitude. Centralized procurement offices negotiate multi-year supply agreements with capsule manufacturers, squeezing distributor margins and standardizing on pre-dosed delivery systems to satisfy occupational health audits.
- Dental Clinics:Fragmented private practices across Latin America purchase through dental supply house networks with limited cold-chain infrastructure. Shelf-stable amalgam capsules dominate over temperature-sensitive composite alternatives in Mexico City and São Paulo clinic clusters.
- Dentists:Solo practitioners in Western Europe face the steepest compliance cost escalations under tightened MDR classification timelines, accelerating migration toward mercury-free alternatives.
- Research Institutions:University dental schools in Japan and South Korea drive formulation innovation through longitudinal clinical trials comparing alloy longevity against nanofilled composite performance.
Procurement concentrates in Hospitals; margin expansion favors Dental Clinics.
Application:
Patient age and restoration longevity requirements dictate alloy selection criteria.
- Restorative Dentistry:Posterior Class I and II cavities in permanent dentition represent the core clinical indication where amalgam's wear resistance justifies aesthetic compromise. Rural clinic networks in Nigeria favor this application where electricity interruptions compromise composite light-curing protocols.
- Pediatric Dentistry:High-copper alloys with rapid setting characteristics accommodate limited pediatric patient cooperation windows. Brazil's Unified Health System dental units specify this application for school-based screening programs.
- Tooth Fillings:Routine single-surface restorations in adult populations sustain baseline demand across Southeast Asian public health systems.
- Preventive Care:Interim therapeutic restorations using low-cost amalgam serve as caries arrestment strategy in resource-constrained settings prior to definitive treatment.
Restorative Dentistry commands volume share; Pediatric Dentistry climbs fastest.
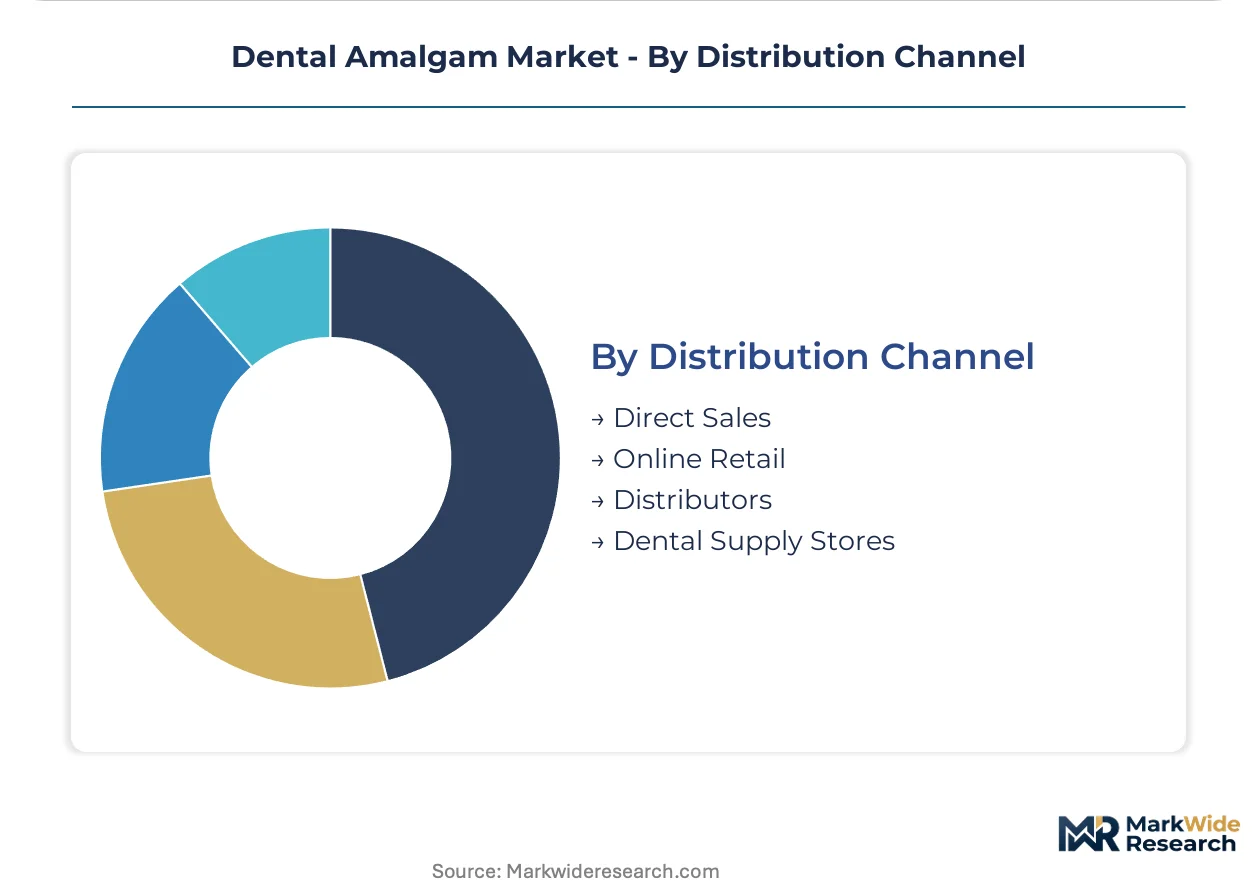
Distribution Channel:
Channel structure determines price realization and technical support intensity.
- Direct Sales:Manufacturer-to-hospital contracts now displace traditional intermediaries in Brazil, Mexico, and South Africa state procurement systems. Technical field support teams train dental nurses on proper trituration technique and waste segregation protocols.
- Distributors:Regional dental supply houses maintain inventory breadth across alloy types and capsule sizes for fragmented private clinic networks. Kenyan and Ghanaian distributors compete on delivery reliability to upcountry clinics with poor road infrastructure.
- Dental Supply Stores:Counter sales to walk-in practitioners persist in Indonesian and Philippine urban centers where immediate product availability outweighs price optimization.
- Online Retail:E-commerce penetration remains minimal due to hazardous material shipping restrictions and cold-chain requirements for certain alloy formulations.
Direct Sales capture institutional volume; Distributors retain private practice access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Oral Health Program operates as the dominant demand concentration zone, channeling government procurement through centralized tender systems that favor cost-effective silver amalgam capsules over mercury-free alternatives.
India
District hospitals under India's National Oral Health Program generate consolidated tender volumes that exceed private clinic purchases by order of magnitude. The Central Drugs Standard Control Organization (CDSCO) governs alloy composition standards for imported and domestic capsule formulations. Manufacturing clusters in Gujarat and Maharashtra supply standardized pre-dosed capsules to state procurement offices in Delhi and Chennai.
Brazil
Brazil's Unified Health System dental units sustain institutional demand through state-level procurement for posterior restorations in pediatric populations. The National Health Surveillance Agency (ANVISA) mandates mercury vapor exposure limits in dental clinic environments. São Paulo-based distributors compete on delivery reliability to municipal health departments across the Southeast region.
Germany
German dental schools pilot mercury-free gallium-based formulations to align with tightened ECHA REACH occupational exposure mandates. The Federal Institute for Drugs and Medical Devices (BfArM) classifies amalgam alloys under intensified MDR scrutiny. Manufacturing concentration in Baden-Württemberg shifts toward encapsulated delivery systems with reduced mercury content.
Indonesia
Public hospital dental departments in Jakarta and Surabaya adopt pre-dosed capsule systems at accelerating rates to comply with occupational health audits. The national pharmaceutical regulator enforces mercury handling certification for dental material importers. Urban supply houses in Java maintain inventory breadth across alloy types for fragmented private clinic networks.
Nigeria
Rural clinic networks in Lagos and Kano favor shelf-stable amalgam over temperature-sensitive composite alternatives due to electricity interruption risks. The national environmental protection agency lags in enforcing Minamata Convention phase-down timelines. Distributors in Abuja compete on upcountry delivery reliability to clinics with poor road infrastructure.
Dental Amalgam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring established alloy suppliers while private clinics access fragmented distributor networks. The market structure concentrates around three to five dominant capsule producers with integrated manufacturing capabilities. Strategic archetypes include European premium-grade specialists, Asia-Pacific scale producers, and Chinese domestic market competitors. Capacity expansion in encapsulated delivery systems and geographic licensing agreements represent the dominant competitive moves as manufacturers navigate regulatory divergence.
Among European-based manufacturers, Ivoclar Vivadent exemplifies the premium-grade specialist archetype through its Liechtenstein manufacturing heritage. Southern Dental Industries (SDI Limited) occupies a position as the scale-driven Asia-Pacific anchor with Australian production capabilities. AT&M Biomaterials represents the Chinese domestic market competitor archetype, competing on volume for standardized formulations within the national procurement system.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| Cooksondental |
| Southern Dental Industries (SDI Limited) |
| CY International |
| AT&M Biomaterials |
| Silmet Dental |
| Wykle Research |
| Foshan SCS Medical Instrument |
| Nordiska Dental |
| Others |
Supply Flow & Price Mechanics
Elemental mercury spot price volatility propagates through alloy manufacturing costs into tiered capsule pricing that separates premium encapsulated systems from economy-grade bulk alloy. CDSCO-mandated import certification for mercury-bearing materials adds compliance overhead that concentrates margin recovery in institutional tender channels serving India's National Oral Health Program.
Pricing Analysis
Short lead-time premiums attach to pre-dosed capsule systems with integrated trituration mechanisms demanded by Southeast Asian public hospitals facing occupational health audit deadlines. Three-tier pricing structure across premium, standard, and economy levels stratifies by mercury encapsulation grade and alloy particle architecture. Price differentiation hinges on CDSCO certification tier and volume scale in government tenders. Cost compression in economy-grade lathe-cut alloys is intensifying because Brazilian state procurement offices consolidate purchasing power under SUS dental unit expansion. District hospital procurement committees in India prove most price-sensitive; European dental schools under REACH mandates show least sensitivity as they pilot mercury-free gallium formulations.
Supply Chain Analysis
Freight cost exposure concentrates in temperature-sensitive gallium-based mercury-free alloys requiring controlled atmospheric shipping to German and Swiss dental schools. Manufacturing gravity centers on India, Australia, and China, with Gujarat and Maharashtra clusters feeding domestic Indian procurement while SDI Limited's Melbourne facility anchors Asia-Pacific trade. Raw material dependencies draw from elemental mercury concentrate, silver-tin-copper alloy feedstock, and precision capsule molding resins. Single-source vulnerability concentrates in mercury supply chains subject to Minamata Convention ratification gaps across Nigeria and Kenya. Distribution runs through direct manufacturer-to-hospital contracts displacing traditional dental supply houses in Brazil, Mexico, and South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental amalgam sector occupies a technology-transition phase as nanofilled composite resins with improved wear resistance displace metallic restorations in aesthetic-conscious private practices across Western Europe and North America.
For Market Incumbents: Anchor market position through backward integration into precision capsule molding capacity in Gujarat and Maharashtra to secure CDSCO-certified supply chains for India's National Oral Health Program tenders. Consolidate formulation R&D around high-copper spherical particle architectures that resist marginal fracture under pediatric chewing loads, defending against gallium-based substitute penetration in European dental schools.
For New Entrants and Emerging Players: Rural clinic networks in Nigeria and Kenya represent the most penetrable buyer archetype, with electricity interruption risks favoring shelf-stable amalgam over composite alternatives. Target East and West African markets through distributor partnerships emphasizing upcountry delivery reliability rather than cold-chain infrastructure. Pursue volume anchor contracts with Abuja-based distributors serving Kano and Lagos municipal health departments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale encapsulation specialists with REACH-compliant pre-dosed systems in Southeast Asian manufacturing jurisdictions. Long-term viability over the coming decade hinges on portfolio positioning between conventional alloy preservation and composite substitution investments. Watch ANVISA enforcement timelines for mercury vapor exposure limits in Brazilian SUS dental units as the critical inflection signal for regional demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Delivery System Scale-Up | Pre-dosed capsules with integrated trituration align with CDSCO occupational health mandates in Indian district hospitals. |
| Backward Integration into Alloy Feedstock | Captive silver-tin-copper supply secures margin protection against elemental mercury spot price volatility. |
| Mercury-Free Formulation Licensing | Gallium-based technology licensing to German manufacturers addresses REACH classification pressures under BfArM scrutiny. |
| Direct Hospital Contract Expansion | Manufacturer-to-SUS agreements in São Paulo bypass distributor margin compression under Brazilian state procurement consolidation. |
| Rural African Distribution Partnership | Abuja-based distributor alliances penetrate Nigerian clinic networks with poor road infrastructure and no cold-chain requirements. |
Methodological Framework
Independent corroboration across CDSCO import registration databases, ANVISA mercury vapor exposure filings, and Indian state procurement tender records underwrites the qualitative findings. Primary interviews with dental material procurement officers at India's National Oral Health Program, biomedical engineers at São Paulo municipal health departments, and distribution channel partners in Abuja and Lagos combined with secondary validation. Regulatory documentation from ECHA REACH restriction proposals, Minamata Convention national implementation reports, and FDA 510(k) alloy composition clearances anchored supply-side assessment. Bottom-up tender volume aggregation and top-down manufacturer capacity estimates provided cross-verification.
Rate-of-change decomposition across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured silver amalgam versus high-copper versus mercury-free formulation splits, hospital versus dental clinic procurement archetypes, and restorative versus pediatric dentistry applications. CAGRs derived from installed base erosion rates for metallic restorations and composite substitution elasticities in regulated versus unregulated markets. Forecast inputs incorporated Minamata Convention ratification timeline uncertainty and REACH encapsulation standard adoption curves.
Revisions become necessary when BfArM accelerates MDR classification timelines, ANVISA tightens mercury vapor enforcement, or nanofilled composite wear resistance crosses mechanical parity thresholds with high-copper amalgam. Forecasts reflect assumptions about regulatory implementation pacing and material science substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Alloys Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Plaster Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Toothpaste Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Bonding Agent Market