
 Dental Gypsum Market | 2026-2036
Dental Gypsum Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Gypsum Market Analysis
Skilled dental laboratory technicians is reorganizing output capacity across developed markets, tightening availability of precision die work and pushing clinics toward pre-mixed, high-strength formulations. Saint-Gobain Formula leverages captive gypsum reserves and integrated calcination networks to control raw material flow. Dentsply Sirona anchors its position through bundled digital workflow solutions that specify proprietary gypsum chemistries. Whip-Mix Corporation specializes in region-specific product portfolios calibrated to North American dental laboratory standards.
Dental gypsum comprises calcium sulfate hemihydrate produced through controlled calcination of gypsum rock, with particle size, porosity, and setting expansion dictating clinical performance in model accuracy and die strength. The material serves primarily as a mold and model substrate for crown, bridge, and implant prosthesis fabrication. High-Strength Gypsum and Type IV Gypsum command the dominant share of value pools, as dental laboratories prioritize dimensional stability for CAD/CAM scanning and ceramic pressing workflows. Fast-Set Gypsum shows the fastest volume trajectory, driven by same-day dentistry protocols that compress model production timelines from hours to minutes.
The FDA regulates dental gypsum as a Class II medical device, requiring 510(k) clearance for formulations marketed with specific clinical claims, while ISO 6873 establishes international standards for dental gypsum products governing setting time and compressive strength. The EU Medical Device Regulation imposes additional conformity assessment burdens on manufacturers exporting to European dental laboratories. Stakeholders must monitor evolving digital dentistry protocols, as intraoral scanner tolerance specifications increasingly dictate acceptable gypsum expansion parameters and may render legacy formulations obsolete without reformulation investment.
Market Dynamics
The maturation of intraoral scanning and CAD/CAM workflows is compressing production timelines for dental laboratories, forcing reformulation of gypsum chemistries to meet tighter dimensional tolerances and faster setting requirements.
Growth Catalysts
- FDA 510(k) pathway for digital workflow claims:Clearance requirements for gypsum products marketed with CAD/CAM compatibility specifications accelerate premium formulation adoption in United States dental laboratories.
- ISO 6873 standard harmonization:International alignment on setting time and compressive strength metrics reduces technical barriers for manufacturers expanding into European and Asian markets.
- Germany's dental technology cluster density:Concentration of precision laboratories in Bavaria and Baden-Württemberg sustains demand for Type IV and high-strength die materials calibrated to ceramic pressing protocols.
Market Restraints
- Calcined gypsum feedstock volatility:Energy-intensive kiln operations expose producers to natural gas price swings, compressing margins on standard-grade formulations.
- Captive reserve concentration:Saint-Gobain's integrated control of French and Spanish gypsum quarries limits independent access to pharmaceutical-grade raw material streams.
- Polymer resin substitution in digital workflows:3D-printed model materials are capturing same-day dentistry applications previously served by fast-set gypsum, threatening volume erosion in chairside segments.
Strategic Opportunities
- India's dental laboratory modernization:CDSCO regulatory alignment with ISO standards and expanding private clinic chains create entry points for compliant high-strength formulations.
- EU Medical Device Regulation technical documentation:MDR conformity assessment burdens favor established suppliers with quality management systems, creating acquisition opportunities for mid-tier European manufacturers.
- Convergence of intraoral scanning and AI-driven design:Software-tolerance specifications for model accuracy are opening specification partnerships between gypsum formulators and scanner OEMs.
Industry Challenges
- Dental laboratory technician attrition:Aging workforce in Germany and Japan is shrinking precision die-work capacity, forcing clinics to absorb quality variance or invest in automated mixing systems.
- Reformulation capex for scanner compatibility:Legacy gypsum lines require particle engineering investment to meet new expansion parameters without setting time degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Gypsum Market |
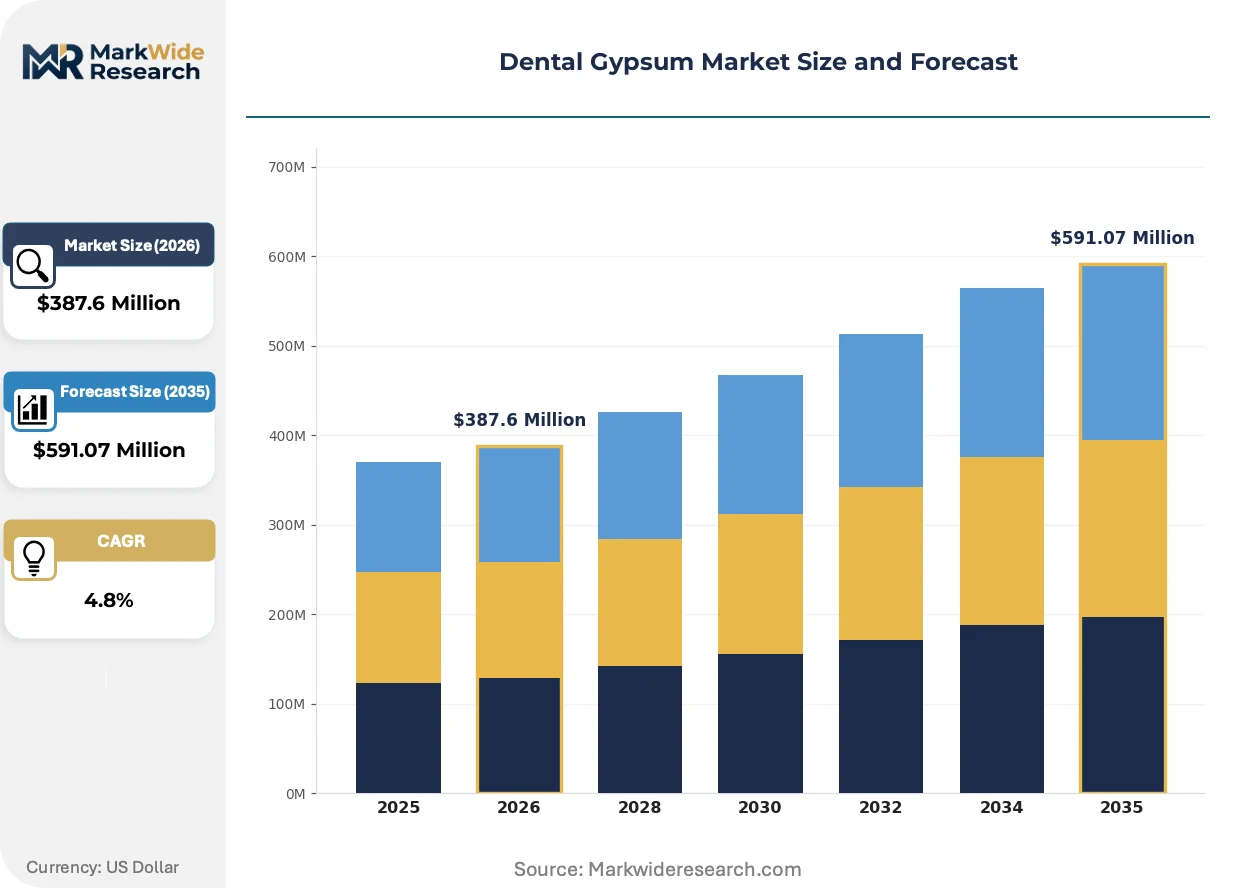
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Gypsum, High-Strength Gypsum, Fast-Set Gypsum, Type IV Gypsum Application: Cast Models, Impression Materials, Die Materials, Dental Restorations End User: Dental Clinics, Dental Laboratories, Hospitals, Educational Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Saint-Gobain Formula, Coltene, Dentsply Sirona, SHERA GmbH, GC America, Whip-Mix Corporation, Kerr Dental, Dentona AG, USG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Gypsum Market Emerging Trajectories
Digital dentistry protocols are rewriting material specifications across the value chain, with gypsum chemistry, regulatory documentation, and procurement models all undergoing simultaneous recalibration.
Fast-set calcium sulfate hemihydrate formulations with engineered particle morphology are decomposing traditional hour-long model production cycles. Same-day dentistry clinics in the United States and Germany are adopting these chemistries to compress crown delivery appointments. The technology is decomposing the historical separation between laboratory and clinical workflows, enabling chairside technicians to produce scan-ready dies within fifteen minutes.
EU Medical Device Regulation expanded technical documentation requirements are elevating compliance costs for gypsum manufacturers exporting to European dental laboratories. The regulation mandates clinical performance data and post-market surveillance systems previously reserved for higher-risk devices. Small and mid-sized suppliers in Italy and Spain are responding by consolidating quality management functions or exiting premium segments.
Dental laboratories are consolidating vendor relationships around suppliers offering bundled digital workflow validation. Large laboratory networks in the United States are replacing fragmented material sourcing with single-source contracts covering gypsum, investment materials, and scanner calibration support. This concentration is most visible in California and Texas, where multi-location groups are standardizing on pre-mixed high-strength systems to reduce technician training variance.
Dental Gypsum Market Segmentation
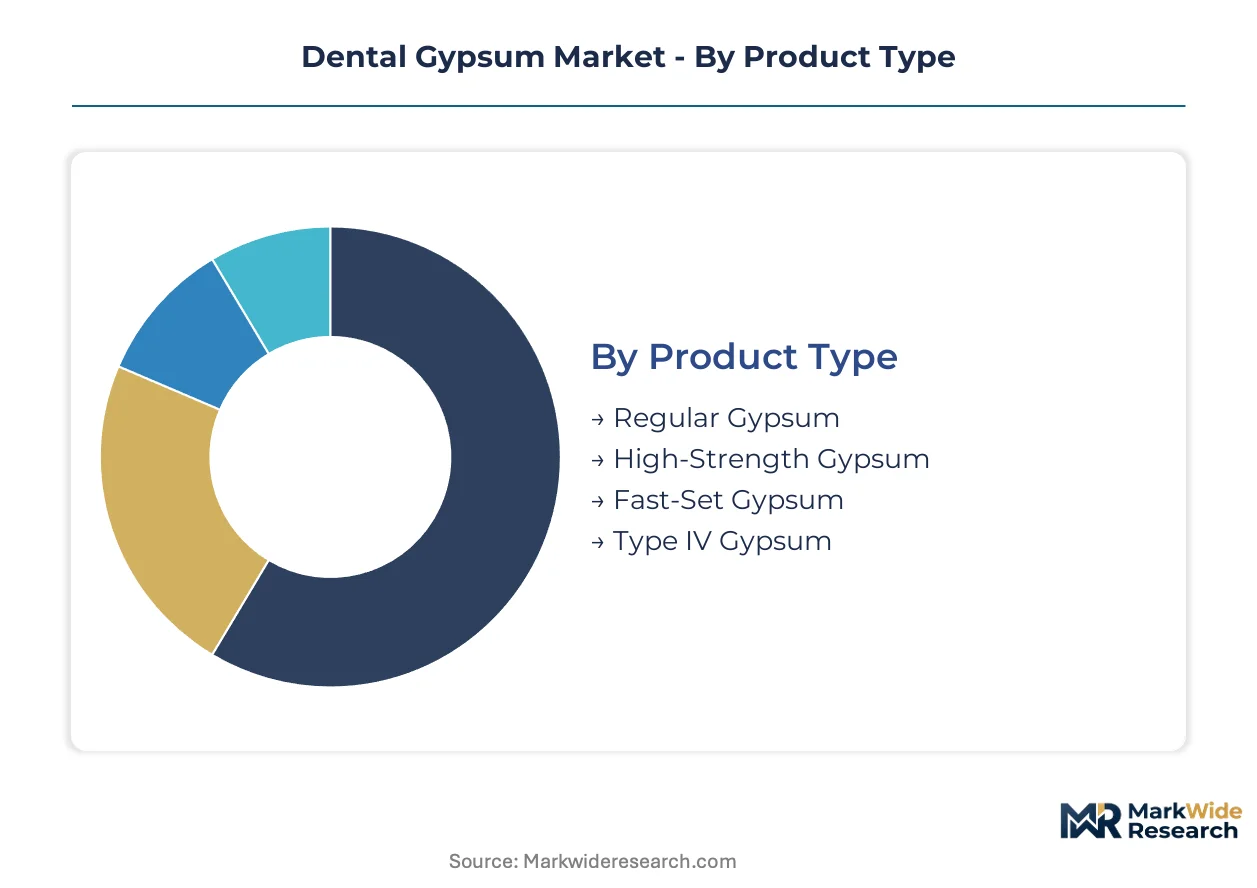
Segmentation in dental gypsum reveals where polymer resin substitutes and 3D-printed alternatives exert the strongest displacement pressure. Laboratories and clinics prioritize different performance thresholds, creating divergent procurement patterns across product grades and application workflows.
Product Type:
Substitution pressure from 3D-printed model materials falls unevenly across product tiers, with fast-set formulations facing the most immediate chairside displacement while high-strength die materials retain defensive moats through ceramic pressing compatibility.
- High-Strength Gypsum:Calcium sulfate hemihydrate with controlled particle morphology delivers compressive strength exceeding standard formulations. Bavarian dental technology clusters in Germany sustain concentrated procurement for ceramic pressing workflows requiring dimensional stability under thermal stress.
- Fast-Set Gypsum:Engineered crystal habit accelerates setting reactions to fifteen-minute working cycles. Same-day dentistry clinics in the United States compress appointment structures, though polymer resin substitutes now capture equivalent chairside applications at equivalent speed.
- Regular Gypsum:Standard calcined gypsum serves baseline cast and study model requirements in educational settings and cost-sensitive laboratories.
- Type IV Gypsum:Ultra-low expansion die stone calibrated to ISO 6873 Type IV specifications for crown and bridge fabrication requiring sub-25-micron accuracy.
High-Strength Gypsum anchors the volume base while Fast-Set Gypsum gains share at the steepest rate.
Application:
Application segmentation tracks the migration of production steps from laboratory to clinical settings, with die work remaining laboratory-resident while impression handling decentralizes toward chairside capture.
- Die Materials:Precision-machined substrates for crown, bridge, and implant prosthesis fabrication. German CAD/CAM integration protocols in Baden-Württemberg sustain premium specification demand for scanner-compatible surface hardness.
- Cast Models:Arch-form reproductions for orthodontic appliance construction and diagnostic evaluation. Volume concentrates in North American multi-location laboratory networks standardizing on pre-mixed systems.
- Dental Restorations:Direct restorative support applications including temporary crown matrices and bite registration.
- Impression Materials:Gypsum-bonded investment compounds for metal casting and ceramic pressing workflows.
Cast Models generate the highest absolute volume throughput while Die Materials command the strongest pricing premium per kilogram.
End User:
End-user structure reflects workforce capacity constraints, with technician attrition in Germany and Japan forcing clinics to internalize simpler workflows while complex die work concentrates in surviving precision laboratories.
- Dental Laboratories:Independent and networked fabrication facilities performing crown, bridge, and implant prosthesis production. California and Texas multi-location groups are consolidating vendor relationships around bundled digital workflow validation.
- Dental Clinics:Chairside service providers adopting fast-set systems for same-day delivery protocols. FDA 510(k) clearance requirements for CAD/CAM compatibility claims shape procurement specifications.
- Hospitals:Institutional dental departments with centralized procurement and standardized material formularies.
- Educational Institutions:Training programs consuming regular-grade gypsum for student technique development at volume-discounted contract pricing.
Dental Laboratories retain the highest per-account consumption intensity while Dental Clinics expand fastest through chairside workflow adoption.
Distribution Channel:
Channel configuration reflects the technical support intensity required for digital workflow integration, favoring direct relationships for complex laboratory accounts while commoditized clinic supply migrates online.
- Direct Sales:Manufacturer-to-laboratory relationships covering technical training, scanner calibration support, and quality management documentation. EU Medical Device Regulation conformity assessment burdens favor established suppliers with post-market surveillance infrastructure.
- Distributors:Regional specialty dental suppliers maintaining local inventory and same-day delivery capability for high-volume laboratory accounts.
- Online Retail:E-commerce platforms capturing standardized product procurement from small clinics and educational buyers with minimal technical support requirements.
- Wholesalers:Broad-line medical distributors serving institutional hospital contracts and government procurement programs.
Direct Sales commands the highest customer lifetime value while Online Retail expands most quickly through small-clinic digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes dental gypsum through precision laboratory networks calibrated to ceramic pressing protocols, while the United States deploys fast-set formulations for chairside same-day delivery. India and Japan diverge sharply—India's procurement concentrates in educational and cost-sensitive segments, Japan's in shrinking but high-specification technician workshops. China's consumption pattern remains laboratory-centric despite clinic digitization pressures.
United States
Multi-location dental laboratory networks in California and Texas consolidate vendor relationships around bundled digital workflow validation. FDA 510(k) clearance requirements for CAD/CAM compatibility claims shape procurement specifications for premium formulations. Same-day dentistry clinics in metropolitan markets compress appointment structures through fast-set system adoption.
Germany
Bavarian and Baden-Württemberg dental technology clusters sustain concentrated procurement for Type IV and high-strength die materials. EU Medical Device Regulation conformity assessment burdens favor established suppliers with quality management systems. Aging technician workforce in precision laboratories tightens availability of complex die work.
China
Domestic dental laboratory expansion drives volume consumption of regular and fast-set grades for model production. NMPA regulatory alignment with ISO standards shapes import requirements for high-strength formulations. Yangtze River Delta manufacturing bases supply calcined gypsum feedstock to regional formulators.
Japan
Shrinking dental laboratory technician population concentrates high-specification die work in surviving precision workshops. PMDA oversight of dental materials maintains stringent setting time and expansion documentation requirements. Tokyo-Osaka corridor laboratories prioritize scanner-compatible surface hardness in gypsum procurement.
India
Private dental clinic chain expansion creates entry points for compliant high-strength formulations in metropolitan markets. CDSCO regulatory alignment with ISO standards reduces technical barriers for imported premium products. Maharashtra and Karnataka training institutions consume regular-grade gypsum at volume-discounted contract pricing.
Dental Gypsum Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with raw material control and digital workflow bundling defining separation. Consolidated procurement by multi-location laboratory networks favors suppliers offering technical training and scanner calibration support. Two strategic archetypes dominate: integrated gypsum reserve holders with captive calcination infrastructure, and dental-focused formulators with region-specific product portfolios. Competitive moves concentrate on quality management system investment for EU MDR compliance and specification partnerships with intraoral scanner OEMs.
Among integrated material suppliers, Saint-Gobain Formula exemplifies the reserve-backed archetype through its position within a broader construction materials group. Dentsply Sirona and Whip-Mix Corporation occupy positions on the dental-specialist vector, with the former representing bundled digital workflow strategies and the latter illustrating region-specific portfolio calibration. SHERA GmbH anchors the European specialist tier alongside Dentona AG, both sitting within quality-intensive regulatory environments.
| Leading Market Players |
|---|
| Saint-Gobain Formula |
| Coltene |
| Dentsply Sirona |
| SHERA GmbH |
| GC America |
| Whip-Mix Corporation |
| Kerr Dental |
| Dentona AG |
| USG Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Saint-Gobain Formula and major French calcination facilities lock in both pharmaceutical-grade gypsum feedstock access and eighteen-month price visibility for Type IV die stone formulations, insulating premium tiers from natural gas volatility while exposing standard-grade producers to spot-market energy swings.
Pricing Analysis
Contract-based long-term offtake dominates procurement for high-strength and Type IV formulations, with pricing stratifying across premium scanner-compatible grades, standard laboratory grades, and economy educational tiers. Price differentiation rests on ISO 6873 certification tier and bundled digital workflow validation support. Cost compression in standard-grade segments is intensifying because polymer resin substitutes capture same-day chairside applications. Educational institutions in India exhibit highest price sensitivity, while Bavarian precision laboratories in Germany demonstrate lowest sensitivity due to ceramic pressing protocol requirements.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg elevate inbound logistics costs for calcined gypsum feedstock moving from Yangtze River Delta manufacturing bases. Geographic supply concentrates in France, Spain, and China. Raw material dependencies include pharmaceutical-grade gypsum rock, natural gas for kiln calcination, and specialized grinding media. Single-source vulnerability runs through Saint-Gobain's captive French and Spanish quarry network. Distribution runs through direct manufacturer-to-laboratory relationships for premium grades and regional specialty distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intraoral scanner OEM specification partnerships are reconstituting dental gypsum as a platform-dependent input, with interoperability certification becoming the primary gating factor for premium formulation access rather than standalone material performance.
For Market Incumbents: Fortify backward integration into pharmaceutical-grade gypsum reserves or lock in exclusive calcination capacity agreements to defend against feedstock concentration risk. Accelerate ISO 6873 and FDA 510(k) documentation investment to meet EU Medical Device Regulation post-market surveillance burdens before mid-tier European competitors consolidate quality management functions. For New Entrants and Emerging Players: CDSCO regulatory fast-track alignment with ISO standards unlocks India's private dental clinic chain expansion as the most penetrable white-space target. Target Maharashtra and Karnataka metropolitan markets through volume-discounted contract pricing for regular-grade educational supply, then ladder into high-strength formulations via technical training partnerships with expanding laboratory networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier European manufacturers with established quality management systems but incomplete EU MDR technical documentation, positioned as acquisition targets for established suppliers seeking conformity assessment infrastructure. Watch for scanner OEM specification partnership announcements as the inflection indicator signaling which formulation chemistries will capture CAD/CAM workflow bundling contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Specification Partnership with Intraoral Scanner OEMs | Locks in premium formulation demand through bundled digital workflow validation protocols. |
| EU MDR Quality Management System Investment | Creates compliance moat against mid-tier Italian and Spanish competitors facing documentation burdens. |
| Captive Gypsum Reserve Acquisition | Secures pharmaceutical-grade feedstock independence from Saint-Gobain's integrated quarry network. |
| Fast-Set Chemistry Reformulation Program | Defends chairside volume against polymer resin substitution in same-day dentistry protocols. |
| India CDSCO Regulatory Fast-Track Entry | Captures private clinic chain procurement before domestic formulators achieve ISO alignment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental laboratory directors, CAD/CAM workflow technicians, GPO contracts managers, and regulatory affairs leads at gypsum formulators; and secondary validation through FDA 510(k) filings, ISO 6873 certification databases, EU MDR technical documentation registries, and customs trade data on calcined gypsum imports. Bottom-up demand modeling from individual laboratory procurement patterns was triangulated against top-down market sizing from manufacturer production disclosures.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product grade tier, application workflow, end-user archetype, and regional regulatory cluster. CAGRs were derived from segmented growth rate analysis applied to base-year market sizing. Industry-specific forecast inputs included intraoral scanner installation rates by dental laboratory network and ceramic pressing protocol adoption curves in German precision clusters.
Decision-makers should treat outputs as directional under assumptions of continued FDA 510(k) pathway stability and no disruptive substitution of gypsum by 3D-printed model materials; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and polymer resin chairside adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Amalgam Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Fluoride Materials Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Composites Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Materials for 3D Printing Market