
 Dental Zirconia Powder Market | 2026-2036
Dental Zirconia Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Zirconia Powder Market Insights
Zirconia dioxide is restructuring crown and bridge economics as dentists abandon metal-ceramic systems. Tosoh Corporation leverages vertical integration from raw mineral to sintered blank, sustaining cost discipline across its supply chain. Aidite Technology Co., LTD dominates chairside milling workflows in China, while Ivoclar Vivadent anchors premium positioning through proprietary shading systems.
Dental zirconia powder consists of yttria-stabilized tetragonal zirconia polycrystal (Y-TZP), typically containing 3-5 mol% yttria to achieve flexural strength exceeding 900 MPa after sintering at 1350-1450°C. Monolithic zirconia leads volume consumption due to its fracture resistance and reduced chairside time, though layered formulations command margin pools in anterior aesthetic cases. Dental laboratories represent the fastest-growing end user channel as outsourcing consolidates in-house milling operations.
The FDA governs 510(k) premarket notification for dental zirconia devices, while the EU Medical Device Regulation mandates notified body involvement under Class IIa rules. ISO 13356 specifies chemical and physical requirements for surgical-grade zirconia, directly influencing procurement specifications by hospital systems. Stakeholders must monitor evolving reimbursement codes for chairside CAD/CAM restorations as payers recalibrate fee schedules.
Market Dynamics
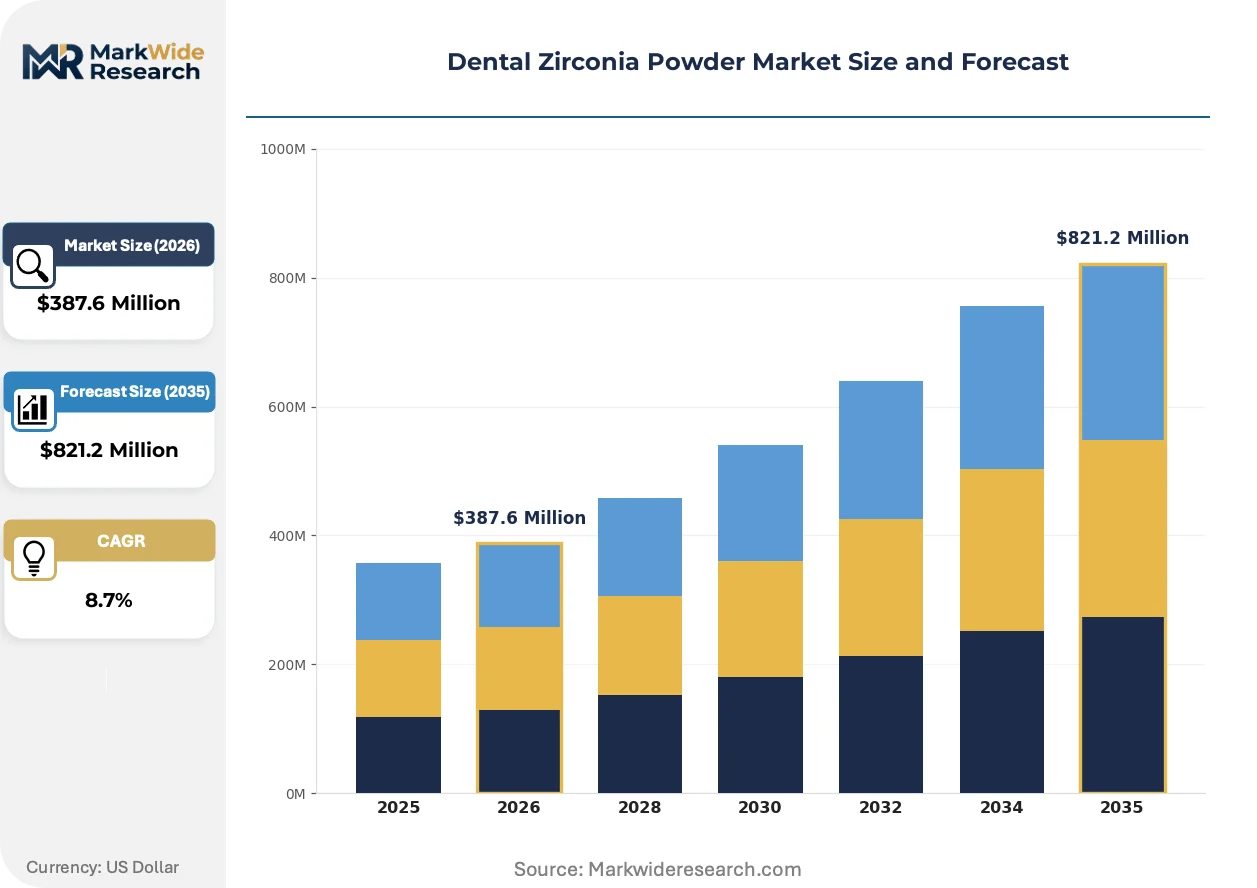
The transition from metal-ceramic to monolithic zirconia restorations is compressing fabrication timelines and reshaping dental laboratory economics worldwide. This material shift eliminates porcelain layering steps while demanding new CAD/CAM infrastructure investments across the supply chain.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's premarket notification process for dental zirconia devices accelerates product commercialization timelines, reducing regulatory friction for manufacturers seeking US market entry compared to full PMA requirements.
- Chairside CAD/CAM adoption:Dental clinics and group practices are installing in-office milling systems, creating direct demand for pre-sintered zirconia blanks and shifting volume from centralized laboratories.
- EU Medical Device Regulation harmonization:MDR Class IIa classification with notified body involvement creates predictable compliance frameworks that reduce market fragmentation across EU member states.
Market Restraints
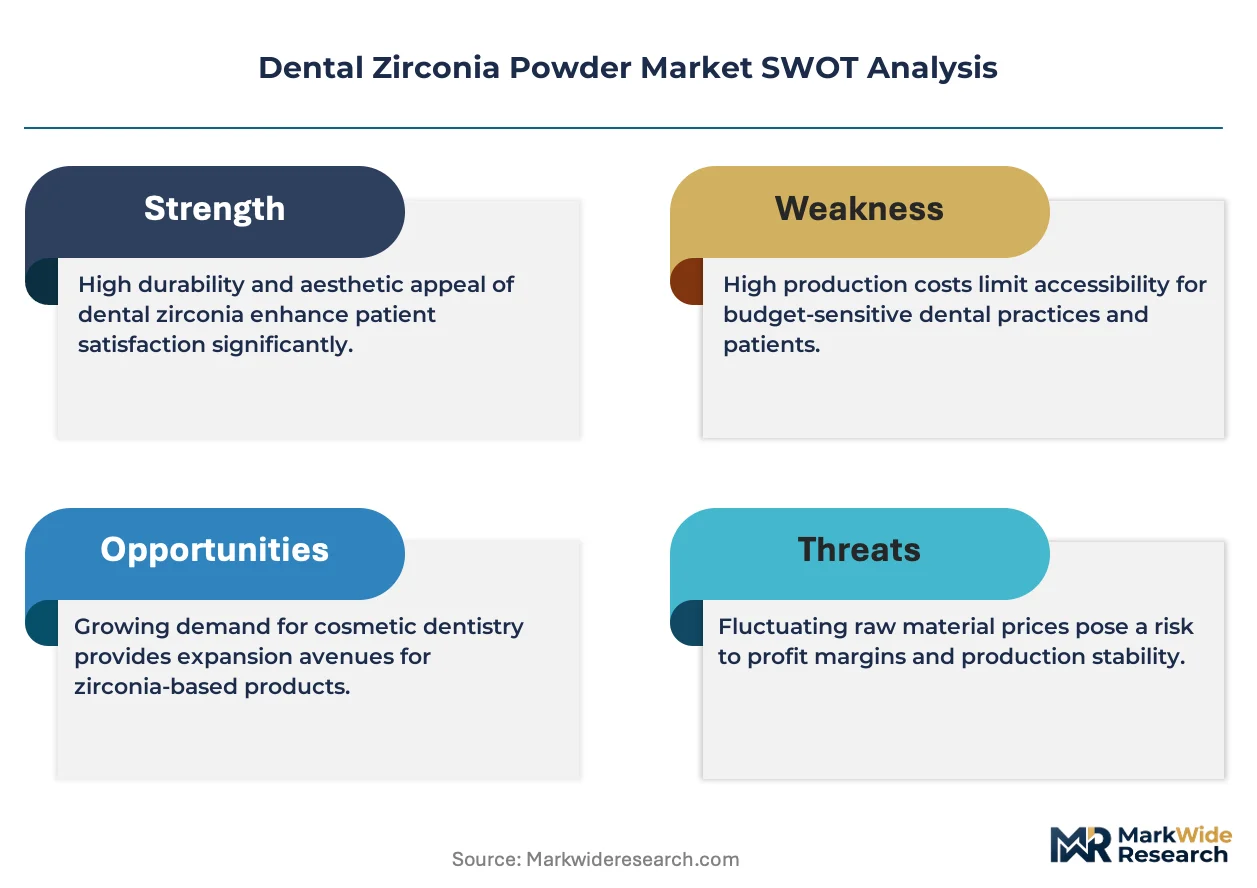
- Yttria supply concentration:Rare earth processing for yttrium oxide stabilizers concentrates in Chinese refining operations, exposing powder producers to input cost volatility and geopolitical supply disruptions.
- Sintering energy intensity:Furnace operations requiring 1350-1450°C for 8-10 hours impose fixed energy costs that scale poorly with batch sizes, compressing margins for smaller laboratories.
- Polymer-infiltrated ceramic network competition:Hybrid materials like VITA Enamic offer chairside polishability and lower abrasiveness to antagonist dentition, threatening zirconia's position in posterior crown applications.
Strategic Opportunities
- India dental infrastructure expansion:The country's PLI scheme for medical devices and nascent dental insurance penetration create whitespace for powder suppliers targeting price-sensitive prosthetic laboratories in Mumbai and Delhi clusters.
- Multi-layer gradient zirconia:Translucent-to-opaque property gradients in single pucks eliminate manual layering while preserving aesthetic outcomes, commanding premium positioning in anterior restoration workflows.
- Digital workflow integration:Convergence of intraoral scanning, AI-based margin detection, and automated nesting software reduces technician labor per unit, enabling laboratory scale economies previously unattainable.
Industry Challenges
- CAD/CAM technician certification gaps:Laboratory workflows now demand proficiency in 3D design software and milling parameter optimization, creating workforce bottlenecks as traditional ceramists transition to digital platforms.
- ISO 13356 testing backlog:Surgical-grade zirconia certification requires extensive biocompatibility and mechanical property documentation, extending product development cycles for new powder formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Zirconia Powder Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Layered, Pre-shaded, Custom Application: Crowns, Bridges, Veneers, Implant Abutments End User: Dentists, Dental Laboratories, Clinics, Hospitals Form: Powder, Disc, Block, Liquid |
| Companies Covered | Ivoclar Vivadent, Dentsply Sirona, 3M, Tosoh Corporation, Kuraray Noritake Dental, Pritidenta GmbH, Aidite Technology Co., LTD, GC America, Zirkonzahn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Zirconia Powder Market Trends and Innovations
Digital dentistry infrastructure is compressing the traditional crown fabrication value chain from two-week laboratory cycles to same-day chairside delivery. This compression demands powder formulations optimized for accelerated sintering protocols without sacrificing translucency or flexural performance.
High-translucency zirconia with 4-5 mol% yttria stabilization is converging with lithium disilicate aesthetic standards in anterior indications. Dental laboratories in Germany and Japan are adopting these formulations for monolithic veneers and anterior crowns, displacing traditional feldspathic porcelain in premium cases. The structural consequence is a bifurcation in powder portfolios between high-strength posterior grades and aesthetic anterior formulations.
The EU Medical Device Regulation's Unique Device Identification requirements are forcing powder-to-blank traceability systems throughout the supply chain. Manufacturers must implement lot-level tracking from raw mineral sourcing through final sintered blank distribution, increasing compliance overhead but creating competitive differentiation for early adopters. German and Swiss suppliers are responding fastest, leveraging existing pharmaceutical-grade quality systems.
Group dental practices and dental service organizations are consolidating procurement decisions previously fragmented across individual laboratories. This buyer concentration is shifting purchasing power toward direct mill blank contracts and away from distributor-mediated powder sales, compressing channel margins in the United States and United Kingdom. Large DSOs now negotiate annual volume commitments with Tosoh Corporation and Ivoclar Vivadent for captive supply security.
Dental Zirconia Powder Market Segmentation
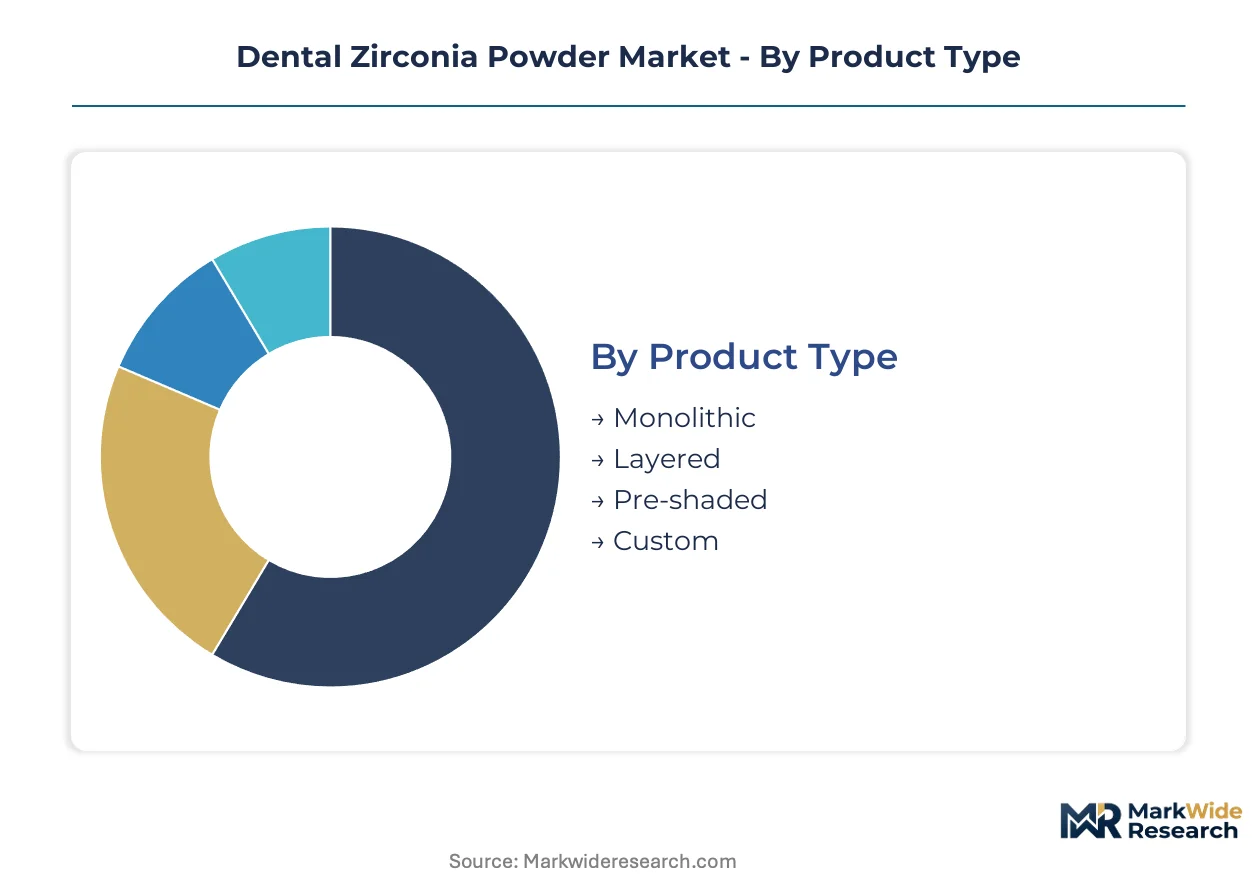
Zirconia powder formulations diverge sharply in sintering behavior and aesthetic performance, forcing procurement decisions that lock laboratories into specific furnace and milling ecosystems. Each segment carries distinct capital requirements and margin profiles that reshape competitive positioning across the supply chain.
Product Type:
Capital intensity varies most dramatically here, with furnace infrastructure and shading systems determining total cost of ownership for laboratories.
- Monolithic:Single-layer construction achieves flexural strength exceeding 900 MPa through 3 mol% yttria stabilization, eliminating porcelain veneer steps. German and US dental laboratories drive volume for posterior crowns where fracture resistance dominates material selection. Chairside milling adoption accelerates demand as clinics seek same-day delivery without outsourcing.
- Layered:Bilayer zirconia frameworks support hand-stacked porcelain veneers for anterior aesthetic cases demanding translucency gradients. Premium laboratories in Japan and Switzerland specify these formulations for high-visibility restorations where lithium disilicate falls short on strength. Manual layering steps extend fabrication timelines but preserve margin pools unavailable to monolithic alternatives.
- Pre-shaded:Pigmented powder eliminates post-sintering staining, reducing technician labor per unit.
- Custom:Patient-specific formulations match adjacent dentition through spectrophotometer-derived prescriptions.
Most installed capacity flows through Monolithic. Expansion is steepest in Pre-shaded.
Application:
Clinical indication determines yttria content specifications and sintering protocols, creating application-specific supply contracts.
- Crowns:Posterior full-coverage restorations consume the majority of high-strength 3 mol% yttria grades, with dental laboratories in Germany specifying these for molar replacements where occlusal loads exceed 400 N. Monolithic fabrication dominates as chairside CAD/CAM systems compress delivery from two weeks to single appointments.
- Bridges:Multi-unit fixed partial dentures demand connector dimensions above 9 mm² to prevent flexural failure under functional loading. Laboratories in the United States specify high-translucency 4-5 mol% yttria formulations for anterior bridges where aesthetic integration with natural dentition determines case acceptance.
- Veneers:Minimal-preparation laminates require ultra-translucent zirconia competing directly with feldspathic porcelain.
- Implant Abutments:Titanium-zirconia hybrid interfaces demand precision-milled screw-retained components.
Volume concentrates in Crowns. Bridges are gaining share fastest in aesthetic-forward markets.
End User:
Procurement authority is fragmenting as group practices consolidate previously independent laboratory relationships.
- Dental Laboratories:Centralized milling operations in Germany, the United States, and Japan account for the majority of bulk powder purchases, leveraging batch sintering economies across multiple clinician accounts. These facilities are consolidating through acquisition as dental service organizations seek captive supply security.
- Dentists:Chairside CAD/CAM adoption in China and South Korea creates direct demand for pre-sintered blanks, bypassing traditional laboratory intermediaries. Solo practitioners face steeper learning curves for design software and milling parameter optimization.
- Clinics:Multi-chair group practices negotiate annual volume commitments with Tosoh Corporation and Ivoclar Vivadent.
- Hospitals:Academic medical centers specify ISO 13356-certified surgical-grade zirconia for complex reconstructive cases.
Procurement weight rests with Dental Laboratories. Dentist-direct purchasing is climbing the fastest.
Form:
Physical configuration determines shipping economics and inventory carrying costs across distribution channels.
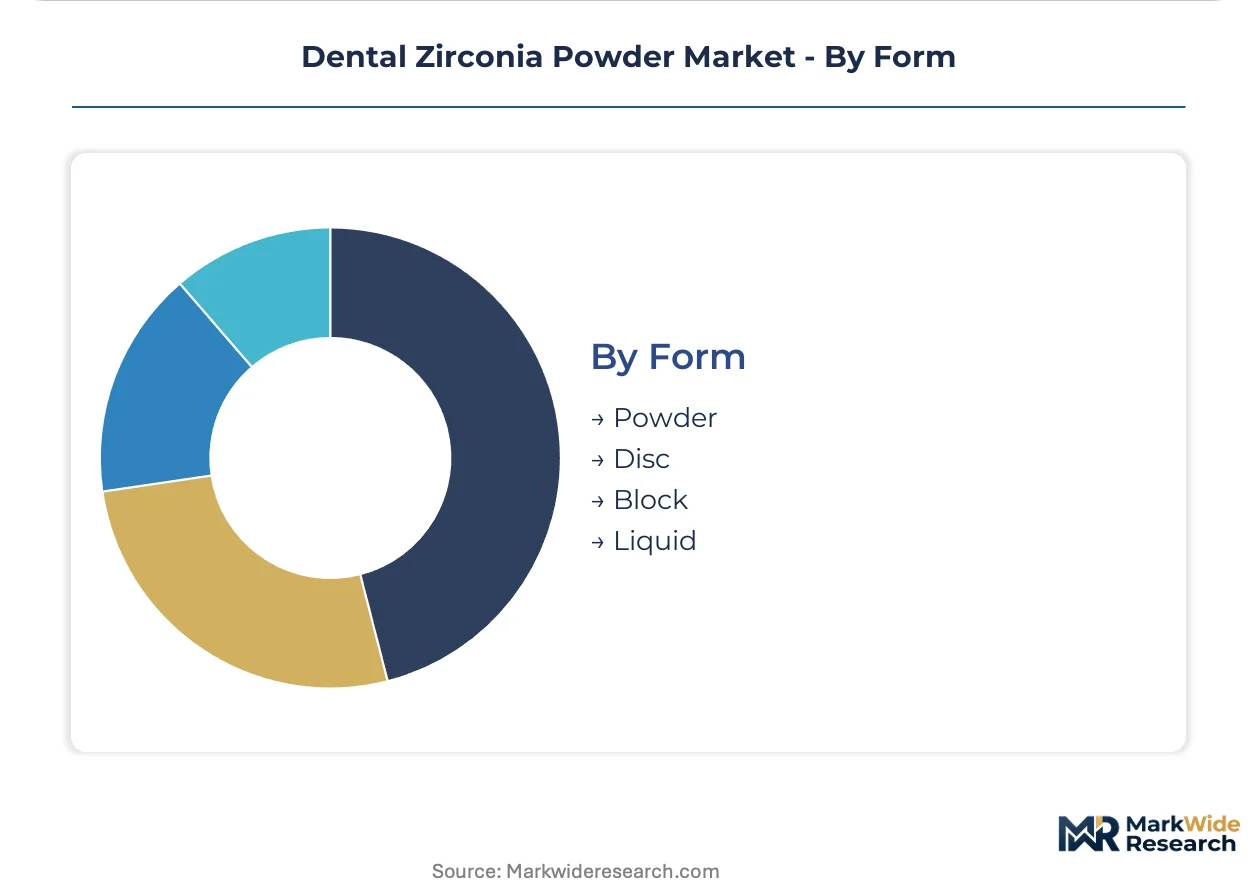
- Powder:Unsintered particulate enables custom pressing and isostatic compaction for specialized geometries, with Japanese suppliers dominating pharmaceutical-grade purification standards. Laboratories with in-house pressing capacity prefer this flexibility for large-span bridge frameworks exceeding standard blank dimensions.
- Disc:Pre-pressed circular blanks align with common milling machine spindles, representing the default format for chairside CAD/CAM systems. Aidite Technology Co., LTD and competitors in China optimize disc diameters for domestic milling machine specifications.
- Block:Rectangular prisms suit multi-unit bridge nesting and automated production workflows.
- Liquid:Slip-casting suspensions serve specialized pressing operations and research applications.
Disc format commands the largest installed base. Block shipments are expanding most quickly in high-throughput laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian supply chains dominate zirconia powder production, with Japanese and Chinese producers controlling yttria stabilization chemistry and pressing technologies that downstream dental laboratories depend upon.
United States
Dental service organizations in Texas and Florida consolidate procurement across multi-chair practices, driving direct mill blank contracts with suppliers. FDA 510(k) premarket notification governs device clearance timelines. The Greater Boston corridor hosts specialized CAD/CAM training centers addressing technician certification gaps.
Germany
Bavarian dental laboratories specify high-translucency formulations for anterior aesthetic cases demanding natural light transmission. CE marking under EU Medical Device Regulation Class IIa rules mandates notified body involvement for market access. The Cologne-Düsseldorf industrial belt concentrates pressing and sintering operations serving Benelux export markets.
China
Chairside milling adoption accelerates in Shenzhen and Shanghai clinic clusters, creating direct demand for pre-sintered disc formats. The country's rare earth refining dominance controls yttrium oxide stabilizer supply. Aidite Technology Co., LTD anchors domestic supply chains for price-sensitive prosthetic workflows.
Japan
Tokyo-Osaka dental laboratories adopt multi-layer gradient zirconia for premium anterior restorations. METI industrial standards influence pharmaceutical-grade purification specifications. Tosoh Corporation leverages upstream chemical processing capabilities from raw mineral to finished blank.
India
Mumbai and Delhi laboratory clusters expand capacity as dental insurance penetration deepens. The PLI scheme for medical devices attracts powder suppliers targeting price-sensitive prosthetic markets. CDSCO registration requirements shape import substitution strategies for domestic manufacturers.
Dental Zirconia Powder Market Competitive Landscape
Global majors compete with regional champions across supply chain control and distribution reach, creating a tiered structure where backward integration separates price leaders from premium positioning. Japanese and German chemical conglomerates dominate upstream yttria stabilization and isostatic pressing technologies. Three archetypes prevail: vertically integrated chemical conglomerates, specialized dental material houses, and regional fabrication specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as laboratories consolidate procurement authority.
Among Japanese chemical conglomerates, Tosoh Corporation exemplifies upstream control from raw mineral through finished blank production. Specialized dental material houses include Ivoclar Vivadent, representing premium-tier positioning through proprietary shading systems. Chinese regional specialists such as Aidite Technology Co., LTD occupy positions serving domestic chairside milling workflows with formats optimized for local equipment specifications.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| Dentsply Sirona |
| 3M |
| Tosoh Corporation |
| Kuraray Noritake Dental |
| Pritidenta GmbH |
| Aidite Technology Co., LTD |
| GC America |
| Zirkonzahn |
| Others |
Pricing and Supply Chain Analysis
Yttrium oxide stabilizer costs cascade through powder formulations into three distinct pricing tiers downstream, with Chinese rare earth refining concentration amplifying margin volatility for European and North American laboratory suppliers.
Pricing Analysis
Input-cost pass-through from yttria stabilization chemistry drives pricing stratification across premium, standard, and economy tiers. ISO 13356 certification grade and volume scale differentiate price bands, with uncertified economy grades facing compression as dental service organizations consolidate procurement. Small independent laboratories exhibit highest price sensitivity, while hospital systems anchored to surgical-grade specifications tolerate premium positioning.
Supply Chain Analysis
Workforce availability constraints in Japanese and German precision ceramics manufacturing elevate labor costs for isostatic pressing operations. Supply concentrates in China, Japan, and Germany, with yttrium oxide, zirconium silicate, and high-purity binders as critical inputs. Single-source vulnerability in Chinese rare earth processing creates tariff exposure risk. Distribution runs through direct mill blank contracts with dental service organizations, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward multi-layer gradient zirconia specifications that command premium positioning in anterior restoration workflows.
For Market Incumbents: Deploy backward integration into yttria stabilization chemistry to secure input cost discipline against Chinese supply volatility. Add certified pressing capacity in Bavaria or Tokyo-Osaka corridors to defend margin position against Aidite Technology's domestic China cost structure. Prioritize ISO 13356 certification investment to maintain hospital system procurement eligibility as regulatory scrutiny intensifies. For New Entrants and Emerging Players: Launch via chairside disc formats targeting price-sensitive dental clinics in Mumbai and Delhi clusters, where PLI scheme incentives reduce import substitution barriers. Penetrate the pre-shaded segment fastest by optimizing pigmentation chemistry for Indian laboratory furnace specifications. Pursue CDSCO registration pathways to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where dental service organization procurement concentration eliminates standalone laboratory viability. Frame long-term viability around captive supply security for group practice networks. Target mid-scale pressing specialists with METI or FDA quality infrastructure already in place. Watch sintering energy cost trajectories as inflection indicator for regional manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Stabilization | Secures rare earth input supply against Chinese processing concentration for Tosoh Corporation and European suppliers. |
| Multi-Layer Gradient Zirconia Launch | Captures premium anterior restoration demand displacing feldspathic porcelain in German and Japanese laboratories. |
| CE Marking Pathway Acceleration | Reduces EU Medical Device Regulation compliance timelines for notified body Class IIa certification. |
| Dental Service Organization Partnership | Locks annual volume commitments with Texas and Florida group practices consolidating procurement authority. |
| India PLI Scheme Manufacturing Footprint | Positions cost-competitive pressing capacity for Mumbai and Delhi price-sensitive prosthetic clusters. |
Research Methodology
Multiple input streams — primary interviews with dental laboratory directors, CAD/CAM equipment procurement officers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR notified body registers, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Cross-referencing historical volume trajectories against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and form configuration, with CAGRs derived from sintering capacity expansion rates and chairside milling adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under yttria supply disruption or energy cost shock scenarios. Material deviation in dental insurance reimbursement codes for chairside CAD/CAM restorations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Fluoride Materials Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Composites Market