
 Global Dental Cements Market | 2026-2036
Global Dental Cements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Cements Market Foresight
Kit-based bundling of resin cements with etchants and primers is pivoting how dental clinics evaluate total procedure cost. GC Corporation leverages integrated adhesive systems to sustain loyalty among prosthodontic facilities. 3M anchors North American distribution through direct sales to large dental service organizations. Ivoclar Vivadent differentiates via specialized shade-matching protocols for aesthetic cementation.
Dental cements comprise biocompatible luting and bonding agents formulated from resin monomers, glass ionomer powders, or zinc oxide-eugenol bases, cured through acid-base reaction or light polymerization to achieve compressive strengths exceeding 100 MPa for permanent restoration fixation. Resin-modified glass ionomer formulations occupy the fastest-expanding product tier due to their dual fluoride release and simplified moisture tolerance. Crown cementation commands the largest application share, while orthodontic bracket bonding generates premium pricing through demand for rapid-set resin systems.
FDA 510(k) clearance pathways govern permanent cement introductions in the United States, while the EU Medical Device Regulation and CE marking framework mandate clinical performance documentation for market access across Europe. ISO 9917 standards establish setting time and solubility benchmarks that manufacturers must meet for international commercialization. Stakeholders should monitor evolving biocompatibility testing protocols and regional reimbursement shifts for adhesive procedures.
Market Dynamics
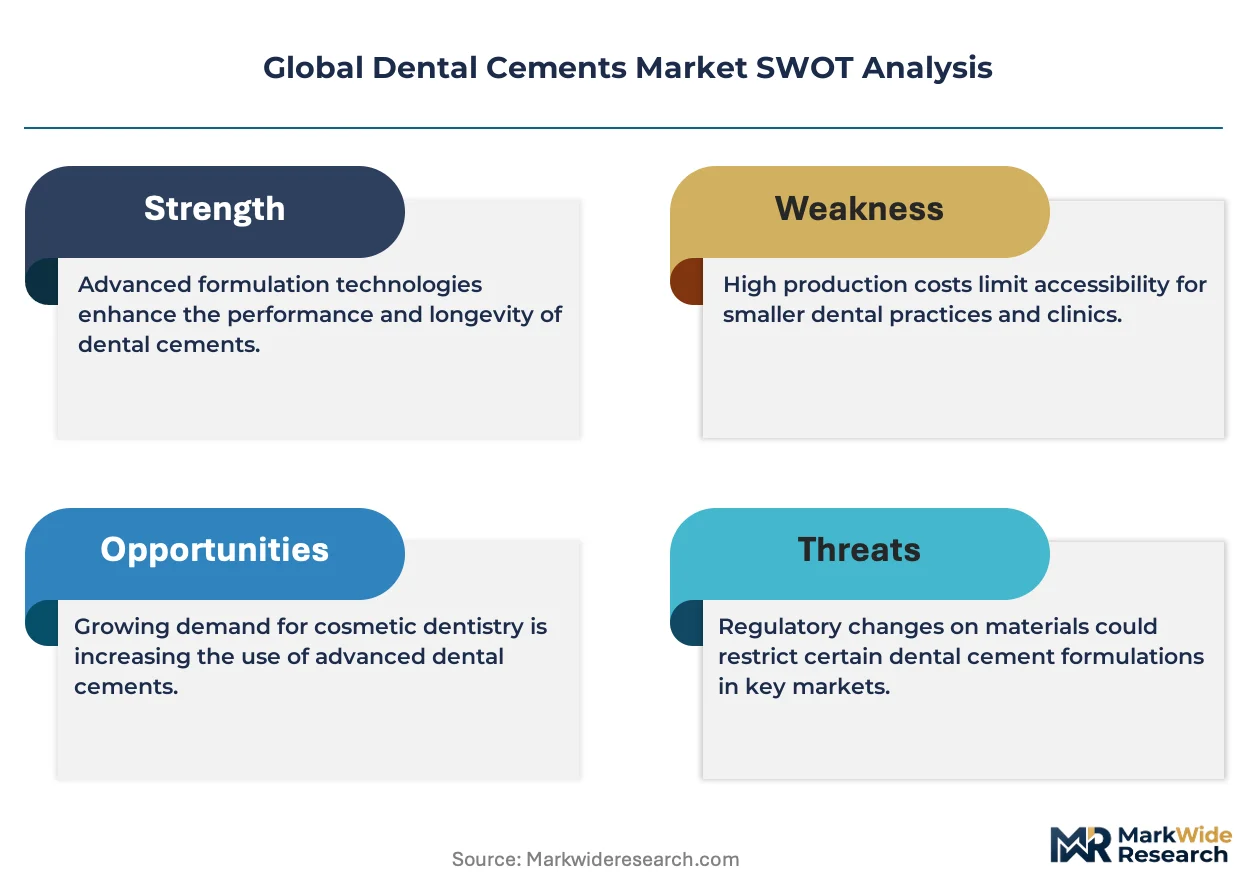
EU Medical Device Regulation biocompatibility documentation requirements are compressing time-to-market for permanent luting agents while forcing manufacturers to restructure clinical evidence portfolios.
Growth Catalysts
- Prosthodontic restoration volume:Aging populations in the United States, Germany, and Japan are driving crown cementation procedures in dental clinics.
- Resin-modified glass ionomer technology:Dual fluoride release and simplified moisture tolerance are accelerating adoption across community health centers.
- ISO 9917 standards harmonization:Unified setting time and solubility benchmarks are reducing regulatory friction for cross-border commercialization.
Market Restraints
- Zinc oxide-eugenol input volatility:Fluctuating eugenol oil prices from Southeast Asian clove plantations destabilize cost structures for temporary cement formulations.
- Biocompatibility testing concentration:FDA 510(k) clearance pathways and EU MDR clinical performance documentation requirements cluster specialized testing capacity in Switzerland and Germany.
- Resin monomer substitution pressure:Bioactive glass formulations threaten conventional resin cement positioning in pediatric dentistry applications.
Strategic Opportunities
- Brazil orthodontic expansion:ANVISA regulatory streamlining opens rapid-set resin system penetration in Latin America's largest dental consumables market.
- Digital workflow convergence:Chairside CAD/CAM milling is integrating with self-adhesive resin cements to enable same-day crown delivery protocols.
- Direct-to-clinic distribution:Dental service organizations in the United States are consolidating procurement through manufacturer bypass channels.
Industry Challenges
- Adhesive protocol standardization:Etch-and-rinse versus self-etch technique disputes complicate training curricula for dental school graduates.
- CE marking timeline compression:EU MDR notified body capacity constraints extend clinical evaluation report review cycles for novel cement formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Cements Market |
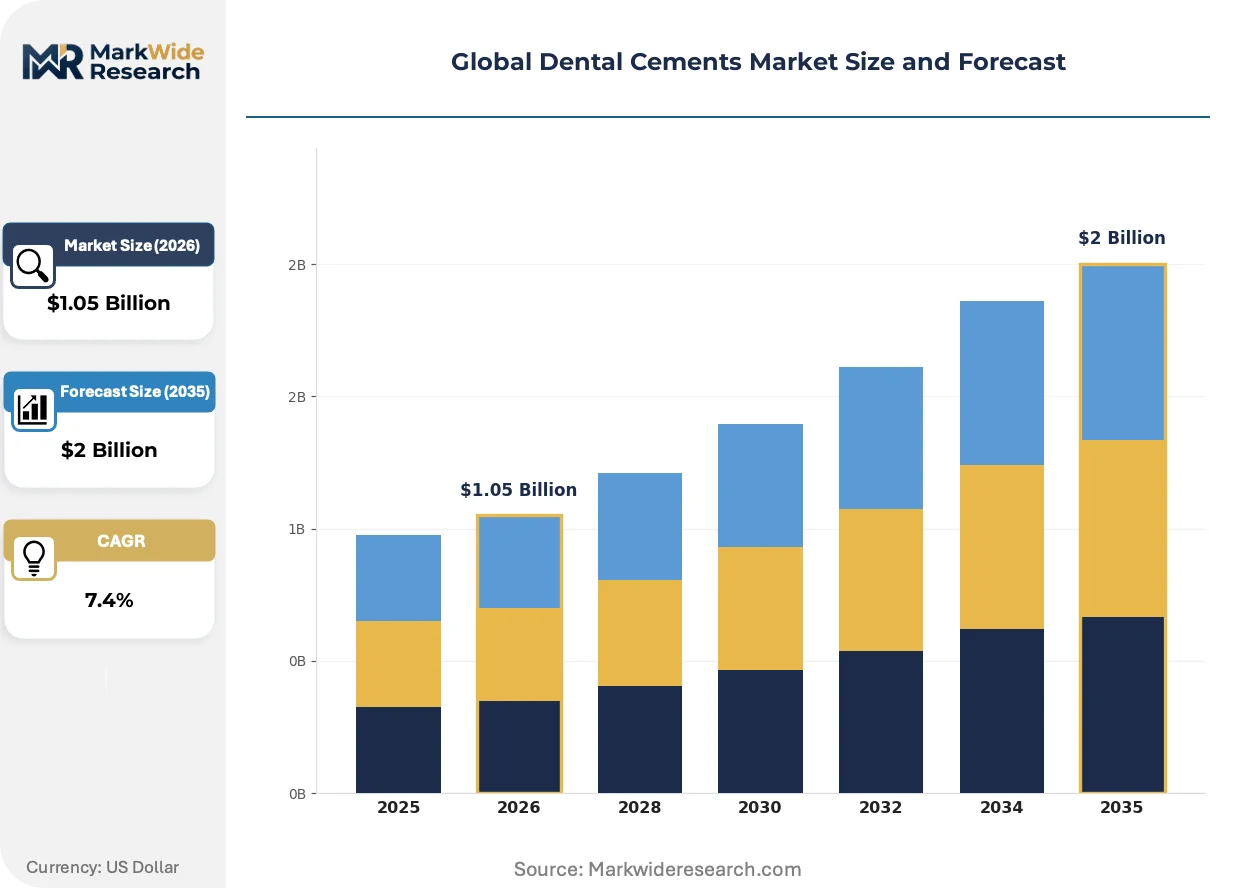
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin-Based, Glass Ionomer, Zinc Phosphate, Polycarboxylate, Resin-Modified Glass Ionomer Application: Crown Cementation, Orthodontic Bracket Bonding, Temporary Restoration, Base/Liner Material, Root Canal Sealing End User: Dental Clinics, Specialty Dental Centers, Dental Laboratories, Oral Surgery Centers, Prosthodontic Facilities Formulation: Powder-Liquid, Paste-Paste, Capsules, Syrups |
| Companies Covered | GC Corporation, KaVo Kerr, 3M, BISCO, Shofu Dental Corporation, Dentsply Sirona, Kerr Corporation, Kuraray Noritake, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Cements Market Shifts & Advancements
Digital dentistry workflows and adhesive chemistry advances are compressing chairside procedure times while elevating performance benchmarks for permanent restoration fixation.
Bioactive resin cements are integrating ion-releasing functionality into conventional polymer matrices. Prosthodontic facilities in Japan and Germany are adopting these formulations at accelerated rates. The technology is integrating remineralization capacity into standard cementation protocols, expanding the addressable case mix for high-caries-risk patients.
EU MDR clinical performance documentation mandates are tightening evidence requirements for permanent luting agents. Manufacturers must now submit prospective clinical data rather than predicate device equivalence. Orthodontic bonding applications face the steepest compliance burden, with notified bodies demanding extended follow-up periods for bracket adhesion failure rates.
Kit-based bundling of etchants, primers, and resin cements is displacing component purchasing in dental service organizations. Large group practices in the United States are consolidating vendor relationships around integrated adhesive systems. This procurement consolidation is most visible in multi-state dental chains seeking standardized inventory management across hundreds of operatories.
Global Dental Cements Market Segmentation
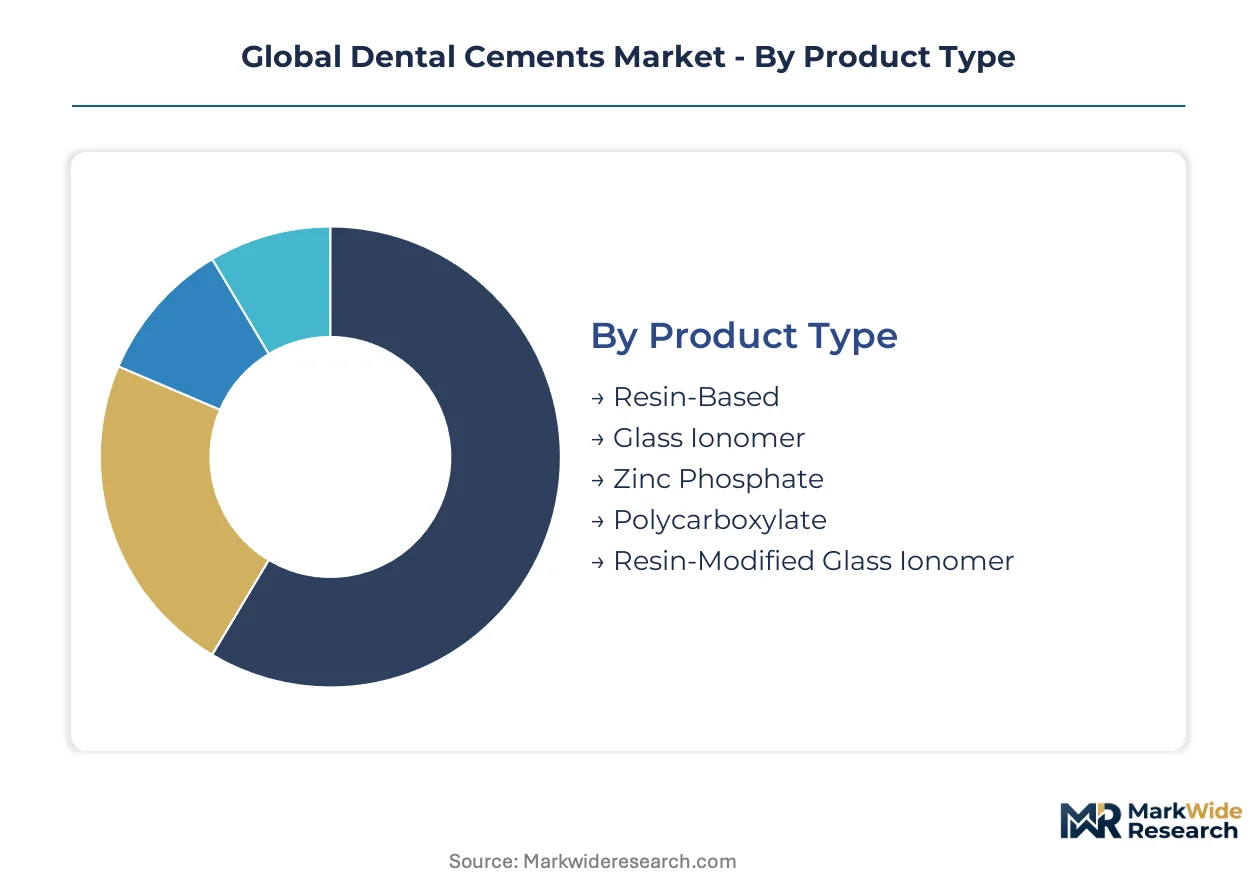
Segmentation in dental cements determines procurement patterns across dental service organizations and influences regulatory submission strategies. Product chemistry dictates FDA 510(k) versus EU MDR pathway requirements, while application type shapes reimbursement coding and clinical evidence thresholds.
Product Type:
FDA 510(k) clearance governs resin-based and resin-modified glass ionomer formulations as Class II devices, while glass ionomer and zinc phosphate cements navigate simpler predicate equivalence routes. EU MDR Annex VIII classification elevates permanent luting agents to Class IIa or IIb depending on duration of contact.
- Resin-Based:These formulations employ methacrylate monomers cured through light polymerization or dual-cure mechanisms, delivering compressive strengths exceeding 150 MPa for permanent crown fixation. Demand concentrates in prosthodontic facilities across the United States and Germany, driven by aesthetic demands for all-ceramic restorations and chairside CAD/CAM integration.
- Resin-Modified Glass Ionomer:Hybrid chemistry combines fluoride-releasing glass ionomer powder with hydrophilic resin monomers, offering simplified moisture tolerance compared to conventional resin systems. Community health centers in Japan and expanding dental clinic networks in Brazil are adopting these formulations for their dual therapeutic and adhesive functionality.
- Glass Ionomer:Acid-base reaction cements releasing sustained fluoride ions for caries prevention around restoration margins.
- Zinc Phosphate:Traditional luting agent with long clinical history, favored for metal-based restorations where aesthetic demands are secondary.
- Polycarboxylate:Polyacrylic acid-based formulation offering biocompatibility advantages for sensitive patient populations.
Leading the category by volume: Resin-Based. Growing fastest: Resin-Modified Glass Ionomer.
Application:
Cost tier stratification separates premium-priced orthodontic bonding from commodity temporary restoration applications, with reimbursement differentials of 3-5x between segments in US dental markets.
- Crown Cementation:Permanent fixation of crowns, bridges, and inlays represents the largest volume application, requiring cements with film thickness below 25 micrometers and radiopacity for postoperative evaluation. Aging populations in Japan and Germany are driving procedure volumes through prosthodontic facilities and multi-chair dental clinics.
- Orthodontic Bracket Bonding:Rapid-set resin systems with controlled working time enable efficient bracket placement across high-volume orthodontic practices. Specialty dental centers in the United States command premium pricing for these procedures, with adhesive failure rate documentation now mandated under EU MDR clinical performance requirements.
- Temporary Restoration:Short-term cementation for provisional crowns and bridges, prioritizing ease of removal over bond strength.
- Base/Liner Material:Therapeutic applications requiring pulpal protection and thermal insulation beneath permanent restorations.
- Root Canal Sealing:Endodontic obturation materials demanding dimensional stability and tissue compatibility within root canal systems.
Volume concentration: Crown Cementation. Margin expansion: Orthodontic Bracket Bonding.
End User:
Customer type determines packaging preferences, with dental service organizations demanding bulk configurations and single-practice clinics favoring unit-dose capsules for inventory control.
- Dental Clinics:General practice settings performing routine crown cementation and restorative procedures represent the foundational demand base. These facilities in the United States are consolidating procurement through direct manufacturer relationships, bypassing traditional dental distribution.
- Specialty Dental Centers:Orthodontic and endodontic practices generate premium pricing through specialized adhesive protocols and rapid-set formulations. German specialty centers are pioneering bioactive cement adoption for high-caries-risk patient management.
- Dental Laboratories:Indirect restoration fabricators influencing cement selection through technical recommendations to prescribing dentists.
- Oral Surgery Centers:Implant-supported prosthesis cementation requiring specialized protocols for retrieval considerations.
- Prosthodontic Facilities:Advanced restorative practices driving aesthetic cementation technology adoption and shade-matching integration.
Procurement scale leadership: Dental Clinics. Technology adoption pace: Prosthodontic Facilities.
Formulation:
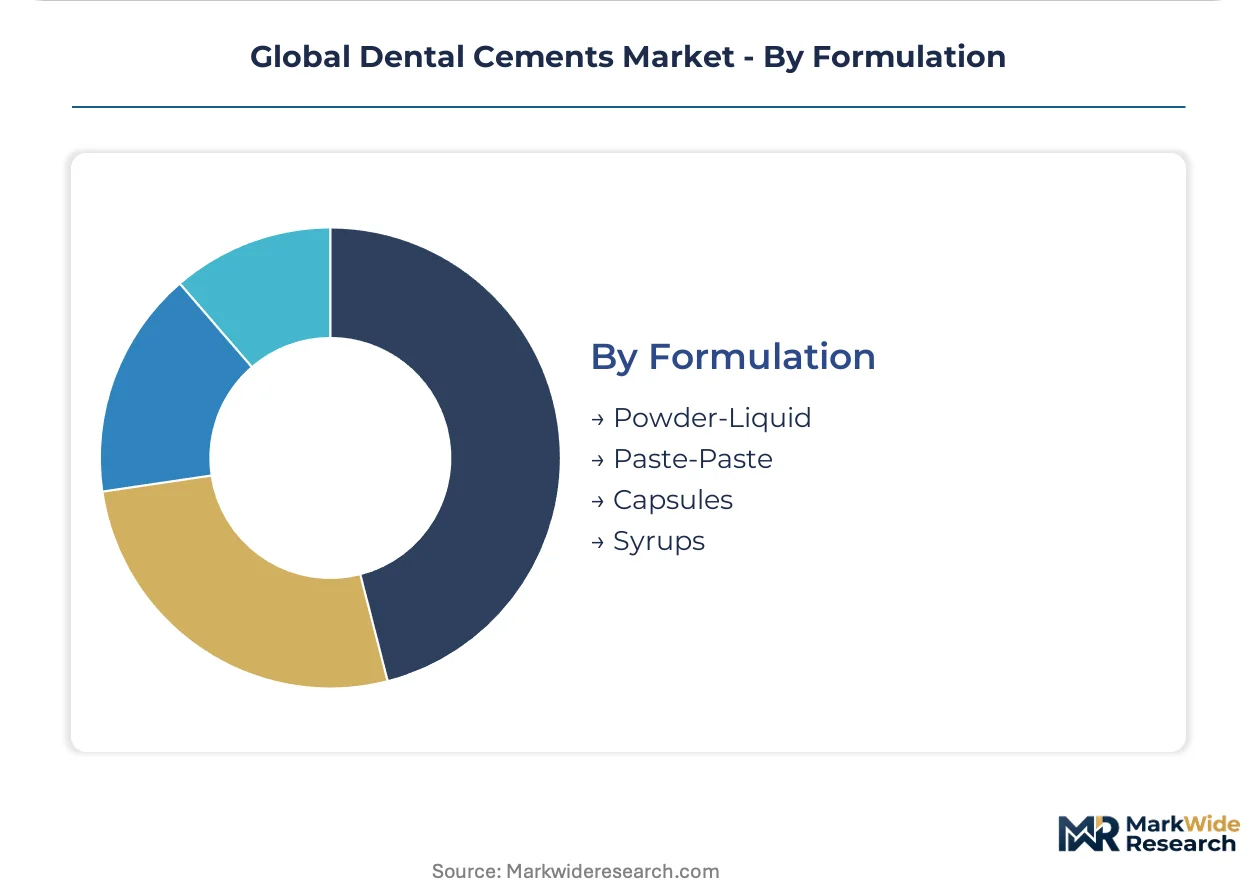
Supply concentration in powder-liquid manufacturing reflects historical production infrastructure, while paste-paste and capsule formats are displacing traditional configurations in high-efficiency practice settings.
- Powder-Liquid:Conventional presentation requiring manual mixing on glass slabs or paper pads, dominant in zinc phosphate and glass ionomer categories. Japanese and German manufacturers maintain production scale advantages in these established formats.
- Paste-Paste:Pre-dispensed base and catalyst pastes in dual-barrel syringes or automix cartridges, eliminating proportioning errors and reducing working time variability. US dental service organizations are standardizing on these configurations for multi-state practice consistency.
- Capsules:Mechanical mixing devices providing standardized powder-liquid ratios and controlled setting reactions.
- Syrups:Liquid concentrate formulations for specific therapeutic applications requiring modified viscosity characteristics.
Installed base dominance: Powder-Liquid. Share gain trajectory: Paste-Paste.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Japan and Germany contrasts with consumption gravity in the United States, where aging demographics and consolidated dental service organizations drive procurement volumes. Cross-border regulatory friction persists as FDA 510(k) pathways diverge from EU MDR clinical performance mandates.
United States
Dental service organizations in Texas and Florida are consolidating procurement through direct manufacturer channels, bypassing traditional distribution. FDA 510(k) clearance pathways govern permanent cement introductions as Class II devices. Large multi-state chains in the Southeast standardize on paste-paste formulations across hundreds of operatories.
Germany
Prosthodontic facilities in Bavaria and Baden-Württemberg anchor European demand for aesthetic cementation systems. EU MDR Annex VIII classification elevates permanent luting agents to Class IIa or IIb, mandating prospective clinical data rather than predicate equivalence. Notified body capacity constraints in Berlin and Munich extend evaluation timelines for novel formulations.
Japan
Community health centers in Tokyo and Osaka are accelerating adoption of resin-modified glass ionomer systems for dual therapeutic functionality. METI guidelines influence biocompatibility documentation standards for domestic manufacturers. Production clusters in the Kansai region maintain powder-liquid format advantages through historical infrastructure scale.
Brazil
Orthodontic practices in São Paulo and Rio de Janeiro generate demand for rapid-set resin systems as ANVISA streamlines regulatory pathways. Expanding dental clinic networks in Minas Gerais are adopting resin-modified glass ionomer formulations for moisture-tolerant protocols. Latin America's largest dental consumables market is consolidating around kit-based bundled procurement.
Switzerland
Specialized testing capacity for biocompatibility documentation concentrates in Basel and Zurich, serving EU MDR and FDA submission requirements. Swissmedic oversight aligns with EU regulatory frameworks while maintaining distinct notification procedures. Research clusters in the Lake Geneva region pioneer bioactive cement formulations with ion-releasing functionality.
Global Dental Cements Market Competitive Landscape
The competitive structure tilts toward integrated adhesive system providers with direct distribution to large dental service organizations. Market participants fragment across three tiers: multinational conglomerates with broad dental portfolios, specialized cement manufacturers with regional manufacturing footprints, and niche bioactive formulation specialists. Consolidation pressures favor players with vertical control over resin monomer supply and notified body relationships for EU MDR compliance. Strategic moves center on kit-based bundling of etchants, primers, and cements to lock in multi-year procurement contracts.
Within the multinational tier, 3M, GC Corporation, and Ivoclar Vivadent exemplify divergent positioning archetypes. 3M anchors North American presence through direct sales infrastructure targeting dental service organizations. GC Corporation leverages integrated adhesive systems to sustain loyalty among prosthodontic facilities. Ivoclar Vivadent occupies a specialized position through shade-matching protocol differentiation for aesthetic cementation. Japanese and European manufacturers maintain production scale advantages in powder-liquid formats while US-based players standardize paste-paste configurations for efficiency-focused clinic chains.
| Leading Market Players |
|---|
| GC Corporation |
| KaVo Kerr |
| 3M |
| BISCO |
| Shofu Dental Corporation |
| Dentsply Sirona |
| Kerr Corporation |
| Kuraray Noritake |
| Ivoclar Vivadent |
| Others |
Supply & Pricing Matrix
Dental service organization consolidation across the United States is compressing procurement negotiations toward contract-based long-term offtake agreements with volume-scaled discounts. This buyer concentration shifts pricing power toward multi-state clinic chains capable of standardizing formulations across hundreds of operatories.
Pricing Analysis
Margin tightening in resin-modified glass ionomer tiers reflects eugenol oil substitution costs and EU MDR compliance investments. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 9917 certification grade and after-sales technical support bundling. Community health centers exhibit highest price sensitivity due to constrained capital budgets, while prosthodontic facilities absorb premium positioning for aesthetic shade-matching protocols.
Supply Chain Analysis
Resin monomer supply rests on Japanese and German specialty chemical producers with captive production of methacrylate precursors. Powder-liquid manufacturing concentrates in the Kansai region of Japan and Bavaria, while paste-paste filling operations cluster in Texas and Florida for US market proximity. Single-source vulnerability in Southeast Asian clove plantations for eugenol oil creates input cost volatility. Distribution runs through direct manufacturer channels to large dental service organizations, bypassing traditional dental distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global dental cements market functions as a cost-of-compliance arena where EU MDR clinical performance documentation erects substantial barriers to entry for undercapitalized challengers. This regulatory moat protects incumbent positions while forcing sustained investment in notified body relationships.
For Market Incumbents: Lock in multi-year procurement contracts with dental service organizations through kit-based bundling of etchants, primers, and resin cements. Deepen backward integration into resin monomer production to offset raw material volatility from Japanese and German chemical suppliers. Prioritize notified body capacity reservations in Berlin and Munich to preempt EU MDR evaluation timeline extensions.
For New Entrants and Emerging Players: Bioactive ion-releasing formulations offer a technology-first wedge into pediatric dentistry applications where conventional resin cements face substitution pressure. Brazil's ANVISA-streamlined orthodontic market presents the most penetrable geography for rapid-set resin system introduction. Pursue direct-to-clinic distribution partnerships with expanding Minas Gerais dental networks to bypass established distributor relationships.
For Investors and Strategic Acquirers: The window for entry favors specialized cement manufacturers with existing ISO 9917 certification infrastructure and regional manufacturing footprints in Japan or Germany. Acquisition targets should demonstrate established notified body relationships for EU MDR Annex VIII compliance. Monitor CE marking timeline compression as the critical inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex VIII compliance enables Class IIa/IIb market access across German and Bavarian prosthodontic facilities. |
| Backward Integration | Captive resin monomer production insulates margin structures from Japanese chemical supplier price volatility. |
| Direct-to-Clinic Distribution | Bypassing traditional dental distribution captures procurement consolidation in Texas and Florida multi-state chains. |
| Kit-Based Bundling | Integrated adhesive systems lock in multi-year contracts with dental service organizations seeking inventory standardization. |
| Bioactive Formulation Development | Ion-releasing functionality expands addressable case mix for high-caries-risk patients in Japanese community health centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with prosthodontic facility directors, dental service organization procurement managers, biomedical engineers, and GPO contracts managers validated demand-side assumptions. FDA 510(k) databases, EU MDR notified body submissions, ISO certification registries, and import-export records provided secondary triangulation. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis reconciled across the analysis window.
Data-stream reconciliation combined shipment volumes, regulatory approval timelines, and end-user procurement patterns. Segmentation dimensions modeled include product chemistry tier, application type, end-user facility category, and regional regulatory cluster. CAGRs derived from procedure volume growth trajectories and pricing trend extrapolation. Forecast inputs incorporated aging demographic projections for the United States, Germany, and Japan alongside ANVISA regulatory streamlining effects in Brazil.
Several conditions sit outside the modeled scope, including unforeseen biocompatibility testing protocol revisions, clove plantation supply disruptions, and dental service organization bankruptcy events. Forecasts reflect documented assumptions about regulatory stability and input cost trajectories. A small set of named triggers warrants ongoing watch: EU MDR notified body capacity constraints, resin monomer substitution breakthroughs, and Brazilian orthodontic market regulatory reversals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Alloys Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Plaster Market
Dental Materials
Teeth Whitening Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Dental Putty Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market