
 Deep Space Robotics Market | 2026-2036
Deep Space Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Space Robotics Market Analysis
Government procurement channels for deep space missions is narrowing as agencies consolidate vendor lists around flight-proven suppliers. Northrop Grumman Corporation leverages its heritage in satellite servicing to sustain long-term NASA contracts. Honeybee Robotics specializes in planetary sampling tools and anchors niche demand for asteroid retrieval mechanisms. Astrobotic Technology competes aggressively on lunar lander-robot integration, positioning itself for CLPS task orders.
Deep space robotics encompasses electromechanical systems engineered to operate in cislunar and interplanetary environments, typically rated for temperature swings exceeding 300°C and radiation doses above 100 krad. These platforms execute sample acquisition, infrastructure assembly, and satellite servicing where human presence remains impractical or impossible. Autonomous rovers currently lead technology investment as Mars mobility demonstrations validate long-duration navigation algorithms without real-time Earth control. Satellite repair applications are expanding fastest among deployment modes, driven by orbital servicing demonstrations that promise to extend asset life and reduce replacement launch costs. Research institutions represent a concentrated margin pool within end users, as university-led instrument development commands premium pricing for bespoke manipulation payloads.
NASA's technical standards and the FAA's commercial space launch licensing framework jointly shape product qualification timelines and market access for U.S. vendors. ISO 17757 space robotics safety protocols and ITU orbital coordination rules further constrain system design, particularly for multi-national missions requiring spectrum allocation and debris mitigation compliance. Stakeholders must monitor how export control recalibrations under EAR and ITAR affect component sourcing for international joint ventures.
Market Dynamics
NASA's Artemis program and ESA's lunar gateway initiatives are consolidating procurement around flight-proven vendors, compressing qualification timelines for new entrants while elevating heritage requirements for radiation-hardened systems.
Growth Catalysts
- Artemis Task Orders:NASA's Commercial Lunar Payload Services contracts create recurring revenue streams for autonomous lander-robot integrators. Federal procurement channels favor vendors with demonstrated cislunar flight heritage.
- Radiation-Hardened Electronics:Advances in silicon-on-insulator architectures extend operational lifespans for deep space platforms. Semiconductor foundries in the United States and Europe are expanding qualified component lines.
- ISO 17757 Adoption:International safety protocols for space robotics standardize design requirements across multinational missions. Standardization reduces requalification costs for vendors serving multiple agencies.
Market Restraints
- Flight Heritage Requirements:NASA and ESA procurement specifications mandate prior spaceflight demonstration. New entrants face multi-year qualification barriers without access to rideshare or technology demonstration missions.
- Rare Earth Magnet Supply:Permanent magnet motors for precision actuation depend on neodymium-dysprosium supply chains concentrated in China. Export licensing creates input volatility for actuator manufacturers.
- Thermal Protection Costs:Multi-layer insulation and phase-change thermal management systems constitute 15-25% of platform mass budgets. Material costs for aerogel and polyimide films constrain unit economics.
Strategic Opportunities
- Asteroid Retrieval Missions:NASA's redirected asteroid capture objectives create demand for precision proximity operations and sample containment systems. Honeybee Robotics and similar specialists anchor instrument development.
- In-Space Servicing:Orbital refueling and satellite life extension applications expand addressable market beyond planetary surfaces. Northrop Grumman's Mission Extension Vehicle validates commercial viability.
- University-Led Payloads:Research institutions command premium pricing for bespoke manipulation instruments. Principal investigator budgets from NSF and national science agencies sustain specialized engineering margins.
Industry Challenges
- Radiation Effects Engineering:Total ionizing dose and single-event upset mitigation require specialized simulation capabilities. Talent pools for spacecraft electronics reliability remain shallow relative to commercial aerospace.
- ITAR Compliance Complexity:Export control classifications for space-qualified components create legal friction for international joint ventures. Vendor legal departments must maintain parallel technical and regulatory expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Space Robotics Market |
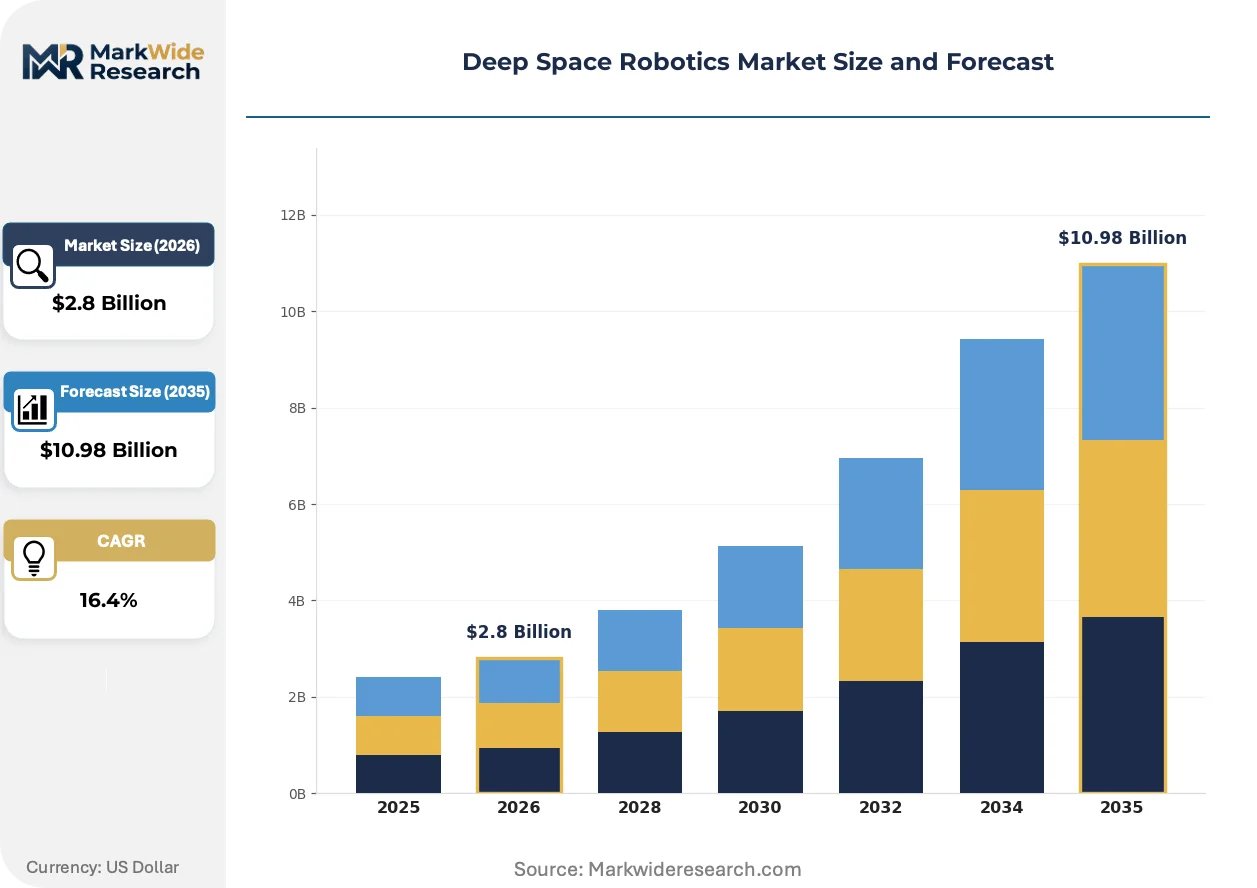
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Arms, Autonomous Rovers, Drones, Manipulators Application: Exploration Missions, Planetary Observation, Satellite Repair, Research Activities End User: Aerospace Agencies, Private Space Companies, Research Institutions, Defense Organizations Deployment: On-Satellite, Ground Control, Spacecraft Integration, Orbital Platforms |
| Companies Covered | Northrop Grumman Corporation, Honeybee Robotics, Astrobotic Technology, Inc., SpaceX, Lockheed Martin Corporation, Redwire Corporation, Motiv Space Systems Inc., Lunar Resources, Inc., Space Applications Services NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Space Robotics Market Emerging Trajectories
Autonomous navigation architectures and modular payload interfaces are compressing development cycles while expanding mission flexibility for multi-target exploration campaigns.
Reinforcement learning-based path planning is rendering obsolete conventional waypoint-command sequences for Martian and lunar rover operations. JPL's Perseverance autonomy demonstrations validate real-time terrain assessment without Earth-in-the-loop control. Mission planners at NASA Ames and ESA ESTEC are mandating onboard decision-making capabilities for future flagship missions.
ITU orbital coordination rules and debris mitigation guidelines are tightening design constraints for multi-spacecraft formations. Satellite servicing vehicles must now demonstrate post-mission disposal trajectories and collision avoidance maneuverability. European operators under ESA oversight are pioneering active debris removal demonstrations that inform forthcoming binding standards.
Agency procurement officers are consolidating instrument orders around platform-agnostic payload specifications. Standardized mechanical and electrical interfaces reduce non-recurring engineering for university science teams. The shift concentrates volume with integrators offering rapid payload accommodation, particularly visible in NASA's CLPS vendor selection criteria.
Deep Space Robotics Market Segmentation
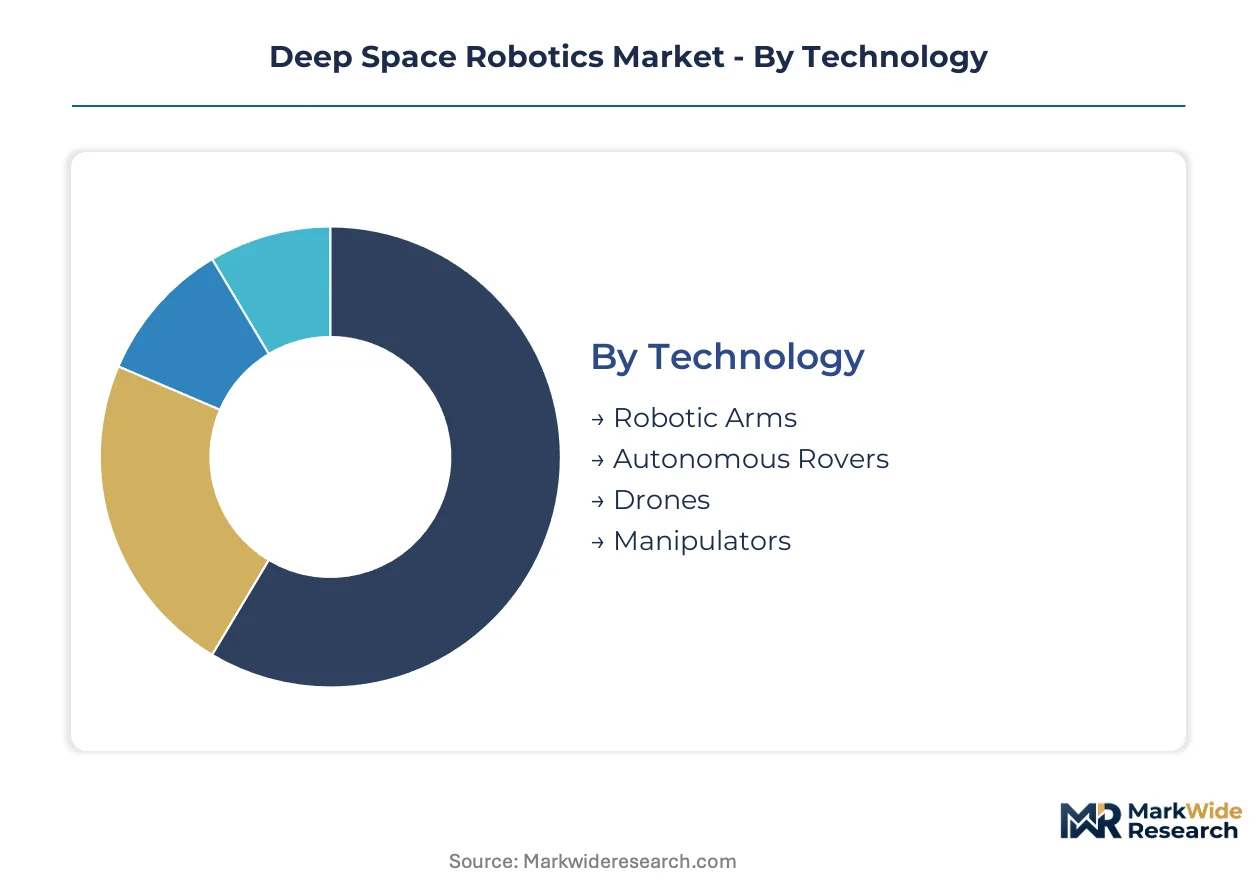
Deep space robotics segmentation reveals how mission requirements dictate technology selection and procurement channels. Different deployment environments impose distinct thermal, radiation, and autonomy constraints that reshape vendor capabilities and pricing structures across each category.
Technology:
Use-case spectrum spans precision manipulation to long-range mobility, with each technology addressing specific mission phases from sample acquisition to infrastructure assembly.
- Autonomous Rovers:Wheeled and legged mobility platforms rated for temperature swings exceeding 300°C and radiation doses above 100 krad. NASA's Artemis program and ESA lunar gateway initiatives concentrate procurement around flight-proven suppliers with demonstrated cislunar navigation algorithms. Established volume favors autonomous rovers; emerging adoption favors satellite repair applications.
- Robotic Arms:Multi-degree-of-freedom manipulators engineered for precision sample handling and infrastructure assembly in zero-gravity environments. Research institutions command premium pricing for bespoke manipulation payloads developed under principal investigator budgets from NSF and national science agencies.
- Drones:Aerial mobility systems for low-gravity atmospheric exploration, particularly Martian helicopter derivatives. JPL's Ingenuity demonstrations validated controlled flight in thin-atmosphere conditions.
- Manipulators:Specialized end-effector systems for asteroid retrieval and proximity operations. Honeybee Robotics anchors instrument development for precision sample containment.
Established volume favors autonomous rovers; emerging adoption favors manipulators.
Application:
Cost tier stratification separates flagship science missions from commercial servicing contracts and technology demonstration flights.
- Satellite Repair:Orbital servicing vehicles executing refueling, life extension, and component replacement. Northrop Grumman's Mission Extension Vehicle validates commercial viability for geostationary asset preservation. Established volume favors exploration missions; emerging adoption favors satellite repair.
- Exploration Missions:Surface and subsurface investigation campaigns targeting lunar polar volatiles and Martian geology. NASA's Commercial Lunar Payload Services contracts create recurring revenue streams for autonomous lander-robot integrators.
- Planetary Observation:Long-duration sensing platforms for atmospheric and geological monitoring. ESA ESTEC mission planners mandate onboard decision-making capabilities for future flagship missions.
- Research Activities:University-led instrument development for technology validation and science return. Standardized mechanical and electrical interfaces reduce non-recurring engineering for academic science teams.
Established volume favors exploration missions; emerging adoption favors satellite repair.
End User:
Customer type determines procurement velocity, with federal agencies imposing multi-year qualification barriers that commercial operators circumvent through rideshare partnerships.
- Aerospace Agencies:NASA and ESA procurement specifications mandate prior spaceflight demonstration, compressing vendor lists around heritage suppliers. Federal spending anchors on Artemis program and Space Force investments in deep space platforms.
- Research Institutions:University-led payload development commands premium pricing for bespoke manipulation instruments. NSF and national science agency budgets sustain specialized engineering margins outside commercial procurement channels.
- Private Space Companies:Astrobotic Technology and similar firms compete aggressively on lunar lander-robot integration for CLPS task orders.
- Defense Organizations:Space Force investments in deep space platforms drive demand for radiation-hardened systems with operational security constraints.
Established volume favors aerospace agencies; emerging adoption favors private space companies.
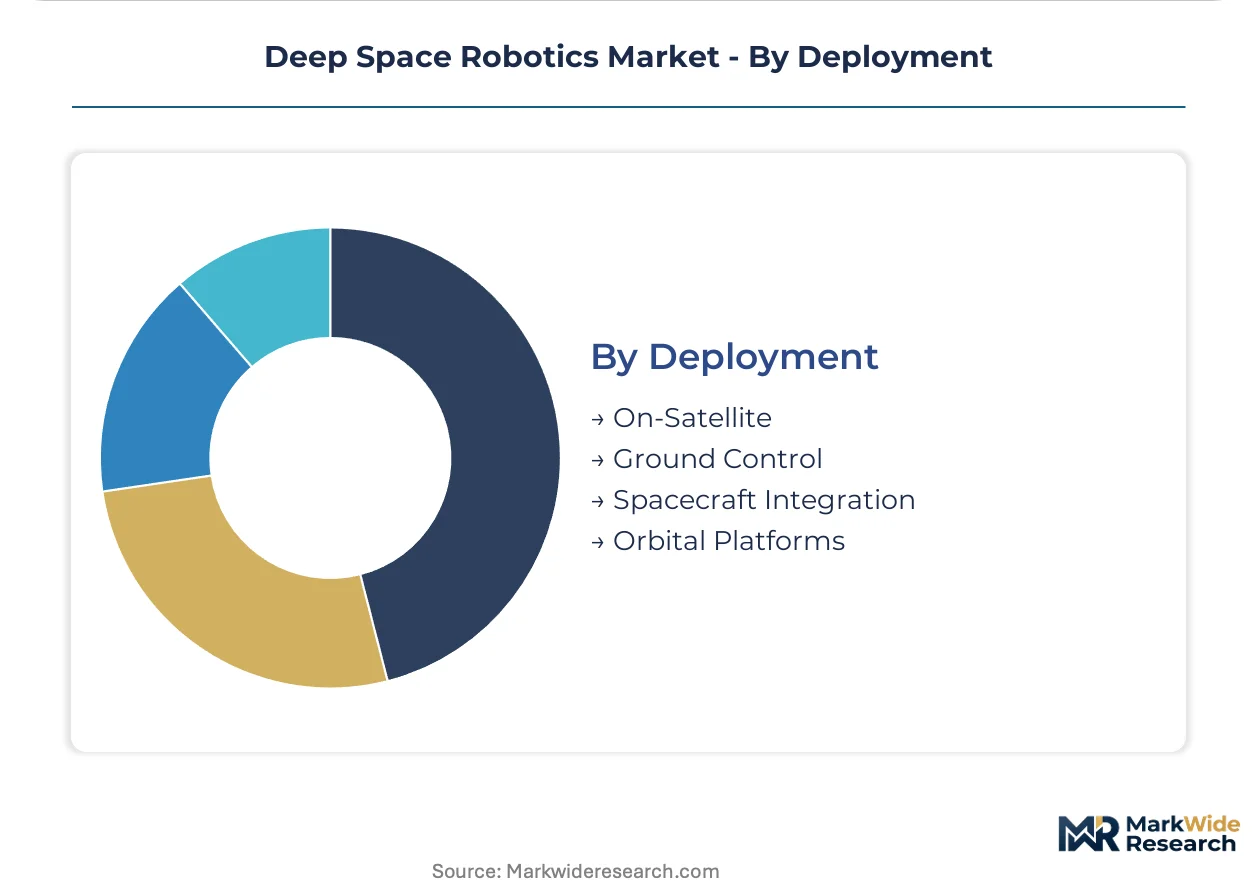
Deployment:
Supply concentration varies by operational domain, with orbital platforms requiring ITU coordination and debris mitigation compliance that ground control systems avoid.
- Orbital Platforms:Free-flying servicing vehicles and observation satellites requiring post-mission disposal trajectories and collision avoidance maneuverability. ESA oversight pioneers active debris removal demonstrations.
- Spacecraft Integration:Robot systems permanently installed on crewed and uncrewed vehicles for mission-critical functions. ISO 17757 safety protocols standardize design requirements across multinational missions.
- On-Satellite:Embedded manipulation and sensing systems for autonomous satellite servicing. ITU orbital coordination rules tighten design constraints for multi-spacecraft formations.
- Ground Control:Terrestrial teleoperation centers for near-real-time command of deep space assets. FAA commercial space launch licensing framework shapes product qualification timelines for U.S. vendors.
Established volume favors spacecraft integration; emerging adoption favors orbital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European vendors absorb qualification cost premiums. NASA's Artemis procurement channels lock in heritage suppliers. ESA's lunar gateway initiatives compress margins for new entrants facing multi-year flight demonstration barriers.
United States
NASA's Commercial Lunar Payload Services contracts and Space Force deep space platform investments anchor federal procurement volume. FAA commercial space launch licensing and NASA technical standards jointly shape vendor qualification timelines. Houston and Pasadena clusters concentrate JPL rover autonomy development and Johnson Space Center mission control operations.
Germany
ESA ESTEC mission planning and DLR robotics research programs sustain institutional demand for planetary manipulation systems. Germany's national space strategy prioritizes in-orbit servicing and debris removal demonstrations. Munich and Bremen industrial corridors host satellite servicing vehicle development and precision actuator manufacturing.
France
CNES lunar exploration commitments and Thales Alenia Space heritage anchor institutional procurement for orbital robotics. France's national space program emphasizes autonomous navigation for future flagship missions. Toulouse and Paris-Saclay clusters concentrate space-qualified electronics development and mission systems engineering.
Japan
JAXA's Martian moon exploration and asteroid sample return missions sustain demand for precision proximity operation systems. METI space industry promotion policies and national technology roadmaps guide radiation-hardened component development. Tokyo and Tsukuba clusters concentrate robotics research institutes and semiconductor foundry partnerships.
United Kingdom
UK Space Agency lunar robotics funding and Satellite Applications Catapult programs support commercial servicing vehicle development. British National Space Centre standards alignment with ESA procurement specifications reduces requalification friction. Harwell and Glasgow clusters concentrate small satellite servicing startups and space manufacturing supply chains.
Deep Space Robotics Market Vendor Landscape
Defense-heritage conglomerates and specialized robotics boutiques split the market into distinct capability tiers. Vendor consolidation around flight-proven suppliers compresses entry pathways for unproven entrants. Two strategic archetypes dominate: diversified aerospace primes leveraging satellite servicing heritage, and focused instrument specialists commanding premium pricing for bespoke manipulation payloads. Competitive moves center on CLPS task order capture and radiation-hardened electronics qualification acceleration.
Within the heritage prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation occupy positions sustained by long-term NASA contract relationships and satellite servicing flight demonstrations. Among specialized boutiques, Honeybee Robotics exemplifies the precision instrument archetype, anchoring niche demand for asteroid retrieval and planetary sampling mechanisms. Astrobotic Technology, Inc. represents the aggressive lunar lander-robot integrator model, positioning for recurring Commercial Lunar Payload Services revenue streams against qualification-intensive procurement barriers.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Honeybee Robotics |
| Astrobotic Technology, Inc. |
| SpaceX |
| Lockheed Martin Corporation |
| Redwire Corporation |
| Motiv Space Systems Inc. |
| Lunar Resources, Inc. |
| Space Applications Services NV/SA |
| Others |
Supply Flow & Price Mechanics
Undercapacity in radiation-hardened semiconductor foundries across the United States and Europe is compressing supplier margins while elevating pricing power for qualified vendors serving NASA and ESA procurement channels. This utilization squeeze forces buyers into longer-term offtake commitments and accelerates qualification cost recovery through premium configured-to-order pricing.
Pricing Analysis
The customization-premium spread between standard catalog components and mission-configured systems exceeds three-to-one for deep space robotics platforms. Pricing stratifies across flight-proven heritage tiers, with NASA Technical Standard certification and prior cislunar demonstration commanding substantial premiums over unqualified alternatives. Cost compression in commercial satellite servicing segments is intensifying because rideshare launch economics are displacing dedicated mission pricing. Research institutions exhibit lowest price sensitivity due to NSF principal investigator budgets, while private space companies face acute pressure from CLPS fixed-price contract structures.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for permanent magnet motors and precision actuator components. Neodymium-dysprosium supply concentrates in China, with secondary sourcing from Japan and limited domestic processing in the United States. Multi-layer insulation materials draw from specialized aerogel production in Germany and polyimide film manufacturing in the United States and Japan. Single-source vulnerability in radiation-hardened electronics creates qualification bottlenecks for new vendor onboarding. Distribution runs through agency-certified prime contractors with direct NASA and ESA contracting authority, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where mission operations support, autonomy software licensing, and extended payload integration services are expanding faster than hardware unit sales. Recurring revenue from flight software updates and operational assistance contracts is displacing one-time platform transactions as the dominant value capture mechanism.
For Market Incumbents: Pre-empt emerging CLPS integrators by accelerating radiation-hardened electronics qualification timelines and securing exclusive payload interface standard-setting roles. Lockheed Martin and Northrop Grumman heritage positions are vulnerable to agile lunar lander-robot specialists unless incumbents compress non-recurring engineering cycles through modular platform architectures. Channel control over university-led instrument development programs represents the critical defensive lever for sustaining premium pricing.
For New Entrants and Emerging Players: Establish a beachhead in satellite servicing autonomy software where flight heritage requirements remain less stringent than planetary surface robotics. The orbital platforms segment offers the most penetrable entry vector because ITU coordination rules and debris mitigation compliance are standardizing faster than NASA procurement specifications. A go-to-market angle anchored on rapid payload accommodation for rideshare missions circumvents multi-year qualification barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radiation-hardened semiconductor foundry expansion and thermal protection system manufacturing. Long-term viability over the coming decade hinges on securing positions in upstream component qualification rather than downstream platform integration. Acquisition targets should display captive radiation-hardening capabilities or exclusive university research partnerships. The signal to monitor is NASA CLPS task order velocity as an indicator of procurement channel openness to non-heritage suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Electronics Qualification Acceleration | Reduces multi-year NASA procurement barriers for semiconductor vendors seeking flight heritage. |
| Modular Payload Interface Standardization | Enables rapid instrument accommodation for university science teams under CLPS contracts. |
| Autonomy Software Licensing Expansion | Captures recurring revenue from mission operations support beyond hardware unit sales. |
| In-Space Servicing Vehicle Development | Validates commercial viability through orbital refueling and satellite life extension demonstrations. |
| University Research Partnership Deepening | Secures premium pricing access to NSF-funded bespoke manipulation instrument development. |
Methodological Framework
A spread of perspectives from NASA procurement officers, ESA mission planners, radiation-hardened electronics foundry managers, university principal investigators, and commercial lunar payload integrators converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against NASA Technical Standards documentation, FAA commercial space launch licensing records, ISO 17757 space robotics safety protocol filings, and ITU orbital coordination databases. Bottom-up segment sizing across technology, application, end user, and deployment dimensions was triangulated against top-down agency budget allocation analysis.
Demand-supply balance dynamics across the analysis window were modeled through segmentation of procurement velocity by customer type, with federal agency qualification timelines treated as supply-constraining factors. The analytical framework incorporated technology maturity curves, flight heritage accumulation rates, and radiation-hardening certification bottlenecks as industry-specific forecast inputs. CAGRs were derived from trajectory fitting to historical contract award patterns and projected Artemis program spending profiles.
Sensitivities concentrate around NASA budget reallocation, ESA lunar gateway timeline adjustments, and export control recalibrations under EAR and ITAR regimes. Forecasts reflect assumptions regarding continued federal prioritization of cislunar presence and sustained semiconductor foundry capacity expansion in qualifying geographies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Lander and Rover Market
Space
Germany Space Electronics Market
Space
Europe Space Logistics Market
Space
Space-Based C4ISR Market
Space
Space Robots Market
Space
Space Debris Monitoring and Removal Market
Space
Asia-Pacific Space Electronics Market
Space
Near Space Robotics Market
Space
Space Mobile Service Market
Space
France Space Electronics Market
Space
Space Tourism Market
Space
Africa Space Electronics Market
Space
Spacecraft Market
Space
Space As a Service Market
Space
Suborbital Space Tourism Market
Space
Spain Space Electronics Market