
 Spacecraft Market | 2026-2036
Spacecraft Market Size, Share, and Industry Trends Forecast 2026-2036
Spacecraft Market Analysis
Modular satellite bus architectures is hardening as the dominant procurement model, letting buyers mix payload packages with standardized platforms rather than purchasing fully integrated custom spacecraft. SpaceX leverages vertical integration across launch and satellite manufacturing to compress production timelines. Lockheed Martin Corporation anchors high-reliability government contracts through its heritage in deep-space missions. Airbus SE competes on dual-use European programs spanning civilian Earth observation and military communications.
A spacecraft is a vehicle or platform designed to operate in outer space, typically incorporating aluminum-lithium alloy structures, multi-layer insulation for thermal control, and propulsion systems capable of precise orbital maneuvers using chemical or electric thrusters; its primary purpose is to host payloads for telecommunications, navigation, remote sensing, or scientific investigation beyond Earth's atmosphere. Satellites dominate current production volumes as commercial operators deploy broadband constellations, while Space Exploration applications command premium engineering margins due to radiation-hardened component requirements. Launch Vehicles within the Technology segment absorb disproportionate capital allocation as reusable systems displace expendable rockets.
The Federal Aviation Administration regulates commercial launch licensing in the United States, while NASA imposes stringent mission assurance standards on crew-rated vehicles; the European Space Agency coordinates CE-marking equivalency for spacecraft components across member states, and the International Organization for Standardization publishes ISO 19683 for small spacecraft design. These frameworks shape market access by dictating testing protocols, insurance requirements, and cross-border technology transfer controls. Stakeholders must track how national security classifications for satellite imagery and quantum-encrypted communications reshape procurement eligibility across government and commercial buyer segments.
Market Dynamics
Reusable launch vehicle maturation is compressing payload economics and forcing satellite manufacturers to accelerate production cadences to match launch availability, reshaping procurement relationships across the value chain.
Growth Catalysts
- ISO 19683 Adoption:Standardized small spacecraft design protocols reduce qualification timelines for commercial constellation operators, enabling faster iteration cycles and lower non-recurring engineering costs.
- Space Force Procurement Expansion:United States national security satellite demand anchors multi-year production commitments, providing revenue visibility that supports manufacturing scale investments.
- Electric Propulsion Maturation:Hall-effect and gridded ion thrusters reduce on-orbit fuel mass requirements, extending operational lifespans for geostationary communications platforms.
Market Restraints
- Radiation-Hardened Component Concentration:Limited qualified suppliers for space-grade semiconductors create single-source vulnerabilities in the United States and European supply bases.
- Launch Licensing Friction:FAA commercial launch approval timelines extend 18-24 months, creating scheduling uncertainty for constellation deployment programs.
- Aluminum-Lithium Alloy Cost Volatility:Primary structural material prices fluctuate with aerospace demand cycles, compressing margins on fixed-price satellite bus contracts.
Strategic Opportunities
- In-Orbit Servicing Infrastructure:Robotic refueling and life-extension missions create aftermarket revenue streams beyond initial satellite sales.
- India Constellation Deployment:ISRO's commercial arm and private launch entrants open access to polar and sun-synchronous orbits for Earth observation operators.
- Quantum-Encrypted Communications Mandates:Defense and intelligence agency requirements for tamper-proof satellite links drive premium payload integration demand.
Industry Challenges
- Spacecraft Systems Engineering Talent Scarcity:Cross-disciplinary expertise combining orbital mechanics, thermal management, and software-defined radio remains concentrated at legacy institutions.
- Mission Assurance Documentation Burden:NASA crew-rating and military qualification protocols require exhaustive test matrices that extend development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spacecraft Market |
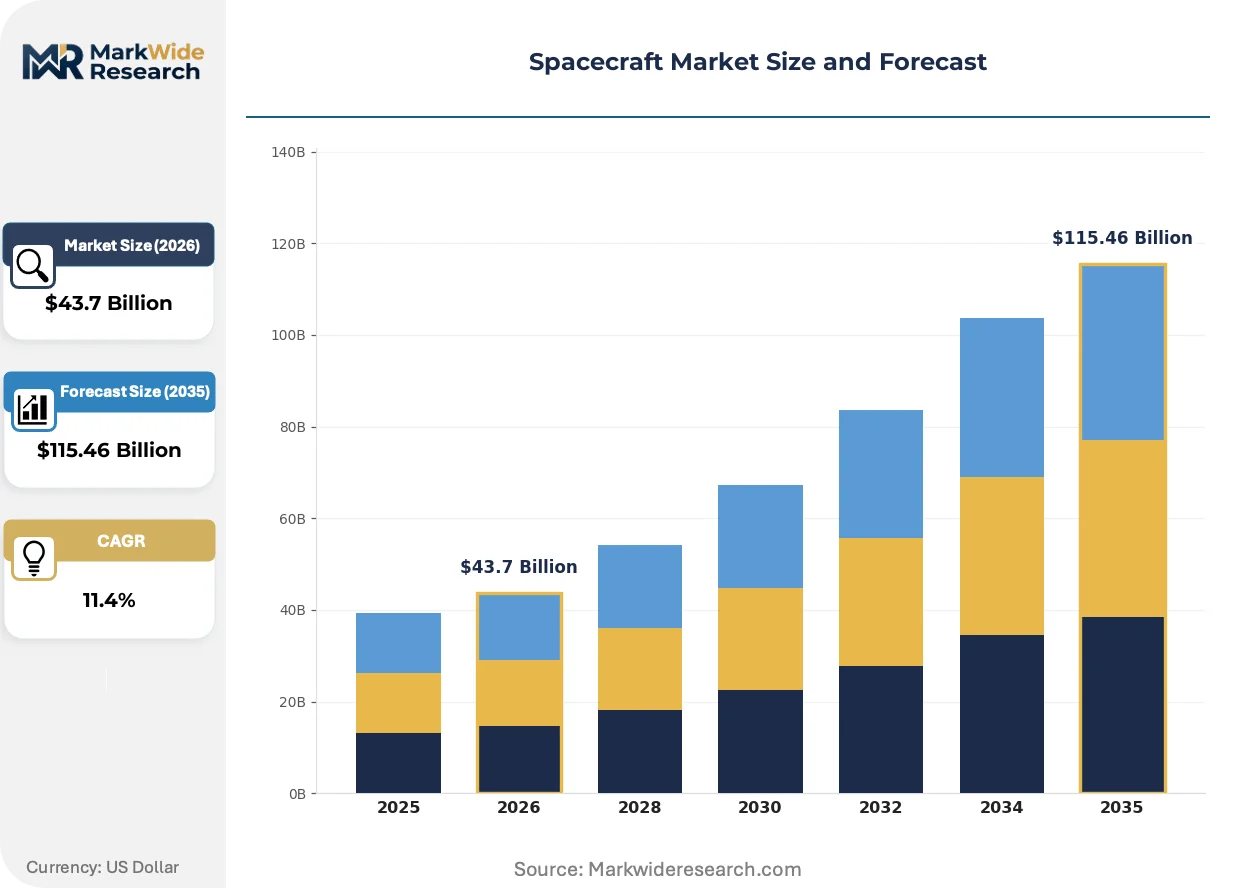
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $115.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Probes, Rovers, Space Capsules Technology: Launch Vehicles, Propulsion Systems, Thermal Protection, Communication Systems End User: Government Agencies, Commercial Firms, Research Institutions, Defence Organizations Application: Telecommunications, Earth Observation, Scientific Research, Space Exploration |
| Companies Covered | Lockheed Martin Corporation, SpaceX, Boeing Defense, Space & Security, Airbus SE, Northrop Grumman Corporation, RTX Corporation, Thales Alenia Space, Blue Origin LLC, Rocket Lab USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spacecraft Market Emerging Trajectories
Software-defined payload architectures are decoupling hardware from function, allowing satellite operators to reconfigure capabilities post-launch without physical modification. This shift demands new manufacturing competencies and contractual frameworks.
Artificial intelligence-enabled autonomous operations is integrating fault detection, orbital maneuver planning, and interference mitigation into onboard processing systems. Commercial remote sensing operators deploy these capabilities to reduce ground segment staffing and compress tasking-to-delivery timelines. The technology is integrating previously separate flight software and ground control functions into unified mission management platforms.
EU Space Surveillance and Tracking framework mandates collision avoidance responsibility for constellation operators above certain satellite counts. This regulatory requirement drives investment in onboard propulsion reserves and autonomous maneuvering systems. European Earth observation programs face the most immediate compliance deadlines, with technical standards still evolving under ESA coordination.
Modular payload procurement is fragmenting traditional satellite prime contractor relationships. Earth observation and telecommunications buyers now source imagers, transponders, and bus platforms from separate vendors, then contract system integrators for final assembly. This pattern concentrates in the United States commercial market, where venture-funded constellation operators prioritize cost and schedule over single-source accountability.
Spacecraft Market Segmentation
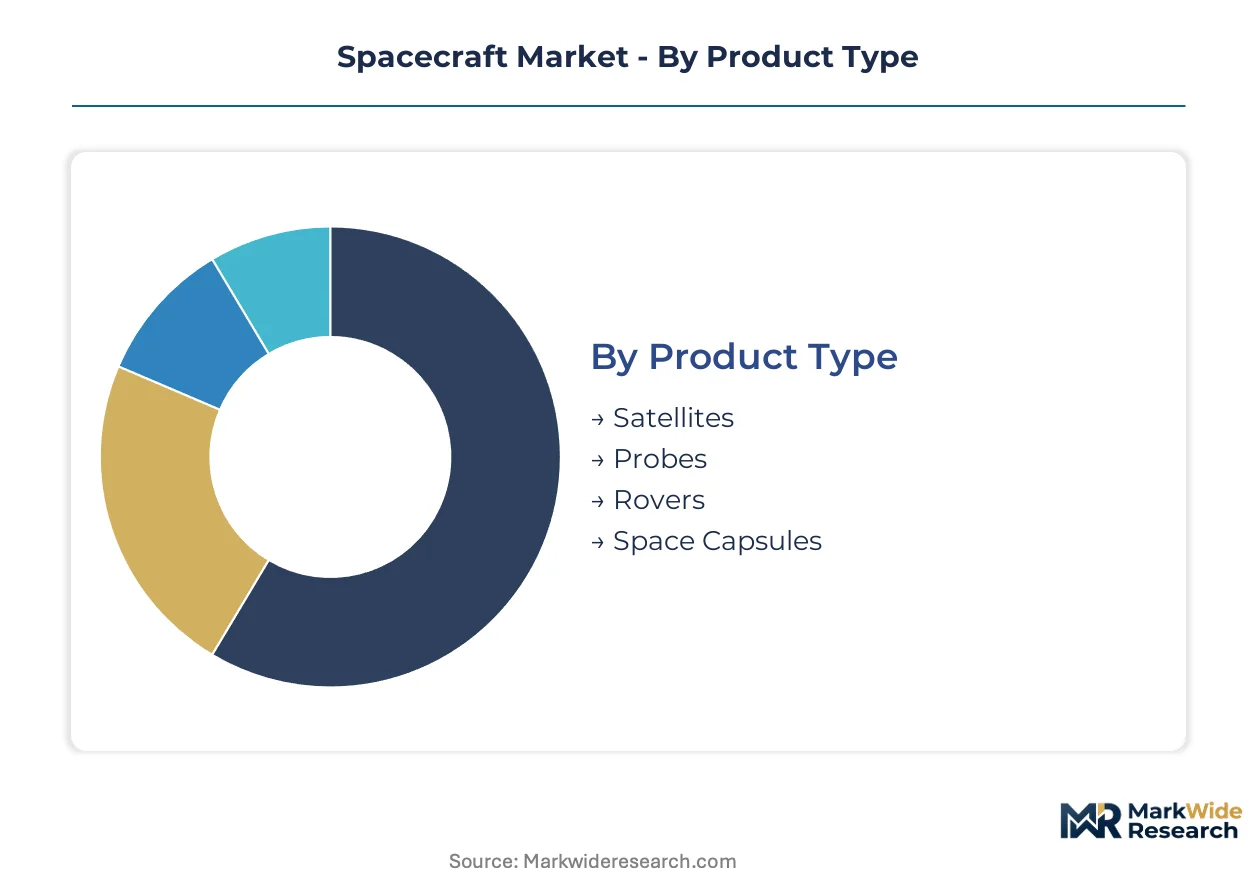
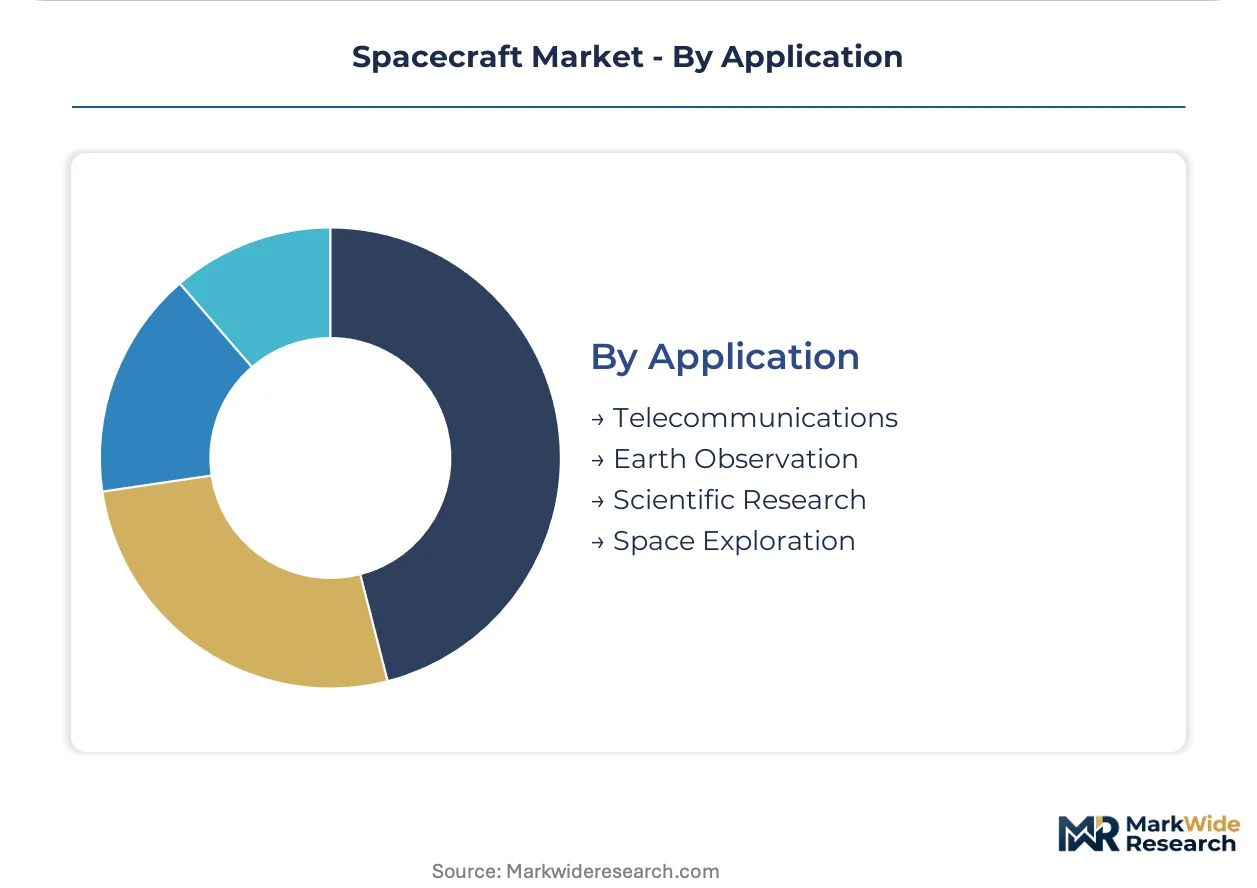
Segmentation reveals how procurement priorities diverge between constellation operators seeking production scale and government buyers demanding mission assurance. Understanding these splits illuminates where capital concentrates and which technology trajectories command premium investment.
Product Type:
Upgrade cycles vary dramatically across spacecraft categories, with commercial broadband constellations driving refresh timelines measured in months rather than years.
- Satellites:Aluminum-lithium alloy bus structures host standardized payload interfaces for telecommunications and remote sensing missions. Demand clusters with United States commercial operators deploying broadband constellations, constrained by FCC spectrum licensing timelines and Space Force launch range availability.
- Probes:Deep-space platforms incorporate radioisotope thermoelectric generators and radiation-hardened avionics for interplanetary missions. NASA Science Mission Directorate procurement anchors development funding, with JPL heritage requirements limiting vendor qualification to a handful of legacy suppliers.
- Rovers:Mobility platforms for planetary surface operations integrate autonomous navigation and sample handling systems.
- Space Capsules:Crew-rated vehicles require NASA human-rating certification and FAA launch licensing for commercial astronaut transport.
Volume placements concentrate in Satellites; the faster expansion belongs to Space Capsules as commercial human spaceflight normalizes.
Technology:
Cost tiering separates proven chemical systems from emerging electric alternatives, with capital intensity dictating procurement consolidation patterns.
- Launch Vehicles:Reusable first-stage architectures using liquid oxygen and kerosene propellants reset payload economics. SpaceX vertical integration across engine production and flight operations compresses per-kilogram costs, forcing expendable rocket competitors toward niche payload segments.
- Propulsion Systems:Hall-effect thrusters and gridded ion engines reduce propellant mass for station-keeping and orbit-raising maneuvers. Commercial geostationary operators in the United States adopt these for extended mission lifespans, though radiation-induced degradation constrains high-power applications.
- Thermal Protection:Multi-layer insulation and ablative heat shields manage extreme temperature differentials during atmospheric entry and deep-space cruise.
- Communication Systems:Software-defined radios and optical laser terminals enable high-bandwidth data relay.
Capital deployment concentrates in Launch Vehicles; the steepest expansion trajectory belongs to Communication Systems as optical inter-satellite links mature.
End User:
Customer type determines specification rigor, with defence and crew-rated applications imposing qualification burdens that commercial operators circumvent.
- Government Agencies:NASA and ESA missions demand traceable component heritage and exhaustive test documentation. United States procurement anchors volume for deep-space platforms, with congressional appropriations cycles creating multi-year production visibility.
- Commercial Firms:Venture-funded constellation operators prioritize schedule compression and cost minimization over single-source accountability. SpaceX and Amazon's Project Kuiper drive demand for standardized small satellite buses.
- Research Institutions:University-led CubeSat programs leverage ISO 19683 standards for rapid qualification.
- Defence Organizations:United States Space Force and National Reconnaissance Office requirements mandate anti-jamming and nuclear-hardening features.
Procurement volume concentrates in Government Agencies; the fastest share gain belongs to Commercial Firms as private capital floods broadband infrastructure.
Application:
Maturity gradients separate established telecommunications from emerging space exploration segments, with margin profiles inverting accordingly.
- Telecommunications:Geostationary and low-Earth-orbit constellations deliver broadband and broadcast services. United States operators lead deployment, with FCC spectrum auctions and ITU coordination procedures shaping competitive access.
- Earth Observation:Multispectral and synthetic aperture radar imagers support agriculture, defense, and climate monitoring. European Copernicus program and United States commercial operators drive sensor demand.
- Scientific Research:Astronomy and heliophysics missions require precision pointing and cryogenic cooling.
- Space Exploration:Crewed lunar and Mars architectures command premium engineering margins due to life-support reliability requirements.
Revenue concentration sits with Telecommunications; the climbing expansion belongs to Space Exploration as Artemis program milestones accelerate hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates where launch infrastructure and government procurement intersect, while demand spreads across operators deploying broadband constellations and national security assets. Production tilts toward countries with established aerospace industrial bases and heavy launch range investment.
United States
NASA Science Mission Directorate and Space Force procurement anchor multi-year production commitments for deep-space platforms and national security satellites. FAA commercial launch licensing governs private operator access to Cape Canaveral and Vandenberg ranges. Los Angeles and Denver corridors concentrate satellite bus manufacturing and propulsion system suppliers.
China
State-owned CASC and emerging commercial launch ventures expand polar and sun-synchronous access for domestic constellation operators. MIIT coordinates spectrum allocation and launch licensing under national space planning frameworks. Xichang and Jiuquan launch centers anchor production clusters in Sichuan and Gansu provinces.
France
ESA member state obligations and ArianeGroup launch vehicle production sustain spacecraft subsystem manufacturing. CNES mission assurance standards shape qualification protocols for European cooperative programs. Toulouse hosts Airbus Defence and Space satellite integration facilities alongside Thales Alenia Space operations.
Japan
JAXA lunar and deep-space exploration missions drive demand for radiation-hardened components and precision pointing systems. METI industrial policy coordinates commercial space activity licensing and technology export controls. Tsukuba and Nagoya corridors concentrate small satellite manufacturers and electric propulsion specialists.
India
ISRO commercial arm Antrix and emerging private launch operators open access to low-inclination orbits for Earth observation constellations. IN-SPACe regulatory framework governs private sector participation in launch and satellite services. Bengaluru and Hyderabad clusters host spacecraft bus integrators and ground segment equipment suppliers.
Spacecraft Market Vendor Landscape
The competitive structure tilts toward vertically integrated launch-service providers with captive satellite manufacturing capabilities. Tiering separates heritage defense contractors holding NASA crew-rating qualifications from venture-funded constellation operators prioritizing production velocity. Strategic archetypes include full-stack integrators controlling launch through operations, specialized bus manufacturers serving dual-use markets, and component suppliers qualified for radiation-hardened applications. Dominant competitive moves encompass reusable launch system maturation and modular payload interface standardization.
Among United States-based defense conglomerates, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions within the mission-assurance tier, anchoring high-reliability government contracts through heritage deep-space capabilities. SpaceX represents the vertically integrated archetype, compressing timelines through in-house production of launch vehicles and satellite constellations. European Airbus SE and Thales Alenia Space sit within the dual-use manufacturing segment, spanning civilian Earth observation and military communications programs across ESA member states.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| SpaceX |
| Boeing Defense, Space & Security |
| Airbus SE |
| Northrop Grumman Corporation |
| RTX Corporation |
| Thales Alenia Space |
| Blue Origin LLC |
| Rocket Lab USA Inc. |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of launch vehicles and satellite buses anchors SpaceX's supply position and compresses procurement timelines, forcing competitors toward outsourced tiered supplier networks with weaker pricing power. This integration choice concentrates cost control with vertically integrated operators while fragmenting margin capture across specialized component vendors.
Pricing Analysis
Cost-down pressure on small satellite buses accelerates because standardized ISO 19683 platforms enable rapid vendor substitution. Three-tier pricing structure across radiation-hardened premium, ITAR-restricted standard, and commercial-off-the-shelf economy levels separates NASA crew-rated missions from Space Force procurement and venture-funded constellations. Brand heritage from JPL or ESA mission success commands premium positioning in deep-space segments. Commercial broadband operators exhibit highest price sensitivity, accepting higher failure rates for per-unit cost minimization.
Supply Chain Analysis
Direct-to-prime channels handle government agency demand while distributor networks serve university CubeSat programs and emerging commercial operators. Manufacturing concentrates in the United States, France, and Japan for radiation-hardened avionics and precision propulsion systems. Aluminum-lithium alloy structures, space-grade semiconductors, and Hall-effect thrusters draw from aerospace and defense industrial bases. Single-source vulnerability for qualified space-grade semiconductors creates procurement risk. Distribution runs through ESA-coordinated European programs and FAA-licensed United States commercial launch ranges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable launch vehicle technology is displacing expendable rocket architectures, compressing production timelines and resetting cost baselines across satellite manufacturing. Incumbents must adapt qualification protocols and supplier relationships to match this transition.
For Market Incumbents: Deploy modular payload interface standardization to defend against vertically integrated constellation operators. Lockheed Martin and Northrop Grumman should accelerate NASA crew-rating recertification cycles to maintain mission-assurance tier positioning. Airbus Defence and Space must deepen European supply chain control as ArianeGroup reusable systems mature. Threat from SpaceX's Starship capacity expansion demands faster production cadences from heritage primes.
For New Entrants and Emerging Players: Cloud-based ground-segment-as-a-service platforms offer lowest barrier-to-entry positioning for venture-funded remote sensing ventures. India polar orbit access through ISRO commercial arm and private launch entrants represents most penetrable geography. Target university-led CubeSat programs requiring rapid qualification under ISO 19683 protocols. Direct sales to Earth observation analytics firms bypass prime contractor markup capture.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense conglomerates seeking radiation-hardened component capabilities or constellation operators needing vertical manufacturing control. Long-term viability favors suppliers qualified for Space Force and National Reconnaissance Office procurement with multi-year appropriations visibility. Acquisition target archetype: specialized electric propulsion vendors with Hall-effect thruster flight heritage. Watch Space Force launch range capacity expansion as inflection signal for manufacturing scale investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Launch Vehicle Maturation | SpaceX Starship and Blue Origin New Glenn reset payload economics, forcing satellite production acceleration. |
| Modular Payload Interface Standardization | ISO 19683 adoption enables vendor substitution, fragmenting traditional prime contractor relationships. |
| In-Orbit Servicing Infrastructure Development | Northrop Grumman MEV missions create aftermarket revenue streams beyond initial satellite sales. |
| Quantum-Encrypted Communications Integration | Space Force requirements for tamper-proof links drive premium payload engineering margins. |
| Software-Defined Radio Architecture Deployment | Thales Alenia Space and Airbus reconfigure satellite capabilities post-launch without physical modification. |
Methodological Framework
Multi-period observation of launch cadence, constellation deployment timelines, and procurement award patterns anchored the trend analysis, supplemented by interviews with satellite bus manufacturing executives, Space Force program officers, ESA mission assurance directors, commercial constellation operators, and FAA licensing officials. Primary intelligence combined with secondary validation from NASA budget justifications, ESA ministerial council documents, FCC spectrum auction records, and SEC filings from publicly traded defense contractors. Bottom-up unit deployment tracking across geostationary and low-Earth-orbit segments triangulated against top-down addressable market sizing.
Input-output matrices mapped propulsion system efficiency gains, launch cost curves, and payload mass-to-orbit economics across the projection horizon. Segmentation modeling incorporated spacecraft type, propulsion technology tier, end-user procurement rigor, and application maturity. CAGRs derived from regression analysis of historical production volumes against announced constellation deployment schedules and government appropriations cycles. Industry-specific forecast inputs included Space Force multi-year procurement commitments and FCC spectrum licensing timelines.
The model holds under steady government appropriations and commercial capital availability; deviation in launch range capacity constraints or radiation-hardened component supply disruption would shift deployment trajectories. Forecasts embed assumptions regarding reusable launch vehicle reliability maturation and ISO 19683 qualification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Oscillator Market
Space
China Space Electronics Market
Space
Space Launch Services Market
Space
Spacesuit Market
Space
UK Space Electronics Market
Space
India Aviation, Defense, and Space Market
Space
US Space Launch Services Market
Space
Space-Based C4ISR Market
Space
Space Service Market
Space
Space Semiconductor Market
Space
Space Battery Market
Space
Space Transportation Market
Space
Space Sensors Market
Space
Carrier Rocket Market
Space
Europe Space Logistics Market
Space
Africa Space Propulsion System Market