
 UK Satellite Imagery Services Market | 2026-2036
UK Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK Satellite Imagery Services Market Insights
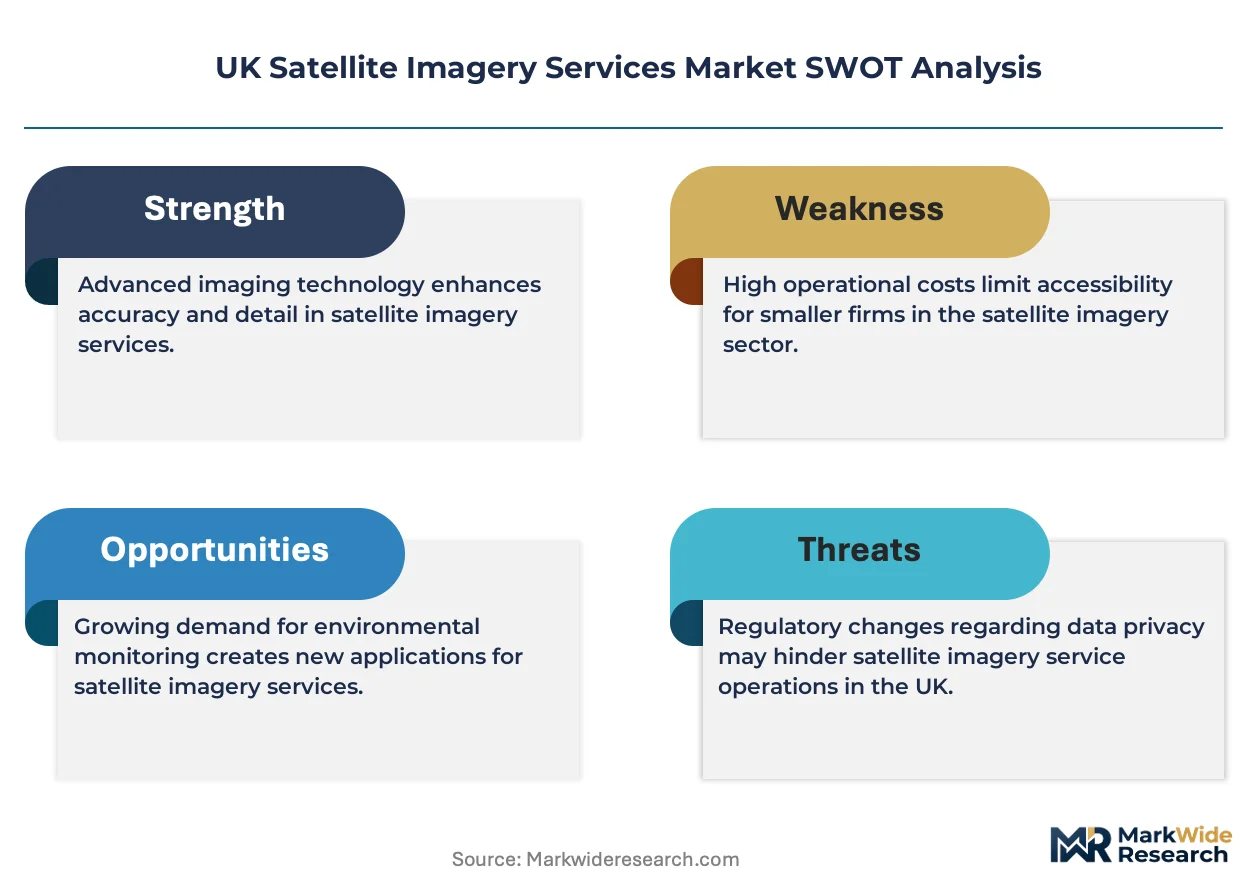
Sub-meter resolution capability is rotating toward mainstream procurement standards across UK government and commercial accounts. Airbus leverages its dual-use heritage to anchor defense and intelligence contracts with sovereign payload control. Planet Labs sustains daily revisit cadence through its Dove and SkySat constellations, competing aggressively on temporal resolution for agricultural monitoring. ICEYE differentiates via synthetic aperture radar technology that penetrates cloud cover, occupying a premium niche in maritime and disaster response applications.
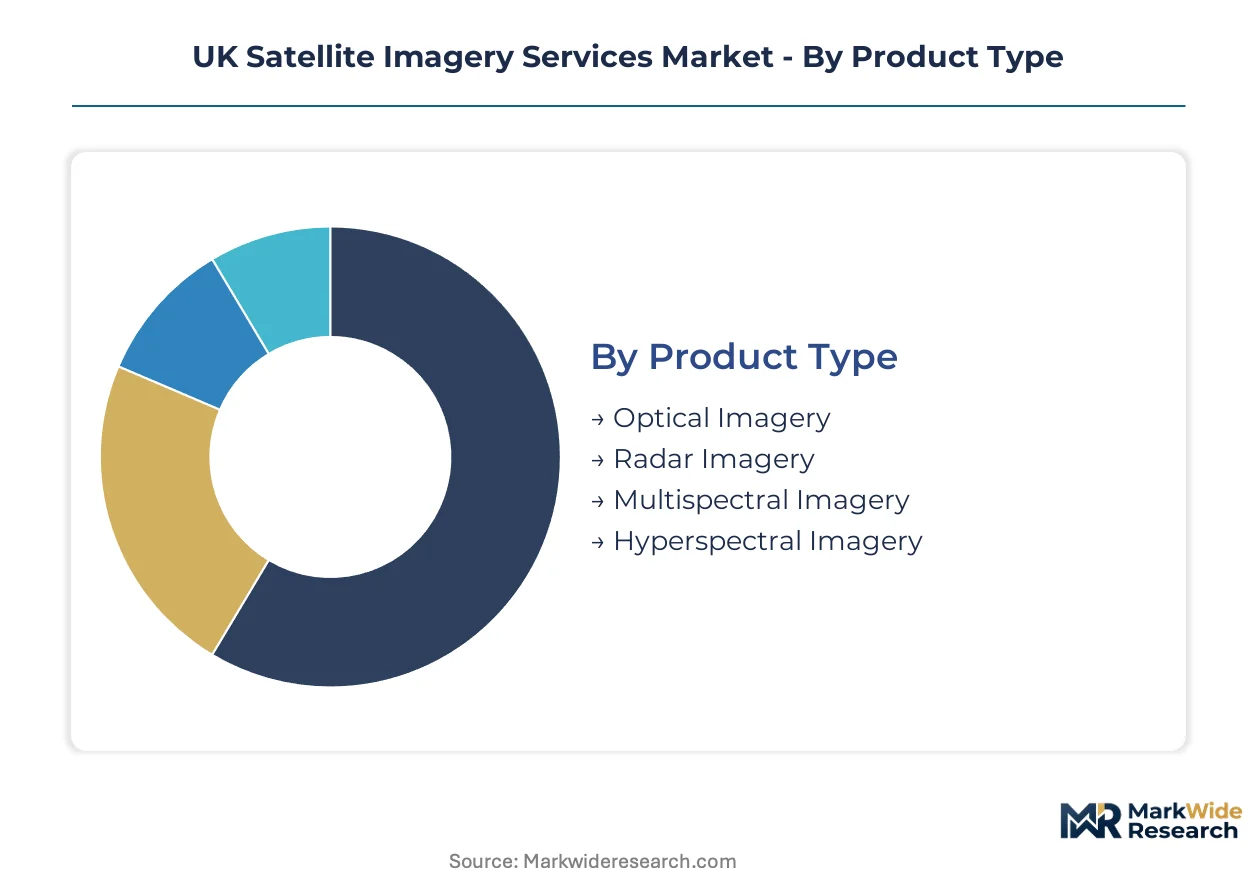
UK Satellite Imagery Services encompass the acquisition, processing, and analytical distribution of geospatial data captured by Earth-orbiting platforms operating at altitudes from low Earth orbit to geostationary positions, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral bands. These services transform raw sensor data into actionable intelligence products for infrastructure assessment, environmental surveillance, and strategic planning across public and private sectors. Optical imagery retains the largest revenue share among product types due to mature processing pipelines and intuitive interpretation, though radar imagery represents the fastest-expanding margin pool as all-weather reliability commands premium pricing in defense and insurance verticals. Among end users, environmental monitoring applications are gaining structural momentum driven by regulatory disclosure requirements and climate risk modeling demand.
The UK Space Agency governs orbital licensing under the Outer Space Act, while the Civil Aviation Authority coordinates airspace integration for launch and reentry operations, collectively shaping market access conditions for domestic and foreign operators. Data protection standards derived from UK GDPR and the National Security and Investment Act influence cross-border imagery sharing and foreign ownership scrutiny in sensitive geospatial analytics. Stakeholders must monitor evolving export control classifications for synthetic aperture radar products and anticipate procurement preference shifts toward sovereign satellite constellations as operational security considerations intensify.
Market Dynamics
Defense procurement protocols across Whitehall are mandating sovereign payload control and domestic ground station ownership, compressing foreign operator access to classified contracts while elevating UK-registered satellite operators with end-to-end domestic custody chains.
Growth Catalysts
- National Space Strategy procurement preferences:UK government frameworks now weight domestic satellite ownership criteria in defense and intelligence tenders, directing contract flow toward operators with sovereign orbital assets.
- Climate disclosure mandates:CSRD-aligned reporting requirements from the Financial Conduct Authority are forcing institutional investors and insurers to procure satellite-derived environmental monitoring for portfolio risk assessment.
- Harwell-Oxfordshire cluster density:Co-location of spacecraft manufacturers, analytics software developers, and specialized talent pools around the UK Space Gateway facility is compressing R&D-to-deployment timelines for commercial Earth observation services.
Market Restraints
- Launch capacity bottlenecks:Domestic orbital insertion options remain limited to SaxaVord Spaceport and Cornwall Spaceport, constraining constellation refresh rates and elevating reliance on foreign launch providers.
- Sensor component concentration:Synthetic aperture radar transmitter modules and high-grade optical focal plane arrays concentrate among a narrow supplier base in Germany and the United States, exposing UK integrators to export control friction.
- Spectral allocation congestion:Ofcom licensing frameworks for Earth observation downlink frequencies face coordination complexity with 5G terrestrial networks, delaying operational authorization for new entrants.
Strategic Opportunities
- Scottish maritime surveillance gap:North Sea and Atlantic fisheries enforcement agencies lack persistent all-weather coverage, creating white space for SAR-equipped constellation operators to anchor recurring monitoring contracts.
- Insurance parametric products:Flood and crop underwriters are piloting automated claims triggers using satellite-derived damage assessments, opening subscription revenue models distinct from traditional tasking fees.
- AI-ML analytics convergence:Machine learning pipelines trained on proprietary orbital archives are enabling predictive infrastructure degradation models that command premium pricing from Network Rail and National Highways.
Industry Challenges
- Geospatial data science talent scarcity:The intersection of orbital mechanics, remote sensing physics, and Python-based analytics tooling faces acute pipeline gaps, with universities struggling to scale specialized MSc programs to industry demand.
- Legacy system integration friction:Defense and civil government clients operate decades-old geographic information system architectures that resist API-native satellite data feeds, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Satellite Imagery Services Market |
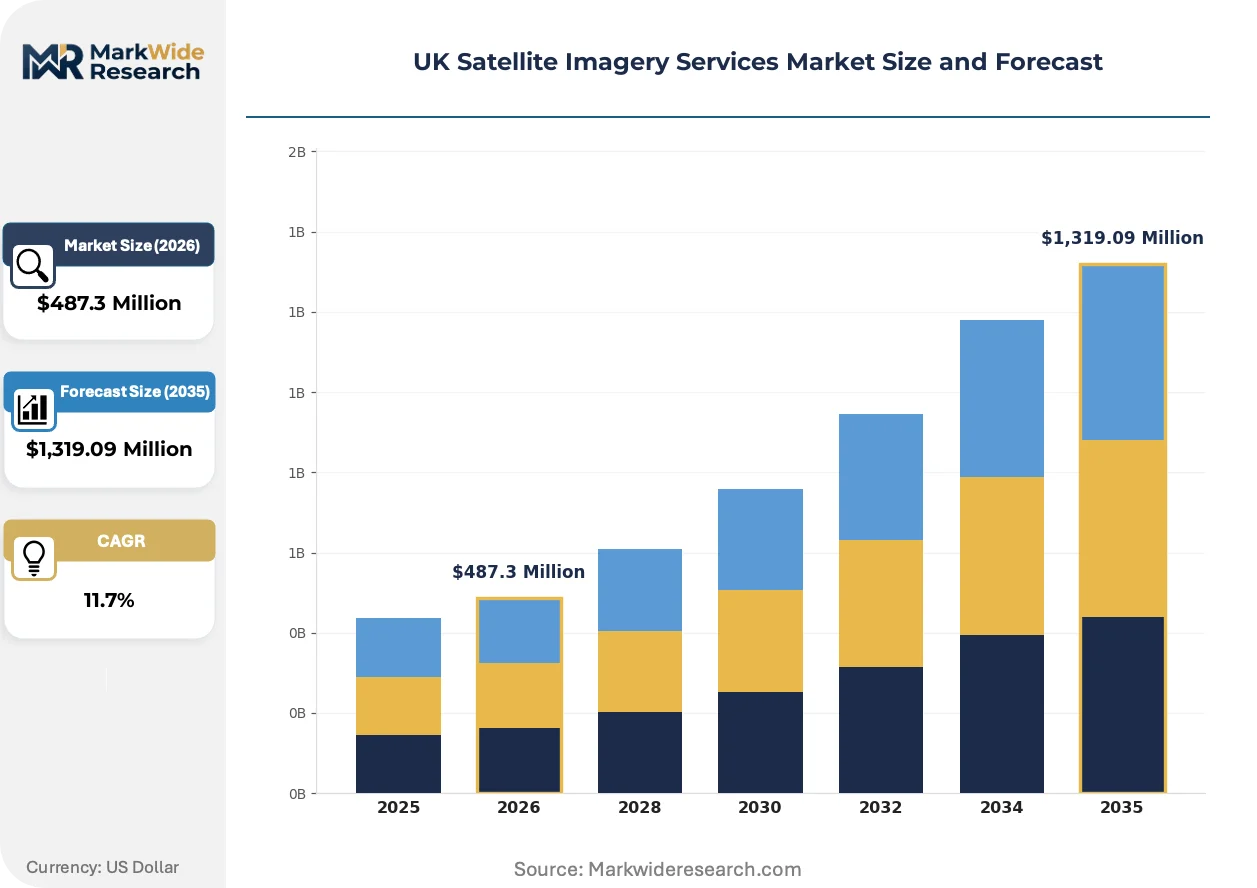
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Imagery, Radar Imagery, Multispectral Imagery, Hyperspectral Imagery End User: Aerospace, Agriculture, Defense, Environmental Monitoring Application: Urban Planning, Disaster Management, Climate Research, Resource Management Solution: Data Analysis, Geographic Information System, Real-Time Monitoring, Custom Mapping |
| Companies Covered | Maxar Technologies, Airbus, Telespazio UK Ltd, CGG SA, L3Harris Corporation, Veritas Imagery Services Ltd, Planet Labs, ICEYE, BlackSky, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Satellite Imagery Services Market Trends and Innovations
Orbital sensor capabilities are compressing revisit intervals while expanding spectral resolution, forcing business model evolution from one-time image sales toward continuous analytics subscriptions anchored in proprietary algorithmic layers.
Synthetic aperture radar constellations are supplanting electro-optical platforms as the default procurement choice for maritime and defense applications where atmospheric obscuration renders traditional imaging unreliable. Royal Navy border patrol contracts and North Sea energy infrastructure operators are specifying SAR-first requirements in tender documents. This technology shift is compressing pricing power for pure-play optical providers while elevating operators with dual-sensor or all-weather portfolios.
The UK Space Agency's streamlined licensing pathway under the Space Industry Act is accelerating orbital authorization timelines from 18 months to sub-90 days for commercial Earth observation missions. This regulatory compression is drawing foreign constellation operators to establish UK legal entities and ground segment presence. Domestic analytics firms in the Southeast cluster are responding by deepening partnership structures with newly licensed spacecraft operators to secure preferred data access terms.
Subscription-based monitoring contracts are displacing transactional image tasking as the dominant commercial arrangement across agricultural and infrastructure verticals. Buyers in England's precision farming sector and Wales-based utilities are consolidating vendor relationships around annual data service agreements rather than per-scene procurement. This behavioral shift is most pronounced among mid-scale agritech aggregators who bundle satellite-derived crop health indices into their own platform offerings.
UK Satellite Imagery Services Market Segmentation
Segmentation of the UK Satellite Imagery Services Market reveals how procurement standards, regulatory frameworks, and end-use requirements reshape vendor positioning. Understanding these divides exposes where pricing power concentrates and which technology trajectories face headwinds.
Product Type:
The UK Space Agency's Outer Space Act licensing and Civil Aviation Authority airspace coordination create differentiated compliance burdens across sensor modalities, with radar platforms facing stricter export control scrutiny under dual-use classifications.
- Optical Imagery:Panchromatic and multispectral sensors capture visible and near-infrared wavelengths at resolutions reaching sub-meter precision. England's Southeast cluster around Harwell dominates processing pipeline development for agricultural monitoring and urban development applications, though cloud cover limitations constrain reliability in maritime domains.
- Radar Imagery:Synthetic aperture radar systems transmit microwave pulses that penetrate atmospheric obscuration, enabling all-weather data collection. Royal Navy border patrol contracts and North Sea energy operators specify SAR-first requirements, compressing pricing power for pure-play optical providers while elevating operators with dual-sensor portfolios.
- Multispectral Imagery:Discrete spectral bands beyond visible wavelengths support vegetation health assessment and mineral identification for precision farming and geological surveys.
- Hyperspectral Imagery:Continuous narrow bands enable material-specific identification for environmental contamination detection and advanced agricultural diagnostics.
Optical Imagery handles the majority of throughput; Radar Imagery is the fastest mover on share.
End User:
Customer concentration patterns across Whitehall procurement frameworks and commercial verticals determine contract scale and data security requirements.
- Aerospace:Satellite manufacturers and launch service providers consume imagery for orbital debris tracking and launch site environmental assessment. Scotland's emerging spaceport infrastructure at SaxaVord and Cornwall drives localized demand for pre-launch terrain analysis and post-flight damage evaluation.
- Defense:Intelligence agencies and military commands mandate sovereign payload control and domestic ground station ownership under National Security and Investment Act scrutiny. UK-registered operators with end-to-end domestic custody chains secure preferential access to classified tenders.
- Agriculture:Precision farming aggregators bundle crop health indices into platform offerings, consolidating vendor relationships around annual data service agreements rather than per-scene procurement.
- Environmental Monitoring:Regulatory disclosure requirements under CSRD-aligned Financial Conduct Authority mandates force institutional investors and insurers to procure satellite-derived risk assessment tools.
Defense commands premium pricing tiers; Environmental Monitoring is expanding most quickly as compliance deadlines approach.
Application:
Functional use cases segment by data refresh frequency requirements and analytical complexity, with automated processing pipelines commanding subscription premiums over manual interpretation.
- Urban Planning:Local authorities in Greater London and Manchester metropolitan areas utilize change detection algorithms for unauthorized construction monitoring and infrastructure density mapping, with Ofcom spectral licensing delays constraining real-time service rollout.
- Disaster Management:Flood and wildfire response agencies require sub-hourly revisit cadences for damage assessment and evacuation routing. ICEYE's SAR-equipped constellations anchor recurring monitoring contracts where cloud cover blocks optical alternatives.
- Climate Research:Academic institutions and government laboratories track ice sheet dynamics and sea level rise through long-duration archival analysis.
- Resource Management:Water utilities and forestry commissions monitor catchment areas and timber stocks through seasonal comparison datasets.
Urban Planning absorbs the largest procurement volumes; Disaster Management shows the steepest expansion trajectory as parametric insurance products mature.
Solution:
Service layer differentiation separates raw data vendors from value-added analytics providers, with API-native platforms displacing legacy GIS middleware.
- Data Analysis:Machine learning pipelines trained on proprietary orbital archives enable predictive infrastructure degradation models. Network Rail and National Highways pay premium subscriptions for automated track and roadway condition forecasting.
- Geographic Information System:Integration layers translate satellite feeds into legacy government architectures, though decades-old system resistance elevates middleware development costs.
- Real-Time Monitoring:Continuous streaming services support maritime domain awareness and border surveillance with minimal latency.
- Custom Mapping:Bespoke cartographic products address litigation support and heritage site documentation with specialized spectral processing.
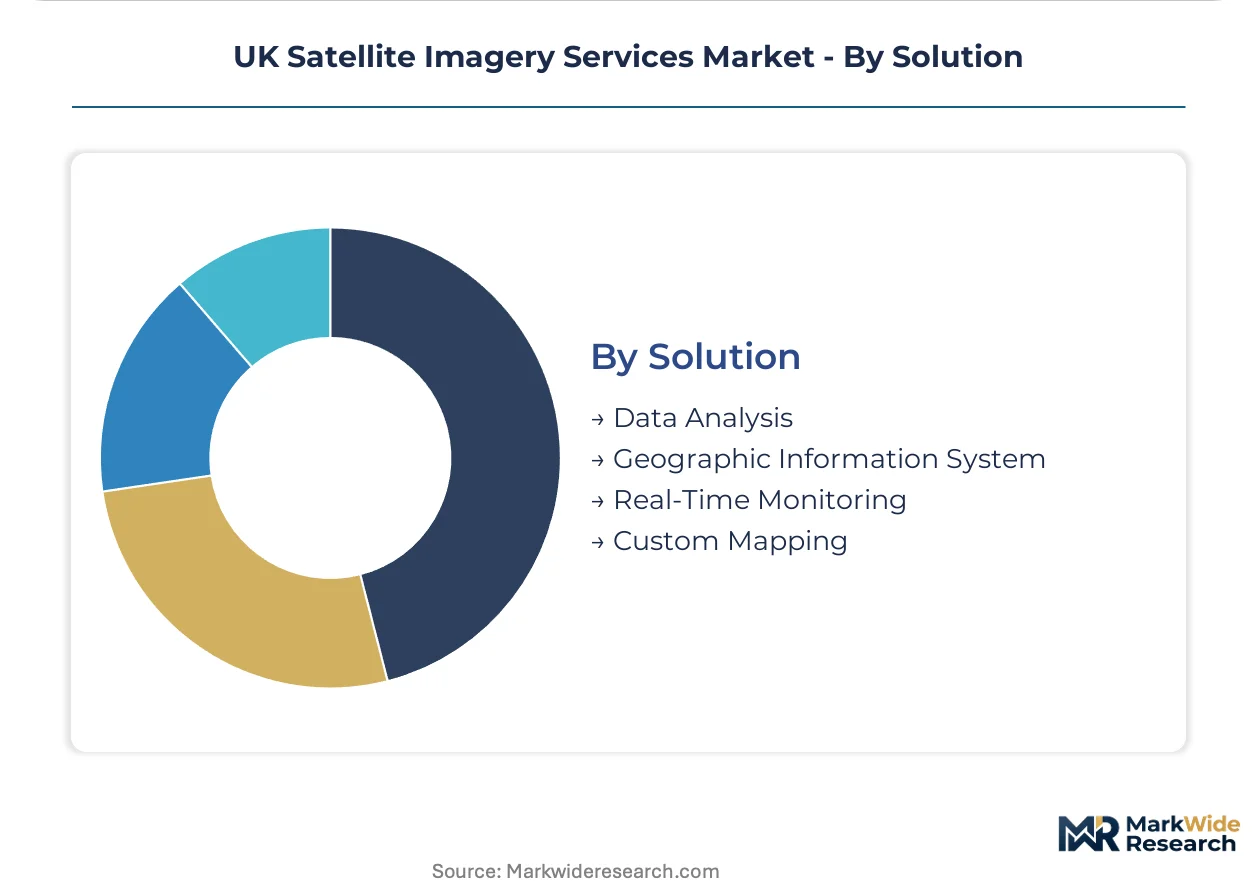
Data Analysis captures the highest margin expansion; Real-Time Monitoring is gaining share fastest as defense procurement specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK satellite imagery providers export analytical services to European defense ministries and Commonwealth maritime agencies, with domestic demand concentrated in England's technology corridor.
London and the Southeast
Defense procurement from Whitehall agencies and intelligence community contracts drive premium service demand. The UK Space Agency's streamlined licensing under the Space Industry Act accelerates orbital authorization timelines. The Harwell-Oxfordshire cluster hosts spacecraft manufacturers, analytics developers, and the UK Space Gateway facility, compressing R&D-to-deployment cycles for Earth observation ventures.
Scotland
North Sea fisheries enforcement and Atlantic maritime surveillance agencies require persistent all-weather coverage for border protection. SaxaVord Spaceport development on Unst creates localized demand for pre-launch terrain analysis and environmental assessment. Edinburgh and Glasgow analytics firms are deepening partnerships with synthetic aperture radar operators to anchor recurring monitoring contracts.
Midlands
Precision agriculture aggregators and utility operators procure crop health indices and infrastructure monitoring for Network Rail corridors. The Civil Aviation Authority coordinates airspace integration challenges that affect drone-to-satellite data fusion trials. Birmingham and Nottingham technology parks house middleware developers translating satellite feeds into legacy government geographic information systems.
Wales
Water utilities and forestry commissions monitor catchment areas and timber stocks through seasonal comparison datasets. Natural Resources Wales leverages satellite-derived environmental monitoring for regulatory compliance and flood risk assessment. Cardiff-based analytics startups are piloting automated claims triggers for parametric insurance products targeting agricultural underwriters.
UK Satellite Imagery Services Market Competitive Landscape
Listed leaders compete with private specialists across sovereign payload control and temporal resolution capabilities. The vendor base fragments across dual-use heritage operators, commercial constellation pure-plays, and analytics-layer specialists. Three archetypes dominate: defense-anchored primes with domestic custody chains, high-revisit commercial constellations, and SAR-equipped niche operators. Competitive intensity concentrates on M&A activity targeting analytics capabilities and strategic partnerships securing preferred data access.
Within the defense-anchored tier, Airbus and L3Harris Corporation exemplify operators leveraging sovereign payload control for classified procurement. Among commercial constellation specialists, Planet Labs and ICEYE occupy positions differentiated by revisit cadence and all-weather reliability. Maxar Technologies sits within the analytics-integrated archetype, bridging raw imagery capture with value-added intelligence products.
| Leading Market Players |
|---|
| Maxar Technologies |
| Airbus |
| Telespazio UK Ltd |
| CGG SA |
| L3Harris Corporation |
| Veritas Imagery Services Ltd |
| Planet Labs |
| ICEYE |
| BlackSky |
| Others |
Pricing and Supply Chain Analysis
Constellation refresh economics at scale compress unit data costs while elevating barriers for sub-scale operators, concentrating pricing power among high-cadence providers with dedicated launch schedules and domestic ground segment ownership. This scale dynamic anchors price floors for synthetic aperture radar tasking above electro-optical alternatives, with sovereign payload control commanding further premiums in UK defense procurement.
Pricing Analysis
Next-generation SAR constellations price at 40-60% premiums over legacy optical platforms, while prior-generation sub-meter electro-optical imagery faces commoditization in agricultural verticals. Three-tier pricing structure across premium, standard, and economy levels segments by revisit frequency and analytical layer inclusion, with defense-intelligence buyers showing lowest price sensitivity and mid-scale agritech aggregators driving hardest volume negotiations. Cost compression in standard-tier optical tasking is intensifying because Planet Labs and BlackSky flood agricultural markets with daily-coverage subscriptions.
Supply Chain Analysis
Sensor component lead times extending 18-24 months for synthetic aperture radar transmitter modules constrain UK integrator output planning and inflate work-in-progress inventory carrying costs. Manufacturing concentration in Germany and the United States for high-grade optical focal plane arrays, plus Canadian and Finnish SAR payload expertise, exposes domestic operators to export control friction under dual-use classifications. Single-source vulnerability for radiation-hardened electronics creates supply chain risk, with distribution running through specialist aerospace component distributors and direct OEM partnerships with spacecraft manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK satellite imagery demand cycles correlate with defense procurement waves and CSRD compliance deadlines, positioning the market for cyclical expansion as regulatory disclosure mandates mature and sovereign constellation investments reach operational status.
For Market Incumbents: Compound defensive moats through backward integration into domestic ground station networks and exclusive licensing partnerships with SaxaVord launch providers. ICEYE and Airbus should prioritize sovereign payload certification under UK Space Agency frameworks to preempt foreign operator access to classified tenders, while investing in proprietary AI-ML analytics layers to escape raw data commoditization. For New Entrants and Emerging Players: Anchor in Scotland's maritime surveillance gap where North Sea fisheries enforcement lacks persistent all-weather coverage, and Wales' parametric insurance pilot programs where automated flood claims triggers remain underdeveloped. The most penetrable entry point is SAR-equipped coastal monitoring subscriptions sold through Edinburgh-based analytics partnerships, with go-to-market execution via direct agency contracts rather than platform aggregator channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analytics-layer specialists with proprietary orbital archives and trained machine learning pipelines over pure-play constellation operators facing capital intensity headwinds. Long-term viability across the projection horizon rests on algorithmic differentiation rather than sensor hardware scale, with acquisition targets screening for Network Rail or National Highways subscription revenue anchoring. The signal to watch is defense procurement specification shifts toward predictive infrastructure degradation models as contract evaluation criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Ground Segment Buildout | Domestic custody chains satisfy National Security and Investment Act scrutiny for classified tenders. |
| AI-ML Analytics Layer Development | Predictive track degradation models command premium subscriptions from Network Rail. |
| SAR-First Maritime Constellation Deployment | All-weather reliability anchors recurring Scottish fisheries enforcement contracts. |
| Parametric Insurance Partnership Structuring | Automated flood claims triggers open subscription revenue distinct from tasking fees. |
| Harwell Cluster Talent Pipeline Investment | Co-located R&D compresses deployment timelines for Earth observation ventures. |
Research Methodology
Initial hypotheses were tested against primary input from satellite operator executives, defense procurement officers at UK Space Agency, precision farming platform engineers, and maritime surveillance agency planners, and refined through secondary validation against UK Space Agency licensing records, Civil Aviation Authority airspace coordination filings, Financial Conduct Authority CSRD implementation guidance, and Cornwall and SaxaVord spaceport development disclosures. Bottom-up constellation capacity modeling and top-down defense budget allocation analysis were triangulated to converge on segment-level demand estimates.
Variance decomposition across sensor modality, end-use vertical, and solution layer dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed base refresh cycles, regulatory compliance deadline clustering, and defense procurement pipeline visibility. Industry-specific forecast inputs included synthetic aperture radar payload production capacity at major European integrators and UK academic geospatial data science program graduation rates.
Material uncertainties — launch schedule slippage at domestic spaceports, export control reclassification of SAR components, and Ofcom spectral licensing congestion — sit outside the modeled envelope. Forecasts reflect documented assumptions about sovereign payload preference intensification and CSRD disclosure mandate enforcement rigor. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
US Remote Sensing Technology Market
Satellite
Satellite Internet Market
Satellite
Satellite Communication Equipment Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Global Dish Antennas Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Satellite Transponder Market
Satellite
Russia Satellite Imagery Services Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Satellite Gateway Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Canada Satellite Connectivity Market