
 Space Robots Market | 2026-2036
Space Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Space Robots Market Analytics
Robotics engineering talent scarcity is reorganizing how prime contractors and startups allocate R&D budgets across lunar and orbital programs. Lockheed Martin Corporation sustains long-cycle development of deep-space manipulation systems through classified and civil agency contracts. SpaceX leverages rapid iteration protocols to compress timelines for in-orbit servicing prototypes. Honeybee Robotics specializes in planetary sampling mechanisms that occupy niche positions within NASA mission architectures.
Space robots encompass electromechanical systems engineered for extraterrestrial operation, typically incorporating radiation-hardened processors, redundant actuation, and thermal control substrates rated for vacuum environments ranging from low Earth orbit to cislunar space. These systems execute proximity operations, surface traversal, payload manipulation, and infrastructure assembly where human presence proves impractical or prohibitive. Robotic arm deployments dominate current revenue flows due to established integration with crewed and uncrewed platforms. Autonomous drones represent the fastest-expanding functionality category as satellite servicing and debris removal missions multiply. Exploration applications anchor near-term procurement volumes, though construction functionality is attracting development capital for lunar base preparation.
FAA licensing requirements for commercial launch and reentry operations shape how robot developers validate flight heritage, while NASA technical standards govern materials selection and verification protocols for agency-funded missions. ESA's Clean Space initiative and debris mitigation guidelines from the Inter-Agency Space Debris Coordination Committee constrain design choices for orbital servicing architectures. Stakeholders must weigh regulatory compliance timelines against the accelerating cadence of private lunar missions when sequencing product development investments.
Market Dynamics
Autonomous proximity operations are compressing development cycles for orbital servicing architectures as satellite operators demand demonstration of flight heritage before procurement commitment.
Growth Catalysts
- Artemis Program Procurement:NASA's lunar exploration roadmap is generating sustained demand for space-qualified manipulators capable of regolith sampling and infrastructure deployment.
- REACH-Compliant Materials:European manufacturers are accelerating adoption of restricted-substance-free thermal control substrates to maintain ESA supply chain eligibility.
- Debris Mitigation Mandates:The Inter-Agency Space Debris Coordination Committee guidelines are compelling satellite operators to fund end-of-life removal robotics.
Market Restraints
- Radiation-Hardened Processor Costs:Foundry capacity constraints for qualified semiconductors are inflating unit economics for deep-space compute modules.
- Launch Integration Bottlenecks:Dependence on a limited set of orbital deployment providers creates scheduling vulnerability for demonstration missions.
- Vacuum-Environment Verification:Ground-based thermal-vacuum chamber availability restricts prototype validation throughput for new entrants.
Strategic Opportunities
- Cislunar Construction Robotics:Lunar base preparation applications represent uncaptured demand for autonomous assembly systems beyond current exploration-focused procurement.
- AI-Enabled Autonomy Convergence:Integration of machine vision with force-feedback manipulation is opening new mission profiles for uncrewed satellite servicing.
- India's Space Industrialization:ISRO's commercialization push and BIS standards alignment are creating entry pathways for component suppliers.
Industry Challenges
- Spacecraft Systems Integration:Robotic payloads must demonstrate electromagnetic compatibility with host platform avionics, extending qualification timelines.
- Multidisciplinary Talent Scarcity:Competition for engineers combining orbital mechanics expertise with real-time control systems knowledge is inflating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Robots Market |
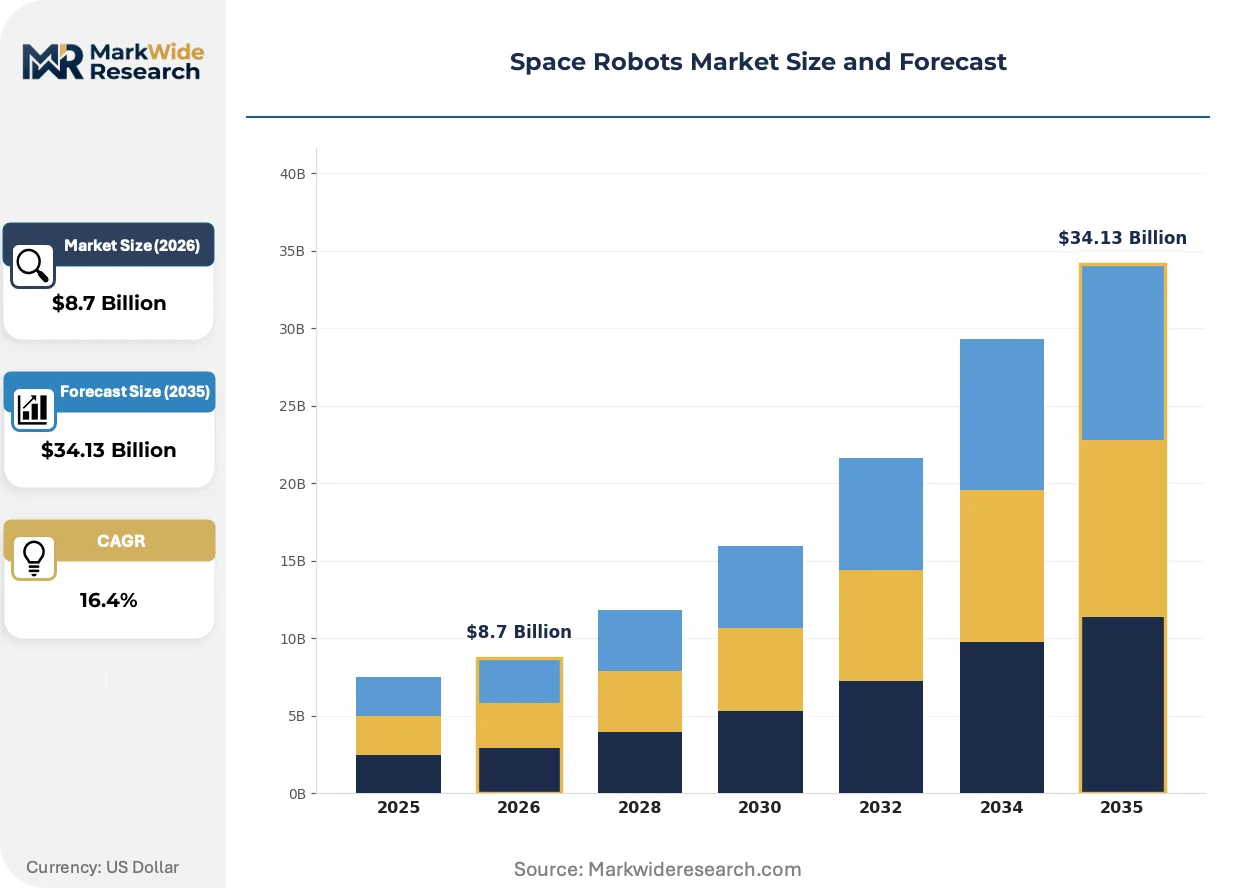
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Robotic Arm, Rovers, Autonomous Drones, Space Probes Functionality: Exploration, Maintenance, Construction, Surveillance End User: Aerospace Agencies, Commercial Companies, Research Institutions, Military Deployment Mode: Uncrewed Missions, Crewed Missions, Research Stations, Orbital Platforms |
| Companies Covered | SpaceX, Honeybee Robotics, Lockheed Martin Corporation, Astrobotic Technology, MDA Space, Airbus SE, Oceaneering International, Redwire LLC, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Robots Market Evolving Landscape
Hardware-software co-design is displacing sequential development as mission timelines compress and autonomy requirements harden. Three forces are restructuring competitive positioning.
Modular robotic architectures are bifurcating procurement patterns across the market. Standardized mechanical interfaces and software-defined control layers enable rapid reconfiguration between servicing, assembly, and exploration functions. Prime contractors are adopting these systems to reduce non-recurring engineering costs, while emerging players leverage module compatibility to bypass traditional integration barriers.
FAA commercial launch licensing requirements are tightening validation protocols for autonomous rendezvous systems. Operators must now demonstrate collision avoidance algorithms through hardware-in-the-loop testing before orbital deployment. Small satellite servicing ventures are responding by partnering with established launch providers to inherit flight heritage rather than building independent certification pathways.
Buyer concentration among constellation operators is compressing vendor qualification cycles. SpaceX and Amazon's Project Kuiper are imposing accelerated acceptance testing on robotic subsystem suppliers, displacing the traditional multi-year agency validation model. This shift is most visible in United States procurement, where commercial demand now outpaces civil agency volumes for proximity operation technologies.
Space Robots Market Segmentation
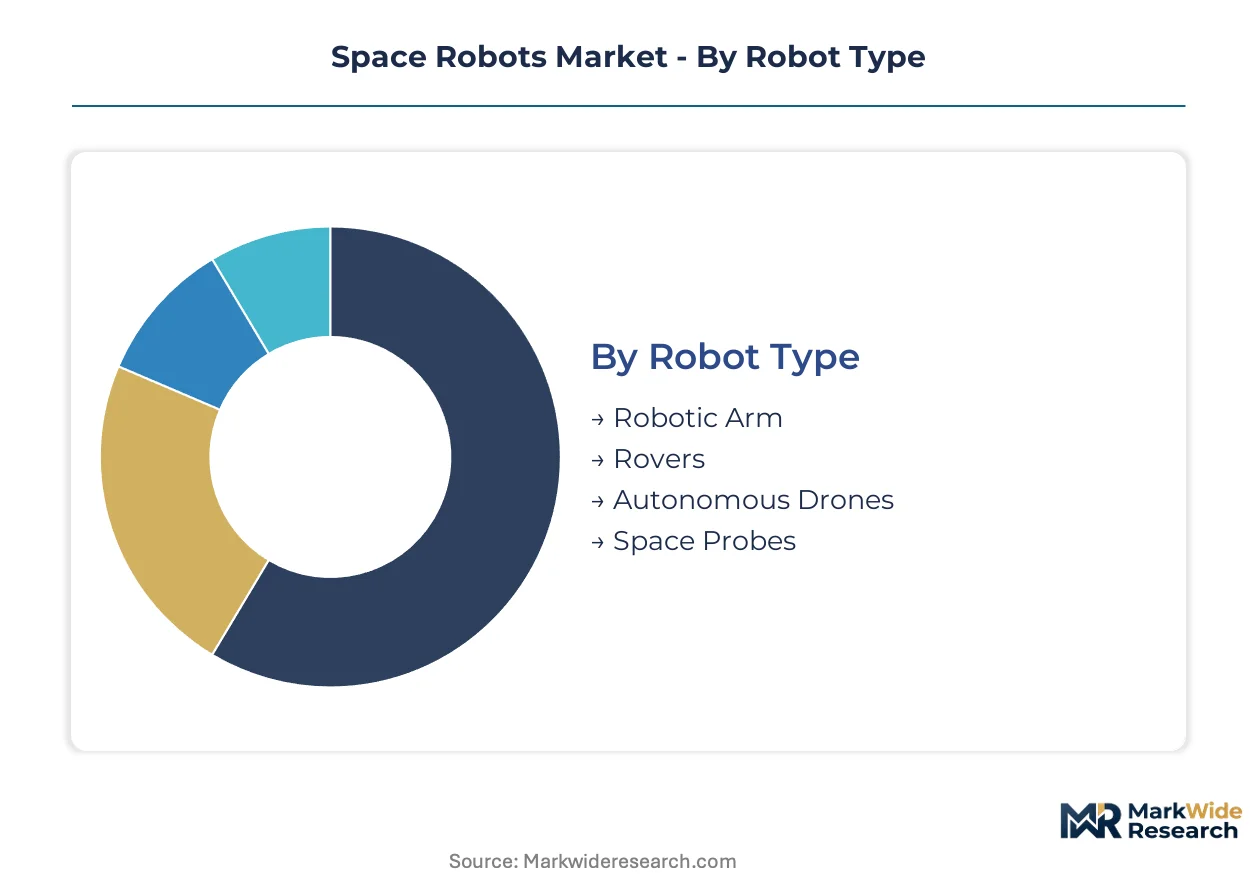
Segmentation in the space robots market reveals how procurement patterns split between established agency programs and emerging commercial constellations. Understanding these divides exposes where development capital concentrates and which technical specifications dominate contract requirements.
Robot Type:
Margin pools concentrate in systems with proven flight heritage and radiation-hardened component supply chains.
- Robotic Arm:These electromechanical systems integrate redundant actuation with force-feedback manipulation for payload handling and infrastructure assembly. NASA's Artemis program and ESA's lunar exploration roadmap anchor procurement volumes in the United States and European member states, where long-cycle development contracts sustain prime contractor revenues.
- Autonomous Drones:Compact propulsion platforms with machine vision navigation execute proximity operations for satellite servicing and debris removal missions. Commercial operators in the United States demand demonstration of autonomous rendezvous capabilities before procurement commitment, compressing vendor qualification timelines.
- Rovers:Surface traversal systems with planetary sampling mechanisms occupy niche positions within exploration architectures.
- Space Probes:Deep-space platforms with extended mission durations require specialized thermal control substrates and qualified semiconductors.
Robotic Arm holds installed capacity. Autonomous Drones is rotating up the share rankings.
Functionality:
Application focus determines which subsystem suppliers qualify for integration into high-reliability mission architectures.
- Exploration:Regolith sampling, surface mapping, and scientific instrument deployment functions anchor near-term procurement volumes from civil space agencies. NASA's lunar exploration roadmap and ESA's Clean Space initiative generate sustained demand for planetary sampling mechanisms rated for vacuum environments.
- Construction:Autonomous assembly and infrastructure preparation for lunar base applications represent uncaptured demand beyond current exploration-focused procurement. Development capital is attracting to cislunar construction robotics as private lunar missions accelerate.
- Maintenance:In-orbit servicing and end-of-life removal functions respond to debris mitigation mandates from the Inter-Agency Space Debris Coordination Committee.
- Surveillance:Persistent monitoring capabilities for orbital platforms and research stations require electromagnetic compatibility with host avionics.
Exploration commands current program budgets. Construction is climbing the fastest as lunar preparation timelines compress.
End User:
Customer type dictates validation protocols and contract structure across procurement cycles.
- Aerospace Agencies:NASA, ESA, and ISRO impose multi-year qualification timelines with NASA technical standards governing materials selection and verification protocols. These civil agency contracts sustain long-cycle development of deep-space manipulation systems through classified and unclassified funding streams.
- Commercial Companies:SpaceX, Amazon's Project Kuiper, and satellite servicing ventures impose accelerated acceptance testing on robotic subsystem suppliers. FAA licensing requirements for commercial launch operations shape how developers validate flight heritage before orbital deployment.
- Research Institutions:Academic and laboratory procurement focuses on technology demonstration missions with reduced reliability requirements.
- Military:Classified programs fund specialized capabilities with restricted supply chain visibility.
Aerospace Agencies hold established procurement pipelines. Commercial Companies is gaining share fastest as constellation deployment scales.
Deployment Mode:
Operational environment constrains thermal control, radiation tolerance, and autonomy requirements.
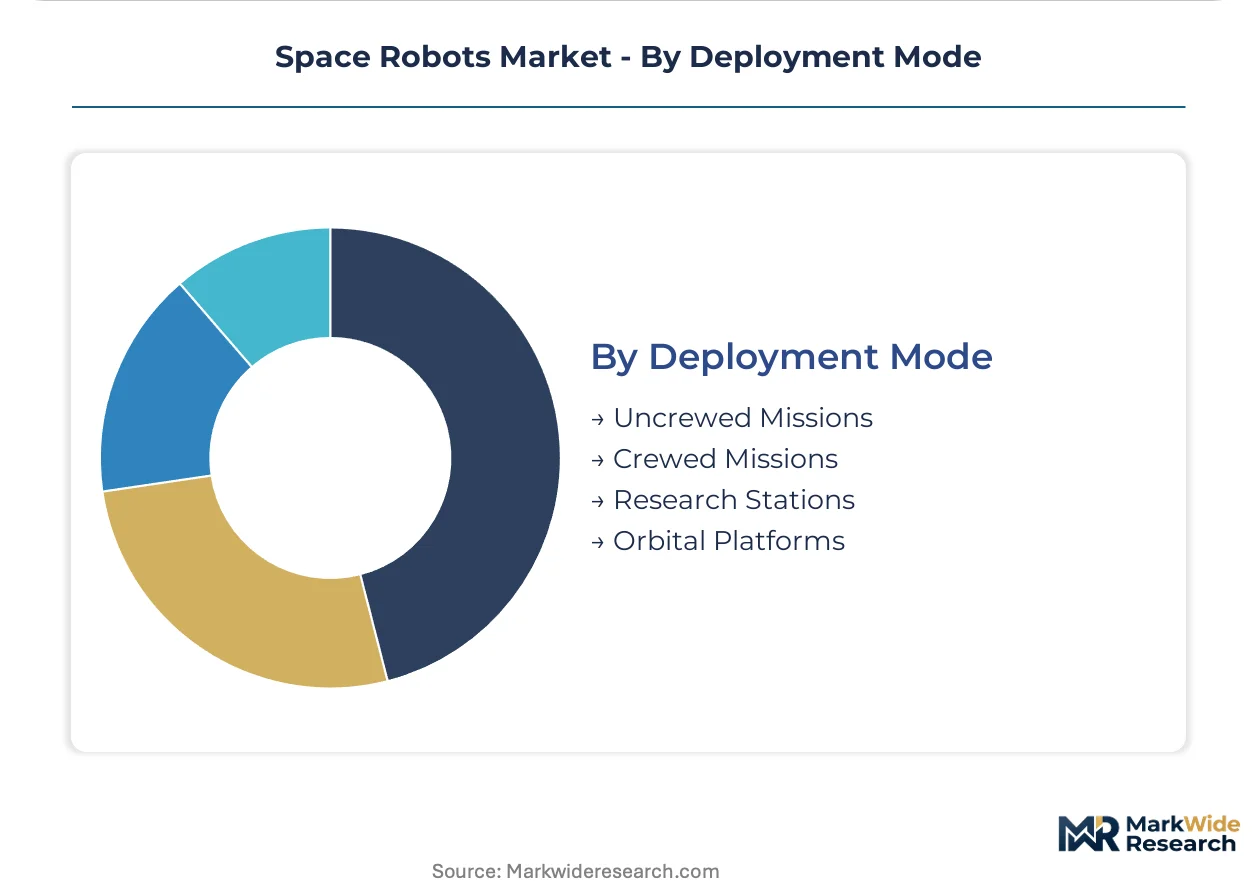
- Uncrewed Missions:Fully autonomous systems with machine vision and force-feedback manipulation execute proximity operations without human intervention. Satellite servicing and debris removal missions multiply demand for these architectures as operators fund end-of-life removal robotics.
- Orbital Platforms:Persistent presence in low Earth orbit and cislunar space requires radiation-hardened processors and redundant actuation rated for extended vacuum exposure.
- Crewed Missions:Human-rated systems with telerobotic interfaces support astronaut activities on lunar surface and orbital outposts.
- Research Stations:Fixed-base installations with modular robotic architectures enable rapid reconfiguration between servicing, assembly, and exploration functions.
Uncrewed Missions dominates current revenue flows. Orbital Platforms is expanding most quickly as satellite servicing commercializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes space robots predominantly through commercial constellation operators demanding accelerated qualification cycles, while European procurement flows through civil agency channels with extended validation timelines. This consumption-mix differential shapes how vendors configure product development investments across geographies.
United States
NASA's Artemis program and SpaceX's satellite servicing initiatives drive demand for autonomous manipulation systems. FAA commercial launch licensing requirements constrain how developers validate flight heritage before orbital deployment. Houston and Denver anchor concentrated engineering clusters where prime contractors sustain long-cycle development programs.
Germany
ESA supply chain eligibility requirements accelerate adoption of REACH-compliant thermal control substrates among component manufacturers. The country's national space agency channels procurement through standardized verification protocols. Bavaria hosts specialized engineering centers focused on planetary sampling mechanisms for lunar exploration architectures.
Japan
METI industrial policy supports domestic capability in radiation-hardened processors and redundant actuation systems. JIS standards govern materials selection for agency-funded missions. Tokyo and Nagoya metropolitan areas concentrate robotics engineering talent serving both civil and commercial satellite operators.
India
ISRO's commercialization push creates entry pathways for component suppliers aligning with BIS standards. The country's national space program generates demand for cost-optimized surface traversal systems. Bengaluru and Hyderabad host emerging clusters where startups develop proximity operation technologies for uncrewed missions.
United Kingdom
UK Space Agency funding priorities emphasize in-orbit servicing and debris removal capabilities. National regulations align with Inter-Agency Space Debris Coordination Committee guidelines constraining end-of-life mission designs. Harwell and Glasgow anchor satellite manufacturing clusters where robotics specialists integrate with platform avionics suppliers.
Space Robots Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the space robots market. Prime contractors with classified and civil agency contracts sustain long-cycle development programs for deep-space manipulation systems. Emerging players compress timelines through rapid iteration protocols and modular architectures. Dominant competitive moves include strategic partnerships with launch providers to inherit flight heritage and portfolio diversification into cislunar construction applications.
Among United States-based integrated primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the established tier sustaining revenues through multi-year agency contracts. SpaceX represents the commercial vector where rapid iteration protocols displace traditional validation models. These three anchors illustrate how vendor positioning splits between civil agency dependency and constellation operator acceleration.
| Leading Market Players |
|---|
| SpaceX |
| Honeybee Robotics |
| Lockheed Martin Corporation |
| Astrobotic Technology |
| MDA Space |
| Airbus SE |
| Oceaneering International |
| Redwire LLC |
| Northrop Grumman Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with NASA and ESA anchor procurement visibility for radiation-hardened component suppliers, locking in foundry capacity years ahead of mission deployment while insulating prime contractors from spot-market volatility in qualified semiconductor supply. These contract structures concentrate pricing power among established vendors with flight heritage, forcing new entrants to absorb premium spot pricing for thermal-vacuum chamber access and subcontracted integration services.
Pricing Analysis
Project-based contracting dominates civil agency procurement, with NASA technical standards and ESA verification protocols creating three-tier pricing stratification across mission-critical, flight-qualified, and research-grade certification levels. Price differentiation hinges on radiation-hardening grade and thermal control substrate compliance with REACH and NASA outgassing requirements. Cost compression in research-grade subsystems is intensifying because constellation operators like SpaceX and Amazon's Project Kuiper impose accelerated acceptance testing that bypasses traditional multi-year validation. Commercial satellite operators exhibit highest price sensitivity, while classified military programs demonstrate lowest sensitivity due to mission-critical reliability mandates.
Supply Chain Analysis
Foundry capacity for radiation-hardened processors in the United States, France, and Japan anchors supply security for deep-space compute modules, with single-source vulnerability concentrated in specialized thermal-vacuum chamber networks serving qualification protocols. Raw material dependencies center on high-purity aluminum alloys, polyimide substrates, and qualified semiconductor wafers. Supply chain risk manifests as logistics chokepoint exposure through limited orbital deployment provider schedules, where dependence on SpaceX and select international launch operators creates scheduling vulnerability for demonstration missions. Distribution runs through prime contractor integration facilities in Houston, Denver, and Bavaria before downstream delivery to agency payload integration sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as procurement bifurcates between accelerated commercial qualification cycles and extended agency validation timelines, creating distinct vendor tiers serving incompatible buyer archetypes with divergent technical requirements.
For Market Incumbents: Compound flight heritage advantages through captive supply of radiation-hardened processor capacity and backward integration into thermal control substrate manufacturing. Lockheed Martin Corporation and Northrop Grumman Corporation should extend long-cycle development contracts into cislunar construction robotics before emerging players establish modular architecture standards. Threat substitution from rapid-iteration commercial protocols demands certification investment in FAA collision avoidance algorithm validation to maintain agency channel control. For New Entrants and Emerging Players: Differentiate on autonomous rendezvous software stacks targeting satellite servicing ventures unable to absorb prime contractor pricing. The most penetrable white space sits in India's ISRO commercialization pathway, where BIS standards alignment creates entry routes for cost-optimized proximity operation technologies. Target research institution technology demonstration missions as beachhead applications with reduced reliability barriers, then ladder into commercial constellation supplier qualification through inherited flight heritage partnerships with established launch providers. For Investors and Strategic Acquirers: Specialist autonomy software developers with machine vision and force-feedback integration capabilities represent the highest-conviction acquisition archetype as AI-enabled manipulation converges with orbital servicing demand. Long-term viability across the analysis window depends on positioning upstream of modular robotic architecture standardization. The signal to watch is FAA licensing timeline compression for autonomous rendezvous systems, which would validate commercial qualification model displacement and revalue software-centric entrants against hardware-integrated primes.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Robotic Architecture Standardization | Reduces non-recurring engineering costs for NASA Artemis infrastructure deployment missions. |
| Autonomous Rendezvous Software Development | Enables satellite servicing ventures to meet FAA collision avoidance validation requirements. |
| Radiation-Hardened Processor Supply Agreement | Secures foundry capacity for deep-space compute modules against semiconductor shortage exposure. |
| REACH-Compliant Thermal Substrate Manufacturing | Maintains ESA supply chain eligibility for European lunar exploration roadmap procurement. |
| Cislunar Construction Robotics Investment | Captures uncaptured demand for autonomous assembly systems beyond exploration-focused budgets. |
Research Methodology
A standing panel of satellite servicing venture CTOs, NASA mission systems engineers, ESA procurement leads, and radiation-hardened component foundry operations directors provided ongoing calibration across primary interview cycles. Secondary validation drew from NASA technical standards documentation, ESA Clean Space initiative guidelines, FAA commercial launch licensing records, and Inter-Agency Space Debris Coordination Committee mitigation protocols. Bottom-up segmentation modeling triangulated against top-down civil agency budget appropriations and commercial constellation operator capex disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework disaggregation by robot type, functionality, end user, and deployment mode. Cislunar construction readiness timelines and autonomous proximity operation technology maturation curves served as industry-specific forecast inputs. CAGRs were derived through regression analysis of historical procurement patterns and projected mission cadence acceleration.
Material uncertainties — foundry capacity constraints, launch integration bottlenecks, and regulatory timeline compression — sit outside the modeled envelope and could revise trajectory assumptions. Practitioners should keep alternative scenarios live as FAA licensing protocols and debris mitigation mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Lander and Rover Market
Space
Space Rover Market
Space
Space Mining Market
Space
UK Space Propulsion System Market
Space
UK Space Electronics Market
Space
Space Debris Monitoring and Removal Market
Space
Spacecraft Market
Space
South Korea Space Electronics Market
Space
Suborbital Space Tourism Market
Space
Space Travel Market
Space
Deep Space Robotics Market
Space
Rocket Launchpad Market
Space
Space Transportation Market
Space
Deep Space Exploration Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space As a Service Market