
 Space Lander and Rover Market | 2026-2036
Space Lander and Rover Market Size, Share, and Industry Trends Forecast 2026-2036
Space Lander and Rover Market Outlook
The capital-intensity divergence between legacy defense primes and venture-backed newcomers is reorganizing competitive tiers in lunar logistics. Lockheed Martin Corporation leverages decades of deep-space heritage to sustain cost-plus contracting dominance for flagship NASA missions. Intuitive Machines competes on fixed-price lunar delivery timelines, while ispace, inc. anchors its position through iterative small-lander development cycles in Japan and beyond.
Space landers and rovers constitute precision aerospace vehicles engineered for controlled descent, surface mobility, and instrument deployment on extraterrestrial bodies, typically incorporating propulsive landing systems, terrain-relative navigation, and radiation-hardened avionics rated for vacuum thermal cycling. Their primary purpose spans scientific data collection, in-situ resource verification, and technology demonstration for sustained human presence. Lunar Lander configurations currently occupy the largest share of near-term procurement budgets given Artemis and Chinese lunar program timelines, while Sample Return Vehicle architectures represent the fastest-growing technology branch as Mars sample retrieval and asteroid mining concepts mature. Autonomous Navigation systems concentrate margin pools due to software validation costs and limited supplier bases for certifiable hazard detection algorithms.
NASA's FAA-licensed commercial lunar payload services framework and the FCC's spectrum coordination rules for lunar communications jointly shape market access conditions for private operators. China's SAMR certification pathways for space-grade components and the EU's REACH material compliance standards for propulsion chemicals add cross-border complexity to supply qualification. Stakeholders must monitor how national security export controls on precision landing sensors fragment vendor eligibility across mission portfolios.
Market Dynamics
Fixed-price contracting mandates from NASA's CLPS program are compressing mission margins and forcing hardware suppliers to absorb technical risk previously borne by government agencies, fundamentally restructuring capital allocation across lunar logistics value chains.
Growth Catalysts
- Artemis Program Procurement:NASA's commercial lunar payload services framework guarantees minimum order volumes for qualified lander vendors, creating predictable revenue streams for precision landing system developers.
- China's CNSA Roadmap:Beijing's lunar base construction timeline anchors state-funded demand for heavy-class landers and long-duration rovers through 2035.
- In-Situ Resource Utilization:Water-ice extraction demonstration missions validate propellant depot architectures, opening recurring service contracts for cryogenic handling equipment.
Market Restraints
- Radiation-Hardened Electronics Supply:Qualified foundry capacity concentrates among three US and European semiconductor fabricators, creating single-source vulnerability for avionics subsystems.
- Propulsion Chemical Compliance:EU REACH restrictions on hydrazine derivatives force reformulation of monopropellant thrusters, extending qualification timelines by 18-24 months.
- Launch Cost Volatility:Ride-share pricing for lunar transfer orbits fluctuates with geostationary satellite demand, complicating mission budget certainty for fixed-price contractors.
Strategic Opportunities
- Martian Sample Return Architecture:ESA-NASA joint missions require ascent vehicles and orbital transfer systems not yet commercially available, creating first-mover advantage for capable developers.
- UAE Space Agency Partnerships:Abu Dhabi's Emirates Lunar Mission anchors procurement for compact rover platforms, offering entry point for mid-scale hardware vendors.
- Optical Navigation Convergence:Fusion of lidar terrain mapping with machine vision hazard detection enables precision landing without ground infrastructure, reducing mission-critical mass allocations.
Industry Challenges
- GNC Talent Scarcity:Guidance, navigation and control engineering expertise pools thinly across legacy aerospace and autonomous vehicle sectors, inflating compensation premiums for lunar-qualified specialists.
- Environmental Test Bottlenecks:Thermal-vacuum chamber availability limits parallel qualification campaigns, forcing serial hardware validation and compressing mission integration schedules.
- ITAR Classification Complexity:US State Department jurisdiction over precision landing sensors fragments vendor eligibility for international consortium missions, requiring parallel supply chain configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Lander and Rover Market |
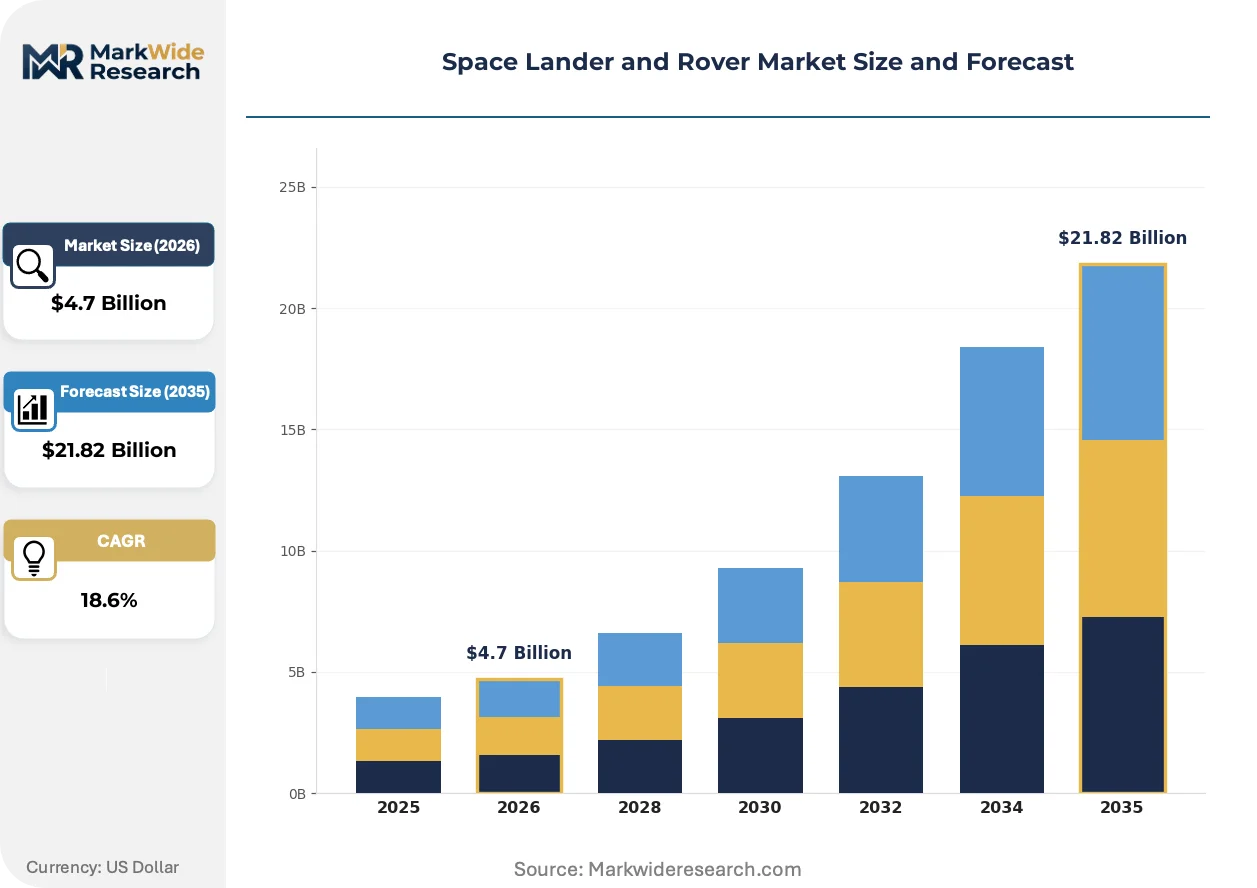
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lunar Lander, Mars Rover, Planetary Explorer, Sample Return Vehicle Technology: Autonomous Navigation, Solar Power, Communication Systems, Robotics Application: Scientific Research, Resource Exploration, Planetary Defense, Commercial Payload Delivery End User: Government Space Agencies, Private Aerospace Companies, Research Institutions, Educational Organizations |
| Companies Covered | Roscosmos, Northrop Grumman Corporation, ISRO, ispace, inc., Astrobotic Technology, Inc, Airbus SE, Lockheed Martin Corporation, Intuitive Machines, Blue Origin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Lander and Rover Market Strategic Shifts
Autonomous surface operations are displacing Earth-in-the-loop command architectures, compressing decision latency from minutes to seconds and enabling missions in communication-denied terrain previously inaccessible to teleoperated systems.
Hazard detection lidar is fragmenting traditional terrain-relative navigation market structures. These active ranging systems generate real-time digital elevation maps during powered descent, enabling landing site redesignation within final approach phases. NASA's Human Landing System program mandates this capability for crewed missions, forcing subsystem suppliers to absorb software validation costs previously externalized to mission operators. The technology is fragmenting established avionics procurement patterns by bundling sensing and decision logic into unified packages.
REACH chemical authorization timelines are reshaping European propulsion supply chains. ECHA's restriction roadmap for carcinogenic propellants forces thruster manufacturers to qualify green alternatives like ammonium dinitramide formulations, extending development budgets and compressing competitive windows for lunar mission bids. Hardware vendors with advance ADN testing programs capture ESA science mission allocations that hydrazine-dependent competitors forfeit.
Fixed-price milestone payments are displacing cost-plus reimbursement for lunar delivery services. NASA's CLPS task orders now tie 60-70% of contract value to successful surface operations rather than development expenditure, transferring performance risk to private operators. This compression of payment schedules concentrates financial exposure among venture-backed newcomers without prime contractor balance sheet depth, favoring entities with diversified revenue streams or strategic investor backing. The shift is most visible in US procurement, where Astrobotic and Intuitive Machines compete against heritage cost-plus incumbents.
Space Lander and Rover Market Segmentation
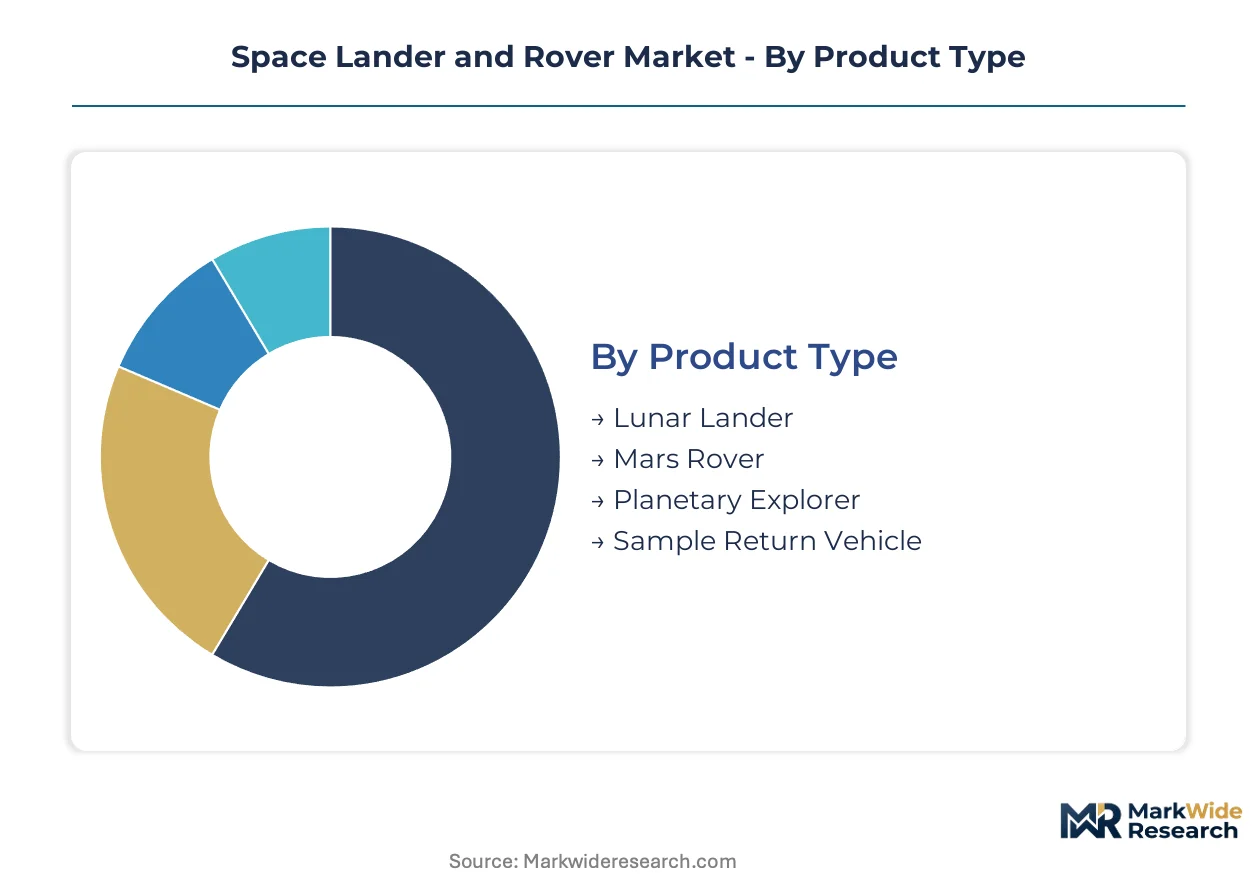
Segmentation in the space lander and rover market reveals how procurement priorities diverge across mission architectures. NASA's Artemis timeline and China's lunar base roadmap concentrate demand in distinct product configurations, while technology maturation cycles reshape vendor qualification pathways.
Product Type:
FAA licensing requirements for lunar payload services and SAMR certification pathways in China create divergent hardware qualification burdens across vehicle classes.
- Lunar Lander:Heavy-class descent vehicles incorporate propulsive landing systems and terrain-relative navigation rated for vacuum thermal cycling. NASA's CLPS program and CNSA's moon base construction anchor procurement volumes in the United States and China.
- Mars Rover:Long-duration surface mobility platforms integrate radiation-hardened avionics and autonomous traverse algorithms. ESA-NASA joint missions and Emirates Lunar Mission extensions concentrate demand in European and Middle Eastern science portfolios.
- Planetary Explorer:Multi-mission architectures designed for asteroid or outer-planet reconnaissance.
- Sample Return Vehicle:Ascent vehicles and orbital transfer systems enabling Mars sample retrieval; climbing the fastest as architecture concepts mature.
Established volume favors Lunar Lander; emerging adoption favors Sample Return Vehicle.
Technology:
Mission-critical margins concentrate in software validation costs for certifiable systems, with supplier scarcity driving tiered pricing across capability levels.
- Autonomous Navigation:Guidance, navigation and control systems fuse lidar terrain mapping with machine vision hazard detection. Limited pools of lunar-qualified GNC specialists inflate compensation premiums across Lockheed Martin and Intuitive Machines supply chains.
- Solar Power:Photovoltaic arrays and regenerative fuel cells rated for extreme thermal cycling and dust accumulation.
- Communication Systems:Spectrum coordination under FCC rules and ITU frameworks for lunar link architectures.
- Robotics:Manipulator arms and in-situ instrument deployment mechanisms; expanding most quickly with ISRU demonstration missions.
Current procurement prioritizes Autonomous Navigation; qualification bottlenecks favor Robotics for second-source strategies.
Application:
Customer risk tolerance varies sharply across mission objectives, with fixed-price contracting penetrating commercial payload delivery while cost-plus persists for crew-rated systems.
- Scientific Research:Instrument packages for geologic and atmospheric data collection. NASA's Science Mission Directorate and ESA's Cosmic Vision program anchor funding pipelines in the United States and Europe.
- Resource Exploration:Water-ice extraction and regolith characterization payloads validating propellant depot architectures.
- Planetary Defense:Asteroid deflection demonstration and impact monitoring systems.
- Commercial Payload Delivery:Private customer missions under FAA-licensed frameworks; steepest expansion trajectory as Astrobotic and Intuitive Machines scale operations.
Institutional funding dominates Scientific Research; venture deployment accelerates Commercial Payload Delivery.
End User:
Balance sheet depth determines contracting structure eligibility, separating prime contractor heritage from fixed-price newcomer exposure.
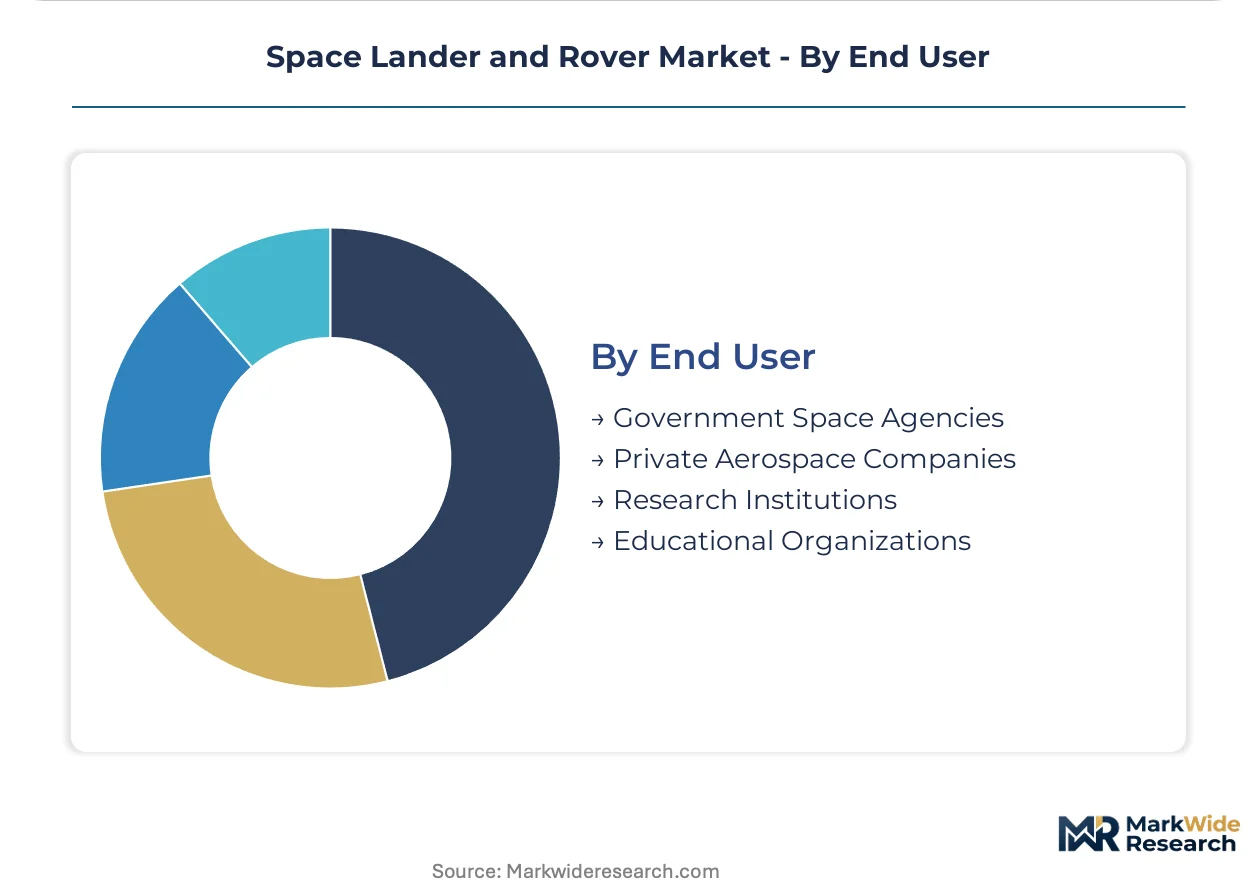
- Government Space Agencies:NASA, CNSA, ESA, and UAE Space Agency procurement with sovereign guarantee backing. Artemis program minimum order volumes create predictable revenue streams for qualified vendors.
- Private Aerospace Companies:Venture-backed operators absorbing performance risk under milestone-based payments.
- Research Institutions:University-led instrument development with limited integration responsibility.
- Educational Organizations:CubeSat-class technology demonstration missions with constrained procurement authority.
Sovereign procurement concentrates in Government Space Agencies; capability demonstration favors Private Aerospace Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and China exhibit low price elasticity given sovereign-backed procurement pipelines, while venture-funded operators in Japan and the UAE face acute margin compression under fixed-price milestone structures. Demand concentration tracks Artemis program minimum order volumes and CNSA's lunar base construction timeline.
United States
NASA's CLPS framework guarantees predictable revenue streams for qualified lander vendors through minimum order volumes. FAA licensing requirements for commercial lunar payload services shape market access conditions for private operators. Houston and the Pacific Northwest host concentrated precision landing system development clusters where Astrobotic and Intuitive Machines compete against heritage cost-plus incumbents.
China
CNSA's moon base construction timeline anchors state-funded demand for heavy-class landers through 2035. SAMR certification pathways for space-grade components add cross-border complexity to supply qualification for international consortium missions. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate state-owned enterprise manufacturing for lunar infrastructure programs.
Japan
METI-backed iterative small-lander development cycles anchor ispace's position in commercial lunar delivery. JIS standards and national space legislation shape component qualification burdens for domestic vendors. Tokyo-Yokohama and Nagoya industrial corridors concentrate robotics and autonomous navigation engineering talent pools for precision landing systems.
United Arab Emirates
Abu Dhabi's Emirates Lunar Mission anchors procurement for compact rover platforms with constrained budget envelopes. MOHAP and UAE Space Agency partnerships create entry points for mid-scale hardware vendors seeking sovereign-backed reference contracts. Dubai's technology investment clusters channel capital toward optical navigation and machine vision hazard detection capabilities.
France
ESA-NASA joint missions for Martian sample return concentrate demand for ascent vehicles and orbital transfer systems. ECHA REACH restrictions on hydrazine derivatives force thruster manufacturers to qualify green alternatives, extending qualification timelines. Toulouse and Paris-Saclay clusters host Airbus SE operations and autonomous navigation software validation centers for lunar-qualified GNC systems.
Space Lander and Rover Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in lunar logistics contracting. Heritage defense primes leverage decades of deep-space heritage to sustain cost-plus dominance for flagship government missions, while venture-backed newcomers absorb performance risk under fixed-price milestone payments. Three archetypes define competitive positioning: sovereign-backed system integrators, commercial fixed-price operators, and component specialists with radiation-hardened electronics or propulsion expertise. Consolidation pressures concentrate around autonomous navigation software validation costs and limited thermal-vacuum chamber availability for parallel qualification campaigns.
Within the sovereign-integrated tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify cost-plus contracting structures for crew-rated systems. Among commercial fixed-price operators, Intuitive Machines and Astrobotic Technology, Inc occupy positions competing on lunar delivery timelines under NASA milestone frameworks. Japanese venture ispace, inc represents the iterative small-lander development archetype with METI-backed cycles targeting iterative mission architectures.
| Leading Market Players |
|---|
| Roscosmos |
| Northrop Grumman Corporation |
| ISRO |
| ispace, inc. |
| Astrobotic Technology, Inc |
| Airbus SE |
| Lockheed Martin Corporation |
| Intuitive Machines |
| Blue Origin |
| Others |
Value Chain & Pricing Dynamics
Fixed-price milestone payments lock in supply access for radiation-hardened electronics while capping price visibility for lunar lander developers absorbing technical risk under NASA CLPS terms. This contracting structure concentrates financial exposure among venture-backed operators without prime contractor balance sheet depth, forcing supply chain choices that trade qualification speed against unit cost.
Pricing Analysis
After-sales service contracts for thermal-vacuum chamber access and GNC software validation drive lifetime value beyond initial hardware delivery. Three-tier pricing structure across heritage cost-plus, commercial fixed-price, and iterative small-lander development separates Lockheed Martin from Intuitive Machines from ispace procurement models. Cost compression in fixed-price tiers is intensifying because NASA ties 60-70% of contract value to successful surface operations. Government space agencies exhibit lowest price sensitivity given sovereign guarantee backing, while venture-funded newcomers face acute margin pressure.
Supply Chain Analysis
Extended lead times for qualified foundry capacity in radiation-hardened electronics concentrate inventory risk among three US and European semiconductor fabricators. Supply draws from United States, Germany, and Japan for avionics subsystems, with propulsion chemicals sourced from France and China. Single-source vulnerability in ITAR-classified precision landing sensors fragments vendor eligibility for international consortium missions. Distribution runs through prime contractor integration facilities in Houston, Toulouse, and Beijing-Tianjin-Hebei clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution defense against terrestrial autonomous navigation systems repurposed for space applications, threatening incumbent GNC software margins as automotive lidar suppliers cross over.
For Market Incumbents: Secure captive supply of radiation-hardened foundry capacity through long-term offtake agreements with BAE Systems or Honeywell Aerospace semiconductor divisions. Lock in thermal-vacuum chamber reservation blocks to compress parallel qualification timelines against Astrobotic and Intuitive Machines. For New Entrants and Emerging Players: Lead with optical navigation convergence offerings that bypass ITAR-classified sensor dependencies for ESA and UAE Space Agency missions. The most penetrable white space sits in compact rover platforms for Emirates Lunar Mission extensions, with machine vision hazard detection as the entry angle. For Investors and Strategic Acquirers: Capital is best deployed toward autonomous navigation software specialists with certifiable lidar fusion algorithms and existing ESA validation relationships. The signal to watch is ECHA REACH authorization timelines for ammonium dinitramide propellants, which will determine which thruster manufacturers capture ESA science mission allocations.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Radiation-Hardened Electronics | Captures foundry margin pools concentrated among three US and European suppliers. |
| Green Propellant Qualification Program | Positions vendors ahead of ECHA REACH restrictions on hydrazine derivatives. |
| Optical Navigation Software Certification | Enables precision landing without ground infrastructure under NASA Human Landing System mandates. |
| Fixed-Price Milestone Structuring | Aligns contractor incentives with surface operation success under CLPS task orders. |
| International Consortium Supply Configuration | Fragments ITAR exposure across parallel vendor networks for non-US mission participation. |
Study Parameters
A standing panel of GNC engineering directors, thermal-vacuum facility operators, ESA procurement leads, and FAA commercial space licensing officers provided ongoing calibration across primary interview cycles. Secondary validation drew from NASA contract announcements, ESA Cosmic Vision program documents, FCC spectrum coordination filings, and SAMR certification pathway disclosures. Bottom-up lander unit economics and top-down sovereign budget appropriations were triangulated against vendor revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product type, technology tier, application mission objective, and end-user balance sheet depth as segmentation dimensions. CAGRs were derived from year-over-year procurement pipeline analysis incorporating Artemis program minimum order volumes and CNSA lunar base construction timelines.
Forecasts assume regulatory continuity in FAA commercial launch licensing, ECHA REACH chemical authorization, and ITAR State Department jurisdiction; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Mining Market
Space
Space Ground System Market
Space
Space Semiconductor Market
Space
Space Traffic Management Market
Space
Space Tourism Market
Space
Space Rover Market
Space
Asia-Pacific Space Electronics Market
Space
Europe Space Electronics Market
Space
Mexico Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Frame Market
Space
Space Designing Market
Space
Space Battery Market
Space
Spacecraft Market
Space
North America Spacesuit Market
Space
Asia-Pacific Space Logistics Market