
 Space-Based C4ISR Market | 2026-2036
Space-Based C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Space-Based C4ISR Market Analytics
Defense agencies are redrawing procurement priorities toward persistent orbital awareness, displacing legacy airborne platforms in contested theaters. Lockheed Martin Corporation leverages classified satellite integration contracts across multiple security envelopes. Northrop Grumman Corporation sustains dominance in space-based radar payloads through captive sensor manufacturing. BAE Systems PLC anchors European sovereign capability with national Skynet derivative programs.
Space-Based C4ISR encompasses orbital platforms, ground processing architectures, and data-link networks that fuse command, control, communications, computers, intelligence, surveillance, and reconnaissance across distributed theaters, typically operating in LEO to GEO orbits with latency tolerances under 500 milliseconds for tactical applications. Satellites and RF Systems command the largest current revenue pools, while Hyperspectral imaging and Synthetic Aperture Radar represent the fastest-expanding technology segments as resolution and all-weather demands intensify. Commercial Entities within the End User dimension are emerging as a structural growth vector as remote sensing data commoditizes.
The US Space Force orbital warfare doctrine, FCC spectrum allocation proceedings for non-geostationary constellations, and NATO's emerging space as an operational domain framework collectively shape contractor design standards and market access conditions. ISO 27001 and IEC 61508 certifications increasingly gate eligibility for intelligence-community contracts. Stakeholders must monitor evolving encryption mandates and anti-jam resilience specifications as determinant variables for program viability.
Market Dynamics
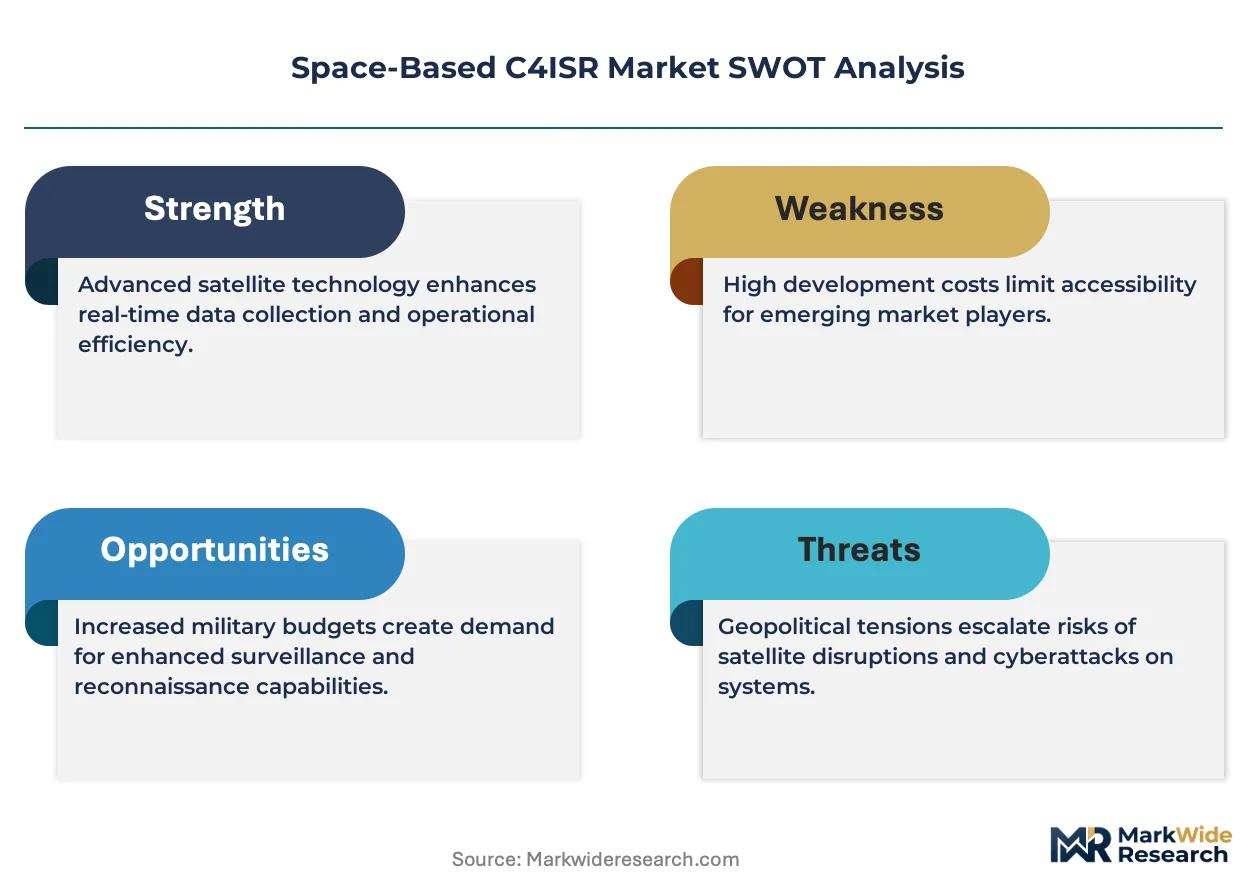
Orbital warfare doctrine from the US Space Force and China's dual carbon launch mandates are compressing procurement cycles while fragmenting supplier qualification requirements across security-cleared and commercial-grade production lines.
Growth Catalysts
- LEO Constellation Density:NATO's space-as-operational-domain framework accelerates sovereign satellite procurement for Indo-Pacific theater awareness.
- FCC Spectrum Reallocation:Non-geostationary constellation licensing proceedings unlock bandwidth for tactical data-link networks under 500-millisecond latency thresholds.
- Hyperspectral Resolution Gains:All-weather imaging demands from defense intelligence agencies pull synthetic aperture radar and hyperspectral payloads into accelerated development cycles.
Market Restraints
- Launch Cost Volatility:Propellant supply concentration and reusable vehicle certification timelines compress margin structures for constellation operators.
- Sensor Manufacturing Bottleneck:Captive radar payload production at dominant primes limits second-tier access to space-qualified component supply.
- ITAR Classification Friction:US State Department export controls fragment international program participation and extend foreign partner onboarding timelines.
Strategic Opportunities
- Commercial Remote Sensing Data:Commoditized Earth observation products create new revenue pools outside classified defense contracts.
- Ground Processing Architecture Disaggregation:Cloud-native mission control software enables mid-tier contractors to bypass legacy prime-dominated integration paths.
- ISO 27001 Certification Tailwind:Intelligence-community encryption mandates gate contract eligibility, favoring suppliers with pre-positioned cybersecurity credentials.
Industry Challenges
- Anti-Jam Resilience Specification Flux:Evolving electronic warfare threats force iterative hardware redesigns mid-program, compressing development schedules.
- Cleared Workforce Scarcity:Polygraph-qualified systems engineers and orbital mechanics specialists command premium compensation, inflating program labor costs.
- Legacy Ground System Integration:New satellite buses must interface with decades-old command architectures, multiplying interface verification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space-Based C4ISR Market |
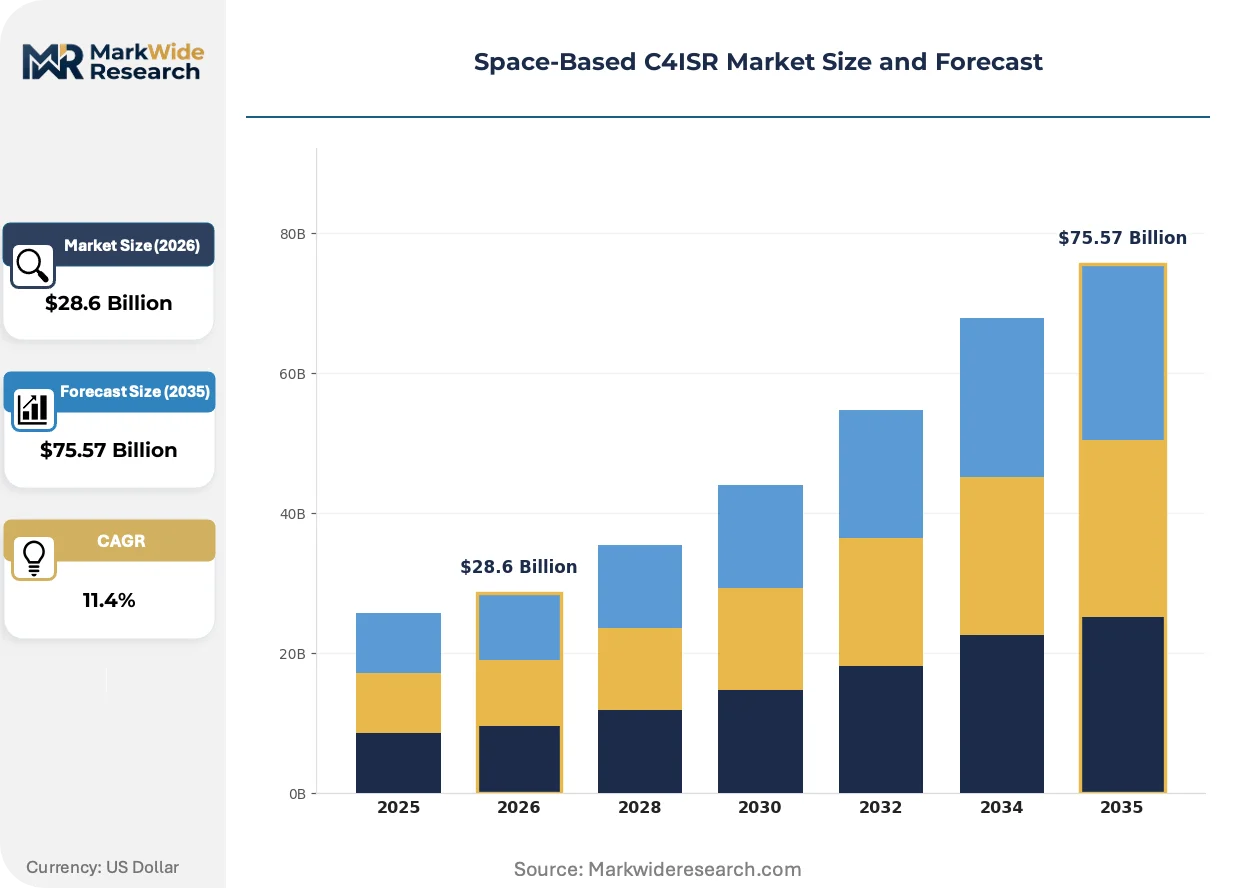
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Sensors, Ground Stations, Communication Systems Technology: Electro-Optical, Synthetic Aperture Radar, Hyperspectral, RF Systems End User: Defense, Intelligence Agencies, Homeland Security, Commercial Entities Application: Surveillance, Reconnaissance, Disaster Management, Environmental Monitoring |
| Companies Covered | BAE Systems PLC, Maxar Technologies Inc., Lockheed Martin Corporation, CACI International, Inc., Elbit Systems Ltd., Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space-Based C4ISR Market Evolving Landscape
Defense procurement patterns are splitting between classified orbital warfare programs and commercial-derived remote sensing platforms, with technology transfer restrictions determining which path contractors can access.
Small satellite bus standardization is bifurcating the supply base. CubeSat and microsatellite form factors now dominate LEO constellation bids for tactical applications. Defense primes with captive manufacturing adapt slowly, while commercial space vendors capture non-classified volume. This technology is compressing prime contractor margins on low-end missions while concentrating high-value payload integration at cleared facilities.
The FCC's accelerated NGSO licensing proceedings are reshaping constellation deployment economics. Spectrum coordination requirements now mandate inter-satellite link interoperability. Operators bidding for US defense contracts must demonstrate compliance with these allocation frameworks before program award, filtering out entrants without Washington regulatory presence.
Intelligence agencies now unbundle satellite tasking from data ownership. Commercial entities purchase raw orbital imagery directly, applying proprietary analytics rather than relying on government-processed products. This pattern concentrates in agriculture and maritime monitoring verticals, where buyers lack security clearance for classified sources.
Space-Based C4ISR Market Segmentation
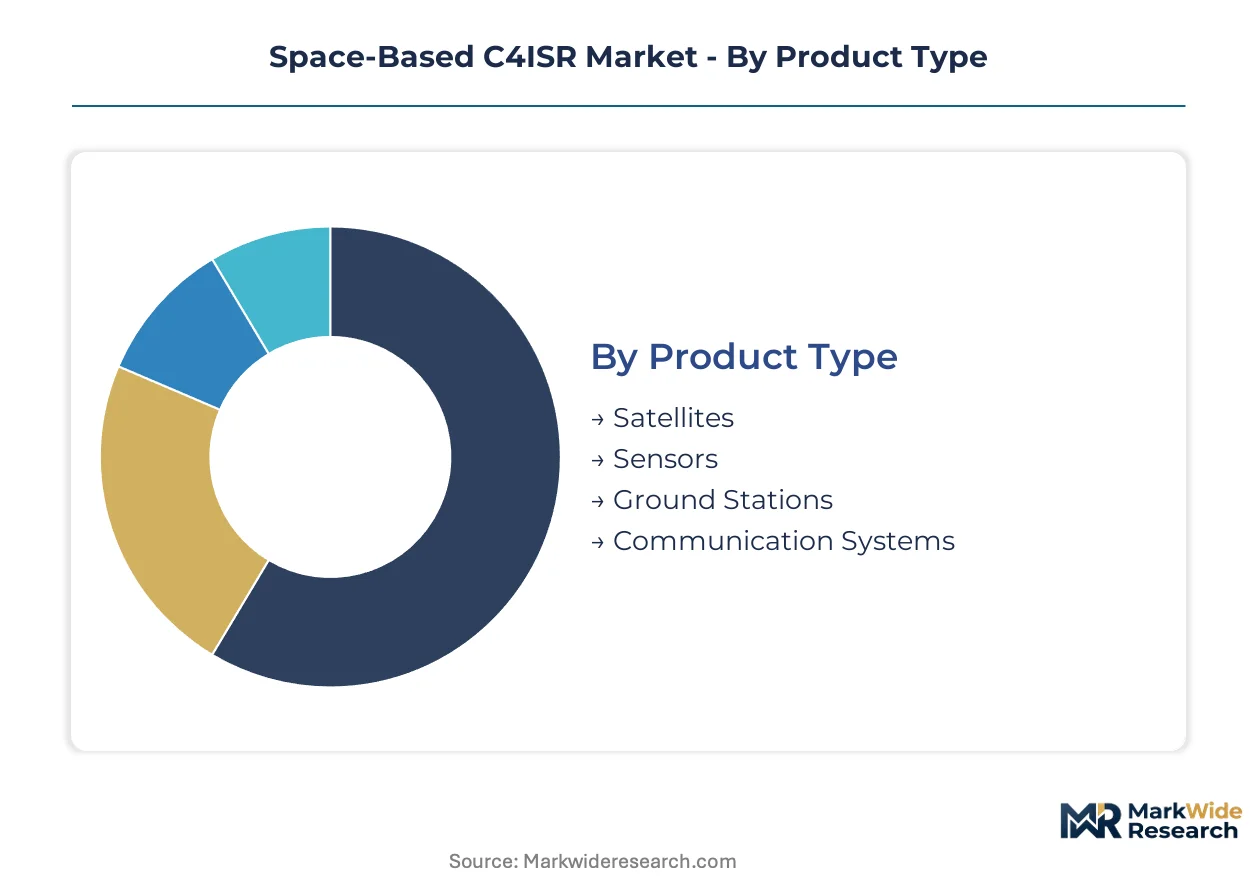
Space-Based C4ISR procurement splits across four distinct dimensions that determine contractor qualification paths and revenue capture. Product type governs hardware margins, while technology selection locks in payload performance ceilings. End user classification controls security clearance requirements, and application scope dictates orbital architecture design.
Product Type:
Satellites and Sensors concentrate margin pools through high-value payload integration and captive manufacturing capabilities at cleared facilities.
- Satellites:Orbital platforms span LEO to GEO configurations with standardized bus architectures now displacing custom designs. NATO members and the US Space Force drive procurement for Indo-Pacific theater awareness, compressing development cycles under orbital warfare doctrine mandates.
- Sensors:Payloads integrate electro-optical, radar, and hyperspectral instruments with resolution thresholds set by defense intelligence specifications. Captive production lines at dominant primes restrict second-tier access to space-qualified component supply, inflating procurement costs for non-integrated vendors.
- Ground Stations:Mission control architectures process telemetry and tasking commands with latency tolerances under 500 milliseconds for tactical applications.
- Communication Systems:Cross-link and downlink hardware enables distributed C4ISR networks across contested theaters.
The dominant share belongs to Satellites, while Sensors is closing the gap fastest through resolution and all-weather payload demands.
Technology:
Application requirements pull technology selection toward all-weather and multi-spectral capabilities that bypass atmospheric interference limitations.
- Synthetic Aperture Radar:Active microwave imaging penetrates cloud cover and darkness with resolution gains from advanced signal processing algorithms. Defense agencies across NATO member states accelerate SAR payload procurement for persistent Indo-Pacific surveillance where optical systems fail.
- Hyperspectral:Contiguous spectral band capture enables material identification beyond visible spectrum limitations, serving environmental monitoring and precision agriculture verticals. Commercial entities now purchase raw hyperspectral data directly, applying proprietary analytics outside classified government processing pipelines.
- Electro-Optical:Visible and infrared imaging remains cost-effective for fair-weather applications with established supply chains.
- RF Systems:Signal intelligence and communications relay payloads support electronic warfare and tactical data-link networks.
Synthetic Aperture Radar holds the installed base lead, though Hyperspectral is expanding most quickly through commercial remote sensing commoditization.
End User:
Security clearance requirements fragment the addressable market between classified defense contracts and commercial-grade procurement channels.
- Defense:Military service branches procure orbital architectures under national security envelopes with ITAR-controlled technology transfer restrictions. The US Space Force orbital warfare directives and NATO's space-as-operational-domain framework reshape contractor design standards and qualification requirements.
- Intelligence Agencies:National reconnaissance organizations task satellites and control data classification with encryption mandates gating contract eligibility through ISO 27001 certification requirements.
- Homeland Security:Border and maritime monitoring applications leverage commercial-derived platforms with lower security thresholds.
- Commercial Entities:Agriculture, insurance, and maritime operators purchase unprocessed orbital imagery directly, bypassing government analytics layers.
Defense commands the revenue concentration, while Commercial Entities is gaining share fastest as remote sensing data commoditizes outside classified channels.
Application:
Orbital tasking priorities split between military intelligence requirements and civil monitoring mandates with divergent resolution and revisit specifications.
- Surveillance:Persistent area monitoring for border security and strategic site observation demands high-revisit LEO constellations. FCC spectrum reallocation proceedings for non-geostationary constellations unlock bandwidth for tactical networks under latency thresholds critical for time-sensitive targeting.
- Reconnaissance:Target-specific data collection requires maneuverable satellites with rapid retasking capabilities against mobile threats. China's dual carbon-adjacent launch sustainability mandates and US Space Force orbital warfare directives compress procurement cycles while fragmenting supplier qualification paths.
- Disaster Management:Rapid response imaging supports humanitarian relief coordination with less stringent resolution requirements.
- Environmental Monitoring:Climate and agricultural observation leverages commercial platforms with standardized product delivery.
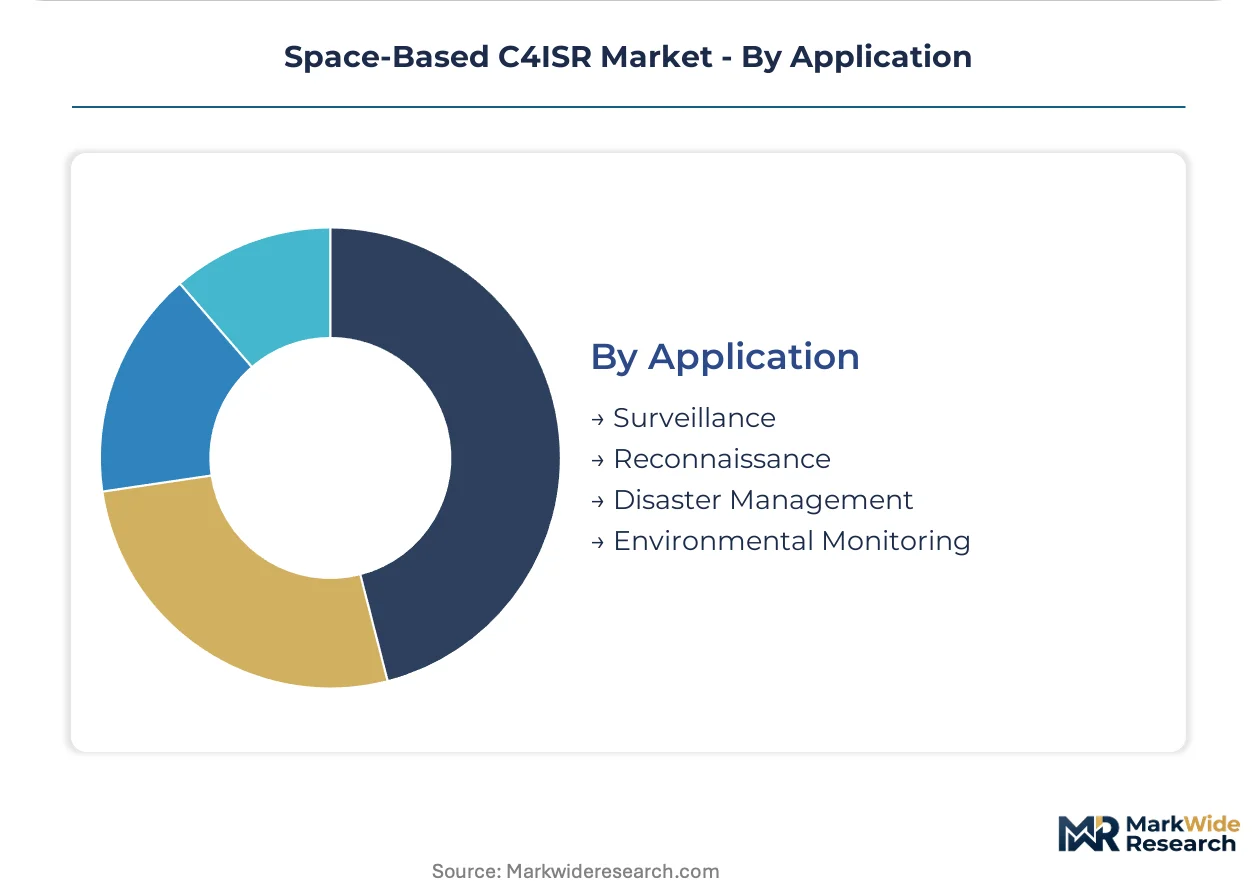
Surveillance maintains the procurement volume lead, though Reconnaissance is climbing the fastest through contested theater awareness demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vandenberg Space Force Base launch corridor underwrites United States dominance in orbital deployment capacity, anchoring Western C4ISR architecture buildout through polar trajectory access and classified payload processing facilities.
United States
US Space Force orbital warfare directives compress procurement cycles for LEO constellations serving Indo-Pacific theater awareness. FCC spectrum reallocation proceedings for non-geostationary constellations mandate inter-satellite link interoperability as a contract prerequisite. The Denver-Aurora aerospace corridor concentrates cleared payload integration facilities serving intelligence community encryption mandates.
China
Dual carbon-adjacent launch sustainability mandates reshape operator requirements toward reusable vehicle certification timelines. MIIT standards govern satellite manufacturing quality protocols for domestic constellation deployment. The Wenchang Satellite Launch Center on Hainan Island anchors southern launch capacity with sea-based recovery advantages for booster reusability programs.
United Kingdom
NATO's space-as-operational-domain framework accelerates sovereign Skynet derivative procurement for secure military communications. UK Space Agency licensing requirements filter commercial operator eligibility through national security assessments. The Harwell Space Cluster in Oxfordshire concentrates satellite bus manufacturing and ground segment engineering for European defense contracts.
Germany
Bundeswehr satellite communications modernization drives SAR payload demand for all-weather reconnaissance against mobile threats. German Aerospace Center (DLR) funding programs prioritize hyperspectral instrument development for dual-use environmental monitoring. The Munich-Ottobrunn aerospace corridor hosts radar payload engineering centers serving NATO interoperability specifications.
Japan
Japan Aerospace Exploration Agency (JAXA) Quasi-Zenith Satellite System expansion supports regional positioning and messaging for defense applications. METI technology roadmaps guide commercial remote sensing platform development outside classified channels. The Tanegashima Space Center anchors domestic launch autonomy with H3 vehicle deployment for government and commercial payloads.
Space-Based C4ISR Market Competitive Landscape
Concentration sits with defense primes possessing cleared manufacturing facilities and captive sensor production lines. The vendor base splits between classified orbital warfare integrators and commercial-derived platform specialists. Two archetypes dominate: vertically integrated primes controlling payload-to-bus integration, and ground segment software vendors disaggregating mission control architectures. Competitive moves center on cybersecurity certification pre-positioning and spectrum licensing regulatory capture.
Within the cleared prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify integrated payload-to-orbit capability. BAE Systems PLC anchors European sovereign positioning through national security-cleared facilities. Among ground architecture specialists, L3Harris Technologies, Inc. and RTX Corporation occupy positions in cross-link and downlink hardware for contested theater networks. Maxar Technologies Inc. represents the commercial-to-defense bridge archetype, supplying unprocessed imagery outside classified government processing pipelines.
| Leading Market Players |
|---|
| BAE Systems PLC |
| Maxar Technologies Inc. |
| Lockheed Martin Corporation |
| CACI International, Inc. |
| Elbit Systems Ltd. |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| L3Harris Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Launch vehicle reusability scale economies at Vandenberg and Cape Canaveral compress unit deployment costs while concentrating price-setting power among cleared payload integrators with captive manufacturing. This scale dynamic elevates price floors for non-integrated vendors seeking access to intelligence-community contracts.
Pricing Analysis
Volume-discount tiering structures separate prime contractor direct awards from commercial constellation batch procurement. Three-tier pricing stratifies across ITAR-controlled integration, NATO-cleared subsystems, and commercial-grade bus components. Cost compression in commercial-grade tiers intensifies because SpaceX reusability and Chinese Long March alternatives expand launch slot availability. Intelligence agencies exhibit lowest price sensitivity given mission-critical encryption mandates, while agricultural remote sensing buyers drive hardest bargain on per-image unit economics.
Supply Chain Analysis
Extended lead times for space-qualified focal plane arrays and radiation-hardened processors constrain constellation deployment schedules. Component sourcing concentrates in the United States, Germany, and Japan for SAR payload electronics and optical sensors. Raw material dependencies include indium gallium arsenide detectors, synthetic aperture radar T/R modules, and satellite bus aluminum-lithium alloys. Single-source vulnerability sits with ITAR-classified microelectronics foundries. Distribution runs through prime contractor integration facilities rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ground segment software and analytics layers expand faster than orbital hardware, creating service-attach opportunities where recurring mission-control subscriptions outpace one-time satellite procurement.
For Market Incumbents: Compound cybersecurity certification advantages by pre-positioning ISO 27001 credentials ahead of evolving encryption mandates. Lock in spectrum licensing regulatory capture through FCC NGSO proceeding participation. Defend against commercial space vendor encroachment by acquiring cloud-native mission control specialists before ground architecture disaggregation accelerates. For New Entrants and Emerging Players: Anchor in commercial remote sensing data commoditization where agriculture and maritime monitoring verticals lack security clearance for classified sources. Target European sovereign capability programs under NATO's space-as-operational-domain framework. Pursue ground processing architecture partnerships that bypass legacy prime-dominated integration paths. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ground segment software vendors with disaggregated mission control architectures over hardware-heavy satellite bus manufacturers. Long-term viability hinges on recurring revenue attachment rates rather than one-time payload integration. Watch FCC spectrum allocation proceedings as inflection indicator for constellation deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Pre-Positioning | ISO 27001 credentials gate intelligence-community contract eligibility under evolving encryption mandates. |
| Spectrum Licensing Regulatory Capture | FCC NGSO proceeding participation mandates inter-satellite link interoperability for defense contract access. |
| Ground Architecture Disaggregation | Cloud-native mission control software enables mid-tier contractors to bypass legacy prime integration paths. |
| Commercial Remote Sensing Data Monetization | Unprocessed orbital imagery sales to agriculture and maritime verticals bypass classified government processing pipelines. |
| Cleared Workforce Development Investment | Polygraph-qualified systems engineers command premium compensation, inflating program labor costs for unprepared operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Space-Based C4ISR value chain. Primary interviews captured perspectives from satellite program managers at defense primes, payload integration engineers at cleared facilities, FCC regulatory counsel, and commercial remote sensing product managers. Secondary validation drew from SEC 10-K filings of publicly traded defense contractors, FCC NGSO licensing dockets, NATO space domain doctrine publications, and US Space Force procurement announcements. Bottom-up segment sizing triangulated against top-down market boundary assessments.
Across the analysis window, forecasts modeled product type segmentation, technology adoption curves, end-user security clearance tiers, and application-specific orbital architectures. CAGRs derived from deployment schedule analysis, constellation replenishment cycles, and defense budget authorization trajectories. Key inputs included launch vehicle capacity forecasts, sensor resolution specification roadmaps, and spectrum allocation proceeding timelines.
Decision-makers should treat outputs as directional under assumptions of sustained Indo-Pacific theater awareness demand and stable ITAR classification frameworks; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Mobile Service Market
Space
Italy Space Electronics Market
Space
Space Transportation Market
Space
Space Debris Monitoring Market
Space
Space Lander and Rover Market
Space
Europe Space Electronics Market
Space
UK Space Electronics Market
Space
Space Launch Services Market
Space
Space Propulsion Systems Market
Space
US Space Launch Services Market
Space
Space Sensors Market
Space
Spacecraft Market
Space
Space Designing Market
Space
India Aviation, Defense, and Space Market
Space
Space Rover Market
Space
China Space Propulsion System Market